Global Branded Generics Market Poised for Robust Growth, Estimated to Reach USD 860.5 Billion by 2035 | Future Market Insights, Inc.

The global branded generics market is set for substantial growth, with sales expected to rise from USD 382.4 billion in 2025 to USD 860.5 billion by 2035, expanding at a CAGR of 8.4% during the forecast period. In 2024, the market generated USD 353.7 billion in revenue, demonstrating a strong upward trajectory.

The growth of branded generics is primarily driven by the loss of patent exclusivity on innovator drugs, enabling pharmaceutical companies to introduce branded generics with strong brand recognition at competitive prices. Additionally, policy incentives, including exclusivity periods for first-to-market generics, have accelerated their adoption across various regions.

Track Evolving Market Trends: Request Your Sample Report! https://www.futuremarketinsights.com/report-sample#5245502d47422d31323630

Unlike unbranded generics, branded generics benefit from physician confidence, brand loyalty, and targeted marketing efforts, ensuring continued prescription volume. Furthermore, vertical integration and manufacturing efficiencies have allowed pharmaceutical companies to produce cost-effective alternatives while maintaining quality standards.

Another key factor bolstering market growth is the push for cost-containment by health systems and payers, which favors branded generics over expensive originator drugs. Moreover, strategic collaborations and acquisitions are enabling companies to expand their branded generic portfolios, enhance distribution channels, and strengthen their global footprint.

Analysis by Drug Class

The branded generics market is categorized based on various drug classes, each contributing significantly to market expansion.

  1. Analgesics – Driven by the increasing prevalence of chronic pain conditions and post-surgical pain management, analgesic branded generics are witnessing strong demand.
  2. Antibiotics – With rising concerns over antimicrobial resistance, pharmaceutical companies are focusing on developing branded generic antibiotics to maintain efficacy while ensuring affordability.
  3. Cardiovascular Drugs – The growing burden of cardiovascular diseases (CVDs) globally has fueled the demand for cost-effective treatment options, leading to the expansion of branded generic cardiovascular drugs.
  4. CNS (Central Nervous System) Drugs – With neurological and psychiatric disorders on the rise, branded generics in this category are becoming increasingly essential for long-term patient care.
  5. Respiratory Drugs – The surge in respiratory conditions such as asthma and COPD has boosted the demand for branded generics in this segment.

Analysis by Therapy Area

Branded generics cater to a wide range of therapy areas, with significant growth projected in the following sectors:

  1. Oncology – The rising incidence of cancer worldwide is driving the adoption of branded generic oncology drugs, providing affordable treatment options to patients.
  2. Diabetes Management – With diabetes cases escalating globally, branded generics are bridging the gap between innovation and accessibility in diabetes care.
  3. Infectious Diseases – The demand for effective and affordable medications in combating infections continues to support the growth of branded generics in this segment.
  4. Gastrointestinal Disorders – Increased cases of gastrointestinal diseases, including acid reflux and irritable bowel syndrome, are contributing to market expansion.
  5. Autoimmune Diseases – The growing awareness and diagnosis of autoimmune disorders are propelling the demand for cost-effective branded generics in this category.

“The branded generics market is witnessing a significant transformation, primarily fueled by the wave of patent expirations and supportive policy frameworks. Pharmaceutical firms are leveraging physician trust and brand reputation to maintain market share, even in a competitive generic landscape. The rising emphasis on cost containment by healthcare providers further propels the shift toward branded generics. Moving forward, companies that strategically invest in portfolio expansion and global market penetration through mergers and acquisitions will likely see sustained growth in this space.” says Sabyasachi Ghosh Associate Vice President at Future Market Insights (FMI) analyst.

Surge in Market Needs: Discover Comprehensive Analysis and Insights in Our Detailed Report! https://www.futuremarketinsights.com/reports/branded-generics-market

Key Growth Drivers and Pressing Challenges

Key Drivers:

  • Patent Expirations – The continuous expiration of blockbuster drug patents is creating opportunities for branded generics to capture market share.
  • Cost-Effectiveness – Branded generics offer a middle ground between costly brand-name drugs and traditional generics, ensuring affordability without compromising quality.
  • Regulatory Support – Governments worldwide are promoting branded generics to enhance drug accessibility and reduce healthcare costs.

Challenges:

  • Regulatory Hurdles – Stringent regulatory requirements can impact the approval and marketing of branded generics in certain regions.
  • Competition from Traditional Generics – The presence of low-cost generic drugs poses a challenge to branded generics’ market penetration.
  • Physician and Consumer Perception – Overcoming skepticism regarding the efficacy of branded generics remains a crucial aspect of market growth.

Important Developments in the Branded Generics Sector

  • India is projected to witness the highest CAGR of 7.6% from 2025 to 2035, indicating strong market expansion.
  • China follows closely with a 6.6% CAGR, reflecting significant growth potential in the region.
  • South Korea and Japan are expected to grow at 5.7% and 5.2% CAGR, respectively, showcasing steady advancements.
  • The United Kingdom (4.3%) and United States (4.1%) anticipate moderate yet consistent market growth.
  • Emerging markets in Asia demonstrate higher growth rates compared to Western nations, suggesting increasing industry investments and demand in these regions.

Branded Generics Market Dynamics & Future Trends (2025-2035)

The branded generics market is poised for substantial growth, driven by increasing demand for cost-effective medications, an expanding aging population, and heightened healthcare expenditure. Emerging markets, particularly in Asia-Pacific and Latin America, are expected to witness significant adoption due to favorable regulatory frameworks and rising disease prevalence.

Competition and Market Share in Branded Generics

The branded generics market is highly competitive, with multinational pharmaceutical companies, regional players, and local manufacturers vying for market share. Unlike patented medicines, which enjoy exclusivity, branded generics face challenges from both unbranded generics and competing branded products throughout their patent protection lifecycle. This intensifies competition within the industry.

Market leaders vary by region, with global pharmaceutical giants such as Pfizer, Novartis, and Teva competing alongside strong local players like Sun Pharma in India, Sinopharm in China, and Hanmi Pharmaceutical in South Korea. Foreign companies often face difficulties establishing a strong presence due to domestic firms’ first-mover advantage in regulatory approvals, distribution networks, and physician trust.

Recent Developments in the Branded Generics Market

  • June 2024: Teva Pharmaceuticals received FDA authorization for a generic version of Victoza, a medication used to treat Type 2 diabetes.
  • June 2024: Canadian pharmaceutical company Apotex Inc. announced the successful acquisition of Searchlight Pharma Inc., a leading player in the Canadian pharmaceutical market.

Advantage Healthcare Insights to Outpace Competitors! https://www.futuremarketinsights.com/industry-analysis/pharmaceuticals

Key Players of Branded Generics Market Industry

  • Mylan Pharmaceuticals Inc. (Viatris Inc.)
  • Novartis AG
  • Teva Pharmaceuticals
  • Pfizer Inc.
  • Sun Pharmaceutical
  • Aspen Pharmacare Holding Ltd.
  • Abbott Laboratories
  • Bausch Health Companies Inc. (Valeant Pharmaceuticals Inc.)
  • GlaxoSmithKline Pharmaceuticals Ltd.
  • Zydus Lifesciences Ltd.(CADILA)
  • Lupin Pharmaceuticals Inc.
  • Sanofi S.A.
  • AstraZeneca
  • Dr. Reddy’s Laboratories Ltd.
  • AbbVie Inc. (Allergan, Inc.)
  • Bayer AG
  • Cipla Pharmaceuticals
  • Apotex Inc.
  • Endo International Inc.

Branded Generics Industry Analysis of Key Segments

By Drug class:

  • Anti-Hypertensive
  • Alkylating Agents
  • Antimetabolites
  • Hormones
  • Anti-Hypertensive
  • Lipid Lowering Drugs
  • Anti-Depressants Anti-Psychotics
  • Anti-Epileptics
  • Other

By Therapy Area:

  • Oncology
  • Cardiovascular Diseases
  • Diabetes
  • Neurology
  • Gastrointestinal Diseases
  • Dermatology Diseases
  • Analgesics and Anti-inflammatory
  • Others

By Formulation Type:

  • Oral
  • Parenteral
  • Topical
  • Others

By Distribution Channels:

  • Hospital Pharmacies
  • Retail Pharmacies
  • Online Pharmacies
  • Drug Stores

By Region:

  • North America
  • Latin America
  • East Asia
  • South Asia & Pacific
  • Western Europe
  • Eastern Europe
  • Middle East and Africa (MEA)

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Bone Densitometer Devices Market to flourish to reach USD 525.0 million by 2033

The bone densitometer devices market with a projected 4.2% CAGR from 2023 to 2033, the global market for bone densitometer devices is positioned for impressive growth in the changing healthcare landscape. According to our lead consultant for healthcare industry at Future Market Insights, the market valuation is set to rise from USD 347.7 million in 2023 to USD 525.0 million by 2033.

This tendency is being driven by numerous variables that combine to highlight the crucial role that bone health plays. The demand for sophisticated diagnostic technologies is driven by the incidence of osteoporosis and other bone conditions.

The bone densitometer devices market has witnessed significant growth in recent years, driven by the rising prevalence of osteoporosis and bone-related disorders, particularly among the aging population. These devices play a crucial role in assessing bone health by measuring bone mineral density, aiding in the early detection and monitoring of conditions like osteoporosis. The market encompasses various types of bone densitometer devices, including dual-energy X-ray absorptiometry (DXA), quantitative ultrasound (QUS), and peripheral dual-energy X-ray absorptiometry (pDXA) machines.

Bone Densitometer Devices Market Impact of Diagnostic Technologies on Osteoporosis and More, Stay Ahead in Healthcare Trends: Download the Sample Report Now! https://www.futuremarketinsights.com/report-sample#5245502d47422d373333

Advancements in technology have led to the development of more accurate and efficient bone densitometer devices, enhancing diagnostic accuracy and patient comfort. The demand for these devices is also fueled by the increasing awareness of bone health and preventive healthcare measures. Healthcare providers are focusing on integrating bone density testing into routine check-ups, contributing to the market’s expansion.

Key Takeaways: Deciphering the United States’ Preeminence in the Bone Densitometer Devices Market

  • U.S. Market Dominance: The United States led the global bone densitometer devices market in 2022, contributing approximately 73.2% of total sales. A CAGR of 4.9% is projected due to a large osteoarthritis-affected population and favorable market conditions for manufacturers.
  • Rising Burden of Osteoarthritis: With over 32.5 million people affected in the U.S. and 62% of patients being women, the demand for bone health diagnostics continues to surge.
  • Germany’s Growth in Europe: Accounting for 22.9% of the European market, Germany benefits from prompt DXA scan availability and supportive reimbursement policies, alongside awareness campaigns driving early diagnosis.
  • China’s Promising Outlook: In East Asia, China captured 32.4% market share in 2022 and is set to expand at a CAGR of 5.2%, propelled by an aging population and increased uptake among women over 50.
  • Axial Bone Densitometers Lead in Profitability: Holding 69.0% market share in 2022, axial devices—utilizing DXA and QCT technologies—remain preferred for their superior accuracy in diagnosing spinal and femoral bone loss.
  • DXA Technology Reigns Supreme: Dual-energy X-ray absorptiometry (DXA) accounted for 64.2% of global revenue due to its precision, image quality, and role in diagnosing osteoporosis.
  • Hospitals as Primary End Users: With a 64.6% share in 2022, hospitals dominate the market, driven by increased use of bone density scanning for chronic disease management and monitoring.

Interest in Market Trends: Get Detailed Analysis and Insights with Our Comprehensive Report! https://www.futuremarketinsights.com/reports/bone-densitometer-devices-market

Competitive Landscape:

The rivalry for bone densitometer devices is anticipated to continue fierce and is set to worsen as a result of a confluence of compelling factors. These include the rising prevalence of osteoporosis and related bone diseases, which is creating an urgent demand for cutting-edge diagnostic equipment. Concurrently, as people actively seek more sophisticated evaluation techniques, a growing awareness of bone health enhances this competitive environment. The favourable shift in reimbursement paradigms fuels these fires and makes bone health assessments more widely available. The ongoing development of bone densitometry technologies adds another degree of complexity and keeps market leaders on their toes. New competitors frequently enter this vibrant field, bringing new life to the competitive atmosphere.

  • GE Healthcare
  • Hologic, Inc.
  • OSI Systems, Inc.
  • Diagnostic Medical Systems Group
  • Swissray Global Healthcare Holding, Ltd.
  • BeamMed, Ltd.
  • Echolight S.P.A
  • Scanflex Healthcare AB
  • Medonica Co., Ltd.
  • Eurotec Systems S.r.l
  • AMPall Co., Ltd.
  • L’acn L’accessorio Nucleare S.R.L
  • Shenzhen XRAY Electric Co., Ltd.
  • YOZMA BMTech Co., Ltd.
  • Nanoomtech Co., Ltd.
  • Osteosys Corporation
  • FURUNO Electric Co., Ltd.
  • XinGaoYi Co., Ltd.
  • Anjue Medical Equipment
  • Trivitron Healthcare

Key Developments:

Strategic Alliances: 

The market has seen how these partnerships have accelerated technical advancement. The partnership between GE Healthcare and IBA Molecular Imaging in 2022 is noteworthy because it will result in a ground-breaking bone densitometer that uses molecular imaging. This offers greater precision while upending established notions. Another example of foresight is Hologic’s partnership with Siemens Healthineers in 2023, which uses artificial intelligence (AI) to automate bone density scan analysis, improving efficiency and accuracy.

Product evolution: 

The market has been reshaped by innovations in product design. The QDR-4500+ from Osteometer Meditech, which was announced in 2022, offers improved accuracy and a small footprint.

In 2023, BeamMed aims to release the XR-500+, a portable gadget that revolutionises portability by integrating DXA technology. This is a paradigm change, bringing bone densitometry into patients’ homes from clinical settings.

Bone Densitometer Devices Market Segmentation

By Product:

  • Peripheral Bone Densitometer
  • Axial Bone Densitometer

By Technology:

  • Dual Energy X-Ray Absorptiometry (DXA)
  • Peripheral Dual Energy X-Ray
  • Absorptiometry (pDXA)
  • Quantitative Ultrasound (QUS)
  • Others

By End-User:

  • Hospitals
  • Orthopedic Clinics
  • Diagnostic Centers

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East & Africa (MEA)

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Global Endoscopic Vessel Harvesting (EVH) Systems Market Poised for Strong Growth, Projected to Reach USD 949.0 Million by 2035

Endoscopic Vessel Harvesting (EVH) Systems Market

The global endoscopic vessel harvesting systems market is entering a promising growth phase, anticipated to expand steadily from USD 577.1 million in 2025 to USD 949.0 million by 2035, registering a compound annual growth rate (CAGR) of 5.1%. This steady climb reflects the growing adoption of minimally invasive surgical procedures and the rising global prevalence of cardiovascular diseases.

A Transforming Landscape in Cardiovascular Surgery

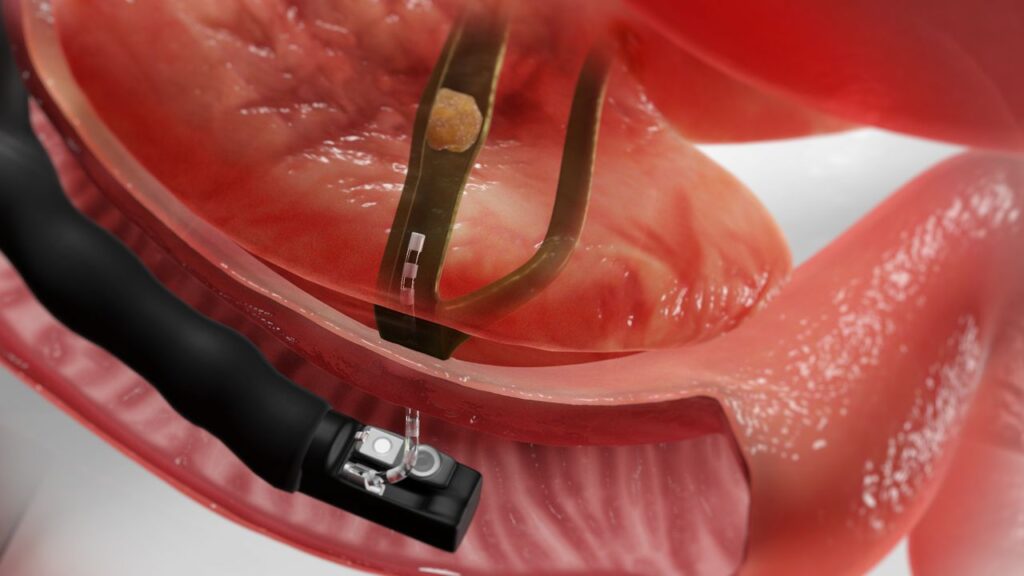
Endoscopic vessel harvesting (EVH) systems have revolutionized surgical methods, especially in coronary artery bypass grafting (CABG) procedures. These systems enable the extraction of blood vessels with minimal trauma, improving patient recovery times, reducing complications, and enhancing surgical outcomes. In 2024, the global revenue from EVH systems stood at USD 552.2 million, laying a solid foundation for sustained growth throughout the next decade.

Track Evolving Market Trends: Request Your Sample Report! https://www.futuremarketinsights.com/report-sample#5245502d47422d31363230

Fueling this momentum is a significant increase in ischemic heart disease cases worldwide. The demand for coronary artery bypass graft surgeries, a common procedure used to treat these conditions, continues to rise. EVH systems, which are primarily used for harvesting the saphenous vein and radial artery, have become essential tools for cardiac surgeons due to their ability to reduce incision sizes, blood loss, and postoperative pain.

Incorporating cutting-edge advancements in imaging technology, electrocautery tools, and robot-assisted surgical systems, EVH is transitioning into a more precise, ergonomic, and patient-centric procedure. However, the industry still faces challenges such as high system costs, training requirements, and regulatory complexities—factors that companies are working aggressively to overcome.

Regional Market Outlooks

United States

The U.S. EVH systems market is witnessing steady growth, driven by the increasing burden of cardiovascular diseases and a strong preference for minimally invasive surgeries. With a CAGR of 2.1% from 2025 to 2035, the country’s healthcare providers continue to adopt EVH systems to improve patient outcomes and surgical efficiencies. The robust healthcare infrastructure and emphasis on precision care further support market expansion.

Germany

Germany remains a key player in the European EVH market, backed by an advanced healthcare system and a strong commitment to quality patient care. With a projected CAGR of 3.8%, the country is embracing EVH systems as part of its broader push for surgical innovation and improved patient safety.

India

India represents a high-potential emerging market, with growth spurred by the rising prevalence of heart diseases and increasing investments in healthcare infrastructure. Urban medical centers are progressively adopting minimally invasive techniques, positioning India’s EVH market for a CAGR of 3.9% over the next decade.

Japan

Japan boasts a highly developed EVH landscape, owing to its sophisticated medical technologies and a healthcare system favoring minimally invasive interventions. The nation’s aging population, combined with its high surgical standards, is expected to drive a CAGR of 4.6%, one of the highest among major economies.

Brazil

Brazil’s EVH market is growing in tandem with rising awareness and healthcare improvements. The surge in cardiovascular cases has prompted a move toward effective, less invasive surgical solutions, pushing the market toward a 3.5% CAGR.

Increased Market Attention: Delve into Detailed Trends and Analysis with Our Report! https://www.futuremarketinsights.com/reports/endoscopic-vessel-harvesting-system-market

Competitive Outlook

The EVH systems market is becoming increasingly competitive, with global medical technology giants and emerging innovators vying for market share. The surge in cardiovascular cases, coupled with consumer demand for shorter recovery periods and fewer surgical complications, is propelling this competition. Players are investing heavily in automation, precision engineering, and user-friendly ergonomics to gain a technological edge.

Manufacturers are also aligning their strategies with the growing emphasis on robotic surgery integration, particularly in high-income markets. With the ongoing shift toward outpatient cardiac procedures, companies that can deliver compact, efficient, and intuitive EVH systems are expected to thrive.

Key Players in the Market Include:

  • Getinge AB
  • Terumo Corporation
  • LivaNova PLC
  • KARL STORZ SE & Co.
  • Saphena Medical Inc.

These companies continue to innovate, focusing on expanding their product offerings to meet the evolving demands of cardiovascular surgeons and healthcare providers globally.

Market Segmentation Highlights

By Product:

  • Reusable
  • Disposable

By Vessel Type:

  • Saphenous Vein
  • Radial Artery
  • Other Vessels

By Application:

  • Coronary Artery Bypass Grafting (CABG)
  • Peripheral Artery Disease (PAD) Surgery
  • Other Cardiovascular Surgeries

By Region:

  • North America
  • Latin America
  • Western Europe
  • Eastern Europe
  • East Asia
  • South Asia & Pacific
  • Middle East & Africa

Download the Latest Healthcare Market Insights Report! https://www.futuremarketinsights.com/industry-analysis/therapeutic-device

Opportunities and Challenges

While developed regions are focusing on advanced integration and robotic-assisted EVH, emerging markets present enormous opportunities for market penetration and localized product development. However, companies must navigate challenges such as:

  • High upfront costs
  • Complex regulatory environments
  • Lack of trained professionals

These barriers, if addressed through strategic partnerships, government collaborations, and focused R&D, could unlock significant value in untapped markets.

Final Thoughts

As EVH systems continue to redefine cardiac surgical standards, the global market stands at the cusp of a transformation. With innovations accelerating and awareness increasing, EVH systems are expected to become integral to modern cardiovascular treatment protocols. The next decade offers a lucrative and dynamic growth environment for players committed to innovation, precision, and better patient outcomes.

Global Intraoperative Radiation Therapy Systems Market to Witness Robust Growth to Reach USD 124.7 Million by 2033

The global intraoperative radiation therapy systems market is poised for significant growth, with projections indicating a substantial increase in value over the next decade. According to recent market analysis, the market, valued at USD 59.3 million in 2023, is anticipated to expand at a Compound Annual Growth Rate (CAGR) of 7.7% from 2023 to 2033, reaching an estimated worth of USD 124.7 million by 2033.

Intraoperative radiation therapy (IORT) plays a crucial role in the treatment of tumors, involving the precise administration of therapeutic radiation doses during surgery. This approach is often integrated into a comprehensive treatment strategy that includes surgery, chemotherapy, and external beam radiation therapy, particularly in cases of chronic and progressively advancing diseases.

Uncover Market Opportunities: Access a Sample Report Now! https://www.futuremarketinsights.com/report-sample#5245502d47422d35313830

The growth trajectory of the intraoperative radiation therapy systems market can be attributed to several key factors:

  • Rising Demand for Targeted Cancer Treatments: As the demand for targeted cancer treatments continues to increase, so does the adoption of intraoperative radiation therapy systems.
  • Technological Advancements Enhancing Precision: Ongoing technological developments are enhancing the precision and effectiveness of radiation therapy equipment during surgery, thereby driving market growth.
  • Widespread Adoption of Mobile Systems: Mobile intraoperative radiation therapy systems are witnessing widespread adoption, stimulating further growth within the IORT systems market.
  • Collaborative Innovation: Collaborations between medical facilities and equipment manufacturers are fostering innovation in IORT systems, leading to the development of advanced technologies and solutions.
  • Dominance of North America: North America maintains its dominance in the intraoperative radiation therapy systems market, attributed to the region’s high healthcare expenditures and advanced healthcare infrastructure.
  • Increased Consumer Awareness: Growing awareness among consumers regarding the advantages of IORT in cancer treatment is contributing to the expansion of the market.

These factors collectively indicate a promising outlook for the intraoperative radiation therapy systems market, with substantial opportunities for growth and innovation.

Expanding Market Need: Access Our Full Report for In-Depth Analysis and Trends! https://www.futuremarketinsights.com/reports/intraoperative-radiation-therapy-systems-market

Regional Trends:

The adoption of IORT systems varies by region due to factors such as healthcare infrastructure, regulatory environments, and reimbursement policies. Developed countries with established healthcare systems tend to have higher adoption rates, while emerging economies are gradually incorporating IORT into their cancer treatment protocols.

Key Companies Profiled:

  • Carl Zeiss Meditec AG
  • IntraOp Medical Inc.
  • iCAD Inc.
  • ZEISS Group
  • Ariane Medical Systems Ltd.
  • Sardina IORT Technologies S.p.A
  • GMV Innovating Solutions
  • Sensus Healthcare Inc.
  • Elekta AB
  • Varian Medical Systems Inc.
  • Eckert & Ziegler Group

Key Segments Covered in the Intraoperative Radiation Therapy Systems Industry Analysis

By Disease Indication:

  • Brain Tumors
  • Breast Cancer
  • Gastrointestinal Tumors
  • Head & Neck Tumors
  • Skin Cancer
  • Spinal Metastases
  • Others

By End User:

  • Hospitals
  • Specialty Clinics
  • Ambulatory & Surgical Centers
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East and Africa (MEA)

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Turning the Tide in Brain Cancer: The Future of Glioblastoma Treatment Drugs Market | FMI

The global glioblastoma treatment drugs market is on the cusp of transformative growth. With market revenues expected to surge from approximately USD 844.8 million in 2025 to a projected USD 1,470.5 million by 2035, the sector is poised for a Compound Annual Growth Rate (CAGR) of 5.7% over the decade. By 2024, the market had already recorded a valuation of USD 799.2 million, reflecting a strong foundation for the years to come.

This expected trajectory is more than just a financial forecast—it mirrors a deeper evolution in cancer treatment technologies, personalized medicine, and collaborative efforts in healthcare innovation. As glioblastoma multiforme (GBM) continues to present significant clinical challenges, the rise in cutting-edge therapies and funding is painting a more hopeful picture for patients and healthcare providers alike.

Discover How Market Trends Are Shaping Industries: Access Your Sample Report! https://www.futuremarketinsights.com/report-sample#5245502d47422d31323438

Understanding the Urgency: The Glioblastoma Challenge

Glioblastoma multiforme is one of the most aggressive and lethal forms of brain cancer, accounting for nearly 15% of all primary brain tumors. Despite conventional treatment options—surgery, radiation, and chemotherapy—prognosis remains poor, with median survival often under 15 months. Its highly invasive nature, rapid progression, and resistance to standard therapies have made it a formidable opponent in oncology.

However, this daunting landscape is precisely what’s driving innovation. Increasing prevalence rates, rising awareness, and public-private investments are converging to fuel the next wave of treatment modalities.

Drivers of Growth: What’s Fueling the Glioblastoma Treatment Drugs Market?

  1. Immunotherapy and Personalized Medicine

One of the most promising avenues has been the emergence of immunotherapy. From CAR-T cell therapies to immune checkpoint inhibitors, researchers are now exploring ways to harness the body’s immune system to fight GBM cells more effectively.

Simultaneously, the rise of precision medicine—which involves tailoring treatment based on a patient’s unique genetic profile—has added a new dimension. Molecular diagnostics and biomarker-targeted therapies are enabling clinicians to design more individualized treatment plans, enhancing outcomes and minimizing side effects.

  1. Advanced Drug Delivery Systems

Another leap has been made in how drugs are delivered. Devices like tumor-treating fields (TTFields)—exemplified by Optune, an FDA-approved device—have shown considerable promise in improving patient survival when used alongside chemotherapy.

Furthermore, nanotechnology and blood-brain barrier-penetrating materials are solving one of the most notorious challenges in brain cancer treatment: delivering drugs effectively to the tumor site.

  1. Surge in Clinical Trials and R&D

With increased government and private funding, there’s a noticeable uptick in clinical trial activities. Early-phase research into gene therapy, tumor microenvironment modulation, and combination regimens has broadened the treatment landscape, bringing previously unavailable options closer to clinical reality.

  1. Collaborations and Regulatory Support

A key enabler of this momentum has been the strategic partnerships between pharma companies and research institutions. Regulatory bodies have also expedited the approval pathways, recognizing the urgency of treating high-fatality diseases like GBM. These alliances and accelerated frameworks are helping move promising candidates from lab to bedside faster than ever before.

Market Restraints: Barriers Yet to Be Overcome

Despite the optimism, the market faces its share of hurdles.

  • High Treatment Costs: Cutting-edge treatments often come with hefty price tags, restricting access, especially in developing regions.
  • Blood-Brain Barrier (BBB): This natural protective layer remains a significant obstacle, preventing many drugs from reaching the tumor effectively.
  • Poor Prognosis and Frequent Recurrence: Even with advancements, low survival rates and high recurrence remain the harsh reality, tempering the enthusiasm around new treatment approaches.

These barriers emphasize the need for ongoing innovation, cost optimization, and infrastructure development to ensure widespread access to emerging therapies.

Growing Market Interest: Explore Comprehensive Insights and Trends with Our Detailed Report! https://www.futuremarketinsights.com/reports/glioblastoma-treatment-drugs-market

Emerging Opportunities: What Lies Ahead?

The decade ahead holds numerous opportunities for industry players:

  • Gene Therapy: The potential of genetic reprogramming to correct mutations at the source is being actively explored. This could become a game-changer in GBM treatment.
  • Combination Therapies: Using multiple drugs or modalities together is showing enhanced efficacy in early trials. Synergistic effects from immunotherapy plus targeted agents, or TTFields with chemotherapy, are being closely studied.
  • AI-Driven Drug Discovery: Artificial intelligence is revolutionizing how new drugs are designed and tested, significantly cutting down the time and cost traditionally associated with development.

Notable Milestones: A Decade of Transformation

The last ten years have witnessed a paradigm shift in glioblastoma research and treatment. Enhanced tumor biology understanding, next-gen clinical trials, and device-based therapies have all contributed to a more comprehensive approach to GBM management.

Optune is a standout innovation. As a non-invasive device that disrupts cancer cell division via electrical fields, it’s offering new hope to patients who previously had very few viable options. Its inclusion in standard treatment regimens represents how technology and medicine are merging to redefine care.

Conclusion: Turning a Corner in Glioblastoma Treatment

The glioblastoma treatment drugs market is no longer treading water—it’s gaining momentum toward a more promising future. A CAGR of 5.7% through 2035 may seem like a statistic, but it symbolizes the tangible strides being made in treating one of the world’s deadliest brain cancers.

From innovation in drug delivery and AI-enhanced therapies to the personalization of medicine and increased stakeholder collaboration, the sector is becoming a beacon of hope for patients and caregivers.

While challenges remain, the path ahead is marked by scientific breakthroughs, investment inflows, and regulatory encouragement, setting the stage for a new era in glioblastoma treatment.

Key Takeaways:

  • Market expected to reach USD 1,470.5 million by 2035, growing at 5.7% CAGR.
  • Drivers: Immunotherapy, precision medicine, nanotechnology, and increased clinical trials.
  • Barriers: High cost, BBB challenges, and low survival rates.
  • Opportunities: AI-driven drug development, gene and combination therapies.
  • Highlight: FDA-approved Optune showcases how tech is reshaping GBM therapy.

As science continues to outpace the disease, the glioblastoma treatment landscape is gradually transforming despair into determination—and data into healing.

Implantable Infusion Pump Market: Fueling the Future of Targeted Drug Delivery | FMI

The global healthcare industry continues to evolve at an extraordinary pace, driven by advancements in medical technology and the ever-growing demand for personalized treatment solutions. Among the innovations reshaping patient care, implantable infusion pumps have emerged as a game-changer in targeted drug delivery. According to the latest projections, the global implantable infusion pump market is poised to reach USD 485.1 million in 2022, and with a steady growth trajectory, it is expected to nearly double, reaching USD 892.6 million by 2032, growing at a CAGR of 5.7% over the forecast period.

What Are Implantable Infusion Pumps?

Implantable infusion pumps are sophisticated medical devices designed to deliver medications and fluids directly into a patient’s body through controlled routes such as intra-arterial, intravenous, subcutaneous, intraperitoneal, intrathecal, and epidural pathways. These devices are surgically implanted into a subcutaneous pocket in the abdominal wall, from where a catheter extends to the targeted site for therapy.

Track the Latest Market Developments: Request a Sample Report! https://www.futuremarketinsights.com/report-sample#5245502d47422d34343036

Unlike external infusion pumps, implantable versions offer precision, reduced risk of infection, and long-term drug delivery with minimal intervention. They are especially vital for patients requiring continuous, long-term medication, such as those with chronic pain, cancer, or severe spasticity. Another major advantage is that most implantable infusion pumps only need to be recharged every 1 to 3 months, enhancing patient comfort and compliance.

Key Drivers Behind Market Growth

  1. Rising Prevalence of Chronic Diseases

One of the primary catalysts driving the demand for implantable infusion pumps is the increasing incidence of chronic conditions such as diabetes, cancer, and severe pain disorders. These conditions often require sustained and precise medication administration, which implantable pumps are uniquely equipped to deliver.

The growing aging population is also contributing to market growth. Elderly patients are more prone to chronic illnesses and typically require more intensive care, making implantable infusion pumps an essential part of long-term therapeutic strategies.

  1. Technological Advancements

Today’s implantable infusion pumps are far more advanced than their predecessors. Enhanced programmability, smart sensors, and wireless connectivity have significantly improved their accuracy and safety profile. Innovations like real-time drug monitoring and adjustable flow rates ensure that the pumps meet the unique needs of every patient, making them a preferred choice in both inpatient and outpatient settings.

  1. Therapeutic Importance and Regulatory Approvals

Implantable infusion pumps have received FDA approval for use in delivering medications for several serious health conditions, including primary liver cancer, metastatic colorectal cancer, and intractable pain, among others. Their therapeutic importance in cancer care and pain management underpins their growing adoption across hospitals, specialty clinics, and ambulatory surgical centers.

Rising Demand for Market Data: Our Full Report Offers Deep Insights and Trend Analysis! https://www.futuremarketinsights.com/reports/implantable-infusion-pump-market

Regional Market Insights

North America: Leading the Charge

North America is projected to dominate the global market, holding a commanding 36.7% share in 2022. This regional dominance stems from a combination of factors:

  • High prevalence of chronic illnesses, especially chronic pain.
  • Advanced healthcare infrastructure and strong insurance frameworks.
  • Presence of leading market players and increased regulatory approvals.

For instance, data from the CDC in 2020 revealed that 20.4% of U.S. adults experienced chronic pain in 2019, with 7.4% suffering from severe pain that disrupted daily activities. Implantable infusion pumps, which offer consistent and effective pain management, are becoming increasingly vital in such cases.

Furthermore, the U.S. FDA’s recent product authorizations are encouraging wider clinical use of these devices, further bolstering market expansion.

Asia Pacific: Fast-Paced Growth

The Asia Pacific region (excluding Japan) is expected to witness significant market expansion in the years to come. The surge in R&D activities, economic development, and healthcare infrastructure improvements are fueling growth in countries like China, India, and South Korea.

Additionally, the region boasts a growing number of regional manufacturers, who are driving affordability and accessibility of implantable infusion pumps at a local level. As disposable income increases and awareness of advanced treatments spreads, adoption of these medical devices is poised to accelerate.

Europe: Healthcare Evolution in Progress

Europe is not far behind. The region is anticipated to grow at a CAGR of 6.2% from 2022 to 2032, accounting for 29.5% of the global market share in 2022. Europe’s growth is propelled by:

  • The rising prevalence of chronic illnesses such as cancer and diabetes.
  • Expansion of home healthcare services, leading to greater demand for ambulatory infusion systems.
  • Increased investment in intensive care units (ICUs) during and after the COVID-19 pandemic, where infusion devices are frequently used.

Looking Ahead: The Future of Implantable Infusion Pumps

As medical science continues to lean towards personalized and targeted therapy, implantable infusion pumps will likely play a central role in the treatment paradigm. Their ability to improve patient outcomes, reduce hospital visits, and enhance the quality of life for patients dealing with long-term illnesses makes them indispensable in modern healthcare.

Emerging Opportunities

  • Integration with AI and digital health platforms to enable remote monitoring and dosage optimization.
  • Use in neurological disorders, such as Parkinson’s disease and multiple sclerosis, where continuous drug infusion can enhance symptom control.
  • Expansion into low and middle-income countries, supported by government healthcare reforms and international aid programs.

Final Thoughts

The global implantable infusion pump market is at the forefront of transforming drug delivery systems with its unmatched precision, reliability, and therapeutic value. As healthcare providers seek more efficient, patient-centric, and long-term treatment solutions, implantable infusion pumps are emerging as a cornerstone of modern medical care.

With rising chronic disease burden, technological progress, and expanding global healthcare infrastructure, the market’s upward trajectory appears not just promising, but essential.

Global Hemostasis Testing Systems Market: A Rapidly Advancing Frontier in Diagnostic Technology | FMI

The global market for hemostasis testing systems is undergoing a dynamic transformation, fueled by technological innovation, increasing prevalence of bleeding and thrombotic disorders, and an expanding aging population. Valued at USD 2,366.1 million in 2025, the market is projected to grow at a CAGR of 5.4%, reaching USD 3,998.0 million by 2035. The strategic shift towards automation, point-of-care testing, and advanced analyzers underscores a broader trend of enhanced precision, speed, and accessibility in diagnostic healthcare.

Why Hemostasis Testing is in the Spotlight

Hemostasis testing systems play a vital role in detecting, diagnosing, and monitoring conditions related to blood clotting. Disorders like hemophilia, deep vein thrombosis (DVT), factor V deficiency, and pulmonary embolism are becoming more prevalent globally. As the population ages, the risk of developing these conditions increases, necessitating accurate and timely diagnostic solutions.

Access Key Market Insights: Request a Sample Report Now! https://www.futuremarketinsights.com/report-sample#5245502d47422d31333331

Surgical interventions and trauma cases also call for rapid evaluation of a patient’s coagulation profile, increasing the demand for real-time, high-precision diagnostic tools. The market is leaning into automation and AI to deliver faster results, reduce human error, and accommodate the growing volume of tests being performed.

Technological Innovations: A Game Changer

One of the most defining aspects of the market’s evolution is the rise of automated hemostasis analyzers and point-of-care (POC) testing devices. These innovations significantly improve test efficiency, minimize turnaround time, and streamline workflows in hospital labs and clinics.

Technological advancements such as AI integration, microfluidic platforms, and lab-on-a-chip systems are setting new standards for diagnostic performance. These solutions enhance diagnostic accuracy, reduce costs, and are increasingly favored in both developed and emerging markets.

Furthermore, gender-specific therapies and marker-based coagulation diagnostics are poised to shape the future of personalized medicine, further driving demand for sophisticated hemostasis testing systems.

Country-Wise Analysis: Global Trends and Regional Insights

United States: A Mature Yet Expanding Market

The U.S. market remains one of the most advanced globally, with growth driven by:

  • High prevalence of bleeding disorders such as hemophilia and Von Willebrand disease
  • A surge in surgical procedures, particularly cardiovascular and orthopedic operations
  • Increased demand for POC testing in emergency and critical care settings
  • Availability of reimbursement policies that encourage diagnostic testing

With a CAGR of 3.7% from 2025 to 2035, the U.S. market will continue to expand due to its robust healthcare infrastructure and high technology adoption.

Soaring Demand for Market Information: Uncover Detailed Trends and Insights in Our Report! https://www.futuremarketinsights.com/reports/hemostasis-testing-systems-market

Germany: Innovation-Driven Growth

Germany’s market is characterized by its well-developed healthcare system and an ongoing commitment to automation in diagnostic laboratories. The country is at the forefront of precision therapy adoption, which requires detailed coagulation profiling.

Factors driving growth in Germany include:

  • An emphasis on new technology implementation
  • A high incidence of cardiovascular diseases
  • Supportive government policies encouraging preventive diagnostics

The market is expected to grow at a CAGR of 4.3% through 2035.

China: Poised for Exponential Growth

China presents the fastest growing market for hemostasis testing systems, with a CAGR of 6.3%. Factors contributing to this growth include:

  • A rapidly aging population
  • Government-backed healthcare reforms and infrastructure investments
  • Increasing adoption of AI-powered diagnostics
  • A shift towards personalized medicine and tailored anticoagulant therapy

China’s push to become a leader in medtech, along with rising awareness and diagnostic capability, sets a fertile ground for market expansion.

India: A Fast-Emerging Diagnostic Hub

India’s hemostasis testing systems market is growing rapidly, with a CAGR of 7.1%—the highest among all countries analyzed. Key factors include:

  • A high burden of blood disorders
  • Rapid healthcare infrastructure development
  • Government initiatives to enhance diagnostic services
  • Increased access to affordable diagnostic tools

The presence of international healthcare seekers and a growing domestic patient base further contributes to market penetration.

Brazil: Strong Public Sector and Growing Awareness

Brazil’s market is benefiting from public health initiatives and growing awareness of bleeding disorders. With a CAGR of 5.3%, the country is expected to make steady gains through:

  • Expansion of public and private diagnostic services
  • Rising POC testing adoption
  • Government support for universal health coverage
  • Increased need for anticoagulation therapy monitoring

Brazil’s strengthening healthcare system and proactive disease management strategies offer promising opportunities for diagnostic equipment providers.

The Road Ahead: Embracing Smart Diagnostics

As we look toward the future, several trends are poised to shape the trajectory of the global hemostasis testing systems market:

  1. Integration of AI and Machine Learning: To predict coagulation anomalies and optimize therapy in real time.
  2. Portable and User-Friendly Devices: For use in remote areas and decentralized healthcare setups.
  3. Increased Investment in R&D: Both public and private sectors are channeling funds into the development of smarter, faster, and more affordable diagnostic solutions.
  4. Personalized Medicine: Coagulation tests will play a critical role in tailoring treatment plans, especially in chronic illness management.
  5. Global Health Policy Shifts: With governments prioritizing preventive care, hemostasis testing is set to gain prominence in early disease detection programs.

Conclusion

The global hemostasis testing systems market is on the cusp of transformative growth. With an expected market value of USD 3,998.0 million by 2035, driven by technology, demographic shifts, and healthcare policy reforms, this segment holds tremendous promise. Regional markets—from the technologically advanced U.S. and Germany to the rapidly developing landscapes of China, India, and Brazil—are all witnessing substantial momentum.

Healthcare providers, policymakers, and diagnostic manufacturers must work collaboratively to capitalize on these trends. The future of hemostasis diagnostics lies not only in innovation but also in equitable access, clinical integration, and patient-centric design. As bleeding disorders and thrombotic conditions continue to rise, the need for accurate, timely, and accessible testing solutions becomes not just a market opportunity but a global healthcare imperative.

Riding the Digital Wave: Healthcare IT Outsourcing Market Set for Robust Growth from 2025 to 2035

The global healthcare sector stands at the crossroads of innovation and necessity. As organizations across the healthcare spectrum face mounting pressure to improve patient outcomes, streamline operations, and reduce costs, one trend is emerging as a clear strategic enabler—healthcare IT outsourcing.

Between 2025 and 2035, the healthcare IT outsourcing market is projected to grow significantly, rising from USD 60.6 billion in 2025 to a staggering USD 117.1 billion by 2035, expanding at a Compound Annual Growth Rate (CAGR) of 6.8%. This forecasted growth reflects a transformative shift in how healthcare providers are leveraging technology, talent, and third-party expertise to meet modern-day challenges.

Access Key Market Insights: Request a Sample Report Now! https://www.futuremarketinsights.com/report-sample#5245502d47422d333839

The Push Toward Cost-Effective, Scalable IT Solutions

At the core of this market evolution is the urgent need for cost-efficient and scalable IT solutions. Healthcare systems globally are under strain—from aging populations and rising chronic diseases to budgetary constraints and growing consumer expectations. Traditional models that rely heavily on internal IT teams are proving unsustainable for many organizations.

By outsourcing non-core IT functions—such as infrastructure management, software development, and support services—hospitals and clinics can reallocate resources toward core clinical priorities. Not only does this reduce operational costs, but it also opens the door to specialized technology solutions that are often beyond the in-house capabilities of healthcare providers.

Digital Transformation as a Strategic Imperative

The increasing adoption of cloud-based platforms, electronic health records (EHRs), telemedicine infrastructure, and healthcare analytics is accelerating the need for robust IT support. However, the pace at which technology evolves makes it challenging for internal teams to keep up.

Outsourcing offers healthcare organizations a way to achieve faster implementation timelines without overburdening internal resources. This agility is particularly crucial in an era when digital transformation is no longer optional but a strategic imperative. From small clinics to large hospital networks, healthcare providers are realizing that external IT partners bring not just operational efficiency, but also innovation.

Emerging Technologies Reshaping Outsourcing Models

The next frontier of healthcare IT is being shaped by transformative technologies such as artificial intelligence (AI), machine learning (ML), and blockchain. These tools are being increasingly incorporated into outsourcing contracts to drive advanced data analytics, create predictive care models, and enhance data security.

  • AI and ML are helping healthcare providers analyze vast datasets to uncover insights about patient care, optimize treatment pathways, and anticipate disease trends.
  • Blockchain technology is being used to secure patient records, streamline administrative workflows, and ensure data integrity across multiple systems and stakeholders.

As these technologies evolve, outsourcing vendors are emerging as crucial partners that bring the technical expertise and infrastructure needed to integrate such innovations into clinical and administrative workflows.

Increased Market Attention: Delve into Detailed Trends and Analysis with Our Report! https://www.futuremarketinsights.com/reports/healthcare-it-outsourcing-market

Regulatory Compliance and Data Privacy: A Driving Force

In tandem with technological advancement comes the growing complexity of regulatory compliance and data privacy. Regulations such as HIPAA (Health Insurance Portability and Accountability Act) in the United States and GDPR (General Data Protection Regulation) in Europe are pushing healthcare organizations to adopt strict data governance practices.

This is where outsourcing partners with specialized knowledge of healthcare compliance come into play. These vendors offer built-in compliance frameworks, dedicated security protocols, and audit-ready systems, giving healthcare organizations peace of mind while handling sensitive patient data.

By entrusting compliance-heavy functions to seasoned vendors, healthcare providers not only ensure adherence to legal mandates but also free up internal teams to focus on patient-centric innovation.

Population Health Management: Fueling Data-Driven Care

One of the most promising areas of growth in healthcare IT outsourcing lies in population health management. As providers shift toward value-based care models, there is an increasing need for intensive data aggregation and analysis.

Outsourcing companies are stepping in to offer specialized services that help healthcare organizations:

  • Coordinate care across systems
  • Identify at-risk populations
  • Maximize resource allocation
  • Improve health outcomes on a broad scale

These initiatives require robust data platforms, predictive algorithms, and interoperable systems—capabilities that IT outsourcing vendors are uniquely positioned to deliver.

Strategic Benefits of Healthcare IT Outsourcing

Let’s take a closer look at why outsourcing is fast becoming a go-to strategy for healthcare organizations:

  1. Cost Reduction

Outsourcing enables organizations to move away from capital-intensive IT infrastructure toward operational expense models. This frees up capital for clinical investment and improves financial flexibility.

  1. Access to Specialized Talent

In a competitive hiring landscape, outsourcing offers instant access to highly skilled professionals with niche expertise in healthcare technologies, cybersecurity, and compliance.

  1. Improved Focus on Core Functions

By offloading IT operations, healthcare providers can focus more on clinical excellence and patient care, while outsourcing partners handle the back-end complexity.

  1. Scalability and Agility

Outsourced services are inherently scalable, allowing organizations to adapt quickly to demand surges or new technology rollouts without having to retrain or hire.

  1. Faster Time-to-Market

Outsourcing accelerates the deployment of new digital tools, helping organizations stay competitive and responsive to evolving patient needs.

Get Your Hands on Healthcare Market Projections Now! https://www.futuremarketinsights.com/industry-analysis/healthcare-services

The Road Ahead: A Partnership-Driven Ecosystem

Looking ahead, the healthcare IT outsourcing market is poised to evolve into a partnership-driven ecosystem, where healthcare organizations and IT vendors co-create solutions tailored to specific needs. This collaborative model is expected to foster greater innovation, improve patient outcomes, and deliver stronger return on investment (ROI).

As digital transformation continues to reshape healthcare, outsourcing is emerging not as a stopgap, but as a strategic enabler that aligns technology investment with operational goals.

Final Thoughts

The healthcare IT outsourcing market is on the brink of a remarkable growth journey between 2025 and 2035. With investments in cloud technology, data analytics, and cybersecurity on the rise, and the challenges of cost containment, regulatory compliance, and scalability looming large, outsourcing is proving to be a powerful solution.

Healthcare organizations that embrace this trend early—partnering with the right vendors and leveraging cutting-edge technologies—will be well-positioned to thrive in the next decade of digital health evolution.

Graft Versus Host Disease (GvHD) Treatment Market Projected to Reach USD 5,585.2 Million by 2035, Driven by Innovative Therapies and Expanding Transplant Rates | FMI

The global graft versus host disease treatment market is poised for substantial growth, rising from approximately USD 2,881.8 million in 2024 to an estimated USD 3,060.5 million by 2025, and further projected to attain USD 5,585.2 million by 2035, reflecting a steady CAGR of 6.2%. As stem cell transplantation becomes increasingly central to hematologic cancer treatment, the corresponding surge in demand for effective GvHD management solutions is expected to transform the global therapeutic landscape over the next decade.

Immune Modulation at the Core of Market Expansion

Graft versus Host Disease (GvHD) occurs when transplanted donor immune cells attack the recipient’s body tissues, presenting a critical post-transplant complication. Traditionally challenging to treat, recent advances have enabled more effective immune modulation techniques—most notably JAK inhibitors like ruxolitinib and promising cellular therapies. The availability of these therapies, particularly for steroid-refractory GvHD cases, has played a pivotal role in improving patient outcomes and expanding the market.

Get Ahead of Market Shifts: Request Your Sample Report! https://www.futuremarketinsights.com/report-sample#5245502d47422d31343031

The period from 2020 to 2024 served as a turning point in GvHD treatment, witnessing regulatory approvals for new drug indications and increasing adoption of advanced immunomodulatory agents. Moreover, the COVID-19 pandemic inadvertently accelerated GvHD research by reinforcing the importance of immune response management and infection control in immunocompromised patients, catalyzing innovation and clinical trial activity across the board.

Market Drivers: Stem Cell Transplant Growth and Targeted Therapies

A confluence of factors contributes to the GvHD treatment market’s expansion:

  • Rising Incidence of Hematologic Malignancies: Conditions like leukemia and lymphoma continue to necessitate allogeneic stem cell transplantations, a major precursor to GvHD.
  • Early Diagnostics & Better Screening: Enhanced diagnostic modalities now facilitate early detection and intervention, improving prognosis and expanding treatment scope.
  • Breakthrough Therapies: The evolving immunotherapy and targeted therapy landscape provides new hope for personalized treatment of both acute (aGvHD) and chronic (cGvHD) forms of the disease.
  • Increased Research Investment: Growing emphasis on clinical research, particularly involving biologics and cell-based interventions, is contributing to the rich pipeline of GvHD solutions.

Regional Outlook: Growth Trajectories by Country

United States

The U.S. leads the charge with aggressive transplant programs, a high density of clinical trials, and regulatory agility favoring innovative therapies. Real-world evidence, outcome-based reimbursement models, and patient access programs are expected to support a CAGR of 3.8% between 2025 and 2035.

Germany

Backed by a developed healthcare infrastructure, robust cancer screening programs, and a strong commitment to nuclear medicine research, Germany’s market for GvHD treatments will grow steadily at 4.1% CAGR through 2035.

India

India is emerging as a hotspot for GvHD treatment due to a growing number of stem cell transplants, increasing healthcare investments, and greater awareness among oncologists. Cost-effective biologics and a surge in medical tourism will push India’s GvHD treatment market to a 5.7% CAGR—among the highest globally.

China

China’s market is expected to grow at a 4.8% CAGR, fueled by rising transplant numbers, government-led innovation initiatives, and accelerated drug approvals. The integration of AI in diagnostics is expected to further boost competitiveness and innovation in the region.

Japan

Japan’s success in regenerative medicine, generous transplant reimbursements, and thriving cellular immunotherapy programs signal its stronghold on regional innovation. With growing collaborations and precision medicine initiatives, Japan is expected to expand at 5.3% CAGR by 2035.

Soaring Demand for Market Information: Uncover Detailed Trends and Insights in Our Report! https://www.futuremarketinsights.com/reports/graft-versus-host-disease-gvhd-treatment-market

Competitive Landscape: Market Consolidation and Tech Integration

The GvHD treatment landscape is becoming increasingly competitive, with several established players and emerging innovators shaping the future of immune modulation. Key companies in this space include:

  • Sanofi
  • Equillium, Inc.
  • Novartis AG
  • Neovii Biotech GmbH
  • Merck & Co.
  • Astellas Pharma Inc.
  • Soligenix, Inc.
  • Mesoblast Ltd
  • Pfizer
  • Takeda Pharmaceutical
  • Abbott

Strategic alliances with hospitals, diagnostic laboratories, and research institutions are critical for maintaining market presence. Companies are also investing heavily in AI-driven solutions for early diagnosis, treatment monitoring, and workflow automation, all aimed at enhancing precision and efficiency in patient care.

Market Segmentation: Product and Disease Type

By Product:

  • Monoclonal Antibodies
  • mTOR Inhibitors
  • Tyrosine Kinase Inhibitors
  • Thalidomide
  • Etanercept

By Disease Type:

  • Acute Graft Versus Host Disease (aGvHD)
  • Chronic Graft Versus Host Disease (cGvHD)

The shift towards targeted biologics and next-gen inhibitors reflects the growing demand for precision therapies over conventional broad-spectrum immunosuppressants. These products will be central to market performance through 2035.

Navigate the Future of Healthcare with Confidence! https://www.futuremarketinsights.com/industry-analysis/therapy-area

Looking Ahead

As stem cell transplantations increase globally, the corresponding demand for safer, more effective GvHD treatments will only intensify. Future market dynamics will be shaped by:

  • Next-generation cell and gene therapies
  • Real-world clinical data integration
  • Value-based pricing strategies
  • Greater cross-border research collaborations

With the convergence of innovation, access, and infrastructure, the GvHD treatment market is primed for a transformative decade ahead—bringing hope to patients, opportunity to developers, and strategic growth to investors.

Global Equine Veterinary Therapeutics Market Set to Surpass USD 3,047.6 Million by 2035 amidst Surge in Advanced Therapies and Equine Healthcare Awareness | FMI

The global equine veterinary therapeutics market is galloping towards impressive growth, projected to reach approximately USD 1,572.6 million by 2025 and further expand to around USD 3,047.6 million by 2035. This remarkable trajectory, at a compound annual growth rate (CAGR) of 6.8%, underscores a robust and transforming industry increasingly driven by innovation, awareness, and precision animal care.

Advancing Equine Care: The Market Drivers

The surge in market value is primarily fueled by the rising prevalence of equine diseases, growing owner awareness of equine health, and the broader acceptance of advanced therapeutics in veterinary medicine. Equine owners and veterinarians alike are placing greater emphasis on targeted drug delivery, early diagnostics, and regenerative medicine to enhance performance and overall health in horses.

Gain Valuable Market Knowledge: Request a Sample Report! https://www.futuremarketinsights.com/report-sample#5245502d47422d32353030

One of the most transformative innovations in the sector is the emergence of smart equine therapeutics—driven by biosensor technology and intelligent monitoring systems. These solutions are allowing for real-time diagnostics and precision dosing, significantly improving the outcomes of treatment while reducing overall recovery times.

Regenerative medicine, once a distant goal, is now firmly within the reach of modern equine healthcare. Investments in biologics, stem cell therapies, and gene-modulated treatments are reshaping the therapeutic landscape, particularly for performance horses and those engaged in competitive sports.

Challenges That Still Need Tackling

Despite these advancements, several market inhibitors persist. High treatment costs and access disparity—especially in less privileged regions—continue to hinder the full democratization of equine healthcare. Regulatory complexities surrounding veterinary pharmaceuticals also challenge manufacturers looking to fast-track innovation into real-world application.

Nevertheless, the market presents substantial opportunities, including:

  • The rise of precision veterinary medicine for horses;
  • Sustainable drug formulations that reduce environmental impact;
  • The proliferation of telemedicine services enabling remote consultations and care delivery.

A Historical Shift in Veterinary Medicine

From rudimentary wound care and basic antibiotics to the modern use of anti-inflammatories, vaccines, and regenerative therapies, the equine therapeutics field has evolved significantly. As equine sports gained prominence, investment in horse health soared, ushering in an era of sophisticated diagnostics and high-value therapeutics.

Horse owners are now investing in preventative strategies as much as curative ones. With new infrastructure upgrades in veterinary hospitals and clinics, diagnostic accuracy has improved, allowing practitioners to move from reactive to proactive disease management.

Expanding Market Need: Access Our Full Report for In-Depth Analysis and Trends! https://www.futuremarketinsights.com/reports/equin-veterinary-therapeutics-market

Key Country-Level Insights

United States

The U.S. leads the global market with a well-established equine population, a thriving horse racing and recreational ecosystem, and high expenditure on advanced diagnostics and therapeutics. The market’s CAGR from 2025 to 2035 is forecasted at 2.3%, with strong adoption of biologics, pain management solutions, and regenerative therapies.

United Kingdom

In the UK, equestrian sports such as racing, eventing, and dressage bolster demand for veterinary care. High regulatory standards, coupled with focused R&D in equine health, drive the market’s steady CAGR of 3.0%.

China

China’s growing enthusiasm for horse racing and equestrian sports has led to increased investment in rural and urban veterinary services. Widespread use of vaccines and antiparasitics is complemented by a rising interest in regenerative solutions. The market is expected to expand at a CAGR of 6.6%.

Germany

Germany’s equine market thrives on a strong cultural affinity for horse riding and healthcare ethics. Preventative diagnostics, alternative therapies like herbals and homeopathy, and strong investments in sports medicine contribute to a healthy CAGR of 3.4%.

India

In India, military, ceremonial, and recreational use of horses drives demand for equine therapeutics. While current focus remains on basic therapeutics like anti-infectives and wound care, growing access to veterinary education and remote vet services support a promising CAGR of 6.1%.

Competitive Landscape

The global equine therapeutics industry is becoming increasingly competitive as companies aim to meet the rising demand for advanced care across all horse categories—whether racing, performance, or companion. Market players are actively investing in:

  • Antiparasitics and anti-infectives,
  • Vaccines including recombinant and inactivated types,
  • Non-steroidal anti-inflammatories,
  • Regenerative medicine and biologics.

While global animal health giants dominate, the industry is witnessing the emergence of niche pharmaceutical firms and innovative biotech startups catering specifically to equine needs.

Key Companies in the Market Include:

  • Zoetis Inc.
  • Boehringer Ingelheim
  • Merck Animal Health
  • Dechra Pharmaceuticals
  • Elanco Animal Health
  • Virbac Animal Health
  • Vetoquinol
  • Bimeda
  • Norbrook
  • Ceva Santé Animale

Harness Healthcare Market Trends for Your Advantage! https://www.futuremarketinsights.com/industry-analysis/animal-health-therapeutics

Market Segmentation

Key Segments

By Drugs:

Anti- Inflammatory, Anti – Infective, Parasiticides and Others.

By Vaccines:

Recombinant vaccines, Inactivated Vaccines, Live attenuated vaccines and Others.

By Indication:

Infectious Diseases, Musculoskeletal Disorders, Gastrointestinal Disorders, Respiratory Disorders, Reproductive Disorders.

By Route of Administration:

Oral, Parental, Topical.

By Distribution Channel:

Veterinary Hospital, Veterinary Clinics, Pharmacies and drug stores, E-commerce, Other.

By Region:

North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.

Looking Ahead

The equine veterinary therapeutics market is in the midst of a significant transformation. While affordability and accessibility remain challenges, innovations in diagnostics, regenerative care, and smart therapeutics are creating exciting prospects for horse owners, veterinarians, and pharmaceutical players alike.

With targeted drug delivery, real-time health monitoring, and data-backed treatment protocols on the rise, the future of equine health care is undoubtedly more connected, responsive, and advanced than ever before.