Injectable Drug Delivery Market to Reach USD 113.87 Billion by 2034

The injectable drug delivery market is a critical segment within the pharmaceutical and healthcare industries, primarily focusing on the administration of medications through injections. This method offers precise dosing and rapid onset of action, making it essential for treatments ranging from chronic diseases to acute medical conditions. Injectable drug delivery systems have evolved significantly over the years, transitioning from traditional syringes to more advanced technologies like auto-injectors, prefilled syringes, and needle-free devices. This evolution is driven by the need for improved patient compliance, safety, and convenience.

The demand for injectable drug delivery is also influenced by the increasing prevalence of chronic diseases and the growing preference for biologics, which often require injectable forms. The market is characterized by continuous innovation in drug formulations, delivery mechanisms, and device design. These advances are aimed at reducing pain and discomfort, enhancing drug stability, and minimizing the risk of contamination or dosage errors. As healthcare providers and patients seek more efficient and user-friendly delivery methods, the injectable drug delivery market is poised for sustained growth.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-393

Size & Trends

The size of the injectable drug delivery market reflects its expanding role in global healthcare. It encompasses a wide range of products used in hospitals, clinics, and home care settings. The increasing adoption of self-administration devices is a notable trend, as patients and caregivers seek more autonomy in managing treatments. Prefilled syringes, auto-injectors, and wearable injectors are gaining popularity because they simplify the injection process and improve accuracy.

Another significant trend shaping the market is the rise of biologic drugs, including monoclonal antibodies and vaccines, which are typically administered via injection. The growth of these complex drugs is fueling demand for sophisticated delivery systems that maintain drug integrity and ensure patient safety. Furthermore, technological innovations such as smart injectors with connectivity features allow for better monitoring and adherence to treatment protocols.

The shift toward minimally invasive delivery and needle-free technologies also highlights the market’s emphasis on enhancing patient experience. This is particularly important in pediatric and geriatric populations, where needle anxiety and injection-related pain can hinder treatment compliance. Additionally, regulatory support and increased investment in research and development continue to drive the market’s expansion, encouraging the launch of new and improved injectable drug delivery solutions.

Key Highlights

One of the key highlights of the injectable drug delivery market is the broad scope of applications it serves. This market is not limited to a specific therapeutic area but spans numerous conditions such as diabetes, oncology, autoimmune diseases, and infectious diseases. The flexibility to deliver a wide range of drugs, including vaccines, hormones, and biologics, positions injectable delivery systems as a cornerstone of modern medicine.

Another highlight is the emphasis on safety and precision. The design of injectable devices increasingly incorporates features that prevent accidental needle sticks and dosage errors, thereby protecting both patients and healthcare professionals. Innovations in materials and device ergonomics also contribute to better handling and disposal.

Moreover, patient-centricity is becoming a core focus. Manufacturers are developing devices that cater to diverse patient needs, including those with limited dexterity or visual impairments. User-friendly designs, combined with clear instructions and ease of use, facilitate self-administration and enhance adherence to therapy.

The market also benefits from collaborations between pharmaceutical companies, device manufacturers, and technology firms. Such partnerships accelerate the development of integrated solutions that combine drug delivery with digital health technologies. These advances enable personalized treatment regimens and real-time data collection, contributing to improved clinical outcomes.

Challenges and Opportunities

Despite its promising outlook, the injectable drug delivery market faces certain challenges. One significant barrier is the high cost associated with the development and manufacturing of advanced delivery systems. The need for rigorous testing to ensure safety and efficacy, combined with compliance to stringent regulatory requirements, can increase time and expenses before a product reaches the market.

Patient reluctance to injectable treatments remains another challenge. Needle phobia and concerns about pain or infection may reduce willingness to adopt injectable therapies. Overcoming these psychological barriers requires continuous education and innovation focused on minimizing discomfort and simplifying administration.

On the other hand, these challenges present valuable opportunities. The rising demand for home-based care and self-administration creates a fertile ground for introducing innovative delivery devices that prioritize convenience and safety. Furthermore, emerging markets offer significant potential due to increasing healthcare awareness and expanding infrastructure.

Technological advancements also open doors to novel injectable formulations and smart delivery platforms. The integration of sensors and connectivity features allows for remote monitoring of dosage and patient adherence, enhancing treatment effectiveness. Additionally, collaborations across industries can foster the development of multi-functional devices that address unmet medical needs and streamline healthcare delivery.

Key Benefits for Stakeholders

The injectable drug delivery market offers numerous benefits to its diverse stakeholders, including patients, healthcare providers, manufacturers, and payers. Patients gain from improved treatment efficacy and greater control over their therapy regimens. Advanced injectable devices reduce pain, increase dosing accuracy, and support self-administration, which contributes to better health outcomes and quality of life.

Healthcare providers benefit from streamlined workflows and enhanced patient safety. Devices designed to prevent needle-stick injuries and reduce handling errors improve clinical efficiency and reduce occupational hazards. The availability of ready-to-use delivery systems also saves time and minimizes waste, contributing to better resource management.

Manufacturers enjoy the opportunity to innovate and differentiate their product portfolios. The growing injectable drug delivery market incentivizes investment in research and development, leading to new patents and competitive advantages. Moreover, the rising demand for biologics and specialty drugs ensures a steady market for injectable devices.

Payers and healthcare systems gain from the potential reduction in hospitalization rates and complications through improved drug delivery methods. Effective treatment adherence reduces disease progression and associated costs. Additionally, the shift towards outpatient and home care settings enabled by injectable technologies supports cost containment and improved patient satisfaction.

Market Share by Geographical Region

The injectable drug delivery market demonstrates varied dynamics across different geographical regions. Developed regions often lead due to established healthcare infrastructure, high adoption of advanced technologies, and strong regulatory frameworks. These areas tend to have a mature market with widespread use of prefilled syringes, auto-injectors, and wearable injectors.

Emerging regions present promising growth opportunities, driven by increasing healthcare access, rising prevalence of chronic diseases, and growing awareness about injectable therapies. Expansion of healthcare facilities and government initiatives to promote vaccination and treatment accessibility further stimulate market growth.

Differences in healthcare spending, reimbursement policies, and patient demographics influence market penetration in various regions. For instance, regions with aging populations and high incidence of lifestyle-related diseases see greater demand for injectable treatments. Meanwhile, regions with limited access to healthcare may face challenges but also hold the potential for leapfrogging technologies that support home care and remote patient monitoring.

Competitive Outlook

Competition within the injectable drug delivery market is intense, fueled by continuous innovation and growing demand. Key players strive to develop advanced devices that address specific therapeutic and patient needs. Differentiation is often achieved through proprietary technologies, product design, and integration of digital health features.

Strategic collaborations, mergers, and acquisitions are common, allowing companies to expand their product portfolios and enhance their market presence. Partnerships between pharmaceutical companies and medical device manufacturers facilitate the co-development of drug-device combinations, accelerating market entry and improving patient outcomes.

Companies also invest heavily in research and development to introduce novel injectable delivery methods, including needle-free systems and smart injectors with data connectivity. Focus on sustainability and eco-friendly device designs is emerging as a competitive factor, responding to increasing environmental concerns.

The competitive landscape is further shaped by regulatory developments and intellectual property considerations. Companies that navigate these successfully can achieve a strong foothold, while those that fail to innovate risk losing market share to more agile competitors.

Top Companies

The injectable drug delivery market is dominated by several leading companies known for their innovation, product quality, and global reach. These firms invest significantly in developing advanced delivery technologies and expanding their therapeutic applications. Their portfolios typically include prefilled syringes, auto-injectors, needle-free devices, and wearable injectors.

Many top companies emphasize collaboration with biotech and pharmaceutical firms to offer integrated drug-device solutions tailored to biologics and specialty drugs. Their extensive manufacturing capabilities and regulatory expertise enable them to serve diverse markets worldwide.

In addition to product innovation, these companies focus on patient education and support programs to enhance device adoption and adherence. They often lead initiatives promoting sustainability in device design and packaging, aligning with global health and environmental goals.

While competition is robust, the top companies maintain leadership by continuously evolving their offerings and responding to emerging market needs. Their influence helps shape industry standards and drive future advancements in injectable drug delivery.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/injectable-drug-delivery-market

Segmentation Outlook

The injectable drug delivery market can be segmented by product type, drug type, therapeutic application, and end-user. Product segmentation includes traditional syringes, prefilled syringes, auto-injectors, needle-free injectors, and wearable injectors. Each category caters to different patient needs and clinical scenarios, reflecting diverse delivery preferences and safety features.

Drug types delivered via injectable systems range from vaccines and biologics to hormones and small-molecule drugs. Biologics, in particular, require specialized delivery devices that ensure drug stability and ease of use.

Therapeutic applications span oncology, diabetes, autoimmune disorders, infectious diseases, and others. The prevalence of chronic and acute conditions drives demand for tailored injectable solutions that improve treatment adherence and outcomes.

End-users include hospitals, clinics, home care settings, and specialty centers. The trend toward home administration is reshaping end-user segmentation, with self-administration devices gaining traction and empowering patients to manage their treatments outside traditional clinical environments.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
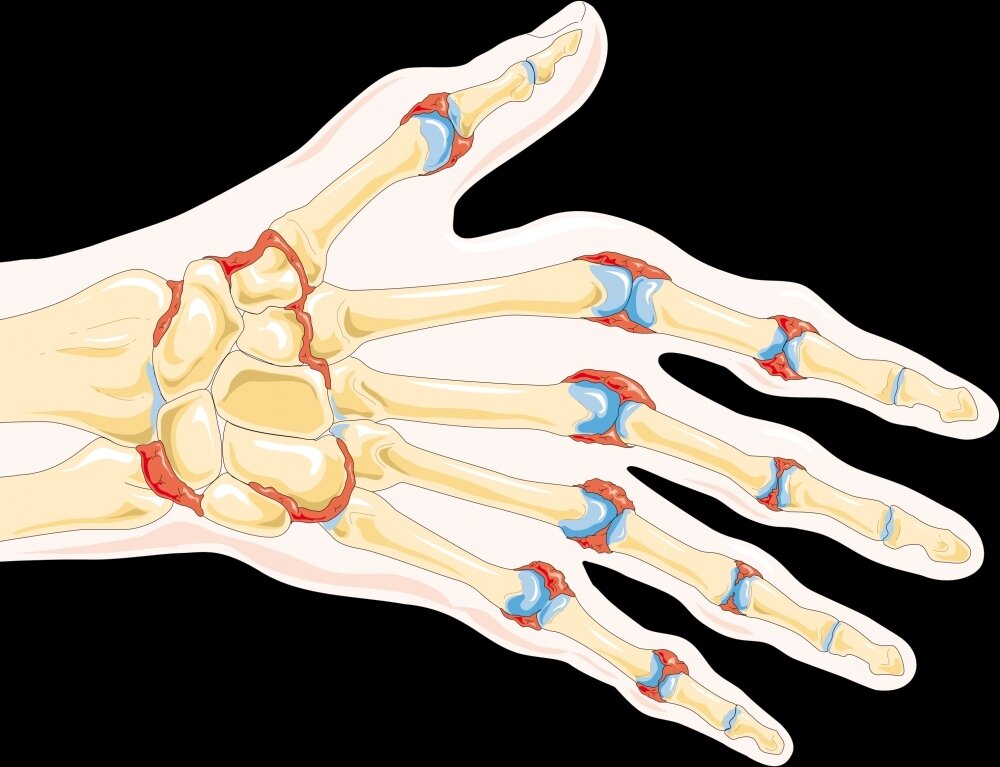
 

Canine Arthritis Treatment Market Valued at USD 2.5 Billion in 2024

The global canine arthritis treatment market stands at a valuation of USD 2.50 billion in 2024. Global demand for canine arthritis treatment medications is predicted to rise at a CAGR of 4.20% and attain a market valuation of USD 3.77 billion by 2034.

The canine arthritis treatment market has been gaining significant traction in recent years due to increasing pet ownership and a growing focus on animal health. As more pet parents become aware of their dogs’ wellbeing, there is a noticeable rise in demand for effective treatment options for canine arthritis. Arthritis in dogs, particularly in older and larger breeds, is a common yet painful condition that significantly impacts mobility and quality of life. This chronic condition has led to an influx of veterinary solutions, including pharmaceuticals, supplements, and therapy-based interventions. As a result, the canine arthritis treatment market is evolving rapidly, addressing not just the medical but also the lifestyle needs of aging canines.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-3552

Market Trends

One of the most prominent trends in the canine arthritis treatment market is the integration of advanced therapeutics and holistic approaches. Pet owners today are looking beyond conventional medications and are embracing natural remedies and alternative treatments such as acupuncture, physiotherapy, and hydrotherapy. The growing preference for organic and natural supplements over synthetic drugs is also shaping the market.

Another important trend is the digital transformation in veterinary healthcare. Telemedicine and mobile veterinary services are making it easier for pet owners to access expert advice and treatment options without geographical constraints. This technological advancement is not only improving accessibility but also increasing the awareness around early diagnosis and management of canine arthritis. Furthermore, the market is witnessing a surge in customized treatment plans that are tailored to the specific needs of each dog, considering factors like breed, weight, and severity of the condition.

Driving Forces Behind Market Growth

Several key factors are fueling the growth of the canine arthritis treatment market. One of the primary drivers is the rising awareness of animal welfare and preventive care. Pet owners are now more informed and proactive when it comes to the health of their pets, leading to an increased demand for early diagnosis and effective treatment options for arthritis.

The expanding global pet population, especially the rise in dog ownership across urban and suburban areas, is contributing significantly to the market. Moreover, the increasing spending on pet healthcare, fueled by rising disposable incomes and changing perceptions of pets as family members, is pushing the demand for high-quality treatment solutions.

Another crucial factor is the ongoing advancements in veterinary medicine. Innovations in drug development, such as monoclonal antibody therapies and regenerative treatments like stem cell therapy, are offering new hope for dogs suffering from arthritis. These developments are expanding the therapeutic arsenal available to veterinarians and further accelerating market growth.

Challenges and Opportunities

Despite the positive outlook, the canine arthritis treatment market is not without its challenges. One of the main issues is the high cost of advanced treatment options, which can be a deterrent for many pet owners. Moreover, access to specialized veterinary care is still limited in certain regions, particularly in developing countries, which restricts market penetration.

Another challenge is the lack of standardized treatment protocols. With multiple treatment options available, including pharmaceuticals, natural supplements, and physical therapy, pet owners often find it difficult to determine the most effective approach. This confusion can delay proper treatment and adversely affect outcomes.

Nevertheless, these challenges open up a wide array of opportunities for stakeholders in the canine arthritis treatment market. The growing emphasis on research and development presents a chance for companies to introduce cost-effective and innovative solutions. Additionally, there is a rising need for educational initiatives that inform pet owners about the signs, prevention, and treatment of canine arthritis, which can significantly enhance market adoption.

Recent Industry Developments

Recent developments in the canine arthritis treatment market underscore the industry’s commitment to innovation and improved patient outcomes. Pharmaceutical companies are investing heavily in developing long-lasting pain relief medications with fewer side effects. Several new products targeting inflammation and joint degradation are either under development or have recently been approved by veterinary authorities.

Another significant development is the use of biologics and gene therapies. These advanced treatments are showing promising results in slowing down the progression of arthritis and enhancing joint regeneration. Furthermore, collaborations between veterinary clinics and tech companies are enabling the use of wearables and apps to monitor dogs’ mobility and pain levels in real-time, facilitating more personalized treatment approaches.

Strategic partnerships and mergers are also on the rise, aiming to expand product portfolios and geographic reach. These alliances are helping companies strengthen their foothold in the highly competitive canine arthritis treatment market.

Regional Analysis

Geographically, North America holds a dominant position in the canine arthritis treatment market, thanks to high pet ownership rates, advanced veterinary infrastructure, and strong consumer spending on pet health. The United States, in particular, is a major contributor to the region’s market share, driven by a growing awareness of canine arthritis and a willingness to invest in advanced treatments.

Europe also commands a significant portion of the market, with countries like the United Kingdom, Germany, and France showing strong demand for both pharmaceutical and alternative therapies. The region’s well-established veterinary services and supportive regulatory environment further aid market growth.

The Asia-Pacific region is emerging as a lucrative market, propelled by a surge in pet adoption and increasing disposable incomes in countries such as China, India, and Japan. While the market is still in a developmental phase, growing awareness and urbanization are expected to drive future growth. Latin America and the Middle East & Africa are gradually catching up, with improving veterinary infrastructure and rising awareness serving as catalysts.

Competitive Outlook

The canine arthritis treatment market is highly competitive, characterized by the presence of several well-established and emerging players. Companies are focusing on innovation, strategic partnerships, and product diversification to stay ahead in the market. The competitive landscape is also shaped by a continuous push toward gaining regulatory approvals and launching new products.

Firms are heavily investing in R&D to create more effective and targeted therapies, aiming to reduce the progression of arthritis and improve the overall quality of life for dogs. In addition to pharmaceutical advancements, many players are also venturing into the nutraceuticals space, offering joint health supplements that cater to the growing demand for natural and preventive solutions.

With increasing competition, marketing strategies have also evolved. Companies are now leveraging social media, online pet communities, and influencer marketing to reach a wider audience and build brand loyalty among pet owners.

Top Companies

Several companies are leading the way in the canine arthritis treatment market. These include both pharmaceutical giants and specialized veterinary health firms. Organizations such as Zoetis, Elanco Animal Health, and Boehringer Ingelheim have a strong presence, offering a wide range of arthritis treatments that include anti-inflammatory drugs, pain relievers, and disease-modifying osteoarthritis drugs.

Other notable players include Vetoquinol, Dechra Pharmaceuticals, and Nutramax Laboratories, which have gained recognition for their contributions to veterinary joint health through both pharmaceutical and nutritional products. Additionally, biotech firms exploring regenerative therapies, such as stem cell and gene therapy, are beginning to make a mark in the industry.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/canine-arthritis-market

Segmentation Outlook

The canine arthritis treatment market can be segmented based on treatment type, distribution channel, and end-user. In terms of treatment, the market includes pharmaceuticals, nutraceuticals, physical therapy, and regenerative medicine. Pharmaceuticals continue to dominate the market, but nutraceuticals are gaining popularity due to increasing consumer preference for natural products.

Based on distribution channels, the market is segmented into veterinary hospitals, retail pharmacies, and online platforms. Veterinary hospitals remain the primary channel due to the professional care required for managing arthritis. However, the convenience of online platforms is driving significant growth in e-commerce sales of pet health products.

When segmented by end-user, household pet owners represent the largest consumer group, followed by animal shelters and pet care centers. The rising awareness among pet owners and the growing emphasis on long-term health maintenance ensure that this segment will continue to drive market expansion.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
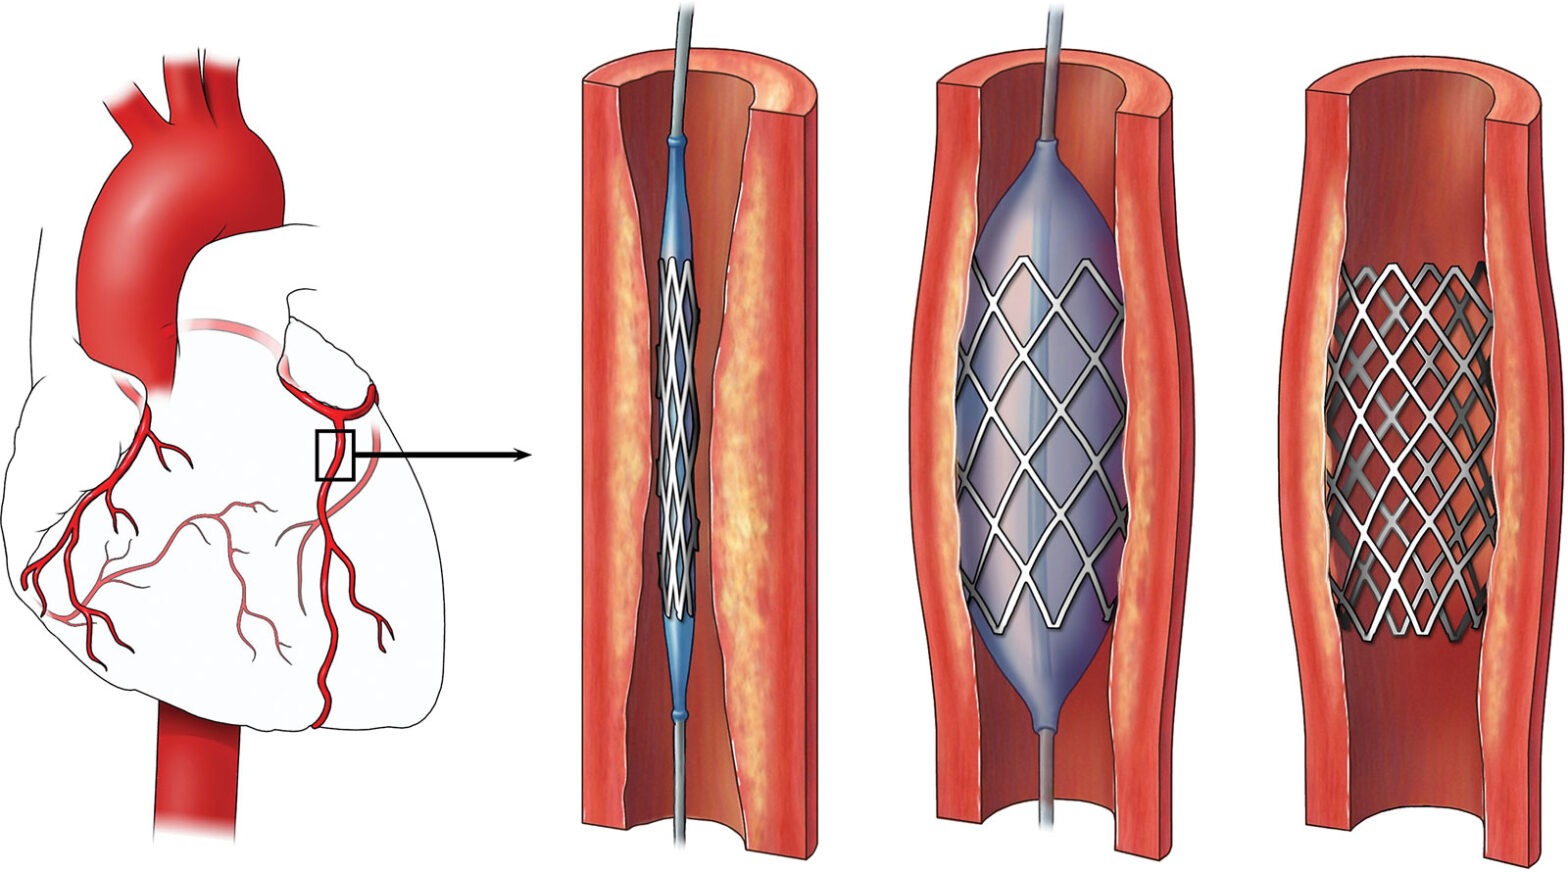
 

Peripheral Vascular Stent Market Expected to Reach USD 8.87 Billion by 2034

The global peripheral vascular stent market, valued at USD 4.26 billion in 2024 to reach USD 8.87 billion by 2034, at a CAGR of 7.60%. The self-expanding segment is the most lucrative segment with a growth rate of 52.40% over the forecast period 2025 to 2035. The peripheral vascular stent industry in China is predicted to grow at a CAGR of 10.30%. Key players include Medtronic Plc, Cardinal Health, Inc., and B. Braun Melsungen AG.

The peripheral vascular stents market has emerged as a pivotal segment within the broader field of cardiovascular devices. Peripheral vascular stents are used in the treatment of diseases that block or narrow blood vessels outside the heart and brain. These medical devices are essential for restoring normal blood flow in arteries and veins affected by peripheral artery disease and other vascular disorders. As healthcare systems globally continue to invest in advanced interventional procedures, the peripheral vascular stents market is witnessing a notable surge in demand.

Technological innovations, rising prevalence of vascular disorders, and growing patient awareness are among the key drivers contributing to the expansion of the peripheral vascular stents market. Hospitals and specialized cardiac care centers are increasingly relying on minimally invasive techniques that make use of these stents, offering patients quicker recovery and fewer complications. Additionally, the aging population and lifestyle-related conditions such as obesity and diabetes further increase the incidence of peripheral vascular diseases, creating steady demand for effective treatment solutions.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-2091

Healthcare reforms in both developed and developing nations are contributing to enhanced access to advanced medical interventions, including stenting procedures. This expansion of healthcare coverage supports the continued growth of the peripheral vascular stents market. Moreover, government initiatives focusing on non-communicable diseases add momentum to the market’s progression.

Market Trends

A number of evolving trends are shaping the trajectory of the peripheral vascular stents market. One of the most prominent is the shift towards drug-eluting stents over traditional bare-metal variants. Drug-eluting stents are designed to reduce the risk of restenosis by gradually releasing medication that prevents tissue growth within the stent. This advancement has led to improved patient outcomes and long-term vessel patency, thereby driving adoption rates.

Another significant trend in the peripheral vascular stents market is the growing emphasis on biodegradable and bioresorbable stents. These devices are engineered to dissolve over time after their function is fulfilled, leaving behind no permanent implant. Such stents reduce long-term complications and may be preferable in younger patients or in regions with limited access to long-term follow-up care.

Technological integration, such as advanced imaging and robotic-assisted procedures, is also influencing the peripheral vascular stents market. Enhanced precision during implantation improves success rates and reduces the likelihood of post-operative complications. The rise of telemedicine and remote patient monitoring is indirectly supporting the stents market by allowing early diagnosis and follow-up, increasing treatment compliance.

Challenges and Opportunities

Despite its growth, the peripheral vascular stents market faces certain challenges that manufacturers and healthcare providers must navigate. One key concern is the potential for complications such as stent thrombosis or restenosis, especially in patients with co-existing conditions. While drug-eluting stents have mitigated some of these risks, the need for long-term clinical data remains critical to justify widespread use.

Another challenge lies in regulatory complexities and approval timelines, especially for newer materials and technologies. The high cost of advanced stents can be a deterrent in price-sensitive markets, limiting their accessibility to a broader patient base. Additionally, reimbursement frameworks vary greatly between regions, influencing the adoption rate of stent procedures.

Nevertheless, the peripheral vascular stents market is rife with opportunities. Emerging markets offer a fertile ground for growth as healthcare infrastructure continues to improve. Innovations focused on cost-effective yet high-quality stents can open new revenue streams in these regions. Collaborations between medical technology companies and research institutions are also likely to accelerate product development and market entry.

Personalized medicine and precision-based treatments offer new dimensions for the peripheral vascular stents market. With the use of advanced analytics and patient-specific data, customized stents could become a future reality, promising enhanced efficacy and safety profiles. Furthermore, rising investments in R&D create pathways for the next generation of vascular stents, offering hope for solving longstanding challenges in vascular interventions.

Key Regional Insights

Geographical analysis of the peripheral vascular stents market reveals interesting dynamics. North America continues to dominate due to its robust healthcare infrastructure, high healthcare expenditure, and widespread adoption of minimally invasive procedures. The presence of leading medical device manufacturers also ensures a steady flow of new product launches and clinical innovations in this region.

Europe follows closely, benefiting from a strong focus on preventive healthcare and the widespread prevalence of vascular diseases, especially among the elderly population. Government-backed healthcare systems support large-scale screening and treatment programs, which bodes well for the peripheral vascular stents market.

In Asia-Pacific, the market is growing rapidly due to factors like increasing healthcare awareness, improved hospital infrastructure, and rising incidences of chronic conditions. Countries such as China and India are experiencing significant healthcare transformations, and their large populations present a vast patient pool. Moreover, regional manufacturers are entering the peripheral vascular stents market with cost-competitive offerings, increasing the availability of affordable solutions.

Latin America and the Middle East & Africa regions are also showing potential, although the market is at a comparatively nascent stage. In these regions, international collaboration and investment will play a crucial role in enhancing access to quality vascular care.

Competitive Outlook

The competitive landscape of the peripheral vascular stents market is characterized by intense rivalry and continuous innovation. Major players are focused on expanding their product portfolios through mergers, acquisitions, and strategic partnerships. Innovation is central to staying competitive, with companies investing heavily in research and clinical trials to launch next-generation stents that offer better safety, efficacy, and usability.

Another key aspect of competition in the peripheral vascular stents market is the ability to navigate regulatory hurdles and obtain timely approvals. Companies with established regulatory expertise tend to enjoy a faster time-to-market, giving them an edge in launching breakthrough products. Customer service, physician training programs, and post-market surveillance also add value to a company’s standing in the marketplace.

Start-ups and mid-sized companies are making their presence felt by targeting niche areas and offering specialized solutions, such as bioabsorbable stents or stents designed for specific anatomical challenges. These firms often collaborate with academic institutions and leverage grants or public funding to support their R&D efforts.

Top Companies

Several prominent companies lead the peripheral vascular stents market. These include multinational corporations with a global footprint and extensive R&D capabilities. These companies continuously work on improving their technologies, expanding geographically, and meeting regulatory standards in different markets.

Some of the market leaders have been at the forefront of introducing drug-eluting technologies and biodegradable stents. Their comprehensive product portfolios cater to a wide range of vascular conditions, enabling them to maintain a strong market presence. Furthermore, their investment in clinical research helps validate the long-term safety and performance of their products, giving them a competitive advantage.

Alongside global leaders, regional companies are carving out space in the peripheral vascular stents market by offering cost-effective solutions. These companies play a vital role in increasing accessibility and affordability, particularly in emerging economies where healthcare budgets are constrained.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/peripheral-vascular-stents-market

Segmentation Outlook

The peripheral vascular stents market can be segmented based on several factors including type, material, end-user, and geography. In terms of type, the market comprises balloon-expandable stents and self-expanding stents. Each type has its unique applications depending on the anatomical location and complexity of the vascular blockage.

Material segmentation includes nitinol, stainless steel, and other advanced alloys. Nitinol stents are favored for their flexibility and shape memory, making them ideal for tortuous vessels. On the other hand, stainless steel stents offer robustness and are often used in larger vessels.

End-user segmentation reveals a predominance of hospitals and specialty clinics as the primary users of peripheral vascular stents. These facilities are well-equipped with diagnostic and interventional tools, making them ideal settings for stent implantation procedures.

Geographical segmentation reflects varying market maturity levels, with developed regions focusing on high-end technology and developing regions prioritizing cost-effective and scalable solutions. This diversity creates room for product differentiation and targeted marketing strategies within the peripheral vascular stents market.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
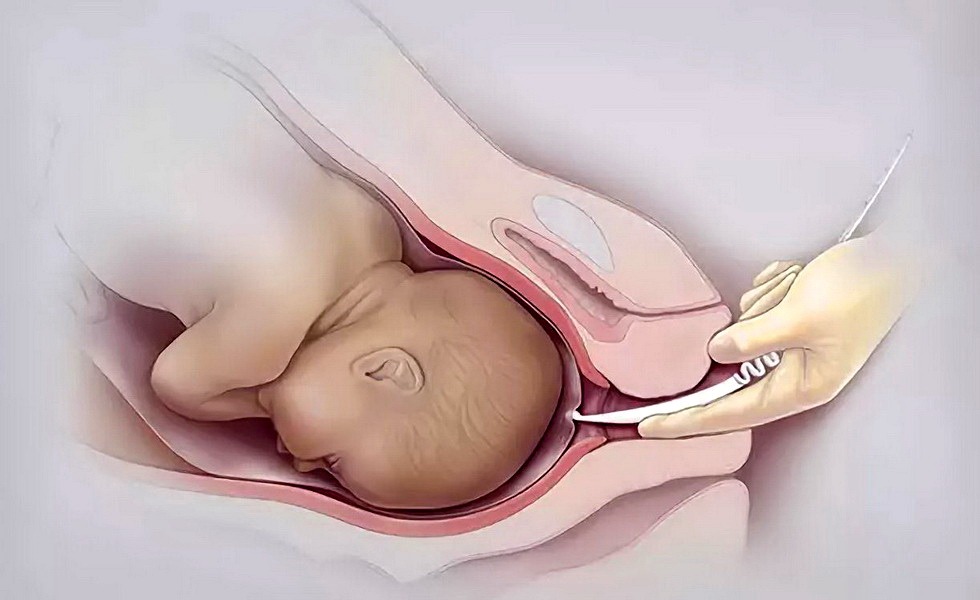
 

Amniotic Membrane Market to Surpass USD 2.27 Billion by 2034

The amniotic membrane market is estimated to stand at USD 1,510.6 million in 2024. The market is forecasted to exceed a valuation of USD 2,279.5 million by 2034, recording a CAGR of 4.2%. Amniotic membrane demand is primarily driven by the therapeutic potential it offers in various medical applications, such as wound healing, ophthalmology, and tissue regeneration.

The amniotic membranes market has witnessed a steady expansion over recent years, driven by increased awareness of regenerative medicine and the growing demand for advanced wound care treatments. Amniotic membranes, derived from the innermost layer of the placenta, have become a vital component in various medical applications due to their anti-inflammatory, anti-scarring, and antimicrobial properties. They are primarily used in ophthalmology, dermatology, orthopedics, and surgical applications, making them a versatile biomaterial in modern healthcare.

Advancements in tissue engineering and biotechnology have propelled the development and commercial availability of amniotic membrane-based products. With hospitals, specialty clinics, and ambulatory surgical centers adopting these solutions more frequently, the market has evolved significantly. Both cryopreserved and dehydrated forms of amniotic membranes are increasingly used, depending on the specific medical requirement, thereby enhancing the overall application scope of these biologics.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-5044

Size & Trends

The trajectory of the amniotic membranes market reflects a robust growth pattern shaped by technological innovations and rising healthcare needs. An upward trend in chronic wound cases, including diabetic foot ulcers, pressure ulcers, and venous leg ulcers, has driven demand for biologically active wound dressings. These conditions, often difficult to treat using traditional methods, benefit substantially from the healing properties of amniotic membranes.

In addition to wound care, the adoption of amniotic membranes in ophthalmic procedures has also surged. Their use in corneal reconstruction, conjunctival surface restoration, and pterygium surgeries has shown promising outcomes, contributing to market growth. Emerging economies have begun recognizing the value of these treatments, further accelerating global penetration.

Moreover, the trend toward minimally invasive procedures and the increasing inclination toward natural biological materials in surgery have further amplified interest in amniotic membrane-based therapies. Research and development activities continue to uncover new clinical benefits, setting the stage for future expansion.

Key Highlights

One of the most notable developments in the amniotic membranes market is the shift toward allograft-based therapies, which offer a more biocompatible and effective solution compared to synthetic alternatives. These products are increasingly gaining regulatory approvals, encouraging healthcare providers to incorporate them into standard treatment protocols.

Another highlight is the rising investment from private and public sectors in regenerative medicine research. Several institutions and companies have allocated substantial funds to develop next-generation amniotic membrane products with enhanced durability and storage capabilities.

Additionally, collaborations between biotechnology firms and healthcare institutions have become more common. These partnerships aim to expand the clinical application range of amniotic membranes and explore their utility in previously untapped therapeutic areas such as urology and cardiovascular surgery.

Challenges and Opportunities

Despite the promising outlook, the amniotic membranes market faces several challenges that could potentially hinder its growth. A primary concern is the complexity of the regulatory landscape, which varies from region to region. Complying with stringent guidelines for the collection, processing, and distribution of human tissue can be time-consuming and costly for manufacturers.

Another challenge is the lack of standardized procedures in the procurement and preparation of amniotic membranes. Variability in product quality can impact clinical outcomes and limit widespread acceptance among medical professionals. Additionally, ethical considerations surrounding the use of human-derived tissues may deter some patients and providers from opting for such treatments.

On the flip side, these challenges also pave the way for significant opportunities. Improved processing technologies and innovative preservation techniques are being developed to enhance product stability and efficacy. Market players who can navigate regulatory hurdles while offering high-quality, ethically sourced products stand to gain a competitive edge.

Moreover, increasing global awareness and training among healthcare professionals about the benefits of amniotic membranes is opening new doors for market penetration. Educational initiatives and clinical studies supporting the efficacy of these products are likely to boost adoption across various specialties.

Key Benefits for Stakeholders

For healthcare providers, the amniotic membranes market presents an opportunity to offer patients advanced treatment options with superior healing outcomes. These biologics reduce inflammation, minimize scarring, and accelerate tissue regeneration, ultimately improving patient satisfaction and reducing hospitalization times.

Manufacturers benefit from an expanding customer base and the potential to innovate in a niche yet growing segment. The ability to produce versatile products that serve multiple specialties—ranging from ophthalmology to orthopedics—allows for diversification and resilience in a competitive landscape.

Investors find the market attractive due to its high growth potential and increasing relevance in regenerative medicine. As more clinical applications are discovered and commercialized, stakeholders can expect robust returns on investment.

For patients, the availability of amniotic membrane-based treatments often means quicker recovery, fewer complications, and reduced need for follow-up interventions. This not only enhances the quality of care but also aligns with broader healthcare goals of efficiency and cost-effectiveness.

Market Share by Geographical Region

Geographically, the amniotic membranes market is most prominent in North America, where advanced healthcare infrastructure, high healthcare spending, and strong research activity drive demand. The United States, in particular, dominates due to the presence of major market players and a high rate of adoption for new medical technologies.

Europe follows closely, with increasing utilization in countries such as Germany, the United Kingdom, and France. These nations benefit from government-supported healthcare systems and rising investment in regenerative medicine research.

In Asia-Pacific, rapid population growth, rising healthcare awareness, and an increasing burden of chronic wounds contribute to growing market share. Countries like China, India, and South Korea are witnessing a surge in demand for advanced wound care solutions, including amniotic membranes.

Latin America and the Middle East & Africa regions are also emerging as potential growth areas. While adoption rates are currently lower compared to developed markets, improvements in healthcare infrastructure and regulatory frameworks could unlock new opportunities in the near future.

Competitive Outlook

The competitive landscape of the amniotic membranes market is characterized by a mix of established companies and emerging startups, each vying for market share through innovation, product differentiation, and strategic partnerships. Companies are heavily investing in R&D to enhance product efficacy and expand their therapeutic applications.

Intellectual property rights and patents play a critical role in maintaining competitive advantage. Firms that can secure proprietary technologies or unique processing methods often position themselves as leaders in the space.

In addition, marketing strategies focusing on educating medical professionals and end-users are essential for gaining trust and driving adoption. Companies that offer robust clinical data supporting the benefits of their products are more likely to build credibility and attract healthcare providers.

Top Companies

Several key players dominate the amniotic membranes market. These include biotechnology and medical device firms with a strong focus on regenerative medicine. Their success often hinges on innovation pipelines, regulatory approvals, and strategic collaborations with research institutions and hospitals.

Many of these companies also engage in mergers and acquisitions to expand their product portfolios and gain access to new markets. The ability to scale operations while maintaining product quality and compliance is crucial in sustaining long-term growth and profitability.

Startups in this space are increasingly making their mark by offering niche products that cater to specific therapeutic needs. Their agility and focus on innovation allow them to compete with larger firms and capture underserved segments of the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/amniotic-membrane-market

Segmentation Outlook

The amniotic membranes market can be segmented by type, application, and end-user. Based on type, the market is divided into cryopreserved and dehydrated membranes. Cryopreserved membranes retain their biological properties more effectively, making them ideal for certain surgical procedures. However, dehydrated membranes offer longer shelf life and ease of storage, making them preferable in outpatient settings.

In terms of application, the market spans ophthalmology, wound care, orthopedics, and other surgical fields. Ophthalmology remains a dominant segment due to the proven effectiveness of amniotic membranes in corneal healing and surface reconstruction. Meanwhile, the wound care segment continues to grow as these products gain recognition for their regenerative benefits.

End-users include hospitals, ambulatory surgical centers, and specialty clinics. Hospitals represent the largest share due to the high volume of surgical procedures and the availability of trained personnel. Ambulatory surgical centers and clinics are becoming increasingly important, particularly in regions focusing on cost-effective and minimally invasive care.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Enzyme Replacement Therapy Market Poised for Healthy CAGR of 6.6%

The enzyme replacement therapy market has gained significant momentum over recent years, driven by rising awareness of rare diseases and growing access to modern healthcare services. Enzyme replacement therapy (ERT) is a medical treatment designed to replace deficient or absent enzymes in patients suffering from specific metabolic disorders. These therapies are commonly used in conditions such as Gaucher disease, Fabry disease, Pompe disease, and mucopolysaccharidoses. As healthcare technologies evolve and patient-centric treatments become more common, the enzyme replacement therapy market is witnessing continuous expansion. With more investments pouring into research and development, this market is positioned for steady growth, especially with advancements in genetic medicine and personalized care approaches.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-3167

Market Trends

Several key trends are shaping the trajectory of the enzyme replacement therapy market. One of the most noticeable developments is the shift toward precision medicine. As understanding of genetic disorders deepens, therapies are being tailored to meet the specific needs of individual patients. This trend has significantly enhanced treatment outcomes and reduced adverse effects, making ERT more attractive to both clinicians and patients.

Another notable trend is the integration of advanced biotechnology techniques into the manufacturing and development process. Recombinant DNA technology, for example, is widely used to produce high-purity enzymes that closely mimic those naturally found in the human body. Additionally, increased collaboration between pharmaceutical companies and academic institutions is fostering innovation, leading to the discovery of novel enzyme candidates for therapeutic use.

Furthermore, patient advocacy groups and support networks have played a pivotal role in raising awareness and lobbying for better access to these life-changing treatments. Their efforts have led to increased funding, more clinical trials, and expanded market access across both developed and emerging economies.

Driving Forces Behind Market Growth

Several core factors are propelling the growth of the enzyme replacement therapy market. One major driver is the increasing prevalence of rare and inherited metabolic disorders. Though individually rare, these diseases collectively impact a substantial number of people worldwide. With enhanced diagnostic capabilities, more patients are being accurately diagnosed, thus fueling demand for effective treatment options such as ERT.

Another significant factor is regulatory support. Governments and regulatory bodies in many countries are facilitating faster approvals and incentivizing the development of orphan drugs. These supportive policies are encouraging pharmaceutical companies to invest in research and bring more ERT products to market.

Technological advancements in drug formulation and delivery mechanisms are also boosting the market. Newer formulations offer improved bioavailability and reduced frequency of administration, improving patient compliance. Additionally, the growing global healthcare infrastructure and increased health insurance coverage are ensuring that more patients have access to these advanced therapies.

Challenges and Opportunities

Despite the strong growth outlook, the enzyme replacement therapy market faces several challenges. High treatment costs remain a major barrier, especially in low- and middle-income countries. The expense involved in producing biologics and conducting rigorous clinical trials contributes to the premium pricing of ERT products. This financial burden often restricts access and poses a challenge to widespread adoption.

Another limitation is the potential for immune responses or reduced efficacy in some patients. As with many biologic treatments, the body may develop antibodies that neutralize the therapeutic enzyme, diminishing its effectiveness over time. Continued research is needed to overcome these biological hurdles and enhance the long-term benefits of therapy.

However, these challenges also open up significant opportunities. The growing emphasis on biosimilars and cost-effective alternatives could help mitigate pricing concerns. Investment in advanced delivery platforms, such as gene therapy or enzyme stabilization techniques, holds promise for creating more efficient and long-lasting treatment options. Moreover, emerging markets present untapped potential, where improved healthcare infrastructure and supportive regulations can drive future growth.

Recent Industry Developments

Recent years have seen a flurry of activity in the enzyme replacement therapy market. Leading pharmaceutical companies are launching next-generation products with better safety profiles and enhanced therapeutic efficacy. Strategic acquisitions and partnerships are also becoming more common, as firms seek to strengthen their pipelines and expand global reach.

One notable trend is the increased number of ERT products receiving orphan drug status. This designation provides benefits such as market exclusivity, tax credits, and reduced regulatory fees, encouraging further innovation. Clinical trials are also being streamlined through adaptive trial designs and real-world evidence collection, enabling faster and more efficient development processes.

Moreover, advancements in genetic editing technologies such as CRISPR have sparked interest in exploring alternatives or complementary therapies to traditional ERT. These developments are creating a more dynamic landscape, where innovation is central to maintaining competitiveness.

Regional Analysis

The enzyme replacement therapy market is experiencing growth across various regions, with North America leading the charge due to strong healthcare systems, early adoption of new technologies, and robust R&D infrastructure. The United States, in particular, holds a significant share owing to high healthcare spending and favorable reimbursement policies. Canada is also emerging as a promising market, thanks to increasing awareness and government support.

Europe follows closely, with countries like Germany, France, and the United Kingdom investing heavily in rare disease management. The region benefits from a well-structured regulatory framework and active patient advocacy networks that promote early diagnosis and access to treatment.

The Asia-Pacific region is witnessing rapid growth, driven by improving healthcare infrastructure and rising disposable incomes. Countries like China, Japan, and India are increasing investments in biopharmaceuticals, and local players are entering the enzyme replacement therapy market, making treatments more accessible and affordable.

Latin America and the Middle East & Africa are also showing potential, although challenges such as limited access to healthcare and high treatment costs persist. Nonetheless, growing partnerships and government initiatives are slowly bridging the gap in these underserved regions.

Competitive Outlook

The competitive landscape of the enzyme replacement therapy market is characterized by the presence of both established players and emerging biotech firms. Market leaders are investing heavily in research to develop innovative therapies and maintain their competitive edge. Strategic alliances, mergers, and acquisitions are common, as companies aim to enhance their portfolios and expand their global footprint.

Key players are also focusing on patient-centric approaches, including digital health solutions and support services, to improve treatment adherence and outcomes. Differentiation through technology and service integration is becoming a critical strategy for maintaining market share in a competitive environment.

Moreover, the entry of new players offering biosimilars is intensifying competition, leading to price reductions and increased accessibility. Companies that can balance innovation with cost-effectiveness are likely to gain a significant advantage in the long run.

Top Companies

Several companies have established a strong presence in the enzyme replacement therapy market. These include global pharmaceutical giants that have dedicated research teams and extensive distribution networks. Some of the most prominent names include Sanofi, Takeda Pharmaceutical Company, BioMarin Pharmaceutical, and Amicus Therapeutics. These firms have introduced multiple ERT products and continue to invest in pipeline development.

Other key players include Alexion Pharmaceuticals, Pfizer, and Chiesi Farmaceutici, each of which contributes to the evolving market landscape through strategic innovations and targeted therapies. The increasing involvement of smaller biotechnology firms is also notable, as these companies often bring unique approaches and specialized expertise to the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/enzyme-replacement-therapy-market

Segmentation Outlook

The enzyme replacement therapy market can be segmented by disease indication, route of administration, end-user, and region. By disease, the market includes Gaucher disease, Fabry disease, Pompe disease, and others. Gaucher disease currently represents a major share due to the availability of approved and effective treatments.

By route of administration, intravenous infusions dominate the market, but research into oral and subcutaneous options is gaining momentum. In terms of end-users, hospitals remain the primary point of care, although home-based treatments are becoming increasingly popular due to advancements in drug stability and administration devices.

Geographically, the market is segmented into North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa. Each region offers unique growth opportunities and challenges, shaping the overall global landscape of enzyme replacement therapy.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Biologic Excipient Market Forecasted to Expand from USD 1.5 Billion in 2024

The biologic excipients market has become a vital component of the pharmaceutical and biotechnology industries, playing a crucial role in the formulation of biologic drugs. These excipients are inactive substances used alongside active pharmaceutical ingredients (APIs) to ensure stability, bioavailability, and effective delivery of the drug. As the demand for biologics such as monoclonal antibodies, vaccines, and cell therapies continues to rise, so too does the importance of biologic excipients in supporting their development and commercialization.

The global biologic excipient market is projected to be appraised at USD 2,241.8 million by 2034, up from USD 1500 million in 2024, advancing at a CAGR of 4.10% from 2024 to 2034.

Biologic excipients differ significantly from those used in traditional small-molecule drugs. Due to the complex nature of biologics, excipients must be carefully selected to maintain the integrity and efficacy of sensitive molecules. The biologic excipients market has witnessed notable growth driven by advances in biopharmaceutical research and increasing approvals of biologic drugs. Manufacturers are investing in excipient innovation, seeking to develop products that meet strict regulatory standards while enhancing the performance of biotherapeutics.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-6982

The biologic excipients market is expanding across multiple regions, with growing investments from both established pharmaceutical companies and emerging biotech startups. Governments are also playing a role, funding research initiatives and providing regulatory support to encourage biologics production. The market is expected to continue its upward trajectory, driven by technological progress and increasing awareness of the importance of excipient selection in biologics formulation.

Market Trends

A key trend shaping the biologic excipients market is the shift toward high-performance excipients specifically designed for biologics. These novel excipients offer superior compatibility and stability for sensitive drug formulations. As the industry moves towards more complex biologics, such as gene therapies and biosimilars, there is an increasing demand for tailored excipients that meet specific formulation requirements.

Another significant trend is the growing use of multifunctional excipients, which provide multiple roles within a single formulation—such as stabilizers, preservatives, and solubilizers. This innovation helps streamline drug development processes and reduces formulation complexity. Additionally, the biologic excipients market is witnessing rising interest in natural and plant-based excipients, aligning with the global preference for sustainable and eco-friendly pharmaceutical ingredients.

Digitalization is also influencing the biologic excipients market. Data-driven decision-making in formulation development, quality control, and supply chain management is gaining traction. The use of AI and machine learning to predict excipient compatibility and performance is enhancing R&D efficiency, further driving growth in the biologic excipients market.

Challenges and Opportunities

Despite promising growth, the biologic excipients market faces several challenges. One major concern is the stringent regulatory landscape governing excipient approval. Regulatory bodies demand comprehensive safety and efficacy data for excipients used in biologic formulations, which often results in lengthy approval timelines. The lack of a standardized global regulatory framework adds another layer of complexity for manufacturers operating in multiple markets.

Another challenge lies in the limited availability of excipients that are specifically designed for biologics. Many existing excipients were developed for small-molecule drugs and may not meet the stringent requirements for biological formulations. This gap in the market presents a significant opportunity for innovation and development of new excipient technologies tailored to biologics.

Cost is also a barrier for smaller companies looking to enter the biologic excipients market. The development and validation of novel excipients involve significant investment, which may be out of reach for startups or smaller firms. However, strategic partnerships and licensing agreements offer potential pathways for these companies to participate in the market.

On the opportunity side, the increasing prevalence of chronic diseases and the global shift toward biologic treatments provide a strong foundation for market expansion. As more biologic drugs enter the market, the demand for reliable, high-quality excipients will continue to rise. Manufacturers that can provide safe, effective, and compliant excipients are well-positioned to capitalize on this growing need.

Key Regional Insights

The biologic excipients market shows varied dynamics across different regions. North America holds a significant share, driven by advanced healthcare infrastructure, strong biopharmaceutical industry presence, and active regulatory bodies like the FDA. The U.S., in particular, is a hub for biologic drug development, making it a key market for excipient manufacturers.

Europe follows closely, with countries like Germany, the UK, and France leading in biologic research and innovation. The European Medicines Agency (EMA) provides a robust regulatory framework that supports the development of biologic drugs and related excipients. Efforts to harmonize excipient guidelines across the EU are further strengthening the region’s market position.

Asia-Pacific is emerging as a promising region in the biologic excipients market, fueled by rapid industrialization, growing investments in healthcare, and expanding pharmaceutical manufacturing capabilities. Countries like China, India, and South Korea are making significant strides in biologic production, creating a surge in demand for suitable excipients.

Latin America and the Middle East & Africa are gradually entering the biologic excipients market, driven by increasing healthcare access and government initiatives to boost local pharmaceutical industries. Although these regions currently represent a smaller market share, their growth potential is considerable as biologic therapies become more accessible.

Competitive Outlook

The biologic excipients market is highly competitive, with companies focusing on product innovation, strategic collaborations, and geographic expansion. Key players are investing heavily in research and development to create excipients that address the unique needs of biologic formulations. Companies are also pursuing mergers and acquisitions to expand their product portfolios and enhance their market presence.

Competition is intensifying as more players enter the market with specialized offerings. Differentiation is often achieved through the development of excipients that provide enhanced stability, reduced immunogenicity, and improved solubility. Companies that can demonstrate the clinical and regulatory advantages of their products stand to gain a significant edge.

Collaborations between excipient manufacturers and biopharmaceutical firms are becoming more common. These partnerships aim to integrate excipient selection early in the drug development process, reducing formulation risks and accelerating time to market. This trend is expected to continue, further driving innovation and competition in the biologic excipients market.

Top Companies

Several companies lead the biologic excipients market, leveraging their expertise and global reach to maintain strong market positions. These include pharmaceutical and chemical giants with well-established R&D infrastructures and extensive product portfolios. These firms offer a wide range of excipients tailored to various biologic drugs and have a strong track record of regulatory compliance.

In addition to large corporations, there is also a growing presence of niche players specializing in high-purity and custom excipients. These companies often cater to specific segments within the biologic excipients market, such as vaccines, monoclonal antibodies, or gene therapies. Their focus on innovation and flexibility allows them to meet the unique demands of small to mid-sized biopharmaceutical companies.

As competition grows, these top companies are increasingly investing in quality control, sustainable production methods, and advanced analytical techniques. This not only helps ensure product safety and efficacy but also enhances their reputation as reliable partners in biologic drug development.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/biologic-excipients-market

Segmentation Outlook

The biologic excipients market can be segmented based on type, function, biologic drug class, and end-user. In terms of type, excipients such as polymers, sugars, surfactants, and amino acids are widely used. Each type plays a distinct role in ensuring the stability and effectiveness of biologic formulations.

By function, the market includes stabilizers, solubilizers, tonicity agents, bulking agents, and others. Stabilizers, for instance, are critical in preserving the structure of protein-based drugs during storage and transportation. Solubilizers help increase the bioavailability of hydrophobic biologics, while tonicity agents ensure compatibility with physiological fluids.

The biologic excipients market is also segmented by the type of biologic drug, including monoclonal antibodies, vaccines, recombinant proteins, and cell and gene therapies. Each category requires specific excipient characteristics to ensure efficacy and safety. With the growing adoption of advanced therapies, the demand for tailored excipients is expected to rise.

End-users in the biologic excipients market primarily include biopharmaceutical companies, contract research organizations (CROs), and academic research institutes. Biopharmaceutical firms represent the largest segment, owing to their direct involvement in drug development and commercialization. However, CROs are playing an increasingly important role as outsourcing trends continue to grow.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Behavioral Health Market Projected to Grow at 3% CAGR Through 2034

The global behavioral health market is estimated at USD 127 billion in 2024 and is anticipated to generate revenues of USD 175.7 billion by 2034. The industry is forecast to rise at a CAGR of 3% in the forecast period.

The behavioural health market encompasses a broad range of services and treatments designed to address mental health conditions, substance abuse issues, and other emotional or psychological disorders. This market has gained increased attention in recent years as awareness about mental wellness continues to rise among populations and governments alike. The growing importance of behavioural health can be attributed to its impact on individuals’ overall well-being and its influence on economic productivity. Healthcare systems around the world are placing greater emphasis on integrating mental health services with primary healthcare, thereby making the behavioural health market a critical component of the global health landscape.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-5375

The market includes outpatient counselling, inpatient psychiatric services, substance abuse treatments, and community mental health programs. Advancements in technology and digital health platforms are also contributing to the evolution of this market, making therapy and support more accessible. Additionally, the global push to destigmatize mental illness and promote emotional well-being is encouraging both private and public sectors to invest in behavioural health infrastructure and solutions.

Size & Trends

The behavioural health market is experiencing robust growth, driven by a combination of rising prevalence of mental health disorders and increasing demand for effective treatment solutions. Social and economic stressors, lifestyle changes, and the ongoing impact of global events such as pandemics have significantly influenced the market dynamics. As mental health continues to be prioritized, more individuals are seeking professional help, which in turn is expanding the market.

Telehealth services have emerged as a transformative trend in this space. With the advent of virtual consultations, behavioural health services have become more accessible to people living in remote and underserved areas. Moreover, wearable devices and mobile applications designed for mental well-being are witnessing increased adoption. These tools provide real-time monitoring and data-driven insights, helping clinicians and patients manage behavioural health conditions more effectively.

Another key trend is the integration of behavioural health into value-based care models. Payers and providers are recognizing the importance of treating mental health in tandem with physical health to improve patient outcomes and reduce long-term costs. This integrated care approach is expected to further drive the behavioural health market forward in the coming years.

Key Highlights

A significant highlight in the behavioural health market is the increasing role of artificial intelligence and machine learning in diagnosis and treatment planning. These technologies are aiding in the early detection of disorders and in personalizing treatment protocols based on individual patient data. AI-enabled platforms are being used to predict potential relapses and improve therapy outcomes by offering insights into patient behavior patterns.

In addition to technological advancements, public policy changes are shaping the market. Many governments are now enforcing parity laws that mandate equal treatment for mental and physical health conditions by insurance providers. These legal frameworks are boosting access to behavioural health services and removing long-standing financial barriers for many patients.

The expansion of employer-sponsored wellness programs is another important development. Corporations are increasingly incorporating behavioural health components into their employee assistance programs (EAPs). This shift is not only beneficial for employees but also advantageous for employers who witness higher productivity and reduced absenteeism.

Challenges and Opportunities

Despite the market’s growth, the behavioural health market faces several challenges. One of the most persistent issues is the shortage of qualified mental health professionals, which leads to long wait times and limits access to care, especially in rural regions. Additionally, the stigma associated with mental health continues to prevent many individuals from seeking the help they need.

Fragmented care delivery systems also hinder progress. Many patients receive services from multiple providers, which can result in inconsistent care and communication gaps. The lack of standardized treatment protocols and outcome measurement tools further complicates the efficacy and scalability of behavioural health services.

However, these challenges also present opportunities. The ongoing digital transformation of healthcare offers promising solutions to the accessibility and fragmentation issues. Telehealth, AI tools, and centralized health records can significantly streamline service delivery and patient management. Moreover, educational campaigns and community-based outreach initiatives are gaining traction, helping to reduce stigma and promote mental health literacy.

Key Benefits for Stakeholders

Stakeholders across the healthcare ecosystem stand to benefit significantly from the growth of the behavioural health market. For patients, the increased focus on behavioural health means better access to timely and effective care. It also contributes to improved quality of life and long-term well-being. Healthcare providers gain from enhanced integration of services and data analytics that can support personalized treatment plans and improved outcomes.

Payers, including insurance companies, can reduce overall healthcare costs through preventive care and early intervention strategies that behavioural health services facilitate. Government bodies benefit from a healthier, more productive population, which reduces the economic burden associated with untreated mental illnesses.

Investors and healthcare technology companies also find promising opportunities in this expanding market. As demand for digital solutions continues to rise, stakeholders who invest in innovative behavioural health tools and platforms can expect substantial returns.

Market Share by Geographical Region

The behavioural health market is seeing variable growth rates across different regions, driven by local healthcare infrastructure, policy frameworks, and cultural attitudes toward mental health. North America, particularly the United States, holds a significant share due to strong insurance coverage, robust digital health ecosystems, and proactive governmental initiatives. The integration of mental health into primary care and school-based health programs further strengthens this region’s market presence.

Europe also represents a mature market with comprehensive public health systems that include behavioural health services. The region continues to invest in mental wellness campaigns and community outreach programs aimed at early intervention and destigmatization.

Asia-Pacific is emerging as a key growth region in the behavioural health market. Countries like India, China, and Japan are increasing their focus on mental health due to rising awareness, urbanization, and growing healthcare expenditures. However, cultural stigma and insufficient infrastructure remain challenges that need to be addressed to unlock the region’s full potential.

Competitive Outlook

The behavioural health market is highly competitive and characterized by the presence of a diverse set of players ranging from large hospital networks and specialty clinics to digital health startups. Companies are differentiating themselves through specialized service offerings, technological innovation, and integrated care models.

Strategic collaborations and mergers are common in this market, aimed at enhancing service delivery and expanding geographical reach. Many players are investing heavily in telepsychiatry and AI-powered diagnostic tools to stay ahead of the curve. Regulatory compliance, patient data security, and service quality remain critical areas of focus for companies operating in this space.

Top Companies

Several leading organizations are making notable contributions to the behavioural health market. These include healthcare service providers, digital health platforms, and pharmaceutical companies. Their efforts are geared toward expanding access to care, improving treatment efficacy, and advancing research in behavioural sciences.

These top companies are also active in public-private partnerships that aim to build sustainable behavioural health infrastructures. Many are investing in R&D to develop novel therapies and digital interventions that cater to a wide range of mental health conditions. Their commitment to innovation and community engagement is helping to elevate the standard of care across the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/behavioral-health-market

Segmentation Outlook

The behavioural health market is segmented by service type, disorder type, end-user, and delivery mode. Service segments typically include inpatient, outpatient, and emergency mental health services. Disorder segments encompass conditions such as depression, anxiety, bipolar disorder, schizophrenia, and substance abuse disorders.

End-users in the market range from adults and adolescents to the elderly, each requiring tailored treatment approaches. Delivery modes are increasingly shifting toward digital platforms, with telehealth and mobile applications playing a crucial role in service provision.

This segmentation allows providers to develop targeted strategies that meet specific population needs while maximizing service efficiency. Understanding these segments also enables stakeholders to identify high-growth areas and allocate resources accordingly, ensuring sustained development within the behavioural health market.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Pulmonary Arterial Hypertension Treatment Market Growth Forecast at 2.3% CAGR Until 2035

The pulmonary arterial hypertension treatment market has witnessed a significant transformation in recent years, driven by advancements in medical research and increasing awareness about rare cardiovascular diseases. Pulmonary arterial hypertension (PAH) is a progressive condition characterized by elevated blood pressure in the arteries that supply the lungs, which can lead to heart failure if left untreated. The growing incidence of PAH across various regions has spurred the demand for effective treatment options, thereby catalyzing the growth of the pulmonary arterial hypertension treatment market.

The pulmonary arterial hypertension market is expected to reach USD 2,080.7 million by 2025 and is expected to steadily grow at a CAGR of 2.3% to reach USD 2,612.0 million by 2035.

Innovations in pharmacological therapies and diagnostic technologies have further expanded the treatment landscape. The availability of a broader range of therapeutic options, including prostacyclin analogs, endothelin receptor antagonists, and phosphodiesterase-5 inhibitors, has allowed physicians to tailor treatments based on individual patient needs. This personalized approach has improved patient outcomes and contributed to the long-term sustainability of the pulmonary arterial hypertension treatment market.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1218

Market Trends

The pulmonary arterial hypertension treatment market is undergoing rapid evolution due to emerging trends in drug development and patient care. One major trend is the increasing adoption of combination therapies, which involve using two or more drugs to target different pathways in the disease process. This approach has demonstrated improved efficacy compared to monotherapy, leading to better disease management and quality of life for patients.

Another prominent trend is the shift towards oral and inhalable drug delivery systems. These alternatives to intravenous medications offer greater convenience and reduce the burden on healthcare systems. Moreover, telehealth and remote patient monitoring technologies are gaining traction, allowing for continuous observation and adjustment of treatment protocols, especially in rural and underserved regions. These innovations are streamlining the overall management of PAH and contributing to the expansion of the pulmonary arterial hypertension treatment market.

Driving Forces Behind Market Growth

Several key factors are driving the growth of the pulmonary arterial hypertension treatment market. The rising prevalence of risk factors such as connective tissue disorders, HIV infection, and congenital heart disease has led to an increase in PAH diagnoses worldwide. As more people become aware of the symptoms and seek medical attention, the demand for effective treatments continues to rise.

Government initiatives and increased healthcare spending have also played a crucial role in market expansion. Many countries have implemented reimbursement policies and public health campaigns to support the diagnosis and treatment of rare diseases like PAH. Additionally, pharmaceutical companies are investing heavily in research and development, seeking to bring novel therapies to market and address unmet medical needs. These combined forces are propelling the pulmonary arterial hypertension treatment market forward at a steady pace.

Challenges and Opportunities

Despite the positive momentum, the pulmonary arterial hypertension treatment market faces several challenges that could hinder its growth. One of the most significant barriers is the high cost of treatment. Many PAH therapies are expensive, placing a financial burden on both patients and healthcare systems. Limited access to advanced treatment options in low-income countries further exacerbates this issue, creating disparities in patient care.

Moreover, the complexity of PAH diagnosis often results in delayed treatment initiation. Symptoms of the disease can be non-specific, making early detection difficult. This highlights the need for more accessible diagnostic tools and greater awareness among healthcare providers.

However, these challenges also present opportunities for market players. Companies that can develop cost-effective, easily accessible therapies and diagnostics stand to gain a competitive edge. The rise of biosimilars and generic drugs could lower treatment costs and improve accessibility. Furthermore, collaborations between public and private sectors can facilitate research and improve patient outcomes, opening new avenues for growth within the pulmonary arterial hypertension treatment market.

Recent Industry Developments

Recent developments within the pulmonary arterial hypertension treatment market have set the stage for a more dynamic and innovative future. Several new drugs have received regulatory approval, offering fresh options for clinicians and patients alike. For instance, therapies targeting novel molecular pathways have shown promise in clinical trials, expanding the scope of available treatments.

In addition to pharmacological advancements, strategic partnerships and acquisitions have become increasingly common. Pharmaceutical companies are joining forces with biotech firms and academic institutions to accelerate drug discovery and development. These collaborations aim to combine expertise and resources, driving innovation and improving the success rate of clinical trials.

Moreover, digital health solutions are being integrated into patient care, allowing for more personalized and proactive treatment strategies. Remote monitoring devices and AI-powered diagnostic tools are enhancing the ability to track disease progression and adjust treatments in real time, further enriching the pulmonary arterial hypertension treatment market.

Regional Analysis

The pulmonary arterial hypertension treatment market exhibits regional disparities due to differences in healthcare infrastructure, economic development, and awareness levels. North America remains a dominant player, driven by robust healthcare systems, high levels of research funding, and favorable reimbursement policies. The United States, in particular, boasts a high concentration of pharmaceutical companies and research institutions, making it a hub for innovation in PAH treatment.

Europe follows closely, with countries like Germany, France, and the United Kingdom investing heavily in rare disease research and treatment. Collaborative healthcare frameworks and government support have contributed to the steady growth of the market in this region.

The Asia-Pacific region is witnessing rapid market expansion, fueled by rising healthcare investments and an increasing burden of cardiovascular diseases. Countries such as China, India, and Japan are enhancing their diagnostic capabilities and pharmaceutical manufacturing capacities. As awareness grows and healthcare access improves, the pulmonary arterial hypertension treatment market in this region is expected to flourish.

Meanwhile, Latin America and the Middle East & Africa are gradually gaining traction. Although these regions face challenges such as limited healthcare infrastructure and lower per capita income, initiatives aimed at improving rare disease management are beginning to yield results. With continued investment and strategic partnerships, these emerging markets hold considerable growth potential.

Competitive Outlook

The competitive landscape of the pulmonary arterial hypertension treatment market is marked by intense rivalry and a focus on innovation. Key players are continuously seeking ways to differentiate themselves through product development, strategic alliances, and global expansion. Companies that can offer comprehensive treatment solutions, encompassing diagnostics, drug delivery, and patient support services, are well-positioned to lead the market.

Research and development remain at the heart of competitive strategy, with many companies exploring next-generation therapies, including gene editing and regenerative medicine. These cutting-edge approaches aim to address the underlying causes of PAH rather than merely managing symptoms, potentially transforming the treatment paradigm.

Additionally, companies are leveraging data analytics and artificial intelligence to optimize clinical trials and improve treatment efficacy. As digital transformation accelerates across the healthcare sector, players that adapt quickly to technological advances are likely to secure a strong foothold in the pulmonary arterial hypertension treatment market.

Top Companies

Several prominent companies are shaping the future of the pulmonary arterial hypertension treatment market through continuous innovation and strategic initiatives. Industry leaders such as Johnson & Johnson, Bayer AG, United Therapeutics Corporation, and GlaxoSmithKline have a robust pipeline of PAH drugs and a strong presence across multiple regions.

Emerging biotech firms are also making their mark by focusing on niche areas and developing novel therapies. These companies often collaborate with larger pharmaceutical firms to bring their innovations to market more efficiently. Their agility and focus on unmet medical needs make them valuable contributors to the evolving treatment landscape.

With ongoing competition and a shared commitment to advancing patient care, these top companies are driving the growth and development of the pulmonary arterial hypertension treatment market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/pulmonary-arterial-hypertension-treatment-market

Segmentation Outlook

The pulmonary arterial hypertension treatment market is segmented based on drug class, route of administration, distribution channel, and end-user. Drug class segmentation includes prostacyclin analogs, endothelin receptor antagonists, soluble guanylate cyclase stimulators, and phosphodiesterase-5 inhibitors. Each of these drug classes offers unique benefits and is chosen based on the severity of the condition and patient response.

Route of administration is another important segment, encompassing oral, injectable, and inhalation therapies. Oral drugs remain the most preferred due to ease of use, but injectable and inhalable options provide critical benefits for certain patient groups.

The distribution channel segment includes hospital pharmacies, retail pharmacies, and online pharmacies. Hospital pharmacies continue to dominate due to the complex nature of PAH treatment, which often requires close medical supervision. However, online pharmacies are gaining popularity due to improved accessibility and convenience.

End-users in this market include hospitals, specialty clinics, and homecare settings. While hospitals and specialty clinics remain primary users, the homecare segment is expanding due to advancements in portable drug delivery devices and telehealth services.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Muscle Stimulation Devices Market Set for Steady Growth Through 2035

The Muscle Stimulation Devices Market is valued at USD 781.9 million USA dollars in 2025. The market to grow through CAGR 3.9% over the forecast years and is expected to reach USD 1,146.6 million by 2035.

The muscle stimulation devices market is witnessing consistent growth due to the increasing demand for non-invasive therapies that promote muscle recovery, rehabilitation, and performance enhancement. These devices use electrical impulses to contract muscles, offering a range of benefits from pain relief to improved blood circulation and muscle conditioning. As healthcare providers and fitness enthusiasts continue to adopt innovative solutions, the muscle stimulation devices market has found applications in both medical and consumer wellness sectors.

This growing acceptance is further supported by technological advancements and the increasing awareness about physical therapy and preventive healthcare. The rise in sports injuries, aging population, and post-surgical rehabilitation needs are further fueling the demand. Additionally, professional athletes and individuals engaged in regular physical activities are seeking muscle stimulation devices to accelerate recovery and boost performance.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1140

The muscle stimulation devices market is not limited to hospitals and physiotherapy clinics. It has expanded into homecare settings and consumer electronics, where portable and user-friendly devices are becoming popular. With more people seeking cost-effective alternatives to traditional therapy, these devices have gained significant traction, signaling a robust growth trajectory in the coming years.

Market Trends

Several emerging trends are shaping the muscle stimulation devices market, contributing to its widespread adoption. One of the prominent trends is the miniaturization of devices, allowing for more compact, wearable, and portable solutions. Consumers now prefer easy-to-use muscle stimulation products that can be conveniently used at home, at work, or even during travel.

Another trend gaining momentum is the integration of smart technology and app-based controls. These features allow users to customize their therapy sessions, track progress, and receive real-time feedback. The integration of artificial intelligence and machine learning is also being explored to deliver more personalized stimulation patterns based on individual needs.

Additionally, the rising popularity of fitness and wellness lifestyles has expanded the scope of the muscle stimulation devices market. Many fitness centers and gyms have started incorporating these devices as part of recovery and muscle conditioning programs. Combined with marketing efforts from top brands and endorsements from professional athletes, this has driven public interest and adoption.

The growing focus on preventive healthcare is another major trend. Consumers are now more proactive about maintaining their physical health and avoiding injuries, which has translated into higher demand for at-home therapeutic options. These factors, when viewed together, underscore the evolving nature of the muscle stimulation devices market and its potential for further innovation.

Challenges and Opportunities

Despite the promising outlook, the muscle stimulation devices market faces several challenges that stakeholders must navigate. One of the key issues is the lack of standardized regulations and certifications across different regions. This creates uncertainty regarding the safety and effectiveness of some products, especially those sold online or through unverified distributors.

In addition, high costs associated with premium devices may deter adoption, particularly in emerging economies where healthcare budgets are limited. Insurance coverage for muscle stimulation therapy is also inconsistent, making it difficult for some patients to afford long-term treatment.

There is also a need for more clinical evidence supporting the efficacy of certain muscle stimulation devices, especially those marketed for non-medical use. Without proper studies and regulatory backing, consumer trust may waver, limiting the market’s potential.

However, these challenges present opportunities as well. Manufacturers can invest in research and development to create cost-effective, evidence-backed products. Expanding into underpenetrated regions with tailored marketing and pricing strategies can also unlock new revenue streams.

Furthermore, collaborations with healthcare providers, fitness institutions, and rehabilitation centers can enhance the credibility of these devices and ensure better consumer education. As awareness grows and accessibility improves, the muscle stimulation devices market is poised to overcome current limitations and continue its upward trend.

Key Regional Insights

The muscle stimulation devices market shows varied dynamics across different geographical regions. In North America, especially the United States, the market is driven by high healthcare spending, advanced technology adoption, and a growing focus on fitness and wellness. The presence of key market players and a well-established distribution network further strengthens the region’s dominance.

In Europe, similar factors contribute to market growth, along with strong public healthcare systems that facilitate access to rehabilitation therapies. Countries like Germany, the UK, and France are leading the regional demand, supported by an aging population and increasing prevalence of chronic pain and musculoskeletal disorders.

The Asia-Pacific region is expected to witness the fastest growth in the muscle stimulation devices market. Rising healthcare awareness, expanding middle-class population, and growing interest in physical wellness are key contributors. Countries like China, India, Japan, and South Korea are becoming lucrative markets for both local and international manufacturers.

Latin America and the Middle East & Africa are emerging markets where adoption is still in the early stages. However, improvements in healthcare infrastructure and increasing exposure to modern therapeutic options offer significant growth potential. Strategic investments and partnerships in these regions could accelerate market penetration and long-term success.

Competitive Outlook

The competitive landscape of the muscle stimulation devices market is marked by the presence of both established companies and new entrants. Leading players are focusing on innovation, product differentiation, and strategic partnerships to maintain their market share and attract a broader customer base.

Product innovation remains at the forefront, with many companies developing multifunctional devices that combine muscle stimulation with other therapies like heat, vibration, and massage. These value-added features enhance user experience and expand the applicability of the devices in various treatment and fitness scenarios.

Marketing strategies are also evolving, with companies leveraging social media, influencer endorsements, and digital campaigns to connect with tech-savvy consumers. Customization and aesthetic design are gaining importance, as buyers increasingly seek products that align with their lifestyle and personal preferences.

Companies are also investing in training programs and partnerships with healthcare providers to ensure proper use of the devices. This improves clinical outcomes and strengthens brand reputation. As competition intensifies, only those companies that balance quality, innovation, and affordability are expected to thrive in the dynamic muscle stimulation devices market.

Top Companies

Several top companies are shaping the future of the muscle stimulation devices market through consistent innovation and strategic growth initiatives. Among the notable players are DJO Global, Zynex Inc., Omron Corporation, Beurer GmbH, and BioMedical Life Systems. These companies offer a broad range of products catering to both medical professionals and consumers.

Other key players include Compex, NeuroMetrix Inc., Tone-A-Matic, and EMS Physio Ltd., each contributing unique capabilities to the market. These companies are known for their strong research and development pipelines, commitment to quality, and extensive distribution channels that ensure widespread product availability.

Startups and niche players are also gaining traction by introducing novel features and targeting specific consumer segments. The rise of e-commerce platforms has further leveled the playing field, enabling smaller brands to compete effectively with established firms in the muscle stimulation devices market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/muscle-stimulation-devices-market

Segmentation Outlook

The muscle stimulation devices market can be segmented based on product type, application, end-user, and distribution channel. Product-wise, the market includes transcutaneous electrical nerve stimulation (TENS) devices, neuromuscular electrical stimulation (NMES) devices, and other specialized units. Each type offers different benefits, catering to various therapeutic and fitness needs.

By application, the market encompasses pain management, neurological disorders, muscle rehabilitation, cosmetic muscle toning, and athletic training. The wide range of use cases has expanded the relevance of muscle stimulation devices beyond conventional medical therapy.

End-users include hospitals, physiotherapy clinics, sports and fitness centers, and homecare settings. The growing demand for personal wellness and convenience has led to a surge in home-use devices, particularly those that are user-friendly and app-enabled.

Distribution channels range from traditional medical equipment suppliers to online platforms, retail stores, and direct-to-consumer sales. The shift toward digital sales channels has opened new avenues for companies to reach global audiences, enhancing accessibility and brand visibility in the muscle stimulation devices market.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Whole Genome Amplification Market Projected to Grow from USD 2.9 Million in 2024 to Over USD 6.5 Million by 2034

The whole genome amplification market is anticipated to reach over USD 6.5 million by 2034, with sales projected to reach USD 2.9 million in 2024. The WGA industry is envisioned to register an 8.1% CAGR between 2024 and 2034, highlighting its sustained demand and potential impact on various research fields.

The whole genome amplification market has emerged as a vital segment within the biotechnology and life sciences industries. Whole genome amplification is a powerful molecular biology technique that enables the replication of an entire genome from minimal amounts of DNA. This technique plays a significant role in genetic and genomic studies, particularly when dealing with limited biological samples. Researchers rely on it for applications in diagnostics, forensic science, and single-cell analysis. With advancements in genomic research and the growing need for accurate DNA profiling, the market is experiencing heightened interest from both public and private research institutions.

In recent years, the whole genome amplification market has seen substantial traction due to the surge in personalized medicine, disease diagnosis, and genomic data analysis. As next-generation sequencing becomes more accessible and cost-effective, the demand for high-quality and amplified DNA samples grows. The technology facilitates more robust and precise downstream analysis, making it indispensable in genomic workflows.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1873

Size & Trends

The whole genome amplification market is experiencing a steady growth trajectory, fueled by technological progress and the increasing demand for genomic data in various research fields. Rising investments in genomics projects, such as population-scale genome sequencing programs, are creating more avenues for the adoption of whole genome amplification technologies. The rise in chronic diseases, genetic disorders, and cancer incidences is also pushing the demand for early diagnosis, thereby supporting the market’s growth.

A growing trend in the market is the shift toward automation and high-throughput solutions. Laboratories and research facilities are increasingly adopting automated systems to streamline the genome amplification process and reduce human error. Moreover, the integration of artificial intelligence and machine learning in genomic data analysis is opening up new possibilities for more effective and efficient research. These trends are expected to continue influencing the whole genome amplification market in the foreseeable future.

Key Highlights

One of the notable highlights of the whole genome amplification market is its extensive utility in single-cell genomics. With the ability to amplify minute DNA samples, researchers can now explore genomic information from a single cell, enabling more precise studies in cancer research, microbiology, and developmental biology. This capability significantly enhances our understanding of cellular functions and mutations.

Another important highlight is the increasing collaboration between academic institutions and biotechnology companies. These partnerships are accelerating innovation and facilitating the development of more advanced whole genome amplification kits and reagents. Moreover, government initiatives and funding for genomic research are also boosting the market, as national healthcare systems prioritize personalized medicine and early disease detection.

Challenges and Opportunities

Despite its promising growth, the whole genome amplification market faces certain challenges. One of the primary concerns is the risk of amplification bias, which can affect the accuracy of downstream applications such as sequencing and microarray analysis. The presence of contamination and technical limitations in certain methods can also impact the quality of amplified DNA. These issues necessitate continued innovation and rigorous quality control measures.

However, these challenges also present opportunities. The ongoing development of novel amplification techniques and enzyme formulations can minimize bias and improve efficiency. Emerging markets, especially in Asia-Pacific and Latin America, offer untapped growth potential due to rising healthcare infrastructure and increased awareness about genetic testing. As researchers look for more refined and scalable solutions, companies that invest in R&D and innovation are likely to capture a larger share of the whole genome amplification market.

Key Benefits for Stakeholders

For stakeholders across the biotechnology and healthcare ecosystems, the whole genome amplification market offers numerous benefits. Research laboratories gain access to high-quality amplified DNA, enabling them to perform more accurate and reproducible experiments. Diagnostic companies benefit from improved sensitivity and specificity in their genetic testing kits, which enhances patient outcomes and trust.

Healthcare providers also find value in the market, as it supports the broader adoption of personalized medicine. Accurate genome amplification allows for better understanding of patient genetics, which in turn informs treatment decisions. For investors and policymakers, the market represents a promising avenue for growth, innovation, and public health advancement.

Market Share by Geographical Region

The whole genome amplification market demonstrates varied performance across different geographical regions. North America currently holds a significant share, driven by well-established research infrastructure, government funding, and a high concentration of leading biotechnology companies. The presence of prominent academic institutions and the early adoption of advanced genomic technologies further solidify its position.

Europe follows closely, with strong investments in life sciences research and collaborations between the private sector and academic institutions. Countries such as Germany, the UK, and France are at the forefront of genomics research in the region.

Asia-Pacific is emerging as a lucrative market due to its growing focus on healthcare modernization, increased funding for genomics research, and a rising number of biotechnological startups. China, India, and Japan are making notable strides in the field, which will likely translate into higher market shares in the coming years.

Competitive Outlook

The whole genome amplification market is characterized by intense competition and rapid innovation. Key players are focusing on product development, strategic partnerships, and global expansion to strengthen their market presence. Companies are investing in R&D to introduce advanced and more efficient amplification kits that reduce errors and enhance reliability.

Additionally, many organizations are adopting digital transformation strategies to integrate genome amplification technologies with bioinformatics and cloud-based platforms. This move not only streamlines data management but also provides end-users with scalable and customized solutions. As competition intensifies, companies that offer high performance, ease-of-use, and cost-effective solutions are expected to outperform their peers.

Top Companies

Several companies play a pivotal role in shaping the whole genome amplification market. These organizations are at the forefront of innovation, offering cutting-edge products and solutions that meet the evolving demands of researchers and clinicians. Their contributions are essential to the advancement of genome analysis and diagnostics.

These top companies typically offer a wide range of amplification kits, reagents, and custom services to cater to various end-users. Their global presence, strong distribution networks, and commitment to quality and compliance standards allow them to maintain a competitive edge. Moreover, ongoing partnerships with academic institutions and research consortia further amplify their influence in the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/whole-genome-amplification-market

Segmentation Outlook

The whole genome amplification market can be segmented based on technology, application, end-user, and region. From a technology standpoint, multiple displacement amplification, PCR-based techniques, and hybrid methods are among the commonly used approaches. Each offers distinct advantages depending on the sample type and research objective.

In terms of application, the market serves diverse sectors such as diagnostics, drug discovery, forensics, agriculture, and single-cell genomics. The growing relevance of personalized medicine and oncology has especially boosted demand in the diagnostics segment. End-users of whole genome amplification solutions include academic research institutions, hospitals, diagnostic laboratories, and pharmaceutical companies.

Regionally, the market outlook remains dynamic, with North America and Europe continuing to lead, while Asia-Pacific presents high growth potential. As technological advancements and funding initiatives increase across these regions, segmentation patterns are expected to evolve in alignment with user demands and regulatory frameworks.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube