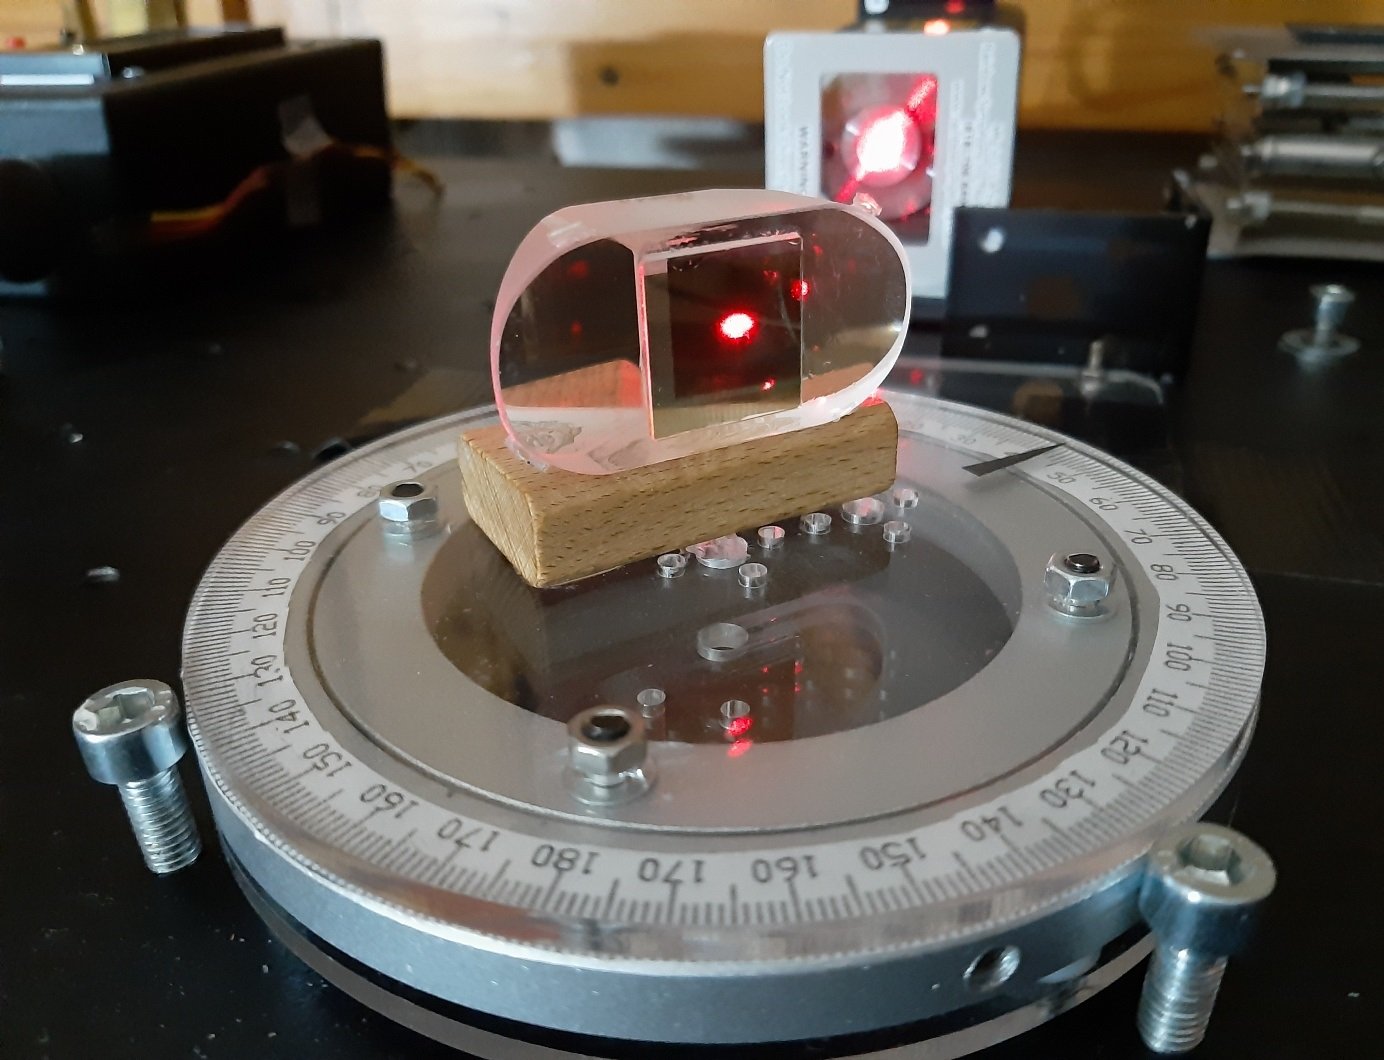
Surface Plasmon Resonance System Market Projected to Hit USD 1.6 Billion by 2034

The surface plasmon resonance market has gained significant attention in recent years due to its crucial role in biosensing, diagnostics, and drug discovery. Surface plasmon resonance (SPR) technology enables real-time, label-free detection of molecular interactions, making it indispensable in various scientific and industrial applications. The growing demand for rapid and accurate biomolecular analysis is fueling the expansion of this market globally. Researchers and companies increasingly rely on surface plasmon resonance systems to better understand binding kinetics, affinities, and concentration of biomolecules. The versatility of SPR in analyzing proteins, nucleic acids, small molecules, and even whole cells provides broad application potential across pharmaceuticals, environmental monitoring, food safety, and healthcare sectors.

The positive trend will endure, with forecasts indicating that the market will escalate to USD 1.6 billion by 2034. This equates to a moderate CAGR of 5.1% over the forecast period.

Advancements in surface plasmon resonance instruments, including improvements in sensitivity, throughput, and ease of use, are further propelling the market’s growth. As more organizations adopt SPR for early-stage drug development and diagnostic assays, the surface plasmon resonance market is poised to transform conventional research methodologies and streamline workflows. However, the cost of sophisticated SPR systems and the need for specialized technical expertise remain factors that could limit widespread adoption in some regions. Nonetheless, ongoing innovation and expanding applications continue to drive the overall market trajectory.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-962

Market Trends

Several notable trends are shaping the surface plasmon resonance market landscape. A prominent development is the integration of SPR with microfluidics and lab-on-a-chip technologies, which enhances analytical capabilities while reducing sample volumes and assay times. This convergence supports the trend toward miniaturization and automation, making SPR instruments more accessible for routine laboratory use.

Another important trend is the increased use of SPR in personalized medicine. By enabling detailed molecular interaction studies, SPR aids in identifying biomarkers and therapeutic targets tailored to individual patients. This trend aligns with the broader movement toward precision healthcare, emphasizing targeted therapies and diagnostics.

Collaborations between academic institutions, pharmaceutical companies, and technology providers are becoming more common, fostering innovation in SPR applications. Such partnerships are accelerating the development of novel sensor surfaces, improved data analysis software, and multiplexed SPR systems capable of analyzing multiple interactions simultaneously.

Environmental and food safety testing is also gaining traction as a significant application area within the surface plasmon resonance market. Growing awareness of contaminants and pathogens in food and water is driving demand for rapid, sensitive detection methods, positioning SPR as a valuable tool in this domain.

Challenges and Opportunities

Despite its promising outlook, the surface plasmon resonance market faces several challenges. One major obstacle is the high initial investment required for purchasing advanced SPR instruments, which may be prohibitive for smaller research labs or emerging markets. Additionally, the complexity of data interpretation and the need for trained personnel can limit the technology’s accessibility and widespread adoption.

Another challenge lies in the competition from alternative biosensing technologies, such as fluorescence-based assays, mass spectrometry, and other label-free techniques. These alternatives sometimes offer complementary advantages or lower costs, which may affect the demand for SPR systems.

On the opportunity front, there is significant potential in expanding SPR applications beyond traditional life sciences. Emerging fields like nanotechnology, material science, and environmental monitoring offer new avenues for SPR utilization. The development of portable and user-friendly SPR devices could unlock markets in point-of-care diagnostics and on-site environmental testing.

Growing investments in research and development across pharmaceutical and biotechnology sectors also present opportunities for the surface plasmon resonance market. As the demand for high-throughput screening and drug candidate validation rises, SPR’s ability to deliver precise kinetic and affinity data positions it as a critical analytical platform.

Key Regional Insights

Geographical dynamics play a vital role in shaping the surface plasmon resonance market. North America continues to hold a substantial share, driven by strong research infrastructure, significant pharmaceutical and biotechnology activities, and early adoption of cutting-edge technologies. The presence of major market players and ongoing clinical trials also contribute to regional growth.

Europe follows closely, with increasing government funding for life sciences research and stringent regulatory frameworks that encourage advanced diagnostic methods. Countries within Europe are actively investing in SPR technology for healthcare, environmental, and food safety applications.

Asia-Pacific is emerging as a rapidly growing region in the surface plasmon resonance market. Rising healthcare expenditure, expanding pharmaceutical industries, and increasing research collaborations are key factors driving growth in this region. Additionally, the growing number of CROs (Contract Research Organizations) and academic institutions adopting SPR technology is contributing to its adoption.

Other regions, including Latin America and the Middle East & Africa, are gradually embracing surface plasmon resonance technologies. Though these markets are at an early stage, increasing awareness and infrastructural development offer growth potential over the coming years.

Competitive Outlook

The competitive landscape of the surface plasmon resonance market is characterized by innovation, product development, and strategic partnerships. Leading companies are continuously enhancing their product portfolios by incorporating advanced features like enhanced sensitivity, multiplexing, and user-friendly interfaces. The competition drives technological progress and expands application possibilities, benefiting end-users.

Collaborations and acquisitions are common strategies adopted by key market players to strengthen their market positions and gain access to new technologies or markets. Investment in research and development remains a priority to maintain competitive advantage and address emerging customer needs.

Moreover, customer support, training programs, and customization options have become important differentiators among competitors. Companies that can provide comprehensive solutions, including instruments, reagents, and software analytics, tend to secure loyal customer bases and expand their reach.

Top Companies

Several companies dominate the surface plasmon resonance market by offering comprehensive SPR systems and solutions. These organizations focus on innovation, quality, and service excellence to meet evolving industry demands.

Market leaders include firms specializing in SPR instrumentation, biosensors, and related reagents. They invest heavily in technology upgrades, product diversification, and global expansion to maintain leadership. By collaborating with academic institutions and pharmaceutical companies, these top companies accelerate the development of new applications and refine existing ones.

In addition to established players, emerging companies are introducing novel SPR platforms tailored to niche applications such as point-of-care testing, environmental monitoring, and food safety. This diversification enhances overall market competitiveness and drives growth.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/surface-plasmon-resonance-spr-systems-market

Segmentation Outlook

The surface plasmon resonance market can be segmented based on technology, application, end-user, and geography. Technological segmentation includes traditional SPR, localized surface plasmon resonance (LSPR), and other emerging variants. Each technology offers unique advantages, catering to different research and industrial needs.

Application-wise, the market serves drug discovery, diagnostics, food safety, environmental monitoring, and academic research, among others. Drug discovery remains a dominant application segment due to the critical role of SPR in analyzing molecular interactions for therapeutic development.

End-user segmentation covers pharmaceutical companies, biotechnology firms, academic and research institutes, and diagnostic laboratories. Pharmaceutical companies constitute a major end-user group, driven by their ongoing need for efficient biomolecular interaction analysis.

Geographically, the segmentation includes North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Each region offers distinct growth drivers and challenges, influencing overall market dynamics.

The segmentation outlook highlights the diversity and broad applicability of surface plasmon resonance technology, which underpins its expanding global market presence.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
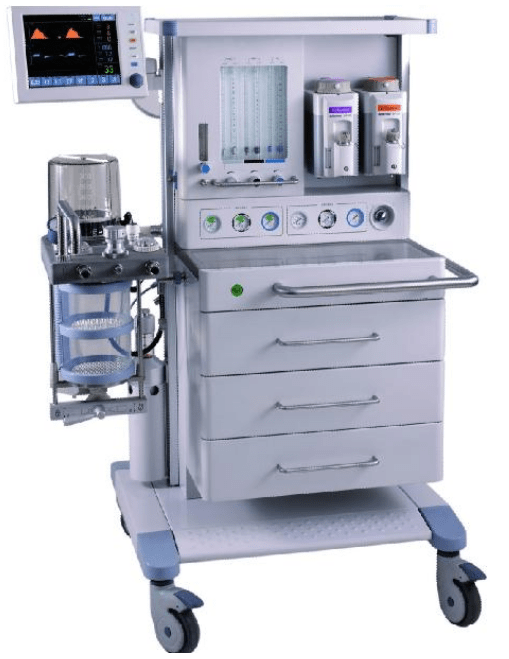
 

Anaesthesia Machines Market Set to Expand at 4.8% CAGR Through 2034

The global sales of anaesthesia machines is estimated to be worth USD 11.1 billion in 2024 and anticipated to reach a value of USD 17.7 billion by 2034. Sales are projected to rise at a CAGR of 4.8% over the forecast period between 2024 and 2034. The revenue generated by anaesthesia machines in 2023 was USD 10,616.4 million.

The anaesthesia machines market plays a crucial role in modern healthcare, providing essential support during surgical procedures by delivering a controlled flow of anaesthetic gases to patients. These machines ensure patient safety and comfort while enabling precise administration of anaesthesia. The demand for anaesthesia machines is driven by the increasing number of surgical procedures worldwide, rising prevalence of chronic diseases requiring surgery, and advancements in medical technology. Hospitals, ambulatory surgical centers, and specialty clinics depend on these machines to enhance operational efficiency and improve patient outcomes. Continuous innovation and integration with digital health technologies are transforming the anaesthesia machines market, making these devices more reliable, user-friendly, and efficient.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-789

Size & Trends

The anaesthesia machines market is witnessing significant growth influenced by various factors. Increasing healthcare infrastructure development, particularly in emerging economies, is a major contributor to market expansion. Furthermore, technological advancements such as the integration of advanced monitoring systems, low-flow anaesthesia techniques, and portable machines are shaping the future of this market. The trend towards minimally invasive surgeries and outpatient procedures also fuels the demand for sophisticated anaesthesia machines that can support diverse clinical settings. Additionally, growing awareness about patient safety and regulatory mandates promoting the use of safer and more effective anaesthesia devices contribute to the expanding market size. Environmental concerns are encouraging manufacturers to develop machines that reduce the release of harmful anaesthetic gases, aligning with sustainability efforts.

Key Highlights

Several key highlights define the anaesthesia machines market landscape. The market is characterized by a shift from conventional mechanical devices to highly automated and digitalized systems that provide enhanced precision and control. User interfaces have become more intuitive, allowing anesthesiologists to monitor vital parameters continuously and adjust anaesthesia delivery in real time. The adoption of wireless connectivity and integration with hospital information systems enables seamless data sharing, aiding clinical decision-making. Market players are focusing on enhancing machine portability and compactness to cater to ambulatory surgical centers and remote healthcare facilities. Furthermore, the growing emphasis on patient safety protocols has resulted in machines equipped with advanced safety alarms and fail-safe mechanisms.

Challenges and Opportunities

Despite promising growth, the anaesthesia machines market faces certain challenges that stakeholders must address. The high cost of advanced anaesthesia machines can limit accessibility, especially in low-resource healthcare settings. Maintenance and calibration of these sophisticated devices require specialized technical expertise, which may not be readily available everywhere. Moreover, the regulatory landscape is stringent, necessitating compliance with rigorous quality and safety standards, which can delay product launches and increase development costs. However, these challenges open doors for opportunities such as the development of cost-effective machines tailored for emerging markets. The rising adoption of artificial intelligence and machine learning in anaesthesia machines offers potential for enhancing predictive maintenance and personalized anaesthesia care. Collaborations between manufacturers and healthcare providers to develop training programs for effective machine use can also improve market penetration.

Key Benefits for Stakeholders

Stakeholders in the anaesthesia machines market, including manufacturers, healthcare providers, and patients, gain multiple benefits from advancements in this field. For manufacturers, innovation and technological integration provide a competitive edge and access to a broader customer base. Healthcare providers benefit from improved surgical outcomes, operational efficiency, and reduced perioperative complications thanks to precise anaesthesia delivery and real-time monitoring features. Patients experience safer procedures, reduced recovery times, and better overall surgical experiences. Additionally, the adoption of eco-friendly anaesthesia machines supports institutional sustainability goals. Training programs and after-sales services offered by manufacturers help healthcare professionals maximize the potential of these machines, ensuring optimal performance and safety.

Market Share by Geographical Region

Geographically, the anaesthesia machines market exhibits variation in growth patterns and market share across regions. Developed regions with well-established healthcare infrastructure dominate the market due to advanced technological adoption and high healthcare spending. These areas have a large installed base of anaesthesia machines and continue to upgrade equipment to the latest standards. Emerging economies are rapidly growing markets, driven by expanding healthcare infrastructure, increasing surgical volumes, and rising government initiatives to improve healthcare access. Regional variations in regulatory environments, reimbursement policies, and availability of skilled healthcare professionals influence market penetration and growth. Additionally, the focus on rural healthcare development in many countries creates demand for portable and user-friendly anaesthesia machines tailored to those settings.

Competitive Outlook

The competitive landscape of the anaesthesia machines market is marked by the presence of several key players who continually innovate to maintain market leadership. These companies invest heavily in research and development to introduce cutting-edge features and enhance machine safety and efficiency. Strategic partnerships, mergers, and acquisitions are common to expand product portfolios and enter new markets. Manufacturers also focus on improving customer service, providing comprehensive training, and offering maintenance solutions to build long-term relationships with healthcare providers. Competition encourages continuous improvement in technology, driving the development of compact, versatile, and more affordable anaesthesia machines. Brand reputation and product reliability remain significant factors influencing buyer decisions in this market.

Top Companies

Leading companies in the anaesthesia machines market have established themselves through innovation, quality, and extensive distribution networks. These organizations offer a wide range of anaesthesia machines, from basic models to highly advanced systems integrated with monitoring and safety features. Their global presence enables them to serve diverse healthcare settings and adapt products to regional needs. These companies actively engage in collaborations with research institutions and healthcare organizations to develop next-generation anaesthesia machines. Continuous investment in product upgrades and customer-centric services contributes to their strong market positions. Their focus on sustainable manufacturing processes and adherence to regulatory standards also strengthens their appeal to environmentally conscious healthcare providers.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/anesthesia-machines-market

Segmentation Outlook

The anaesthesia machines market can be segmented based on product type, technology, application, end user, and geography. Product types range from basic anaesthesia machines to advanced workstations equipped with integrated monitoring systems. Technological segmentation includes mechanical, semi-automatic, and fully automatic machines, reflecting the level of automation and digital integration. Applications cover various surgical specialties such as general surgery, dental surgery, and outpatient procedures, influencing machine specifications and features. End users primarily include hospitals, ambulatory surgical centers, and specialty clinics, each with unique requirements. Geographic segmentation highlights regional market dynamics and helps manufacturers tailor their strategies accordingly. Understanding these segments allows stakeholders to identify growth opportunities and customize offerings to meet evolving market demands.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Molecular Biology Enzymes, Kits & Reagents Market to Grow from USD 25.9 Billion to USD 64.2 Billion by 2035

The Molecular Biology Enzymes, Kits & Reagents Market plays a pivotal role in advancing scientific research and biotechnology development globally. These products form the backbone of molecular biology laboratories, enabling vital processes such as DNA amplification, sequencing, cloning, and gene expression analysis. Enzymes like polymerases, ligases, and nucleases facilitate complex biochemical reactions, while kits and reagents streamline experimental workflows, enhancing accuracy and efficiency. The demand for these molecular tools is driven by their indispensable use in research, diagnostics, and pharmaceutical development. Understanding the dynamics of this market reveals how it is evolving in response to scientific innovations and global health challenges.

The basic research tools of PCR and qPCR as well as NGS and cloning and gene expression analysis allow important studies in both research and diagnostics and biopharmaceutical development. This market will expand at a 9.5% CAGR from USD 25,900.5 million in 2025 to USD 64,187.5 million by 2035.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-6385

Market Trends

Current trends in the Molecular Biology Enzymes, Kits & Reagents Market highlight a strong shift toward the development of highly specialized and user-friendly products. There is an increasing preference for ready-to-use kits that reduce manual errors and save time in experimental setups. Additionally, the adoption of next-generation sequencing (NGS) technologies has fueled demand for enzymes and reagents optimized for high-throughput applications. Automation and miniaturization in molecular biology workflows are also influencing product designs, encouraging suppliers to innovate reagents compatible with advanced robotic platforms. Sustainability and eco-friendly product formulations are emerging trends, as laboratories worldwide seek to reduce environmental impact. Furthermore, the rise of personalized medicine is pushing the market toward customized reagent solutions tailored to specific genetic profiles.

Driving Forces Behind Market Growth

The expansion of the Molecular Biology Enzymes, Kits & Reagents Market is propelled by multiple interrelated factors. Increasing investments in life sciences research by governments and private institutions form a significant driver, providing the necessary funding to explore novel therapeutic avenues and improve diagnostics. The growing prevalence of genetic disorders and infectious diseases has escalated the need for accurate molecular diagnostics, directly boosting demand for these molecular tools. Advances in genomics and proteomics have unlocked new research possibilities, encouraging scientists to rely heavily on molecular enzymes and reagents to decipher complex biological systems. Additionally, the surge in biopharmaceutical production, including gene therapies and vaccines, demands robust molecular biology products to ensure quality and efficiency during manufacturing. Educational institutions adopting modern molecular biology techniques also contribute to the expanding user base.

Challenges and Opportunities

Despite robust growth prospects, the Molecular Biology Enzymes, Kits & Reagents Market faces certain challenges. One significant hurdle is the high cost associated with premium-quality enzymes and specialized kits, which may limit accessibility for smaller research facilities or institutions in developing regions. Intellectual property issues and patent expirations can affect the availability and pricing of specific enzyme formulations, complicating market dynamics. Moreover, the requirement for stringent regulatory approvals can delay the introduction of innovative reagents and kits. However, these challenges open avenues for opportunities. The development of cost-effective alternatives and generic enzymes can attract a broader customer base. Emerging markets with growing biotechnology sectors represent untapped potential for expansion. Additionally, integrating artificial intelligence and machine learning with reagent development promises smarter, more efficient molecular biology solutions. Collaborations between academic institutions and industry players can accelerate product innovation and market penetration.

Recent Industry Developments

The Molecular Biology Enzymes, Kits & Reagents Market has witnessed several noteworthy advancements recently. Companies are investing heavily in research to develop high-fidelity enzymes with enhanced stability and reduced error rates, which are crucial for applications such as PCR and sequencing. Innovations in lyophilized reagents have improved the shelf life and transportability of products, making them more accessible globally. There has also been a surge in multiplex kits that allow simultaneous detection of multiple genetic targets, increasing laboratory throughput. Partnerships between biotech firms and research organizations have led to the creation of tailored reagent kits for emerging fields such as CRISPR gene editing. Moreover, digital platforms for reagent ordering and inventory management have streamlined procurement processes for laboratories, improving operational efficiency. The response to the COVID-19 pandemic accelerated demand for molecular diagnostics reagents, prompting rapid development and approval of related kits.

Regional Analysis

The Molecular Biology Enzymes, Kits & Reagents Market exhibits varied growth patterns across different regions. North America remains a dominant player due to its strong biotech infrastructure, high research funding, and presence of leading molecular biology companies. Europe also maintains significant market share, supported by robust pharmaceutical and academic research sectors. The Asia Pacific region is emerging rapidly, fueled by increased government initiatives, expanding biotechnology education, and growing pharmaceutical manufacturing activities. Countries like China, India, and Japan are becoming key contributors to market growth by establishing advanced molecular biology labs and fostering innovation ecosystems. Latin America and the Middle East & Africa, while currently smaller in market size, show promising potential driven by expanding healthcare infrastructure and growing interest in genomics research. Regional variations in regulatory landscapes and funding availability impact product adoption rates, shaping the market’s global structure.

Competitive Outlook

The competitive environment within the Molecular Biology Enzymes, Kits & Reagents Market is characterized by continuous innovation and strategic collaborations. Companies compete not only on product quality and pricing but also on technological advancements that enhance reagent performance. Providers strive to differentiate themselves through the introduction of novel enzymes, comprehensive reagent kits, and integrated solutions that simplify molecular workflows. Customer service, technical support, and ease of product customization are additional competitive factors influencing buyer decisions. Mergers, acquisitions, and partnerships are common strategies to expand product portfolios and enter new markets. Furthermore, the ability to secure patents and maintain proprietary technologies grants companies a competitive edge by safeguarding unique formulations and methods.

Top Companies

Leading companies in the Molecular Biology Enzymes, Kits & Reagents Market have established strong brand reputations through decades of experience and innovation. These market leaders consistently invest in research and development to enhance their product offerings and meet evolving customer needs. They often maintain global distribution networks ensuring widespread availability of their reagents and kits. Prominent players focus on maintaining quality standards compliant with international regulations and continuously improving manufacturing processes to increase product reliability. Additionally, these companies engage in collaborations with academic institutions and biotech startups to stay at the forefront of molecular biology advancements. Their ability to adapt to emerging market trends and offer comprehensive product portfolios secures their positions at the top of the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/molecular-biology-enzymes-kits-reagents-market

Segmentation Outlook

The segmentation of the Molecular Biology Enzymes, Kits & Reagents Market provides insights into diverse product categories and end-user applications. Products can be categorized based on enzyme type, including polymerases, ligases, nucleases, and other functional enzymes essential for various molecular processes. Kits are segmented by application such as PCR kits, sequencing kits, cloning kits, and gene expression analysis kits. Reagents encompass buffers, nucleotides, primers, and probes. End-users range from academic research labs and pharmaceutical companies to diagnostic centers and biotechnology firms. Each segment exhibits unique growth drivers and challenges. For instance, PCR kits dominate due to their widespread use in diagnostics, while sequencing kits grow rapidly thanks to genomic research trends. Understanding segmentation helps market participants tailor strategies and develop specialized products to meet distinct customer requirements efficiently.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Exosomes Diagnostic and Therapeutic Market Outlook, Demand Drivers, Opportunities, and Forecast 2024 to 2034

Increasing demand for non-invasive biomarkers to catapult growth in the exosome diagnostic and therapeutic market. The market size is expected to increase from USD 88.56 million in 2024 to USD 211.6 million by 2034, at a 9.10% CAGR.

The Exosomes Diagnostic and Therapeutic market has emerged as a promising frontier in modern medicine, driven by the unique capabilities of exosomes in disease detection and treatment. Exosomes are tiny extracellular vesicles secreted by cells that carry molecular information, including proteins, lipids, and genetic material. Their ability to facilitate intercellular communication makes them invaluable both as biomarkers for diagnostic purposes and as carriers for targeted therapies.

In recent years, the growing interest in personalized medicine has accelerated the development of exosome-based diagnostics and therapeutics. These innovative approaches are reshaping how diseases, especially cancer, neurological disorders, and infectious diseases, are diagnosed and managed. The Exosomes Diagnostic and Therapeutic market is witnessing rapid evolution due to advancements in isolation techniques, biomarker discovery, and drug delivery systems. The market encompasses various applications such as early disease detection, monitoring disease progression, and delivering drugs with enhanced precision and fewer side effects.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-6379

As healthcare systems increasingly prioritize non-invasive and accurate diagnostic methods, exosomes offer a revolutionary alternative to traditional biopsy and imaging techniques. Moreover, their natural ability to cross biological barriers and deliver therapeutic molecules positions exosome therapeutics as a potential game-changer in treating chronic and hard-to-treat conditions. The Exosomes Diagnostic and Therapeutic market is poised for significant growth as research efforts continue to uncover new applications and enhance existing technologies.

Market Trends

The Exosomes Diagnostic and Therapeutic market is shaped by several compelling trends that underline its dynamic nature. One of the primary trends is the shift toward liquid biopsy techniques, which allow for minimally invasive collection of body fluids like blood or urine to detect exosomal biomarkers. This trend is transforming cancer diagnosis and monitoring by providing real-time insights into tumor progression and treatment response without the need for invasive procedures.

Another notable trend is the increasing integration of artificial intelligence and machine learning with exosome analysis. Advanced algorithms enable the identification of complex biomarker patterns within exosomes, improving the accuracy and speed of diagnostics. This integration also enhances therapeutic development by predicting exosome behavior and optimizing drug delivery strategies.

Collaborations between academic institutions, biotechnology firms, and pharmaceutical companies are accelerating innovation in the Exosomes Diagnostic and Therapeutic market. These partnerships focus on overcoming technical challenges such as standardizing exosome isolation and characterization methods, which are crucial for regulatory approvals and clinical adoption.

Additionally, there is a growing focus on developing exosome therapeutics for neurological disorders. Since exosomes can cross the blood-brain barrier, they offer a unique delivery system for drugs targeting the brain, opening new possibilities in treating diseases like Alzheimer’s and Parkinson’s.

Challenges and Opportunities

Despite the promising outlook, the Exosomes Diagnostic and Therapeutic market faces several challenges that require strategic attention. One of the key hurdles is the complexity involved in isolating pure and functional exosomes from biological samples. The lack of standardized, cost-effective, and scalable isolation techniques limits the widespread adoption of exosome-based solutions.

Regulatory challenges also pose significant barriers. Since exosome diagnostics and therapeutics represent relatively new medical technologies, regulatory frameworks are still evolving. Navigating these regulations requires robust clinical data demonstrating safety, efficacy, and reproducibility, which can delay market entry.

Furthermore, the heterogeneity of exosomes presents both a challenge and an opportunity. Exosomes vary based on the cell of origin, physiological state, and pathological conditions, making it difficult to develop universal diagnostic markers or therapies. However, this diversity also enables highly specific and personalized medical applications tailored to individual patients, which is a significant growth driver in the Exosomes Diagnostic and Therapeutic market.

On the opportunity front, the expanding scope of exosome research continues to uncover novel therapeutic targets and diagnostic markers. The ability of exosomes to deliver nucleic acids such as RNA and DNA to specific cells presents exciting potential for gene therapy and regenerative medicine. Additionally, the demand for non-invasive diagnostic tools fuels market growth as healthcare providers seek safer and more convenient patient care solutions.

Key Regional Insights

The Exosomes Diagnostic and Therapeutic market exhibits distinct characteristics across different geographic regions. North America leads the market, driven by robust research infrastructure, favorable funding, and a high prevalence of chronic diseases that benefit from advanced diagnostics and therapeutics. The presence of key biotechnology hubs and collaborations between research institutions and industry players further fuel innovation in this region.

Europe follows closely with strong regulatory frameworks and increasing government initiatives to support precision medicine. The region benefits from collaborative research networks and well-established clinical trial ecosystems, facilitating faster translation of exosome technologies from lab to market.

Asia-Pacific is emerging as a significant market due to increasing healthcare expenditure, growing awareness of advanced diagnostic methods, and expanding biotech sectors in countries like China, Japan, and South Korea. The rising burden of cancer and neurodegenerative diseases in this region creates substantial demand for Exosomes Diagnostic and Therapeutic solutions.

Other regions such as Latin America and the Middle East & Africa show growing interest, supported by improving healthcare infrastructure and rising investments in biotechnology. However, market growth in these areas is comparatively slower due to economic and regulatory challenges.

Competitive Outlook

The competitive landscape of the Exosomes Diagnostic and Therapeutic market is characterized by a mix of established pharmaceutical companies, emerging biotech firms, and innovative startups. These players are continuously investing in research and development to expand their product portfolios and improve the efficacy and safety of exosome-based solutions.

Key strategies adopted by companies include strategic collaborations, mergers, and acquisitions aimed at leveraging complementary expertise and accelerating product development. Intellectual property generation through patents is another critical competitive factor, as firms seek to protect their proprietary technologies in exosome isolation, analysis, and therapeutic delivery.

Moreover, companies are focusing on expanding their presence across different regions to capture emerging market opportunities. Innovative product launches that offer enhanced sensitivity, specificity, and user-friendly platforms contribute significantly to gaining a competitive edge.

The competitive outlook also reflects growing interest from contract research organizations and service providers that support exosome research and clinical trials. Their role in facilitating faster development cycles and regulatory compliance enhances the overall ecosystem supporting the Exosomes Diagnostic and Therapeutic market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/exosome-diagnostic-and-therapeutics-market

Top Companies

  • Thermo Fisher Scientific
  • NanoSomix
  • NX Pharmagen
  • Malvern Instruments
  • Capricor Therapeutic
  • Exosome Diagnostics
  • Exiqon A/S
  • System Biosciences
  • Exosome Sciences
  • Aegle Therapeutic
  • AMS Biotechnology
  • Miltenyi Biotec
  • Codiak BioSciences Inc.

Segments:-

By Products for Exosomes Diagnostic and Therapeutic are as follows:

  • Instruments
  • Software
  • Reagents and Kits

The Market is Bifurcated Based on Applications as:

  • Diagnostics
  • Therapeutic

Key End Users of Exosomes Diagnostic and Therapeutic are:

  • Hospitals
  • Cancer Institutes
  • Diagnostic Centers and Others

Different Markets for Exosomes Diagnostic and Therapeutic are:

  • North America
  • Europe
  • Asia Pacific
  • Middle East and Africa
  • Latin America

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Genital Herpes Treatment Market Size, Share, Trends, Growth Analysis & Forecast 2025 to 2035

The global market for Genital Herpes Treatment is forecasted to attain USD 2,334.1 million by 2025, expanding at 4.9% CAGR to reach USD 3,772.1 million by 2035. In 2024, the revenue of Genital Herpes Treatment was around USD 2,234.2 million

The genital herpes treatment market is a crucial segment within the broader healthcare and pharmaceutical industries. Genital herpes, a common sexually transmitted infection caused by the herpes simplex virus (HSV), affects millions worldwide, necessitating ongoing demand for effective treatments. This market focuses on the development, manufacturing, and distribution of therapies aimed at managing symptoms, reducing outbreaks, and improving patients’ quality of life. Treatments typically include antiviral medications, topical creams, and emerging therapeutic approaches. The growing awareness about sexually transmitted infections and advances in medical technology have driven significant attention towards this market, highlighting the importance of innovative treatment options and patient-centric care.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1390

Size & Trends

The size of the genital herpes treatment market is influenced by various factors, including the prevalence of the infection, public health initiatives, and advancements in pharmaceutical research. Increasing rates of genital herpes infections in various regions have contributed to steady market growth. Additionally, trends such as rising awareness campaigns, improved diagnostic facilities, and the introduction of novel antiviral drugs have shaped the market dynamics. The shift towards personalized medicine and the focus on developing treatments with fewer side effects are also notable trends. Moreover, the integration of digital health platforms to enhance patient adherence to treatment regimens has started to influence how therapies are delivered and monitored.

Key Highlights

Several key highlights define the genital herpes treatment market’s landscape. Innovations in drug formulations, such as sustained-release antiviral medications, have improved patient compliance and treatment effectiveness. Research is also exploring vaccine development as a preventive measure, which, if successful, could dramatically alter market prospects. Patient education and support programs have become pivotal in managing the condition’s social stigma and encouraging timely treatment. Additionally, regulatory bodies are emphasizing the safety and efficacy of genital herpes treatments, leading to more rigorous clinical trials and approval processes. These factors collectively contribute to a more dynamic and patient-focused market.

Challenges and Opportunities

The genital herpes treatment market faces several challenges, including the social stigma attached to the disease, which often leads to underreporting and delayed treatment. Resistance to antiviral medications is an emerging concern, prompting the need for continuous research into alternative therapies. Access to treatment in low-resource settings remains limited, affecting overall market penetration. However, these challenges present numerous opportunities for market players. Developing affordable and accessible treatment options could capture unmet needs in emerging economies. Furthermore, advances in biotechnology and drug delivery systems offer potential breakthroughs. The opportunity to create effective vaccines and immunotherapies also represents a promising avenue for long-term disease control.

Key Benefits for Stakeholders

Stakeholders in the genital herpes treatment market benefit in multiple ways. Pharmaceutical companies gain from ongoing demand for innovative and effective therapies, which support revenue growth and brand reputation. Healthcare providers can offer better care options that enhance patient outcomes and satisfaction. Patients benefit from improved quality of life through treatments that reduce the frequency and severity of outbreaks. Additionally, public health systems benefit by potentially lowering the disease burden through preventive and management strategies. Investors and researchers are also positioned to gain from the expanding pipeline of drugs and therapies, fostering innovation and market expansion.

Market Share by Geographical Region

The genital herpes treatment market exhibits significant regional variation. Developed regions typically hold a substantial share due to advanced healthcare infrastructure, higher diagnosis rates, and greater awareness. These areas also see considerable investment in research and development, which fuels market growth. Emerging economies, on the other hand, are witnessing increasing market presence driven by improving healthcare access and rising awareness campaigns. The Asia-Pacific and Latin America regions, in particular, offer considerable growth potential as healthcare services expand and patient education improves. Meanwhile, market players often tailor their strategies to regional needs, considering factors such as economic conditions, cultural perceptions, and regulatory environments.

Competitive Outlook

Competition in the genital herpes treatment market is intense and driven by innovation and strategic collaborations. Companies invest heavily in research to develop new antiviral drugs and delivery methods that enhance efficacy and reduce side effects. Strategic partnerships between pharmaceutical firms and biotechnology companies accelerate the development of novel therapies, including vaccines. Patent expirations for some antiviral drugs have increased generic competition, impacting pricing and market dynamics. Additionally, companies emphasize patient-centric approaches by providing educational resources and support programs, strengthening brand loyalty. As the market evolves, those able to innovate while maintaining affordability and accessibility tend to lead the competitive landscape.

Top Companies

Leading companies in the genital herpes treatment market typically include well-established pharmaceutical giants known for antiviral medication portfolios. These companies invest significantly in clinical research and often have diverse pipelines that address various forms of herpes infections. They benefit from strong distribution networks and regulatory expertise, enabling them to maintain a solid market presence. Alongside big pharma, smaller biotechnology firms are gaining recognition for their innovative approaches, such as immunotherapy and vaccine candidates. These top companies also focus on expanding their geographic reach and engaging in mergers and acquisitions to strengthen their position within the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/genital-herpes-treatment-market

Segmentation Outlook

The genital herpes treatment market is segmented based on treatment type, patient demographics, and end-user categories. Treatment types primarily include antiviral oral medications, topical applications, and emerging biologics or vaccine candidates. Oral antiviral drugs remain the most widely used segment due to their effectiveness in managing outbreaks and reducing transmission risks. Patient demographics segmentation considers factors such as age, gender, and risk groups, as treatment needs and disease prevalence vary across these categories. End-user segmentation involves hospitals, clinics, and retail pharmacies, with increasing interest in telehealth platforms facilitating treatment access. This segmentation helps companies tailor their products and marketing strategies to better meet patient needs and market demands.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
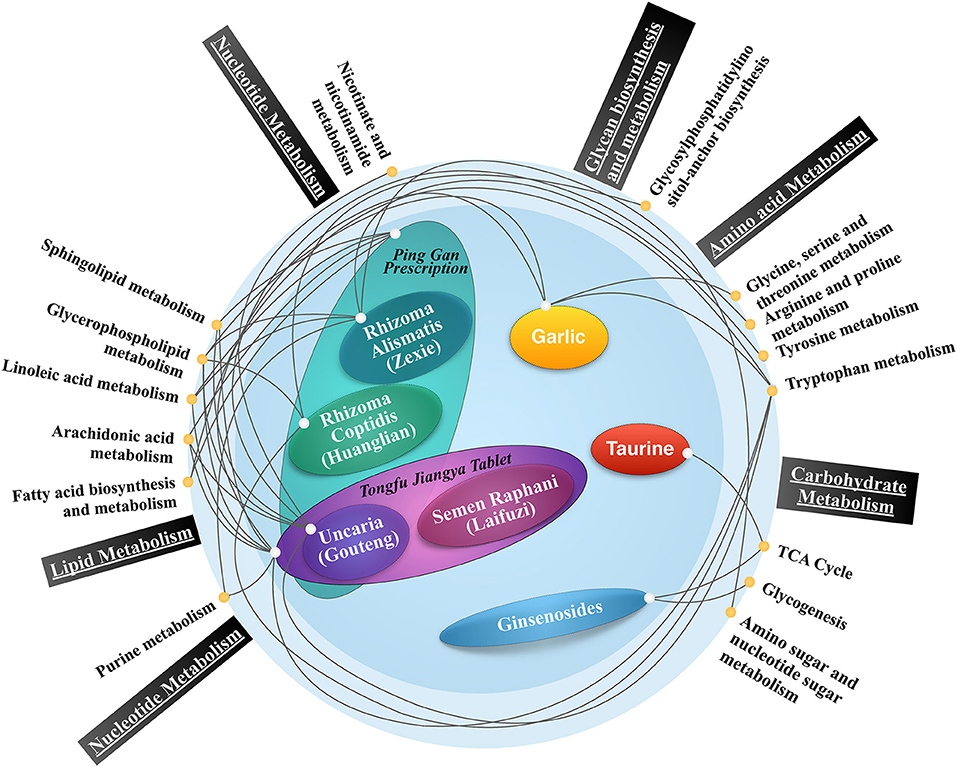
 

Amino Acid Metabolism Disorders Treatment Market Demand, Size & Forecast 2024 to 2034

The Amino Acid Metabolism Disorders Treatment Market is a critical segment within the broader healthcare industry, focusing on therapies and interventions for rare but serious metabolic conditions. These disorders occur due to genetic mutations that disrupt the body’s ability to process amino acids properly, leading to harmful accumulation or deficiency that can affect various organs and systems. Treatment approaches in this market encompass enzyme replacement therapies, dietary management, gene therapies, and pharmacological solutions aimed at restoring normal metabolism or managing symptoms effectively.

As awareness about these rare disorders grows among clinicians and patients, the demand for innovative treatments increases steadily. Advancements in biotechnology and personalized medicine have opened new avenues for addressing amino acid metabolism disorders, making this market a vital area of medical research and commercial interest. The development of targeted therapies that can correct metabolic imbalances at the molecular level is particularly promising, setting the stage for significant market growth.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-6359

 Market Trends

Current trends in the Amino Acid Metabolism Disorders Treatment Market reflect a growing focus on precision medicine. With advancements in genetic screening and diagnostics, early identification of metabolic disorders is becoming more accessible, which in turn drives demand for tailored treatment options. There is a noticeable shift toward non-invasive therapies that offer improved patient compliance and fewer side effects compared to traditional methods.

Another important trend is the integration of digital health technologies and telemedicine to monitor patients remotely, ensuring better management of chronic conditions. Additionally, the rise of patient advocacy groups and rare disease networks plays a crucial role in raising awareness and facilitating access to treatment, thereby influencing market dynamics. Research investment in gene editing and RNA therapies is also reshaping the therapeutic landscape, suggesting a future where more curative treatments could be available.

Driving Forces Behind Market Growth

Several key factors are propelling the growth of the Amino Acid Metabolism Disorders Treatment Market. Foremost among these is the increasing prevalence of diagnosed metabolic disorders due to improved genetic testing capabilities. Early and accurate diagnosis enables timely intervention, which can prevent severe complications and improve quality of life for patients.

The expanding pipeline of novel therapeutics developed through advanced biotechnological techniques is another significant driver. These innovations aim to address unmet medical needs by offering safer, more effective treatment alternatives. Additionally, growing government support and funding for rare disease research help accelerate drug development and market penetration.

Increasing awareness among healthcare professionals and patients about the importance of managing amino acid metabolism disorders also contributes to market expansion. Furthermore, improvements in healthcare infrastructure and reimbursement policies in emerging economies are creating new opportunities for market players to reach previously underserved populations.

Challenges and Opportunities

Despite its potential, the Amino Acid Metabolism Disorders Treatment Market faces several challenges. One of the primary obstacles is the high cost associated with developing and administering specialized therapies. This can limit patient access, especially in low-income regions where healthcare budgets are constrained. Moreover, the rarity and complexity of these disorders complicate clinical trials, often resulting in prolonged development timelines and regulatory hurdles.

Another challenge lies in the need for continuous patient monitoring and adherence to complex treatment regimens, which may affect overall treatment outcomes. However, these challenges also present opportunities for innovation. For instance, companies focusing on affordable therapeutic options and simplified treatment protocols can gain a competitive edge.

Advances in artificial intelligence and machine learning offer promising tools to enhance diagnosis, treatment personalization, and patient management. Collaborative efforts among pharmaceutical companies, research institutions, and patient advocacy groups can drive more efficient drug development and distribution strategies, maximizing market growth potential.

Recent Industry Developments

Recent developments in the Amino Acid Metabolism Disorders Treatment Market highlight significant progress in therapeutic innovation and strategic partnerships. Breakthroughs in gene therapy have resulted in promising clinical trial outcomes, suggesting potential cures for certain metabolic conditions previously deemed untreatable. These therapies target the underlying genetic defects, offering hope for long-term remission.

The market has also seen increased mergers and acquisitions as companies seek to expand their research capabilities and product portfolios. Collaborative research agreements between biotech firms and academic institutions are accelerating the discovery of novel treatment modalities.

In addition, regulatory bodies have introduced expedited review pathways for therapies addressing rare diseases, facilitating faster market entry. Enhanced diagnostic platforms incorporating next-generation sequencing technologies have improved the detection of amino acid metabolism disorders, enabling timely treatment initiation.

Regional Analysis

The Amino Acid Metabolism Disorders Treatment Market exhibits diverse growth patterns across different regions. North America leads in terms of market share, driven by advanced healthcare infrastructure, substantial R&D investment, and high patient awareness. The presence of major pharmaceutical companies and supportive regulatory frameworks further strengthen this region’s position.

Europe also contributes significantly, with well-established healthcare systems and increasing emphasis on rare disease management. Various European countries have implemented national plans for rare diseases, promoting access to innovative treatments.

In the Asia-Pacific region, rapid urbanization, improving healthcare facilities, and growing government initiatives to address rare disorders are fueling market growth. Emerging economies such as China and India are witnessing increased diagnosis rates due to enhanced screening programs, creating new demand for treatments.

Latin America and the Middle East & Africa represent smaller but growing markets, where increased healthcare spending and international collaborations are gradually improving patient access to metabolic disorder therapies.

Competitive Outlook

The Amino Acid Metabolism Disorders Treatment Market is highly competitive, with several leading biopharmaceutical companies and specialized biotech firms striving to develop innovative therapies. Market players focus on expanding their product pipelines through continuous research, partnerships, and acquisitions.

Companies are also investing in improving patient support programs and awareness campaigns to strengthen brand loyalty and market penetration. The competition extends beyond product innovation to include pricing strategies, distribution networks, and collaboration with healthcare providers.

Moreover, smaller firms with novel technologies are entering the market, creating a dynamic environment that fosters rapid advancements and diversified treatment options. This competitive landscape benefits patients by accelerating the availability of more effective and accessible therapies.

Top Companies

Key players dominating the Amino Acid Metabolism Disorders Treatment Market include multinational pharmaceutical giants and specialized biotech companies with expertise in rare diseases. These organizations are actively engaged in developing enzyme replacement therapies, gene therapies, and dietary management solutions tailored to specific metabolic disorders.

Some of the prominent companies are recognized for their robust research and development pipelines, extensive clinical trial activities, and strategic collaborations with academic institutions and patient groups. Their efforts contribute significantly to improving treatment standards and expanding market reach globally.

These companies also prioritize regulatory compliance and aim to navigate complex approval processes efficiently, ensuring timely delivery of new treatments to the market. Their commitment to innovation and patient-centric approaches positions them as leaders in the evolving landscape of amino acid metabolism disorder treatments.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/amino-acid-metabolism-disorders-treatment-market

Segmentation Outlook

The Amino Acid Metabolism Disorders Treatment Market can be segmented based on treatment type, disorder type, end-user, and distribution channel. Treatment modalities include enzyme replacement therapy, gene therapy, dietary supplements, and pharmacological agents. Each segment addresses different aspects of managing amino acid metabolism disorders, offering personalized options to patients.

Disorders covered under this market include phenylketonuria, maple syrup urine disease, homocystinuria, and other less common metabolic conditions. Understanding the specific needs and challenges associated with each disorder helps guide targeted therapy development.

End-users comprise hospitals, specialized clinics, and home care settings, reflecting the diverse care environments where treatment is administered. Distribution channels include hospital pharmacies, retail pharmacies, and direct-to-patient delivery models, ensuring accessibility across regions.

This segmentation helps market stakeholders tailor their strategies, optimize resource allocation, and better meet the demands of various patient groups, ultimately enhancing treatment outcomes and market growth.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
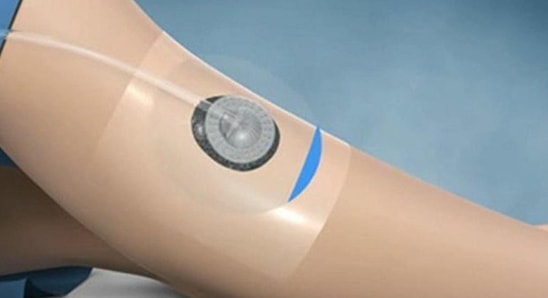
 

Disposable Negative Pressure Wound Therapy Devices Market Analysis, Trends & Forecast 2024 to 2034

The global sales of disposable negative pressure wound therapy devices are estimated to be worth USD 287.5 million in 2024 and are anticipated to reach a value of USD 529.7 million by 2034. Sales are projected to rise at a CAGR of 6.3% over the forecast period between 2024 and 2034. The revenue generated by disposable negative pressure wound therapy devices in 2023 was USD 270.5 million.

The disposable negative pressure wound therapy devices market is an emerging sector within the broader wound care industry. These devices offer a significant advancement in wound management by providing a convenient and cost-effective solution for patients and healthcare providers. Designed to promote faster healing through controlled negative pressure, disposable systems are particularly favored for their ease of use and portability. Unlike traditional negative pressure wound therapy (NPWT) devices, disposable variants are single-use, which minimizes the risk of cross-contamination and reduces maintenance requirements. This aspect makes them increasingly popular in outpatient settings, home care, and situations requiring short-term therapy. The market growth is driven by rising awareness of advanced wound care options, increasing prevalence of chronic wounds, and a focus on reducing healthcare costs and hospital stays.

Disposable negative pressure wound therapy devices have revolutionized the approach to managing wounds such as diabetic ulcers, pressure sores, and traumatic injuries. By providing a sealed environment and removing excess fluid and infectious material, these devices accelerate the healing process and improve patient comfort. The convenience of disposability aligns well with infection control protocols, making these devices an attractive choice for healthcare facilities striving to maintain high hygiene standards. Additionally, advancements in technology have resulted in more compact, lightweight designs that enhance patient mobility and compliance. With healthcare systems increasingly emphasizing outpatient care, these devices fill a critical gap by delivering professional-level wound care outside traditional hospital environments.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-6348

Market Trends

A significant trend shaping the disposable negative pressure wound therapy devices market is the shift toward minimally invasive and user-friendly wound care solutions. Patients and clinicians are seeking devices that are simple to apply and manage without requiring extensive training or frequent maintenance. This has led to innovations focusing on improving the ergonomics and battery life of disposable NPWT units, enabling longer use without replacement. Moreover, the integration of smart sensors and digital connectivity is gaining momentum, allowing for real-time monitoring of wound conditions, which supports better clinical outcomes.

Another important trend is the growing adoption of home-based wound care, driven by the increasing burden on hospitals and the preference for patient-centered care. Disposable negative pressure wound therapy devices, with their single-use design, are ideal for home settings as they reduce the need for device sterilization and complex upkeep. Additionally, the rise in chronic conditions such as diabetes and obesity, which contribute to non-healing wounds, has expanded the target patient population for these devices. The market also reflects a trend toward value-based healthcare, where cost-efficiency and improved patient outcomes are prioritized. Disposable NPWT devices are increasingly recognized for their potential to reduce overall treatment costs by shortening healing times and minimizing hospital readmissions.

Challenges and Opportunities

Despite the promising growth prospects, the disposable negative pressure wound therapy devices market faces several challenges. One notable barrier is the relatively higher upfront cost of disposable devices compared to conventional reusable systems. Although disposability reduces long-term expenses related to maintenance and infection control, budget constraints in some healthcare settings may limit adoption. Additionally, the lack of standardized reimbursement policies for these devices in certain regions hampers widespread utilization.

Another challenge lies in educating healthcare providers and patients about the proper use and benefits of disposable NPWT devices. Misapplication or premature discontinuation of therapy can compromise effectiveness, making training and awareness crucial components for market expansion. Furthermore, regulatory hurdles in obtaining device approvals and ensuring compliance with safety standards can slow down the introduction of innovative products.

However, these challenges open avenues for opportunities. Increasing investments in research and development are expected to yield more affordable and technologically advanced disposable NPWT devices. Companies focusing on user-centric designs and comprehensive training programs can enhance market penetration. Collaborations with healthcare institutions to demonstrate cost-effectiveness and improved patient outcomes may also drive wider acceptance. Additionally, expanding applications of NPWT devices beyond traditional wound types, such as in burns and surgical wounds, present untapped potential for growth.

Key Regional Insights

Regional dynamics play a crucial role in shaping the disposable negative pressure wound therapy devices market. North America remains a dominant region due to its well-established healthcare infrastructure, high incidence of chronic wounds, and early adoption of advanced medical technologies. The presence of key market players and favorable reimbursement frameworks also support the growth in this region. In contrast, Europe exhibits steady growth driven by rising healthcare expenditure and increasing awareness about wound care innovations among clinicians and patients.

The Asia-Pacific region is witnessing rapid expansion, fueled by growing healthcare investments, a large patient pool, and improving access to advanced wound care solutions. Emerging economies in this region are adopting disposable NPWT devices to address the rising burden of diabetic ulcers and other chronic wounds. Latin America and the Middle East & Africa show potential for market growth as healthcare infrastructure improves and disposable medical devices gain preference for infection control.

Each region presents distinct challenges such as varying regulatory environments and differing levels of healthcare access, but these also create opportunities for tailored market strategies. Companies that customize their products and marketing approaches to local needs are better positioned to capture regional growth.

Competitive Outlook

The disposable negative pressure wound therapy devices market is competitive, characterized by both established medical device companies and innovative startups. Key players continuously invest in product development to improve device functionality, patient comfort, and cost-effectiveness. Strategic partnerships, mergers, and acquisitions are common as companies strive to expand their product portfolios and geographic reach.

Competition also drives innovation in materials and battery technologies, contributing to lighter and more durable disposable devices. Furthermore, companies focus on enhancing customer support and education services, helping healthcare providers implement these therapies effectively. The emphasis on sustainability and environmental considerations is emerging as a competitive factor, with some firms exploring biodegradable components for disposable devices.

Ultimately, competitive differentiation often hinges on the ability to offer reliable, easy-to-use devices backed by strong clinical evidence demonstrating faster healing and fewer complications. As demand grows, companies with robust supply chains and comprehensive market access are likely to maintain an advantage.

Top Companies

Leading companies in the disposable negative pressure wound therapy devices market include global medical device manufacturers recognized for their innovation and quality. These companies leverage extensive research and clinical collaborations to introduce advanced disposable NPWT systems that meet diverse patient needs. Their product lines often feature a range of device sizes and pressure settings to cater to different wound types and care environments.

Top companies emphasize building relationships with healthcare providers, offering training programs and technical support to maximize device effectiveness. They also invest in marketing campaigns highlighting the clinical and economic benefits of disposable negative pressure wound therapy. These firms maintain competitive pricing strategies and strive to enhance patient comfort through ergonomic designs and noise reduction.

While large multinational corporations dominate the market, smaller companies and startups contribute by introducing niche products and exploring emerging technologies. The presence of a varied mix of competitors ensures continuous innovation and broad availability of disposable NPWT devices across different regions.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/disposable-negative-pressure-wound-therapy-devices-market

Segmentation Outlook

The disposable negative pressure wound therapy devices market can be segmented based on product type, application, end-user, and distribution channel. Product segmentation typically distinguishes between portable devices designed for outpatient or home use and devices suited for hospital or clinical environments. Each product category addresses specific user requirements in terms of size, battery life, and pressure range.

Applications cover a wide spectrum of wounds, including diabetic foot ulcers, pressure ulcers, traumatic wounds, and post-surgical wounds. The ability of disposable NPWT devices to adapt to various wound types enhances their utility across clinical scenarios. End-users primarily include hospitals, wound care centers, and home healthcare settings. The growth of home healthcare as a segment reflects a broader trend toward patient autonomy and remote management.

Distribution channels involve direct sales to healthcare facilities, partnerships with distributors, and online platforms. Increasing digitalization has facilitated access to disposable negative pressure wound therapy devices, especially in remote or underserved areas. Tailoring distribution strategies to local healthcare systems and patient preferences is essential for market success.

Overall, the segmentation outlook highlights the diverse demand drivers and opportunities within the market, encouraging companies to develop specialized products and targeted approaches to address the evolving needs of healthcare providers and patients.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
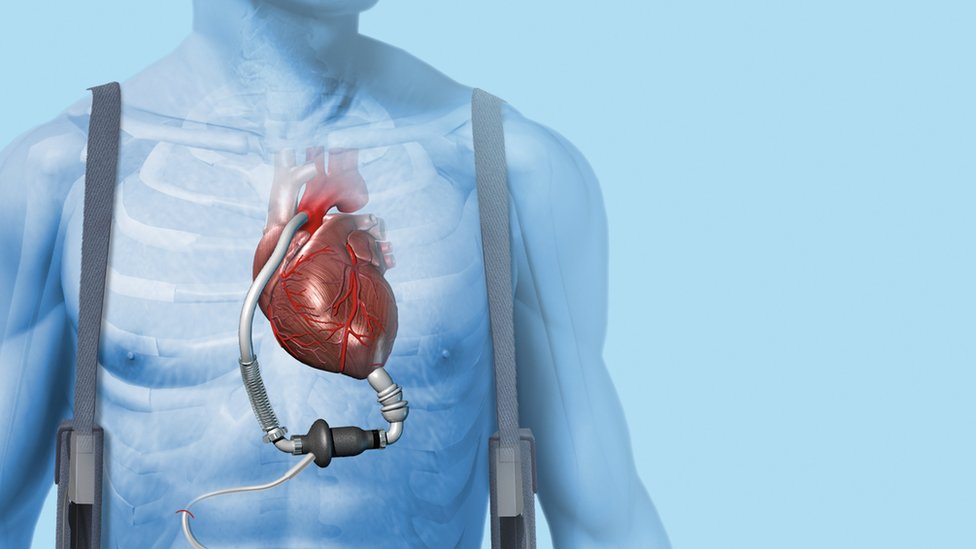
 

Cardiac Assist Devices Market Forecast USD 1.4 Billion in 2025 to USD 2.5 Billion by 2035

The cardiac assist devices market plays a vital role in managing heart-related conditions by providing mechanical support to patients suffering from heart failure or other cardiac dysfunctions. These devices assist the heart in pumping blood effectively, thereby improving patient outcomes and quality of life. With an increasing prevalence of cardiovascular diseases globally, the demand for cardiac assist devices has risen significantly. The technology behind these devices has evolved considerably, incorporating advanced materials, miniaturization, and improved biocompatibility to ensure better patient tolerance and enhanced performance. Cardiac assist devices are crucial not only for bridging patients to heart transplantation but also for long-term therapy and emergency support during acute cardiac events. This market’s growth is fueled by advancements in medical technology, increased awareness of cardiac diseases, and rising healthcare expenditures.

The market is estimated to be worth USD 1.4 Billion in 2025 and is expected to grow to USD 2.5 Billion by 2035, with a CAGR of 5.8% during the forecast period. The global increase in heart failure cases, aging population, and growing awareness about advanced treatment options are contributing to the market expansion.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-467

Size & Trends

The cardiac assist devices market has witnessed steady expansion, supported by the growing patient population and advancements in device technology. Trends in the market reveal a shift toward minimally invasive devices that reduce recovery time and complications. There is a clear movement from traditional external devices to implantable and portable systems that offer patients greater mobility and independence. The development of more efficient, smaller, and longer-lasting cardiac assist devices is reshaping treatment protocols. Additionally, integration with digital health platforms and remote monitoring capabilities is becoming increasingly common, enhancing patient care and enabling timely interventions. Demographic factors such as aging populations in many regions also contribute to the expanding market, as older adults are more susceptible to cardiac conditions requiring assist devices.

Key Highlights

Several key aspects define the cardiac assist devices market. One is the growing acceptance of these devices among clinicians and patients as a reliable alternative to heart transplants or as a bridge therapy. Regulatory approvals of innovative devices have accelerated market growth by increasing the availability of safer and more effective solutions. The market is marked by a strong emphasis on research and development, with companies continuously seeking to improve device performance and patient outcomes. Clinical trials and real-world evidence play a crucial role in validating these devices’ benefits and driving their adoption. Furthermore, collaborations between medical device manufacturers and healthcare providers are instrumental in fostering innovation and facilitating device integration into treatment workflows.

Challenges and Opportunities

Despite the positive growth trajectory, the cardiac assist devices market faces several challenges. High costs associated with device development, implantation, and maintenance can limit accessibility, especially in developing regions. Additionally, the complexity of the devices requires specialized healthcare infrastructure and trained professionals, posing hurdles to widespread adoption. Potential complications such as infection, thrombosis, or device malfunction also require careful management. However, these challenges create opportunities for innovation. There is significant scope for developing cost-effective devices with improved safety profiles and user-friendly designs. Emerging markets offer untapped potential due to rising healthcare investments and increasing prevalence of cardiovascular diseases. Moreover, advancements in materials science, sensor technology, and artificial intelligence can lead to smarter and more adaptive cardiac assist devices, broadening their applications and improving patient care.

Key Benefits for Stakeholders

Stakeholders in the cardiac assist devices market, including manufacturers, healthcare providers, and patients, stand to benefit significantly. For manufacturers, continuous innovation and expanding demand present lucrative business opportunities. Healthcare providers can enhance treatment capabilities and improve patient prognosis by incorporating advanced cardiac assist devices into their care protocols. Patients gain from improved survival rates, enhanced quality of life, and reduced hospital stays thanks to these devices. Furthermore, the ability to monitor patients remotely and adjust device parameters in real time supports better clinical decision-making. Insurance companies and healthcare systems also benefit by potentially reducing long-term healthcare costs through effective management of chronic cardiac conditions.

Market Share by Geographical Region

The cardiac assist devices market displays notable regional variations driven by differences in healthcare infrastructure, economic development, and disease prevalence. Developed regions typically hold a substantial share due to advanced medical facilities, higher healthcare spending, and greater awareness of cardiac assist technologies. These regions benefit from well-established regulatory frameworks that facilitate quicker device approvals and market penetration. Emerging markets, meanwhile, are rapidly growing as investments in healthcare infrastructure increase and cardiovascular disease burden rises. Growth in these regions is supported by increasing government initiatives to improve cardiac care and the introduction of affordable device options. Regional market dynamics also reflect differing patient demographics and treatment practices, contributing to a diverse and evolving global landscape.

Competitive Outlook

The competitive landscape of the cardiac assist devices market is shaped by innovation, strategic partnerships, and regulatory achievements. Companies compete by focusing on product differentiation, such as enhanced device durability, ease of implantation, and integration with digital health platforms. Innovation in battery technology and device miniaturization also serves as a key competitive advantage. Collaborations between device manufacturers and research institutions accelerate the development of next-generation products. Moreover, mergers and acquisitions are common strategies to consolidate market positions and expand product portfolios. Companies that emphasize patient-centric designs and regulatory compliance tend to maintain strong competitive standing. The increasing focus on personalized medicine further encourages competitors to tailor cardiac assist solutions to individual patient needs.

Top Companies

Several leading companies dominate the cardiac assist devices market, leveraging their expertise, resources, and innovative capabilities to shape the industry. These companies invest heavily in research and development to deliver cutting-edge technologies that address unmet clinical needs. Their extensive global presence ensures wide accessibility and strong customer support. They also actively engage with healthcare professionals and patient communities to gather feedback and improve product offerings. These companies often lead in obtaining regulatory approvals and setting industry standards. By focusing on quality, reliability, and continuous improvement, they play a pivotal role in advancing cardiac assist device technology and expanding its reach worldwide.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/cardiac-assist-devices-market

Segmentation Outlook

The cardiac assist devices market is segmented based on device type, application, end user, and geography. Device types include ventricular assist devices (VADs), intra-aortic balloon pumps, and total artificial hearts, among others. Each type serves distinct clinical needs and varies in complexity, implantation method, and duration of use. Applications typically focus on heart failure management, bridge to transplantation, and post-operative cardiac support. End users encompass hospitals, cardiac care centers, and ambulatory surgical centers, reflecting where these devices are most commonly used. Geographic segmentation reveals varied adoption rates and growth patterns influenced by local healthcare systems and economic conditions. Understanding these segments helps stakeholders tailor strategies to meet specific market demands and address the unique challenges and opportunities within each category.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Dry Powder Inhaler Market to Grow at 3.70% CAGR, Reaching USD 29.95 Billion by 2034

The dry powder inhaler market is projected to be worth USD 20.83 billion in 2024. The market is likely to reach USD 29.95 billion by 2034. The Industry is expected to surge at a CAGR of 3.70% from 2024 to 2034.

The dry powder inhaler market has witnessed significant growth over recent years, driven by the increasing prevalence of respiratory diseases and the growing demand for effective drug delivery systems. Dry powder inhalers (DPIs) are devices designed to deliver medication in the form of dry powder directly to the lungs, providing targeted treatment for conditions such as asthma, chronic obstructive pulmonary disease (COPD), and other respiratory ailments. Their popularity stems from advantages such as ease of use, portability, and the ability to deliver medication without the need for propellants, making them environmentally friendly compared to traditional metered-dose inhalers.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-5150

The increasing incidence of respiratory diseases worldwide, coupled with a growing aging population prone to such conditions, has contributed to the expansion of the dry powder inhaler market. Patients and healthcare providers alike prefer DPIs because they offer consistent dosing and reduce the dependency on patient coordination during inhalation, a common challenge with other inhaler types. With advancements in technology, dry powder inhalers are becoming more user-friendly and efficient, further boosting their acceptance among patients.

Market Trends

One of the most prominent trends in the dry powder inhaler market is the shift towards digital and smart inhalers. Integration of sensors and mobile applications allows real-time monitoring of medication adherence and inhalation technique, helping improve patient outcomes. This digital transformation enhances patient engagement and supports healthcare providers in managing chronic respiratory diseases more effectively.

Another notable trend is the focus on developing combination therapies that deliver multiple drugs simultaneously through a single dry powder inhaler. This innovation aims to simplify treatment regimens and improve patient compliance. Moreover, there is a rising preference for environmentally sustainable inhalers due to increased awareness about climate change and the phasing out of inhalers containing hydrofluoroalkane (HFA) propellants.

The growing use of biologics and advanced formulations suitable for dry powder inhalation is also shaping the market landscape. Manufacturers are investing in research to optimize powder characteristics, such as particle size and flowability, to enhance drug deposition in the lungs and improve therapeutic efficiency.

Driving Forces Behind Market Growth

Several factors are driving the growth of the dry powder inhaler market. The rising burden of respiratory diseases globally remains the primary catalyst. Increasing air pollution, smoking rates, and occupational hazards contribute to the surge in asthma and COPD cases, thereby increasing the demand for effective inhalation therapies.

Patient preference for convenient, portable, and non-invasive drug delivery systems also fuels market growth. Dry powder inhalers offer the advantage of being breath-actuated, eliminating the need for coordination between actuation and inhalation, which is particularly beneficial for elderly patients and children. Additionally, the growing awareness about respiratory health and better diagnosis rates have expanded the patient base for DPIs.

Healthcare providers and governments are increasingly focusing on improving disease management strategies, which includes promoting the use of inhalers that enhance adherence and reduce hospitalizations. Furthermore, ongoing innovations in drug formulations and inhaler designs improve treatment efficacy, further encouraging adoption.

Challenges and Opportunities

Despite the promising outlook, the dry powder inhaler market faces challenges. One significant challenge is ensuring consistent and effective drug delivery, as the performance of DPIs depends heavily on the patient’s inhalation technique. Poor technique can lead to suboptimal dosing and reduced therapeutic outcomes. Therefore, patient education and training remain critical.

Another challenge involves the stability of dry powder formulations, which require sophisticated manufacturing processes to maintain drug potency and prevent moisture absorption. Additionally, regulatory hurdles related to device approval and drug-device combination products can delay market entry for new innovations.

Nevertheless, these challenges also present opportunities for growth. Developing user-friendly devices with built-in feedback mechanisms can address adherence and technique issues. The increasing focus on personalized medicine opens avenues for creating tailored inhalation therapies. Emerging markets with rising respiratory disease incidence offer untapped potential for expanding sales and market penetration.

Moreover, partnerships between pharmaceutical companies and technology firms can drive innovation in smart inhalers and connected health solutions, enhancing patient care and market competitiveness.

Recent Industry Developments

Recent developments in the dry powder inhaler market highlight continuous efforts toward improving device technology and drug formulations. Companies are actively investing in research to enhance powder dispersion mechanisms and reduce inhalation resistance, thereby improving drug delivery efficiency.

Several manufacturers have introduced smart inhalers equipped with Bluetooth technology to track usage patterns and provide reminders, supporting better disease management. Collaborations between inhaler developers and digital health companies are accelerating the integration of data analytics and remote monitoring features.

Additionally, regulatory bodies are streamlining approval processes for combination therapies and novel drug-device products, encouraging innovation and faster market access. The push for eco-friendly inhalers has led to the introduction of devices made from recyclable materials, addressing environmental concerns without compromising performance.

Regional Analysis

The dry powder inhaler market exhibits varied dynamics across different regions. Developed regions such as North America and Europe dominate the market due to high healthcare expenditure, advanced medical infrastructure, and greater awareness of respiratory diseases. The presence of major pharmaceutical companies and stringent regulatory frameworks also support the introduction of cutting-edge inhaler technologies in these areas.

Asia-Pacific is emerging as a rapidly growing market, driven by increasing pollution levels, a large patient pool, and improving healthcare accessibility. Countries like China and India are witnessing rising demand for affordable and effective respiratory therapies, prompting manufacturers to expand their footprint. The region also offers cost advantages for manufacturing and clinical trials, attracting investments.

In Latin America and the Middle East & Africa, the market is gradually developing as healthcare systems evolve and diagnosis rates improve. However, challenges such as limited awareness and lower healthcare spending may slow growth in these regions compared to more established markets.

Competitive Outlook

The competitive landscape of the dry powder inhaler market is characterized by innovation-driven companies striving to enhance device performance and patient convenience. Market players focus on strategic partnerships, mergers, and acquisitions to broaden their product portfolios and geographical reach.

Companies are increasingly investing in research and development to create inhalers with improved powder formulations and integrated digital features. This focus on innovation allows them to differentiate their offerings in a crowded market.

Pricing strategies, regulatory compliance, and strong distribution networks are critical for gaining a competitive edge. Additionally, building awareness and educating healthcare professionals and patients about the benefits of dry powder inhalers contribute to market penetration.

Top Companies

Several leading companies dominate the dry powder inhaler market, known for their extensive product lines and continuous innovation. These companies leverage advanced technologies and global reach to maintain their market leadership.

Top companies invest heavily in clinical research and device engineering to stay ahead of evolving customer needs and regulatory requirements. Their strategic collaborations with biotech firms and digital health companies enhance product capabilities and open new market opportunities.

By focusing on patient-centric solutions and sustainability, these companies set industry standards and contribute significantly to the advancement of respiratory drug delivery systems.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/dry-powder-inhaler-market

Segmentation Outlook

The dry powder inhaler market is segmented based on product type, application, end-user, and geography. Product segmentation includes single-dose, multi-dose, and reservoir-type inhalers, each catering to different patient needs and medication requirements. Multi-dose inhalers, for example, offer convenience and cost-effectiveness for chronic therapy.

Application-wise, the market covers respiratory diseases like asthma, COPD, and cystic fibrosis, along with other therapeutic areas that benefit from inhaled drug delivery. Asthma remains a dominant segment due to its high prevalence worldwide.

End-user segmentation includes hospitals, clinics, home care settings, and pharmacies. The home care segment is expanding rapidly as more patients prefer self-management of chronic conditions with easy-to-use devices.

Geographical segmentation reflects market maturity and growth potential, with North America and Europe leading, followed by fast-growing regions such as Asia-Pacific.


About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Neonatal Thermoregulation Market to Grow at 5.2% CAGR, Reaching USD 1.23 Billion by 2035

The neonatal thermoregulation market focuses on the technologies and solutions designed to maintain the optimal body temperature of newborn infants. Thermoregulation is critical for neonates because their ability to regulate body temperature is not fully developed, making them vulnerable to hypothermia or hyperthermia. The market includes devices such as radiant warmers, incubators, and warming mattresses that help stabilize newborns’ temperatures during their crucial early days. As healthcare providers worldwide aim to improve neonatal care outcomes, the neonatal thermoregulation market has gained significant importance. This market caters to hospitals, neonatal intensive care units (NICUs), and maternity centers that prioritize the health and survival rates of infants, particularly premature and low birth weight babies.

The market is projected to grow at a compound annual growth rate (CAGR) of 5.2% from 2025 to 2035, increasing from USD 739.3 Million in 2025 to USD 1227.5 Million by 2035.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-5881

Market Trends

Recent trends in the neonatal thermoregulation market reveal a growing emphasis on integrating advanced technologies to enhance the efficacy and safety of thermoregulation devices. There is a noticeable shift towards non-invasive and automated temperature management systems that offer precise control with minimal manual intervention. Additionally, the demand for portable and energy-efficient devices is increasing, especially in emerging regions where healthcare infrastructure is evolving. Another trend involves incorporating digital monitoring and remote management capabilities to allow healthcare professionals to track neonatal temperature data in real-time. These innovations aim to reduce complications related to temperature instability, improving overall neonatal health outcomes. Sustainability and eco-friendly designs are also emerging trends as manufacturers respond to global environmental concerns.

Driving Forces Behind Market Growth

The neonatal thermoregulation market is propelled by several key factors. The rising incidence of premature births and low birth weight infants globally significantly boosts demand for effective thermoregulation solutions. Advances in neonatal care have increased survival rates for at-risk newborns, but this has concurrently raised the need for sophisticated temperature management to avoid complications. Growing awareness among healthcare professionals and parents about the importance of maintaining proper body temperature for neonates fuels market expansion. Additionally, increasing healthcare expenditures and investments in neonatal care infrastructure worldwide support market growth. Government initiatives to improve maternal and child healthcare services also play a crucial role in expanding the market by promoting better neonatal outcomes and reducing infant mortality rates.

Challenges and Opportunities

Despite the promising growth prospects, the neonatal thermoregulation market faces challenges that need addressing. The high cost of advanced thermoregulation devices may limit accessibility, particularly in low-income regions where healthcare budgets are constrained. Moreover, a lack of trained healthcare personnel capable of operating sophisticated equipment can hinder effective implementation in some areas. Technological complexity and the need for regular maintenance of devices also pose barriers to widespread adoption. However, these challenges create opportunities for innovation, especially for manufacturers developing affordable, easy-to-use, and low-maintenance solutions. Expanding healthcare infrastructure in emerging markets presents significant growth potential. Collaborations between technology providers and healthcare institutions can facilitate knowledge transfer and improve the quality of neonatal care, opening further avenues for market players.

Recent Industry Developments

The neonatal thermoregulation market has witnessed notable advancements and strategic developments recently. Many companies are focusing on research and development to introduce products with enhanced features such as improved temperature stability, energy efficiency, and integration with hospital IT systems. Partnerships and collaborations between manufacturers and healthcare organizations have increased, aiming to pilot new technologies and gather clinical feedback. Some players have launched portable thermoregulation devices catering to homecare settings, enabling parents to manage neonatal temperature effectively outside hospitals. The incorporation of artificial intelligence and machine learning in device design to predict temperature fluctuations and adjust settings automatically marks a significant step forward. Additionally, regulatory approvals and certifications for safer and more reliable devices have increased, boosting market credibility and consumer confidence.

Regional Analysis

The neonatal thermoregulation market exhibits regional variations influenced by healthcare infrastructure, economic conditions, and demographic factors. Developed regions with advanced healthcare systems have a high demand for sophisticated thermoregulation devices, driven by the prevalence of neonatal intensive care units and well-established maternal care programs. These areas also lead in adopting cutting-edge technology and integrating digital health solutions. In contrast, emerging regions are witnessing rapid growth due to improvements in healthcare facilities and increasing awareness of neonatal health. Governments in these regions are investing in healthcare modernization, which includes upgrading neonatal care capabilities. However, challenges such as affordability and lack of trained personnel remain more pronounced here. Regional market dynamics also reflect the availability of local manufacturing and supply chains, which can affect pricing and accessibility.

Competitive Outlook

The neonatal thermoregulation market is moderately competitive, with several established and emerging players vying for market share. Companies compete on factors such as product innovation, quality, pricing, and after-sales services. Brand reputation and global distribution networks also influence competitive positioning. Many market players invest heavily in research and development to differentiate their offerings by adding advanced features like digital monitoring, automated control, and user-friendly interfaces. Strategic collaborations, mergers, and acquisitions are common strategies to expand product portfolios and enter new geographic markets. Additionally, some companies focus on tailored solutions for specific neonatal care settings, such as portable devices for home use or specialized incubators for preterm infants. Overall, innovation and customer-centric approaches are vital for sustaining competitiveness.

Top Companies

Several key companies dominate the neonatal thermoregulation market, known for their technological advancements and extensive product ranges. These market leaders continuously invest in developing innovative solutions that address diverse neonatal care needs globally. Their offerings include radiant warmers, advanced incubators, warming mattresses, and monitoring systems designed to optimize neonatal temperature control. These companies have a strong presence in hospitals and neonatal care centers worldwide, supported by robust sales and service networks. Many of them prioritize sustainability by enhancing energy efficiency and reducing environmental impact in their products. Moreover, leading players actively collaborate with healthcare professionals and institutions to refine device designs based on clinical feedback, ensuring better neonatal outcomes.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/neonatal-thermoregulation-market

Segmentation Outlook

The neonatal thermoregulation market can be segmented based on product type, end-user, and geography. Product segmentation includes radiant warmers, incubators, warming mattresses, and other accessories, each designed to meet specific neonatal temperature management needs. Radiant warmers are preferred for ease of access during medical procedures, while incubators provide controlled environments for prolonged temperature regulation. End-user segmentation focuses on hospitals, neonatal intensive care units, and homecare settings. Hospitals and NICUs remain the primary consumers due to the critical nature of neonatal care provided there. However, the homecare segment is gaining traction with the introduction of portable and user-friendly devices that empower parents to manage neonatal temperature at home. Geographic segmentation reflects variations in market maturity and healthcare infrastructure across regions.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube