Clinical Alarm Management Market Expected to Grow at 5.1% CAGR Through 2035

In the coming years, the clinical alarm management market is expected to reach USD 3,439.2 million by 2025 and is expected to steadily grow at a CAGR of 5.1% to reach USD 5,655.7 million by 2035. In 2024, cluster headache syndrome generated roughly USD 3,286.0 million in revenues.

The clinical alarm management market has gained significant attention due to the increasing reliance on medical devices that generate alarms in healthcare settings. These alarms serve as critical alerts to caregivers, notifying them of potential patient health issues or equipment malfunctions. However, the sheer volume and complexity of these alarms have created challenges around alarm fatigue, which can compromise patient safety.

Clinical alarm management involves the systematic approach of designing, implementing, and optimizing alarm systems within hospitals, clinics, and other healthcare facilities. Effective management helps prioritize critical alarms, reduce false alerts, and ensure timely responses. As patient care becomes increasingly technology-driven, the clinical alarm management market is evolving rapidly to address the needs for improved safety, workflow efficiency, and regulatory compliance.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1713

Market Trends

A prominent trend within the clinical alarm management market is the adoption of intelligent alarm systems that utilize advanced algorithms to filter and prioritize alerts. These systems aim to reduce alarm fatigue by minimizing non-actionable alarms and enabling clinicians to focus on truly urgent situations. The integration of data analytics and machine learning helps customize alarms based on patient conditions, enhancing clinical decision-making.

Another significant trend is the growing use of wireless and wearable technologies that transmit real-time patient data, enabling continuous monitoring beyond traditional bedside devices. This shift is expanding the scope of clinical alarm management to include remote and mobile monitoring environments, which are critical in home care and telehealth settings.

Healthcare providers are also increasingly investing in comprehensive alarm management programs. These programs combine technology upgrades with staff training, policy development, and continuous performance evaluation. The market is witnessing a movement toward more holistic approaches that balance technology with human factors to improve outcomes.

Challenges and Opportunities

Despite advancements, the clinical alarm management market faces notable challenges. One major issue is alarm fatigue, where excessive false alarms desensitize healthcare workers, leading to delayed or missed responses to critical alerts. Balancing sensitivity and specificity in alarm systems remains complex, requiring ongoing refinement.

Additionally, interoperability among medical devices and alarm systems presents challenges. Different manufacturers use varying protocols, making it difficult to integrate alarms into a unified platform. This lack of standardization can hinder data sharing and coordinated responses.

Regulatory compliance adds another layer of complexity. Hospitals must adhere to stringent safety and quality standards related to alarm management, which can vary across regions. Keeping systems updated and compliant requires resources and expertise.

However, these challenges also reveal significant opportunities. There is strong demand for customizable and interoperable solutions that can adapt to specific healthcare environments. Vendors that develop user-friendly platforms facilitating seamless device integration and intelligent alarm filtering are well-positioned to capture market share.

Moreover, the increasing focus on patient safety and quality improvement initiatives drives hospitals to invest in comprehensive alarm management strategies. Education and training programs aimed at reducing alarm fatigue offer opportunities for service providers to partner with healthcare institutions.

Emerging technologies like artificial intelligence and predictive analytics offer promising avenues for innovation. These tools can analyze trends and predict clinical deterioration before alarms sound, moving from reactive to proactive patient care.

Key Regional Insights

The clinical alarm management market varies across regions based on healthcare infrastructure, technology adoption, and regulatory frameworks. Developed regions, with advanced healthcare systems, lead in adopting sophisticated alarm management solutions. Hospitals here prioritize compliance with strict safety standards and leverage cutting-edge technology to enhance patient monitoring.

In contrast, emerging regions are gradually increasing investments in healthcare modernization. Growing awareness of patient safety issues is prompting adoption of alarm management practices, though budget constraints and infrastructure gaps may slow progress. Nonetheless, these markets represent significant growth potential as healthcare facilities upgrade their monitoring capabilities.

Regulatory agencies across different regions are increasingly emphasizing alarm safety. This regulatory focus drives healthcare providers to implement standardized alarm management protocols, fueling market demand. Moreover, regional collaborations and partnerships between technology providers and healthcare institutions help tailor solutions to meet local requirements.

Competitive Outlook

The clinical alarm management market is highly competitive, featuring a mix of established medical device manufacturers and specialized technology providers. Leading companies are focused on innovation, expanding their product portfolios with smart alarm systems and integrated software platforms.

Competition is also based on the ability to deliver end-to-end solutions that cover device integration, alarm customization, staff training, and analytics. Vendors offering comprehensive service packages and strong customer support tend to have a competitive advantage.

Mergers, acquisitions, and strategic partnerships are common strategies used by players to enhance technological capabilities and geographic reach. Collaborations with hospitals and research centers foster innovation and enable the development of tailored solutions.

Emerging startups focusing on artificial intelligence and predictive alarm management technologies are challenging traditional players by introducing disruptive solutions. These newcomers emphasize the use of big data and machine learning to transform alarm management from a reactive to a proactive approach.

Top Companies

Several top companies dominate the clinical alarm management market, each bringing unique strengths to the field. These companies offer a broad spectrum of products, from advanced alarm hardware to sophisticated software solutions for alarm integration and data analytics.

These market leaders invest heavily in research and development to improve alarm accuracy and reduce false positives. Their global distribution networks enable wide adoption of their solutions across diverse healthcare settings.

Customer service and training programs are vital components of their offerings, as effective alarm management requires not only technology but also skilled healthcare personnel. Their commitment to regulatory compliance and sustainability further enhances their reputation and customer trust.

Many of these companies also collaborate with medical institutions and technology partners to develop innovative solutions that address specific clinical challenges. This collaborative approach helps them stay at the forefront of the evolving market landscape.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/clinical-alarm-management-market

Segmentation Outlook

The clinical alarm management market can be segmented based on product type, end-user, and application. Product types include alarm hardware such as monitors and sensors, alarm management software platforms, and integrated systems combining both.

End-users primarily consist of hospitals, ambulatory care centers, long-term care facilities, and home healthcare providers. Each segment has unique requirements; hospitals often demand highly customizable and scalable solutions, while home care settings require portable and easy-to-use devices.

Applications of clinical alarm management span patient monitoring in critical care units, surgical suites, emergency departments, and outpatient clinics. The complexity and criticality of alarms differ across these settings, influencing the choice of alarm management strategies and technologies.

Geographically, segmentation reveals varying adoption rates and market growth dynamics based on healthcare infrastructure, economic factors, and regulatory environments. Understanding these nuances allows companies to tailor their offerings and marketing efforts effectively.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Lab Automation Market Forecasted to Hit USD 6.3 Billion by 2035

The market for laboratory automation is expected to grow significantly from 2025 to 2035, as it will be worth about USD 2.5 billion in 2025, increase to over USD 6.3 billion at a 9.7% annual growth rate by 2035. High-throughput screening, microplate readers, and liquid-handling robots are all being favoured in the marketplace with the drive toward automated, miniaturized labs.

The lab automation market has seen remarkable growth due to the increasing demand for efficiency and accuracy in laboratory processes. Automation in labs encompasses a range of technologies and tools designed to streamline workflows, reduce human error, and enhance productivity. From pharmaceuticals and biotechnology to clinical diagnostics and environmental testing, automation plays a critical role in advancing research and quality control.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-394

Laboratories face growing pressure to deliver faster results with consistent quality, especially in an era where data-driven decisions are paramount. This has driven the adoption of sophisticated automated systems such as robotic arms, automated sample handling, and integrated data management platforms. The lab automation market is evolving rapidly as innovations in artificial intelligence, machine learning, and robotics enable more intelligent and adaptive solutions.

Market Trends

One of the most significant trends shaping the lab automation market is the integration of artificial intelligence and machine learning with traditional automation technologies. These advancements allow labs to perform complex analyses with minimal human intervention, improving accuracy and throughput. Additionally, the push for personalized medicine and genomics research has created a surge in demand for high-throughput screening and sample processing.

Another notable trend is the rise of cloud-based platforms that facilitate real-time data sharing and remote monitoring. Laboratories can now operate more flexibly and collaborate globally, enhancing efficiency and reducing operational costs. The miniaturization of devices and the development of lab-on-a-chip technologies are also redefining how automation can be implemented, making it more accessible to smaller laboratories or point-of-care testing environments.

Sustainability is gaining attention in the lab automation market as well. Manufacturers and laboratories are focusing on reducing waste and energy consumption by designing eco-friendly automated solutions. This focus aligns with broader corporate social responsibility goals and regulatory pressures to minimize the environmental footprint of lab operations.

Challenges and Opportunities

Despite the promising growth, the lab automation market faces certain challenges. High initial investment costs for automation equipment can be a barrier for small and mid-sized laboratories. The complexity of integrating various systems and ensuring compatibility with existing laboratory information management systems requires expertise and careful planning.

Furthermore, skilled workforce availability remains a concern, as technicians and scientists need training to operate and maintain automated systems effectively. Resistance to change and adapting to new technologies within traditional lab environments can slow down adoption rates.

However, these challenges also open numerous opportunities. The demand for affordable, scalable automation solutions is pushing innovation toward modular and customizable systems. These systems can be tailored to specific workflows and budgets, lowering entry barriers. Training programs and user-friendly interfaces are improving the usability of automation tools, encouraging broader adoption.

There is also potential in emerging markets where laboratory infrastructure is expanding rapidly. As healthcare and research activities increase in these regions, the lab automation market stands to benefit from rising demand. Collaborations between technology providers and research institutions can foster innovation tailored to local needs.

Key Regional Insights

The lab automation market exhibits distinct regional characteristics shaped by technological advancements, economic factors, and regulatory landscapes. Developed regions often lead in adopting cutting-edge automation due to established infrastructure and significant research funding. These regions prioritize precision, compliance, and throughput, resulting in sophisticated automation solutions becoming the norm.

Conversely, emerging regions are witnessing growth due to expanding healthcare access and rising investments in scientific research. Governments and private entities are investing heavily in laboratory infrastructure, creating opportunities for lab automation suppliers to introduce cost-effective and adaptable solutions. The ability to customize automation systems to fit diverse laboratory sizes and budgets is crucial in these areas.

Additionally, regional regulations around laboratory safety, data security, and environmental standards influence the lab automation market’s growth trajectory. Companies operating in this market must navigate these regulations carefully to ensure compliance and successful market penetration.

Competitive Outlook

The lab automation market is highly competitive, with a blend of established multinational corporations and innovative startups driving advancements. Industry leaders continually invest in research and development to enhance product portfolios and maintain technological superiority. Their strategies often include forming partnerships, acquisitions, and expanding service offerings to provide comprehensive automation solutions.

Competition extends beyond just product quality. Customer support, integration capabilities, and customization options play significant roles in winning client trust and loyalty. Companies that offer end-to-end solutions—ranging from hardware to software and data analytics—have a competitive advantage.

Innovation remains at the heart of this market’s competitive landscape. Firms that focus on AI-powered automation, modular platforms, and sustainable technologies are better positioned to meet evolving customer demands. Additionally, expanding presence in emerging markets by understanding local requirements gives certain players an edge.

Top Companies

Within the lab automation market, several top companies have established themselves as pioneers and innovators. These organizations boast diverse product portfolios that include robotic systems, liquid handlers, automated analyzers, and software solutions for workflow management.

Many of these companies invest heavily in technology partnerships and collaborations with academic and research institutions. This approach accelerates innovation and helps them stay ahead in a fast-evolving market. Their global distribution networks and comprehensive customer service further solidify their market positions.

Furthermore, leading companies are increasingly emphasizing sustainability and user-centric designs in their product development strategies. This commitment resonates with customers who are mindful of environmental impact and ease of use, broadening their appeal.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/lab-automation-market

Segmentation Outlook

The lab automation market can be segmented by product type, application, end-user, and geography. Product types generally include robotic systems, automated liquid handling systems, centrifuges, microplate readers, and software platforms that manage workflows and data.

Applications span multiple industries such as pharmaceuticals, biotechnology, clinical diagnostics, environmental testing, and academic research. Each application has unique requirements, influencing the types of automation technologies deployed. For instance, pharmaceutical labs may prioritize high-throughput screening and drug discovery automation, while clinical labs focus on diagnostic accuracy and compliance.

End-users include hospitals, research institutions, contract research organizations, and diagnostic labs. Each end-user segment drives demand for specific automation features tailored to their workflows and scale of operations.

Geographically, the market segments reflect varying levels of adoption and growth potential based on regional infrastructure, economic conditions, and regulatory environments. Companies targeting these segments must adapt their strategies to meet diverse needs effectively.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Keloid Treatment Market to Reach USD 5,975.7 Million by 2035

The global market for keloid treatment is forecasted to attain USD 4,135.1 million by 2025, expanding at 3.8% CAGR to reach USD 5,975.7 million by 2035. In 2024, the revenue of this market was around USD 3,996.2 million.

The keloid treatment market is an important segment within the broader dermatology and wound care industry, focusing on solutions to manage and reduce the formation of keloids—raised scars that result from an overgrowth of tissue during the healing process. These scars can cause significant physical discomfort and psychological distress for patients, making effective treatment a critical need. The market encompasses a variety of treatment methods, including surgical procedures, corticosteroid injections, silicone sheets, laser therapy, and emerging innovative therapies such as cryotherapy and pressure therapy. The demand for keloid treatment is growing as awareness of cosmetic and health impacts rises, along with advancements in medical technology that enhance treatment efficacy and patient outcomes.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1313

Size & Trends

The keloid treatment market has been steadily expanding, driven by increasing cases of skin injuries, surgeries, and acne that often lead to keloid scarring. There is a growing preference for minimally invasive treatments, which has accelerated the development and adoption of advanced laser technologies and topical treatments. Additionally, the rise of personalized medicine is influencing the market, as patients and clinicians seek tailored solutions based on genetic and environmental factors that contribute to keloid formation. Public awareness and patient education campaigns are also contributing to market growth by encouraging earlier intervention and ongoing management of scars. Telemedicine and digital health platforms have further facilitated access to specialist consultations and follow-up care, improving treatment adherence.

Key Highlights

Several factors stand out within the keloid treatment market. Firstly, the focus on research and development is intense, with many companies exploring novel biologics and gene therapies to prevent or reverse keloid formation. Secondly, the integration of multidisciplinary approaches combining surgery, pharmacotherapy, and physical therapies is becoming more prevalent, offering better holistic care. Another highlight is the increasing investment in healthcare infrastructure, particularly in regions with high prevalence rates, which is enabling wider accessibility to treatment options. Patient-centric innovations such as painless injection devices and wearable scar management products are also gaining attention. Lastly, regulatory support for new treatment approvals and the growing trend of non-invasive cosmetic procedures contribute significantly to market momentum.

Challenges and Opportunities

The market faces several challenges, with variability in treatment efficacy being a major concern. Keloids are notoriously difficult to treat due to their unpredictable nature and tendency to recur, which can frustrate both patients and healthcare providers. Additionally, the lack of standardized treatment protocols across different regions complicates clinical management. Cost and accessibility of advanced treatments pose barriers, especially in low- and middle-income countries where specialized care may be limited. Despite these hurdles, there are considerable opportunities. Increasing investments in research could lead to breakthrough therapies that offer permanent solutions. There is also potential in expanding treatment awareness campaigns to reduce stigma and encourage early intervention. Digital tools and AI-driven diagnostic systems can enhance treatment personalization and outcome tracking. Collaborations between pharmaceutical companies and healthcare providers may further accelerate product innovation and distribution.

Key Benefits for Stakeholders

Stakeholders across the keloid treatment market stand to benefit in various ways. Patients receive improved quality of life through reduced pain, itching, and psychological distress associated with keloid scars. For healthcare providers, advancements in treatment options allow for more effective management and better patient satisfaction. Pharmaceutical and medical device companies gain from growing demand and the ability to diversify product portfolios. Investors find opportunities in a market with consistent growth driven by unmet medical needs and technological progress. Furthermore, healthcare systems benefit as effective treatments can potentially reduce long-term complications and associated costs. Advocacy groups and policymakers also play a crucial role in promoting equitable access and supporting research initiatives, thus aligning public health goals with market growth.

Market Share by Geographical Region

Geographically, the keloid treatment market shows distinct patterns influenced by demographic and economic factors. Regions with higher skin injury rates and diverse populations tend to report a greater incidence of keloid scarring, driving demand for specialized treatments. Developed regions benefit from advanced healthcare infrastructure and higher awareness, resulting in robust adoption of innovative therapies. Emerging markets are witnessing increasing growth due to rising healthcare expenditure and expanding dermatology services. The market dynamics also reflect cultural attitudes towards scar treatment and cosmetic care, which can vary significantly by region. Additionally, regional regulatory environments impact the availability and approval of new treatments, shaping competitive positioning and patient access.

Competitive Outlook

The competitive landscape of the keloid treatment market is characterized by a mix of established pharmaceutical companies and innovative startups. Companies are focusing on research-driven product development and strategic partnerships to strengthen their market presence. Innovations in drug delivery systems, such as microneedle patches and localized injections, are offering new competitive edges. Additionally, firms are investing in clinical trials to validate the safety and efficacy of novel therapies, which helps build credibility and customer trust. Market competition is also influenced by the ability to provide comprehensive patient support programs and educational initiatives. Pricing strategies and regional expansion efforts further define competitive positioning, as companies strive to capture market share across different geographic areas.

Top Companies

Leading companies in the keloid treatment market include both global pharmaceutical giants and specialized dermatology firms. These organizations invest heavily in research and product innovation, focusing on improving existing therapies and developing new treatment modalities. They typically offer a broad portfolio ranging from corticosteroids and silicone-based products to advanced laser devices and emerging biological therapies. Many of these companies actively engage in collaborations with academic institutions and clinical research organizations to accelerate innovation. Furthermore, they emphasize patient engagement and support through digital platforms, helping to improve treatment adherence and outcomes. Their global reach and established distribution networks enable them to effectively penetrate diverse markets.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/keloid-treatment-market

Segmentation Outlook

The keloid treatment market can be segmented based on treatment type, end-user, and distribution channel. Treatment types include surgical interventions, topical treatments, injectable corticosteroids, laser therapy, and combination therapies. Each segment addresses different patient needs and stages of keloid development. End-users mainly comprise hospitals, dermatology clinics, and outpatient centers, reflecting where most treatments are administered. Distribution channels range from direct sales by manufacturers to pharmacies, online platforms, and healthcare providers. Segmentation by patient demographics and keloid severity is becoming increasingly relevant as personalized medicine gains traction. This multi-faceted segmentation helps companies tailor their offerings and marketing strategies to meet specific market demands effectively.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Neuroendocrine Carcinoma Treatment Market Forecasted to Hit USD 4,305.7 Million by 2034

The global neuroendocrine carcinoma treatment market is likely to generate revenue amounting to USD 1,976 million in 2024. Over the assessment period, the industry is projected to expand at an 8.1% CAGR, reaching an industry size of USD 4,305.7 million by the end of 2034.

The Neuroendocrine Carcinoma Treatment Market focuses on the therapies and solutions designed to treat neuroendocrine carcinoma, a rare and complex form of cancer originating from neuroendocrine cells. These cells have traits of both nerve cells and hormone-producing cells, making the carcinoma unique in its behavior and treatment approach. The market encompasses various treatment modalities, including surgery, chemotherapy, targeted therapy, and emerging immunotherapies. This market’s growth is influenced by advancements in diagnostic technologies and an increasing understanding of neuroendocrine tumor biology. Patients diagnosed with neuroendocrine carcinoma often require personalized treatment plans due to the heterogeneous nature of the disease, making the market diverse and dynamic.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1278

The demand for effective neuroendocrine carcinoma treatment options continues to grow as awareness about the disease improves and healthcare infrastructure evolves globally. Market players are investing in research and development to discover novel therapies that can improve patient outcomes and manage side effects more efficiently. The Neuroendocrine Carcinoma Treatment Market is not only driven by technological innovation but also by the rising prevalence of cancer and improvements in early detection techniques. With rising healthcare expenditure and better access to specialized treatment centers, the market is positioned for steady growth.

Market Trends

The market is witnessing several important trends that are shaping its trajectory. Personalized medicine is gaining prominence, with therapies tailored to the genetic and molecular profile of individual tumors. This approach improves the effectiveness of treatment and reduces adverse effects. Another trend is the increasing integration of advanced diagnostic tools such as molecular imaging and genetic testing, which aid in early detection and accurate classification of neuroendocrine carcinoma.

The adoption of targeted therapies, especially those focusing on specific receptors and signaling pathways involved in tumor growth, is rising. These therapies provide more precise treatment options compared to traditional chemotherapy, often resulting in better patient quality of life. Immunotherapy has also started to emerge as a promising area, offering new hope for patients resistant to conventional treatments.

Collaboration between pharmaceutical companies and research institutes is accelerating innovation. Such partnerships facilitate clinical trials, allowing faster market entry for new drugs and treatment protocols. Additionally, digital health technologies, including telemedicine and patient monitoring systems, are becoming part of the treatment landscape, improving patient adherence and follow-up care.

Driving Forces Behind Market Growth

Several factors drive the Neuroendocrine Carcinoma Treatment Market forward. Firstly, the increasing incidence of neuroendocrine tumors globally, partly due to improved diagnostic capabilities and heightened awareness, contributes to market expansion. Early and accurate diagnosis enables timely treatment, thereby expanding the demand for advanced therapies.

The growing focus on research and development plays a critical role. Pharmaceutical companies are continuously exploring new drug candidates and combination therapies to address treatment-resistant cases. Regulatory support and expedited approvals for orphan drugs related to rare cancers also facilitate market growth.

Advancements in healthcare infrastructure, particularly in emerging economies, are improving access to specialized treatments. As more hospitals and cancer centers become equipped to handle complex neuroendocrine carcinoma cases, patient reach increases. Furthermore, rising healthcare expenditure and insurance coverage for cancer treatment enhance affordability, enabling more patients to seek care.

The increasing patient preference for minimally invasive treatments with fewer side effects propels demand for novel therapeutic options. Additionally, educational campaigns and support groups for cancer patients are raising awareness about treatment possibilities, encouraging early intervention.

Challenges and Opportunities

Despite positive growth factors, the market faces notable challenges. The rarity of neuroendocrine carcinoma presents difficulties in conducting large-scale clinical trials, which slows down the approval of new treatments. Limited awareness among healthcare professionals in some regions can delay diagnosis, affecting treatment success rates.

High treatment costs remain a barrier for many patients, especially in low-income countries, limiting market penetration. The complexity of neuroendocrine tumors, which can behave differently depending on their origin and grade, complicates treatment standardization. Resistance to current therapies and side effects also pose ongoing challenges.

However, these challenges open significant opportunities. There is a clear need for more effective, affordable, and accessible treatment options. Biotech companies focusing on innovative therapies, including gene therapy and immunomodulators, have promising avenues to explore. The development of companion diagnostics to better tailor treatments offers a growth path.

Expanding awareness programs can improve early diagnosis, allowing interventions at stages when treatment is more effective. Emerging markets with improving healthcare infrastructure provide untapped potential. Collaborative efforts between governments, private sector, and research institutions could lead to better patient outcomes and market growth.

Recent Industry Developments

  • The Neuroendocrine Carcinoma Treatment Market has seen several notable developments recently. Advances in targeted therapy drugs that focus on somatostatin receptors, commonly expressed in neuroendocrine tumors, have improved disease management. New formulations with enhanced delivery systems are helping to reduce dosing frequency and improve patient compliance.
  • Clinical trials investigating combinations of immunotherapy with existing treatments have shown encouraging results, broadening therapeutic options. The use of peptide receptor radionuclide therapy (PRRT), a form of targeted radiation, has gained approval in multiple regions, marking a significant milestone in the treatment landscape.
  • Pharmaceutical companies are increasingly investing in biologics and small molecule inhibitors tailored to molecular abnormalities found in neuroendocrine carcinoma. Strategic partnerships and acquisitions within the sector are helping accelerate the availability of innovative therapies.
  • The integration of artificial intelligence in diagnostics and treatment planning is another recent advancement, allowing more precise and personalized treatment regimens. Regulatory bodies have also become more receptive to fast-tracking drugs addressing rare cancers, shortening time to market.

Regional Analysis

The market exhibits regional variations based on healthcare infrastructure, regulatory environment, and prevalence of neuroendocrine carcinoma. North America leads in market size due to robust healthcare systems, high research funding, and early adoption of advanced therapies. The United States, in particular, has numerous specialized cancer centers and active clinical trial programs.

Europe follows closely with significant investment in cancer research and well-established treatment protocols. Countries like Germany, France, and the United Kingdom have a strong presence of pharmaceutical companies focused on neuroendocrine carcinoma treatment. Increasing collaboration between European nations helps standardize care and accelerate innovation.

Asia-Pacific is an emerging market with rising healthcare awareness and expanding infrastructure. Countries like China, Japan, and India are witnessing improved access to diagnostic tools and treatments. However, disparities in healthcare access and affordability remain a challenge in some parts of the region.

Latin America and the Middle East & Africa regions are gradually developing their capabilities with increased government support and private sector involvement. These regions represent future growth opportunities as awareness improves and healthcare systems evolve.

Competitive Outlook

The Neuroendocrine Carcinoma Treatment Market is moderately fragmented with a mix of large pharmaceutical companies and smaller biotech firms. Competition revolves around innovation, clinical trial success, and regulatory approvals. Market players focus on developing therapies that offer better efficacy and safety profiles compared to existing options.

R&D intensity is high, with companies investing in both new drug development and improving existing treatment regimens. Marketing strategies emphasize collaborations with healthcare providers and patient advocacy groups to enhance treatment adoption. Intellectual property protection and patent portfolios are crucial competitive factors.

Strategic alliances between companies and academic institutions help accelerate drug discovery and clinical testing. Companies with broad treatment portfolios that cover various cancer types tend to have an advantage in resource allocation and market reach. Pricing strategies also influence competitive positioning, especially as healthcare payers demand cost-effective solutions.

Top Companies

Several key players dominate the Neuroendocrine Carcinoma Treatment Market by virtue of their innovative drug pipelines and established market presence. These companies lead in research, clinical trials, and bringing new therapies to patients worldwide. Their extensive global distribution networks allow them to reach diverse patient populations.

The top companies actively engage in collaborations and licensing agreements to broaden their neuroendocrine carcinoma treatment portfolios. They focus on both targeted therapies and emerging immunotherapies, aiming to capture multiple segments of the market. Strong investment in scientific research supports their ability to introduce next-generation treatments.

These companies also play an important role in educational initiatives and patient support programs, improving treatment adherence and outcomes. By maintaining robust manufacturing capabilities and regulatory compliance, they ensure consistent product availability.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/neuroendocrine-carcinoma-market

Segmentation Outlook

The Neuroendocrine Carcinoma Treatment Market can be segmented based on treatment type, tumor location, and end user. Treatment types include surgery, chemotherapy, targeted therapy, immunotherapy, and peptide receptor radionuclide therapy. Each segment addresses different patient needs and disease stages.

Tumor location segmentation considers whether the carcinoma arises in the pancreas, lungs, gastrointestinal tract, or other sites. This classification is vital since treatment protocols vary depending on tumor origin and grade. End users include hospitals, specialty cancer centers, and outpatient clinics where treatments are administered.

Geographically, the market segments into regions such as North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa, reflecting diverse healthcare dynamics. This segmentation helps companies tailor strategies and allocate resources efficiently.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Endoscope Reprocessing Device Market Forecasted to Hit USD 4.94 Billion by 2035

The endoscope reprocessing device market is estimated to reach USD 2.68 billion in 2025. It is anticipated to grow at a CAGR of 7.3% during the assessment period and reach a value of USD 4.94 billion by 2035.

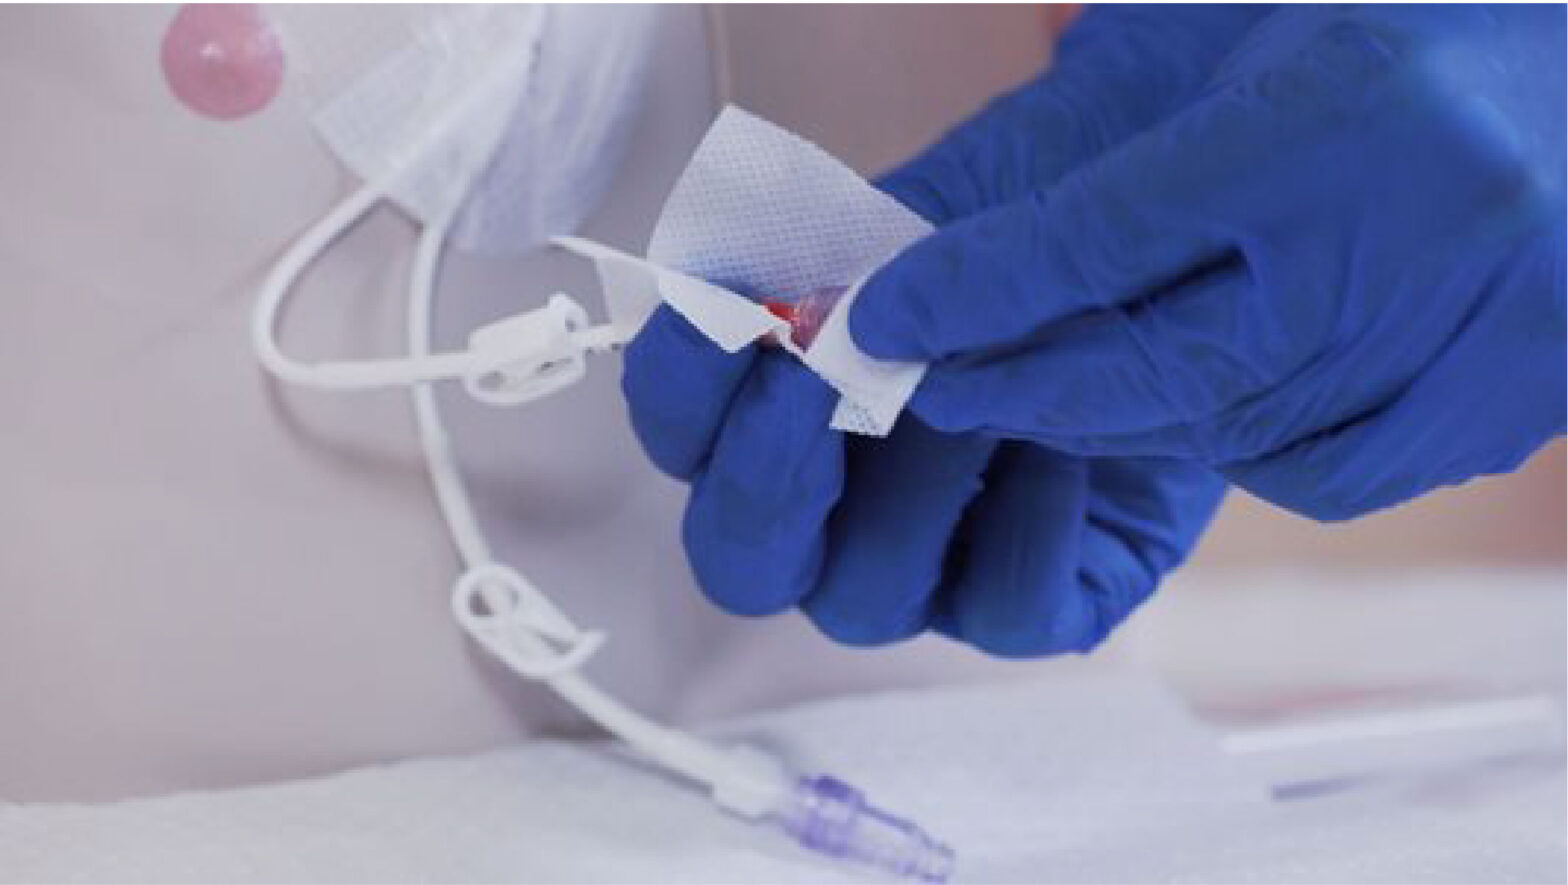
The endoscope reprocessing device market is a critical component of the healthcare industry, playing a central role in infection control and patient safety. As endoscopic procedures become more widespread in diagnosing and treating various medical conditions, the importance of ensuring that these instruments are adequately reprocessed has grown exponentially. Endoscope reprocessing devices are specialized systems that clean, disinfect, and sterilize endoscopes, which are otherwise vulnerable to contamination due to their complex design and reuse nature.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-2058

Hospitals, clinics, and ambulatory surgical centers depend heavily on these devices to maintain high standards of hygiene. Regulatory authorities and healthcare organizations worldwide have implemented stringent guidelines to prevent cross-contamination, further driving the adoption of endoscope reprocessing devices. Technological advancements, such as the integration of automation and digital monitoring, have significantly enhanced the reliability and efficiency of these systems. As the demand for minimally invasive surgeries continues to rise, so too does the necessity for robust and dependable endoscope reprocessing solutions.

Market Trends

Several prevailing trends are shaping the trajectory of the endoscope reprocessing device market. Automation and digitization are at the forefront of these developments, with newer systems incorporating real-time monitoring features and data logging capabilities to ensure thorough documentation of the reprocessing cycle. This digital evolution not only improves compliance with healthcare standards but also minimizes the risk of human error.

Another prominent trend is the increasing preference for single-use endoscopes in certain high-risk scenarios. While reusable endoscopes remain prevalent due to cost-efficiency, the growing concern over healthcare-associated infections (HAIs) has prompted healthcare providers to explore alternatives. Additionally, the market is witnessing a rise in demand for eco-friendly and sustainable reprocessing solutions, driven by global initiatives to reduce environmental footprints.

Geographic expansion by leading manufacturers is another significant trend. Companies are targeting emerging markets where the healthcare infrastructure is improving and awareness regarding infection control is increasing. As hospitals in developing nations modernize their operations, the uptake of advanced endoscope reprocessing devices is set to climb, creating new avenues for growth.

Challenges and Opportunities

Despite the promising outlook, the endoscope reprocessing device market faces several challenges. One of the most pressing concerns is the high initial cost of acquiring and installing these systems, which can be a significant burden for smaller healthcare facilities and those in resource-constrained regions. Additionally, the complexity of the reprocessing procedure demands skilled personnel and continuous training, which may not always be readily available.

Another challenge is maintaining consistency in reprocessing outcomes. Variations in procedure adherence can result in subpar sterilization, increasing the risk of infections. Addressing these inconsistencies requires robust training programs and better workflow integration. Moreover, evolving regulatory landscapes across different countries can create compliance difficulties for manufacturers aiming to operate globally.

On the other hand, these challenges present opportunities for innovation and service development. There is significant potential for developing cost-effective, user-friendly, and compact reprocessing units suited for smaller facilities. Investment in training services, remote support systems, and AI-based monitoring can further enhance compliance and effectiveness. Additionally, collaborations between manufacturers and healthcare providers can foster the creation of tailored solutions that meet specific operational needs.

Key Regional Insights

The endoscope reprocessing device market exhibits varied dynamics across different regions. North America remains a dominant force due to its advanced healthcare infrastructure, high procedural volume, and strict regulatory standards. The United States, in particular, is a key market owing to its focus on patient safety and infection control protocols.

Europe follows closely, driven by similar healthcare priorities and well-established medical facilities. Countries like Germany, France, and the United Kingdom are notable contributors to market demand, especially with their increasing investments in healthcare technologies.

The Asia-Pacific region is emerging as a lucrative market, fueled by expanding healthcare systems in countries such as China, India, and Japan. Rapid urbanization, increasing healthcare expenditure, and a growing population have contributed to the rising need for efficient endoscopic procedures and their associated reprocessing solutions. Latin America and the Middle East & Africa are gradually catching up, supported by government initiatives and international collaborations aimed at improving medical infrastructure.

Competitive Outlook

The competitive landscape of the endoscope reprocessing device market is characterized by the presence of both global and regional players vying for market share. These companies are focused on innovation, partnerships, and expansion strategies to strengthen their positions. Continuous product development is a central theme, with manufacturers emphasizing the creation of automated systems that reduce manual handling and improve safety.

Mergers and acquisitions are also common in this sector, as larger firms aim to broaden their product portfolios and tap into new geographic regions. Furthermore, companies are investing in research and development to introduce more sophisticated features such as RFID tracking, AI-based diagnostic alerts, and cloud-based compliance reporting.

Another area of competition lies in after-sales service and customer support. As endoscope reprocessing systems require regular maintenance and updates, the ability to provide comprehensive service packages has become a distinguishing factor for many market leaders. Additionally, companies are competing to offer training and certification programs that ensure their clients use the equipment correctly and efficiently.

Top Companies

Several key players dominate the endoscope reprocessing device market, contributing to its dynamic growth. These include renowned healthcare equipment manufacturers known for their extensive experience and technological innovation. Their global presence, strong distribution networks, and commitment to research and development have enabled them to maintain a competitive edge.

These top companies often focus on introducing next-generation products that incorporate user-centric designs, automation, and smart connectivity features. Through strategic collaborations with healthcare providers, they tailor their solutions to meet real-world clinical needs. As awareness of infection prevention continues to grow, these leading firms are well-positioned to drive the market forward with cutting-edge innovations and enhanced service offerings.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/endoscope-reprocessing-device-market

Segmentation Outlook

The endoscope reprocessing device market can be segmented based on product type, end-user, and geographical region. Product types typically include automated endoscope reprocessors, washer disinfectors, drying cabinets, and other associated accessories. Among these, automated systems are gaining popularity due to their ability to standardize processes and minimize errors.

In terms of end-users, hospitals remain the primary segment owing to their high patient throughput and diverse surgical departments. Ambulatory surgical centers and specialty clinics also represent significant demand, especially as outpatient procedures become more common. Each of these segments has distinct requirements, which influence purchasing decisions and product design.

Geographically, the market segments align with the regional insights mentioned earlier, reflecting the maturity of healthcare systems and regulatory enforcement in each region. These segmentation categories allow manufacturers to target specific needs and refine their marketing strategies accordingly, ensuring their products align with customer expectations.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Vascular Access Catheters Market Expanding Rapidly to USD 6.17 Billion by 2035

The global sales of vascular access catheters are estimated to be worth USD 3.54 billion in 2025 and anticipated to reach a value of USD 6.17 billion by 2035. Sales are projected to rise at a CAGR of 5.7% over the forecast period between 2025 and 2035. The revenue generated by vascular access catheters in 2024 was USD 3.35 billion.

The vascular access catheters market is an essential segment of the global healthcare industry, providing a crucial solution for administering medications, fluids, blood products, and for hemodialysis and parenteral nutrition. These catheters are designed to be inserted into the veins and remain in place for a specified period, offering both short-term and long-term treatment solutions. The increased prevalence of chronic illnesses, such as cancer, kidney disorders, and infectious diseases, has significantly driven the demand for vascular access devices across various medical settings. Hospitals, clinics, ambulatory surgical centers, and homecare facilities are among the primary users of these devices, ensuring consistent medical support for patients who require repeated vascular access.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-5327

Size & Trends

The vascular access catheters market has experienced steady expansion, influenced by technological advancements, increasing hospital admissions, and the rise of minimally invasive procedures. As medical technology evolves, catheter design and materials have improved to enhance patient comfort, reduce infection risk, and prolong catheter life. A shift towards home-based care and outpatient services has also played a role in market growth, with peripherally inserted central catheters and tunneled catheters becoming increasingly popular for long-term treatment.

Another notable trend is the growing preference for antimicrobial-coated and heparin-coated catheters. These innovations are intended to reduce catheter-related bloodstream infections, a significant concern in the healthcare environment. Furthermore, rising investments in healthcare infrastructure and expanding awareness among medical professionals and patients contribute to the increasing demand for vascular access solutions worldwide.

Key Highlights

One of the most prominent highlights in the vascular access catheters market is the continuous development of materials that enhance catheter durability and compatibility with the human body. Manufacturers are actively investing in research and development to create catheters that can withstand prolonged use without causing adverse reactions. Bio-compatible materials, flexible tubing, and enhanced locking mechanisms are some of the innovations that have emerged to improve the patient experience and clinical outcomes.

The integration of imaging technologies, such as ultrasound and fluoroscopy, in the placement of vascular access catheters has also proven to be a game-changer. These tools improve placement accuracy, reduce complications, and enhance procedural efficiency. Moreover, the adoption of value-based healthcare models in developed regions is encouraging the use of cost-effective yet high-performance vascular access devices.

Challenges and Opportunities

Despite its growth, the vascular access catheters market faces several challenges. One of the most pressing concerns is the risk of catheter-related infections, which can lead to severe complications and increased healthcare costs. Managing these infections requires strict adherence to sterile techniques and post-insertion care, which can be a hurdle in resource-limited settings. Additionally, the high cost of advanced catheter systems and lack of trained professionals in certain regions can slow down adoption rates.

On the opportunity front, emerging economies offer significant potential for market expansion. Rising healthcare investments, supportive government initiatives, and a growing burden of chronic diseases in regions such as Asia-Pacific and Latin America are opening new doors for industry players. The shift towards homecare and remote patient monitoring also presents an avenue for companies to introduce portable, user-friendly vascular access solutions tailored to non-clinical environments.

Key Benefits for Stakeholders

The vascular access catheters market provides numerous benefits to stakeholders, including healthcare providers, patients, and manufacturers. For healthcare providers, these devices facilitate efficient and timely treatment administration, enabling better clinical outcomes and reduced hospital stays. Patients benefit from reduced discomfort and fewer needle sticks, particularly with long-term treatment regimens.

Manufacturers, on the other hand, benefit from a growing customer base and an expanding range of application areas. Innovations in catheter technology allow companies to differentiate their offerings and gain competitive advantages. Distributors and suppliers also play a critical role in ensuring timely availability of products across various healthcare facilities, contributing to improved patient care.

Market Share by Geographical Region

Geographically, the vascular access catheters market is segmented into North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America holds a significant share of the global market, driven by a high prevalence of chronic diseases, advanced healthcare infrastructure, and widespread adoption of innovative medical technologies. The presence of leading industry players and well-established reimbursement policies further boost market growth in the region.

Europe follows closely, with countries such as Germany, France, and the UK contributing significantly due to high healthcare expenditure and a focus on patient safety. Meanwhile, the Asia-Pacific region is anticipated to experience the fastest growth due to rapid urbanization, improving healthcare facilities, and increasing awareness of advanced treatment options. Countries like China and India are emerging as key markets, driven by large patient populations and growing government focus on healthcare modernization.

Competitive Outlook

The vascular access catheters market is characterized by intense competition among established and emerging players. The competitive landscape is shaped by a combination of innovation, strategic partnerships, mergers and acquisitions, and geographic expansion. Companies are investing heavily in R&D to enhance product offerings and comply with evolving regulatory standards.

Key strategies employed by market leaders include the development of antimicrobial and anti-thrombogenic catheters, as well as advanced delivery systems that minimize patient discomfort and improve insertion accuracy. Furthermore, strategic alliances with healthcare institutions and research organizations enable companies to stay ahead of market demands and refine their solutions based on real-world usage data.

Top Companies

Several leading companies dominate the vascular access catheters market by offering a broad portfolio of products and maintaining a strong global presence. These include established medical device manufacturers known for their commitment to quality and innovation. Their products span across various catheter types such as central venous catheters, peripherally inserted central catheters, and dialysis catheters.

These top companies continuously invest in improving product performance, ensuring regulatory compliance, and expanding their market reach through strategic distribution channels. Additionally, they engage in training programs for medical professionals to promote safe and effective catheter use. Through these efforts, they maintain a stronghold in the competitive landscape while also fostering trust among healthcare providers and patients.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/vascular-access-catheters-market

Segmentation Outlook

The vascular access catheters market can be segmented based on product type, application, end-user, and geography. Product-wise, the market includes central venous catheters, peripheral catheters, and dialysis catheters. Among these, central venous catheters are widely used due to their versatility and ability to deliver treatments over extended periods.

In terms of application, these catheters are commonly used for drug administration, fluid and nutrition management, blood sampling, and dialysis. Hospitals account for the largest end-user segment, followed by clinics and ambulatory surgical centers. The growing adoption of homecare services also highlights the need for user-friendly and reliable catheter options suited for non-clinical settings.

Geographically, as mentioned earlier, regions such as North America and Europe hold a substantial share, but the Asia-Pacific region is emerging as a vital area of growth. The combined impact of healthcare modernization, increasing disease prevalence, and favorable regulatory frameworks make these regions attractive for future investments and market penetration.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Hip and Knee Reconstructive Market Expected to Grow at 5.6% CAGR Through 2035

The global sales of hip and knee reconstruction is estimated to be worth USD 23,880.2 million in 2025 and is anticipated to reach a market of USD 41,071.4 million by 2035. Sales are projected to rise at a CAGR of 5.6% over the forecast period between 2025 and 2035. The revenue generated by hip and knee reconstructive in 2024 was USD 22,777.0 million.

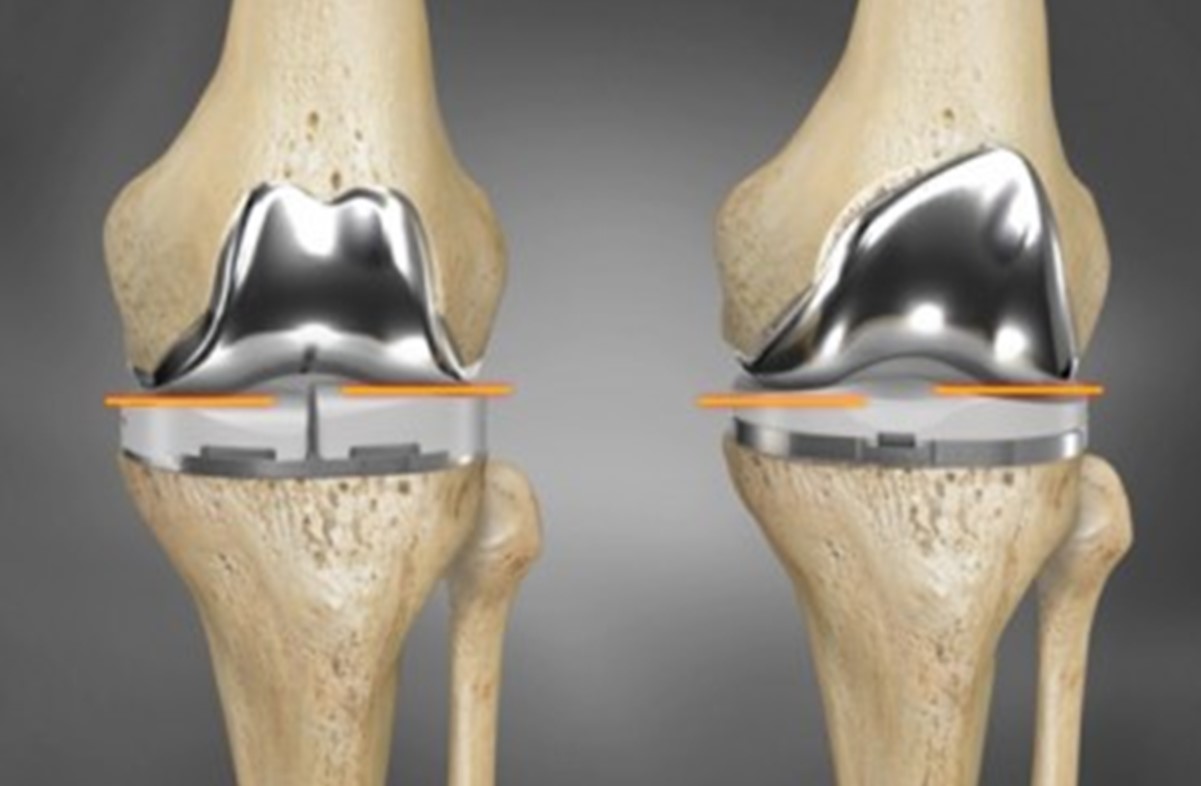
The hips & knees reconstructive market is witnessing transformative changes in recent years, driven by the rising prevalence of joint-related disorders and increased demand for mobility solutions. With an aging population and increasing awareness about advanced surgical options, this market has grown significantly, especially in developed economies. These reconstructive procedures are crucial for restoring joint functionality and enhancing patients’ quality of life, particularly those affected by osteoarthritis, rheumatoid arthritis, or traumatic injuries. The market encompasses various implants, prosthetics, surgical instruments, and navigation systems, all aimed at improving surgical outcomes and patient satisfaction.

The growth of the hips & knees reconstructive market is also propelled by technological advancements that offer better longevity of implants and minimally invasive surgery techniques. Furthermore, improvements in materials used for prosthetic joints, such as titanium and ceramics, are enhancing durability and compatibility with the human body, contributing to positive patient outcomes.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-2717

Market Trends

Several prevailing trends are shaping the trajectory of the hips & knees reconstructive market. One of the most prominent is the surge in demand for minimally invasive surgical procedures. These techniques result in reduced hospital stays, lower postoperative pain, and quicker recovery times, making them attractive for both patients and healthcare providers.

Another emerging trend is the integration of robotic-assisted surgical systems. Robotics improves the precision and accuracy of joint replacement surgeries, reducing the margin for human error. Additionally, 3D printing technology is making inroads by enabling the creation of customized implants tailored to an individual’s anatomy. This personalization increases the effectiveness of reconstructive surgeries and enhances patient satisfaction.

Furthermore, there is a growing inclination towards outpatient or same-day discharge surgeries, facilitated by better perioperative care and advanced anesthesia protocols. These procedures lower the total cost of care, which is becoming increasingly important in healthcare systems focused on cost-efficiency.

Driving Forces Behind Market Growth

A primary driver of the hips & knees reconstructive market is the rapidly aging global population. Older adults are more susceptible to degenerative joint diseases, making them key candidates for reconstructive surgeries. This demographic shift alone is a major catalyst for market expansion.

Another significant factor is the rising prevalence of lifestyle-related conditions such as obesity and diabetes, which contribute to joint deterioration and increase the need for hip and knee surgeries. Coupled with growing awareness about treatment options and improved access to healthcare in emerging markets, this has fueled the demand for reconstructive procedures.

Technological innovation also plays a crucial role. Innovations such as computer-aided design (CAD), augmented reality (AR), and artificial intelligence (AI) are enhancing surgical planning and execution. These technologies not only improve surgical accuracy but also support better patient education and engagement, leading to improved surgical outcomes.

Challenges and Opportunities

Despite its robust growth, the hips & knees reconstructive market faces several challenges. High costs associated with joint replacement surgeries can be a deterrent, particularly in low- and middle-income countries where health insurance coverage may be limited. The expensive nature of implants and surgical equipment further adds to the financial burden on both patients and healthcare systems.

In addition, the risks associated with surgery, including infection, implant failure, or revision surgery, may limit the adoption rate among patients who are reluctant to undergo invasive procedures. Also, regulatory hurdles and the time required for product approvals can slow down the introduction of new and innovative solutions in the market.

Nevertheless, opportunities abound. The expansion of healthcare infrastructure in developing countries, coupled with increased government initiatives aimed at improving orthopedic care, offers fertile ground for market growth. Education campaigns that emphasize early diagnosis and intervention can also play a pivotal role in driving adoption.

Recent Industry Developments

  • The hips & knees reconstructive market is experiencing a wave of innovation, with key players introducing advanced solutions to improve patient care. Recent developments include next-generation implants that mimic natural joint movement more accurately, providing better post-operative mobility.
  • Companies are also focusing on launching smart implants embedded with sensors that provide real-time data on joint performance, patient activity, and implant longevity. These smart implants help healthcare providers monitor recovery and anticipate potential issues before they escalate.
  • Additionally, partnerships and mergers among companies are reshaping the competitive landscape. Collaborations between med-tech companies and healthcare providers aim to streamline surgical workflows and enhance patient outcomes through integrated care solutions.

Regional Analysis

North America holds a significant share of the hips & knees reconstructive market, largely due to its advanced healthcare infrastructure, favorable reimbursement policies, and high patient awareness. The United States, in particular, leads the market thanks to its technological advancements and robust demand for orthopedic procedures.

Europe follows closely, with countries such as Germany, the UK, and France driving market growth through a mix of public and private healthcare initiatives. The European market also benefits from a strong emphasis on research and innovation in joint reconstruction technologies.

The Asia-Pacific region presents immense growth potential due to its large population base and rising incidence of joint-related ailments. Countries like China and India are witnessing increased investments in healthcare and greater adoption of advanced surgical techniques. Moreover, as disposable incomes rise and urbanization accelerates, the demand for quality orthopedic care is expected to surge.

Latin America and the Middle East & Africa are emerging markets with untapped potential. While these regions currently face challenges like inadequate healthcare infrastructure and affordability issues, strategic investments and international collaborations could unlock substantial opportunities in the near future.

Competitive Outlook

The competitive landscape of the hips & knees reconstructive market is marked by the presence of several established players as well as new entrants. Companies are competing on various fronts, including product innovation, pricing strategies, and customer service.

Brand loyalty and strong distribution networks give leading players a competitive edge. Moreover, companies are increasingly investing in R&D to create more durable and biocompatible implants. These investments are expected to pay dividends in terms of both market share and customer trust.

Strategic alliances, mergers, and acquisitions are also common in this market, allowing companies to expand their product offerings and geographical reach. These partnerships are instrumental in enabling firms to stay ahead of technological trends and meet the evolving demands of healthcare providers and patients.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/hips-and-knees-reconstructive-market

Top Companies

Several top-tier companies dominate the hips & knees reconstructive market, offering a diverse range of products and solutions. These include multinational corporations that have established a strong global presence and are known for their innovative technologies.

Zimmer Biomet, Stryker Corporation, and DePuy Synthes (a Johnson & Johnson company) are among the market leaders, known for their high-quality joint replacement solutions. Smith & Nephew and B. Braun Melsungen are also prominent players with significant market influence, especially in Europe.

Emerging companies and startups are not far behind, bringing disruptive technologies such as AI-assisted surgical tools and patient-specific implants to the forefront. These innovators are contributing to a more competitive and dynamic market environment, which ultimately benefits patients and healthcare systems alike.

Segmentation Outlook

The hips & knees reconstructive market can be segmented based on product type, procedure, end-user, and geography. In terms of product type, the market includes primary hip and knee replacements, revision implants, and partial replacements. Primary replacements account for the largest share due to the higher frequency of initial joint surgeries compared to revisions.

Based on procedure, the market is segmented into total replacement, partial replacement, and revision surgeries. Total replacement remains the most common, particularly for elderly patients with advanced joint degeneration.

In terms of end-users, hospitals and ambulatory surgical centers (ASCs) dominate the market. Hospitals offer comprehensive orthopedic services and are preferred for complex surgeries, while ASCs are gaining popularity for less complicated, outpatient procedures due to their cost-effectiveness and convenience.

From a geographical perspective, segmentation helps stakeholders understand regional demand patterns and tailor strategies accordingly. As different regions have unique healthcare policies, economic conditions, and patient demographics, a localized approach is essential for success.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

DNA Polymerase Market Projected to Grow at 6.2% CAGR Through 2035

The global sales of DNA polymerase are estimated to be worth USD 397.7 million in 2025 and anticipated to reach a value of USD 725.8 million by 2035. Sales are projected to rise at a CAGR of 6.2% over the forecast period between 2025 and 2035. The revenue generated by DNA polymerase in 2024 was USD 374.8 million.

The DNA Polymerase Market is evolving rapidly due to its indispensable role in molecular biology, genetic engineering, diagnostics, and therapeutic research. DNA polymerases are enzymes that facilitate the replication of DNA by catalyzing the synthesis of DNA molecules from deoxyribonucleotides. Their usage spans across a wide range of applications, including PCR (polymerase chain reaction), DNA sequencing, cloning, and other advanced genetic technologies.

As scientific research and biotechnological innovation accelerate, the demand within the DNA Polymerase Market continues to rise. Academic institutions, pharmaceutical companies, and diagnostic laboratories are increasingly adopting these enzymes to support their genomic and proteomic studies. With their capacity to amplify and edit DNA with high precision, DNA polymerases are crucial tools that enable breakthroughs in personalized medicine, forensic science, and disease diagnostics.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-801

Market Trends

Several emerging trends are shaping the future of the DNA Polymerase Market. The growing focus on personalized medicine is one of the key trends driving innovation. As the understanding of genetic variations improves, customized treatment plans based on individual genomic profiles are becoming more mainstream. This, in turn, increases the need for high-fidelity and thermostable DNA polymerases capable of producing accurate genetic data.

Another trend is the rise of point-of-care diagnostics and portable molecular testing kits, which are increasingly reliant on advanced DNA polymerase enzymes. Miniaturized and rapid testing kits demand enzymes that are robust, fast-acting, and capable of functioning under variable environmental conditions. This need has prompted enzyme engineering companies to develop next-generation polymerases tailored for such compact diagnostic platforms.

In addition, the expansion of the DNA Polymerase Market is supported by the increased funding for genomic research from both governmental bodies and private investors. Projects related to gene therapy, synthetic biology, and CRISPR-based editing tools require specialized DNA polymerases, thereby boosting product development and commercialization efforts.

Challenges and Opportunities

Despite its promising outlook, the DNA Polymerase Market faces a number of challenges. One of the primary concerns is the high cost of advanced DNA polymerase products, especially those engineered for high accuracy and stability. For smaller research labs and institutions in emerging economies, the expense can be a barrier to adoption.

Another challenge is the presence of strict regulatory environments that govern enzyme usage in clinical applications. Companies entering the DNA Polymerase Market must navigate complex approval processes to demonstrate the safety and efficacy of their products, particularly for therapeutic or diagnostic purposes. This often slows down the time to market and increases R&D costs.

However, these challenges also bring unique opportunities. There is a growing interest in developing low-cost alternatives without compromising quality, especially to cater to developing regions. Moreover, the ongoing demand for enzyme innovation presents a window for startups and biotech firms to enter the DNA Polymerase Market with specialized, application-specific products.

Partnerships and collaborations with academic institutions can further spur innovation and reduce development costs. As open-source biotechnology becomes more prevalent, knowledge-sharing initiatives could also play a critical role in overcoming technical and financial barriers.

Key Regional Insights

Geographical analysis reveals that the DNA Polymerase Market is seeing robust growth across North America, Europe, Asia-Pacific, and parts of Latin America. North America remains a dominant force due to its strong research infrastructure, presence of leading biotech firms, and supportive government initiatives in genomic medicine. The United States, in particular, hosts a large number of clinical trials and research projects that extensively utilize DNA polymerase enzymes.

Europe follows closely, with countries like Germany, the UK, and France leading in molecular diagnostics and academic research. Investments from EU-funded programs into biotechnology and healthcare innovation continue to propel market growth in this region.

Meanwhile, the Asia-Pacific region is experiencing significant market expansion, driven by increasing awareness of genetic diseases, growth in academic research, and rising healthcare expenditures. Countries like China, India, and South Korea are investing in life sciences and biotechnology sectors, which directly influences the demand within the DNA Polymerase Market.

Latin America and the Middle East are also showing promise due to gradual improvements in research infrastructure and interest from international companies looking to expand their operations.

Competitive Outlook

The DNA Polymerase Market is highly competitive, with numerous players striving to enhance their market position through technological innovation, mergers, acquisitions, and strategic partnerships. Companies are actively investing in R&D to create enzymes with higher processivity, lower error rates, and broader temperature ranges.

Customization has become a key strategy, as end-users increasingly seek DNA polymerases tailored to their specific research or diagnostic needs. Firms offering robust customer support, training programs, and flexible product solutions often gain a competitive edge.

The DNA Polymerase Market also benefits from the growing demand in contract research and manufacturing services. Many biotech firms are outsourcing the development and bulk production of enzyme reagents to specialized third-party providers, creating a dynamic supply chain ecosystem.

Top Companies

Several notable players dominate the DNA Polymerase Market. Thermo Fisher Scientific remains a global leader, known for its comprehensive portfolio of high-performance polymerases and extensive distribution networks. The company continuously invests in innovation and global outreach.

New England Biolabs is another major contributor, widely respected for its specialized research enzymes and commitment to open-access scientific tools. Its DNA polymerase products are trusted by many researchers worldwide for their quality and reproducibility.

QIAGEN is prominent in the DNA Polymerase Market due to its focus on molecular diagnostics and sample preparation technologies. The company offers integrated solutions that combine enzymes with assay kits and instrumentation.

Takara Bio and Agilent Technologies also have a strong market presence, each providing a wide array of enzyme products designed for advanced genetic studies. These companies compete on quality, specificity, and customer-centric service models.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/dna-polymerase-market

Segmentation Outlook

The DNA Polymerase Market can be segmented based on product type, application, end-user, and region. In terms of product type, the market is generally categorized into thermostable DNA polymerases and non-thermostable DNA polymerases. Thermostable variants, like Taq polymerase, are widely used in PCR and DNA amplification processes.

Application-wise, the DNA Polymerase Market serves diverse domains including diagnostics, drug development, forensic analysis, academic research, and synthetic biology. The increasing use of polymerases in next-generation sequencing and CRISPR applications has led to a surge in demand from both the clinical and research sectors.

By end-user, the market includes academic and research institutes, pharmaceutical and biotechnology companies, hospitals, and diagnostic laboratories. Among these, research institutes and biotech firms represent a significant portion of the market due to the frequent use of polymerases in experimental setups.

Regionally, as mentioned earlier, the market is growing across North America, Europe, Asia-Pacific, and other emerging regions, each with its own driving factors and regulatory dynamics.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Laser Therapy Devices Market Forecasted to Hit USD 8.3 Billion by 2035

The Laser Therapy Devices market is expected to reach approximately USD 3.6 billion in 2025 and expand to around USD 8.3 billion by 2035, reflecting a compound annual growth rate (CAGR) of 8.8% over the forecast period.

The laser therapy devices market is witnessing growing interest across various medical specialties due to its non-invasive nature, minimal side effects, and growing therapeutic efficiency. These devices utilize focused light energy to stimulate cellular activity, promote healing, and reduce pain and inflammation. With technological advancements continuing to reshape healthcare delivery, laser therapy is becoming an essential part of modern treatment approaches. From dermatology and orthopedics to dental care and ophthalmology, the adoption of laser therapy devices is expanding due to their effectiveness and versatility.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-5241

Healthcare professionals are increasingly incorporating laser-based treatments to address a variety of acute and chronic conditions. Additionally, the preference for painless and drug-free therapies among patients is supporting the market’s momentum. As hospitals and clinics become more technologically equipped, the demand for innovative and cost-effective laser therapy devices is expected to remain strong.

Size & Trends

The laser therapy devices market is on a steady growth trajectory, influenced by increasing patient awareness, growing incidences of chronic conditions, and the rise of outpatient care services. A significant trend shaping the market is the integration of laser technology in homecare settings, allowing patients to manage pain and other conditions from the comfort of their homes. Furthermore, manufacturers are focusing on producing portable and user-friendly devices that cater to this demand.

Another notable trend is the surge in cosmetic and aesthetic procedures. With the rise in social media influence and the desire for minimally invasive treatments, laser therapies for skin resurfacing, hair removal, and wrinkle reduction are gaining traction. This trend is expected to continue, particularly in urban areas with higher disposable incomes and healthcare access. Moreover, the fusion of laser therapy with AI and digital monitoring tools is expected to transform treatment protocols and enhance precision and outcomes.

Key Highlights

One of the key highlights of the laser therapy devices market is its expanding scope across medical and cosmetic disciplines. Laser therapy is widely used for treating arthritis, musculoskeletal disorders, wound healing, and neuropathic pain. In cosmetic applications, its benefits include skin rejuvenation, acne treatment, and pigmentation correction. The versatility of laser devices has allowed practitioners to offer a broader range of treatments without the need for invasive procedures.

In addition, the rise in chronic health conditions like diabetes and osteoarthritis is propelling the need for alternative therapies that provide relief without long-term medication use. Laser therapy offers a compelling option, particularly in pain management, where opioids and pharmaceutical treatments pose significant side effects and dependency risks. Innovations in device design, including adjustable wavelength settings and built-in safety protocols, are further supporting the market’s development.

Challenges and Opportunities

Despite its promising growth, the laser therapy devices market faces several challenges that could affect its expansion. High initial costs of advanced laser systems remain a barrier for small- and medium-sized healthcare facilities. Moreover, the lack of universal reimbursement policies for laser treatments often deters patients from opting for these therapies, especially in developing economies.

Another challenge lies in the need for specialized training. Improper use of laser therapy devices can result in burns or ineffective treatment, making clinician expertise critical for successful outcomes. This necessitates investment in training programs and certification, which some healthcare centers may find burdensome.

Nevertheless, the market presents numerous opportunities. As regulatory bodies become more favorable towards approving laser-based therapies, the pathway for device commercialization becomes smoother. The increasing emphasis on personalized medicine also aligns well with laser therapy, which can be customized to match patient-specific conditions. Moreover, as wearable laser devices enter the market, particularly for homecare and sports medicine applications, the user base is expected to expand significantly.

Key Benefits for Stakeholders

Stakeholders in the laser therapy devices market stand to benefit from several factors that contribute to value creation and business expansion. For healthcare providers, laser devices offer improved patient outcomes with reduced recovery times, fewer complications, and lower dependency on pharmaceutical interventions. This supports improved patient satisfaction and operational efficiency.

Manufacturers gain from the steady demand for technologically advanced devices, especially in niche markets such as sports medicine, veterinary care, and cosmetic dermatology. The ongoing research into wavelength optimization and light modulation techniques also opens up pathways for product differentiation and innovation.

Patients, arguably the most crucial stakeholders, benefit from a non-invasive, efficient, and often cost-effective treatment approach. As awareness increases and more clinical evidence supports the efficacy of laser therapy, patients are likely to embrace these devices as part of long-term treatment strategies.

Market Share by Geographical Region

The laser therapy devices market shows a varied landscape when analyzed by geographical region. North America holds a prominent share, driven by the presence of advanced healthcare infrastructure, high patient awareness, and favorable regulatory environments. The U.S., in particular, continues to invest heavily in research and development, promoting adoption among hospitals, sports medicine clinics, and rehabilitation centers.

Europe follows closely, with countries such as Germany, the UK, and France leading in device usage across both therapeutic and aesthetic applications. The integration of laser therapies in public healthcare systems has further boosted their acceptance in this region.

In the Asia-Pacific region, rapid urbanization, growing medical tourism, and increasing chronic disease prevalence are driving market growth. Countries like China, India, and Japan are witnessing a surge in demand for cost-effective and portable laser therapy devices, particularly in outpatient and homecare settings.

The Latin America and Middle East & Africa regions are gradually entering the market, with increased investments in healthcare infrastructure and rising demand for advanced treatment options. While still emerging, these regions offer significant potential for growth due to expanding populations and a rising burden of chronic diseases.

Competitive Outlook

The competitive landscape of the laser therapy devices market is characterized by a mix of established medical device giants and innovative startups. Companies are focused on expanding their product portfolios, investing in R&D, and entering strategic collaborations to gain a competitive edge. Product innovation remains a key differentiator, with manufacturers working on improving energy output, portability, and multifunctionality.

Mergers and acquisitions are also common strategies aimed at market consolidation and technological advancement. Additionally, several players are looking to expand their global footprint by tapping into underserved markets where demand for non-invasive therapies is growing.

The competition also extends to software integration, with some companies embedding AI-driven diagnostics and treatment customization features in their devices. These technological leaps not only enhance clinical outcomes but also improve the user experience, making laser therapy more accessible to both professionals and patients.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/laser-therapy-devices-market

Top Companies

Several top-tier companies dominate the laser therapy devices market with a diverse range of products and solutions. These include long-established names known for medical innovations, as well as emerging players introducing groundbreaking laser technologies. While some focus primarily on therapeutic applications, others have made their mark in aesthetic and dermatological markets.

Many of these companies are known for their global distribution networks, strong brand presence, and robust customer support systems. They continue to lead in innovation, introducing products that are more compact, efficient, and versatile. Furthermore, partnerships with academic institutions and healthcare organizations enable these companies to stay ahead of clinical trends and regulatory requirements.

Their ongoing commitment to quality assurance, clinical validation, and user training has been instrumental in maintaining customer trust and loyalty in a competitive market landscape.

Segmentation Outlook

The laser therapy devices market is segmented based on application, product type, end user, and technology. By application, the market includes pain management, wound healing, skin treatments, dental procedures, and ophthalmology. Pain management holds a significant share due to increasing incidences of musculoskeletal disorders and chronic pain conditions.

In terms of product type, the market features handheld devices, table-top systems, and wearable lasers. Handheld and portable devices are gaining popularity due to their convenience and expanding use in outpatient and homecare settings.

End users include hospitals, specialty clinics, rehabilitation centers, and homecare providers. Hospitals currently dominate the market owing to their access to high-end technologies and skilled practitioners. However, homecare is rapidly growing as devices become more affordable and user-friendly.

The technology segment includes low-level laser therapy (LLLT) and high-intensity laser therapy (HILT), with LLLT being more commonly used due to its safety profile and broader application base. As technology continues to evolve, segmentation will become more refined, catering to specific medical needs and user preferences.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Sports Medicine Market to Reach USD 2,317.6 Million by 2035

The sports medicine market is expected to reach approximately USD 1,300.0 million in 2025 and expand to around USD 2,317.6 million by 2035, reflecting a compound annual growth rate (CAGR) of 6.0% over the forecast period.

The sports medicine market is gaining remarkable traction across the healthcare industry, largely due to the growing focus on fitness, sports participation, and injury management. As more people engage in physical activity, including amateur and professional sports, the demand for medical solutions that cater to injury prevention, rehabilitation, and performance enhancement has surged. Electric bikes, which have emerged as a popular mode of exercise and mobility, contribute to this demand by fostering healthier lifestyles and making sports and fitness more accessible. The sports medicine market is thriving as medical practitioners and physiotherapists emphasize the importance of targeted treatment and recovery protocols tailored to sports-related injuries.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-5173

This market encompasses a wide range of products and services including joint repair, arthroscopic devices, braces, physiotherapy equipment, and support services. The consistent innovation in medical technologies, such as wearable sensors and regenerative medicine, adds momentum to the expansion of the sports medicine market. With increasing awareness and investments in physical well-being, the market continues to evolve rapidly.

Market Trends
One of the most prominent trends shaping the sports medicine market is the integration of advanced technologies. Innovations like 3D-printed implants, robotic-assisted surgeries, and AI-powered diagnostic tools are becoming more prevalent. These tools are enabling more precise and effective treatment for sports-related injuries, enhancing both patient outcomes and recovery times. Additionally, regenerative medicine—including platelet-rich plasma (PRP) and stem cell therapies—is gaining popularity among athletes and sports enthusiasts. These therapies are non-invasive and support natural healing processes, aligning with the preferences of patients seeking quicker recovery.

Another noticeable trend is the rise of telemedicine and virtual physical therapy. These digital solutions are especially beneficial for patients living in remote areas or those who prefer rehabilitation from the comfort of their homes. Coupled with wearable devices that monitor physical activity, virtual consultations are streamlining access to sports medicine care.

Driving Forces Behind Market Growth
Several factors are driving the growth of the sports medicine market. One of the main drivers is the increased participation in sports and fitness activities across all age groups. Governments and organizations worldwide are promoting physical activity to combat lifestyle diseases, which inadvertently contributes to more sports-related injuries—and thus more demand for sports medicine solutions.

The growing elderly population, who are keen on maintaining active lifestyles, is another key factor. As older adults engage in recreational sports, their vulnerability to injuries like sprains, fractures, and joint issues boosts the need for specialized sports medicine treatments. Moreover, the increasing prevalence of chronic conditions such as obesity and arthritis, which benefit from guided physical activity, fuels the market further.

Electric bikes, which combine the health benefits of cycling with motorized assistance, are also influencing the market. They allow individuals, especially those with limited mobility or chronic conditions, to participate in physical activities, indirectly increasing the demand for sports medicine as a support system for injury prevention and management.

Challenges and Opportunities
Despite the promising outlook, the sports medicine market faces a few challenges. One of the primary concerns is the high cost associated with advanced treatments and surgical procedures. These costs can be prohibitive for uninsured or underinsured patients, limiting market reach. Additionally, there is a lack of trained medical professionals who specialize in sports medicine, especially in developing countries. This shortage impacts the quality and availability of care in several regions.

However, these challenges also present significant opportunities. There is ample scope for market expansion in emerging economies where sports infrastructure and healthcare services are improving. As medical education and awareness grow, the gap in skilled professionals is likely to narrow. The development of cost-effective and portable treatment solutions—such as compact ultrasound devices or mobile rehab units—can also drive adoption in underserved markets.

Furthermore, the shift toward value-based care and preventive medicine is a major opportunity. Providers that emphasize long-term injury prevention and holistic wellness, rather than reactive treatments, are expected to gain traction. Sports medicine practices that integrate wellness programs, mental health support, and nutritional guidance stand to benefit greatly in this evolving landscape.

Recent Industry Developments
The sports medicine market has witnessed a wave of recent innovations and strategic partnerships. Medical device manufacturers are collaborating with tech companies to develop smart rehabilitation devices that provide real-time feedback to both patients and clinicians. These tools enhance treatment personalization and compliance, improving outcomes.

Hospitals and healthcare providers are also investing in dedicated sports medicine centers, which offer multidisciplinary services under one roof. These centers are equipped with the latest imaging, surgical, and rehab technologies, providing a comprehensive approach to injury care. Research into gene therapy and tissue engineering is also accelerating, with the potential to transform how injuries are treated at a cellular level.

Moreover, sports organizations are increasingly employing in-house sports medicine professionals, such as athletic trainers and sports psychologists, to support athlete health. This proactive approach is fostering a culture of injury prevention and rapid intervention.

Regional Analysis
Geographically, the sports medicine market shows varied growth patterns. North America dominates the global market, thanks to its advanced healthcare infrastructure, high sports participation, and supportive reimbursement policies. The United States, in particular, is a leader in sports medicine innovations and adoption, fueled by professional leagues and collegiate sports programs.

Europe is another strong region, with countries like Germany, the UK, and France investing significantly in sports and medical research. The presence of leading medical device companies and academic institutions boosts market growth in the region.

In Asia-Pacific, the market is expanding rapidly due to increasing health awareness, government initiatives promoting fitness, and the growing middle-class population. Countries like China, India, and Japan are seeing a surge in sports medicine adoption as urbanization and disposable incomes rise.

Latin America and the Middle East & Africa are emerging markets that present growth opportunities. Though infrastructure challenges persist, gradual improvements in healthcare access and sports facilities are driving interest in sports medicine solutions.

Competitive Outlook
The sports medicine market is highly competitive, with a mix of large healthcare conglomerates and specialized medical device companies. Companies are focusing on research and development to stay ahead, with particular emphasis on minimally invasive surgical tools and biologics. Mergers and acquisitions are common as players aim to broaden their portfolios and enter new regional markets.

Strategic partnerships between sports teams, academic institutions, and healthcare providers are also becoming a key feature of the competitive landscape. These collaborations foster innovation and provide access to real-world data, which is invaluable for developing effective treatments.

Brand differentiation is often achieved through service integration and patient engagement tools. Companies that offer holistic care models, combining diagnostics, treatment, and rehabilitation with patient education, tend to have a competitive edge.

Top Companies
Several companies play a prominent role in shaping the sports medicine market. Arthrex Inc. is known for its extensive range of orthopedic surgical solutions, particularly for minimally invasive procedures. Smith & Nephew offers a strong portfolio in joint repair and surgical devices, often used in sports injury treatment.

Stryker Corporation and Zimmer Biomet are major players, focusing on orthopedic implants and advanced surgical tools. Medtronic and Johnson & Johnson also maintain a presence in the market through their medical device divisions, which support a broad array of treatments.

Other notable companies include CONMED Corporation, DJO Global (an Enovis company), and Mueller Sports Medicine, which specialize in braces, supports, and rehabilitation equipment. Emerging startups are also contributing by introducing innovative wearable tech and mobile rehabilitation platforms.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/sports-medicine-market

Segmentation Outlook
The sports medicine market is segmented by product, application, end user, and region. In terms of products, the market includes body reconstruction devices, body support and recovery products, and accessories. Among these, body reconstruction—such as knee and shoulder implants—holds a major share.

By application, the market covers knee injuries, shoulder injuries, ankle and foot injuries, elbow and wrist injuries, and hip and groin injuries. Knee injuries are the most common, especially among athletes, leading to high demand for related treatments and surgeries.

End users include hospitals, ambulatory surgical centers, and physiotherapy clinics. Hospitals dominate due to their comprehensive facilities, but ambulatory centers are growing in popularity for minor procedures.

Regionally, as previously noted, North America leads, followed by Europe and Asia-Pacific. These segments reflect the diverse and evolving needs of different demographics and healthcare systems, shaping the future trajectory of the sports medicine market.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube