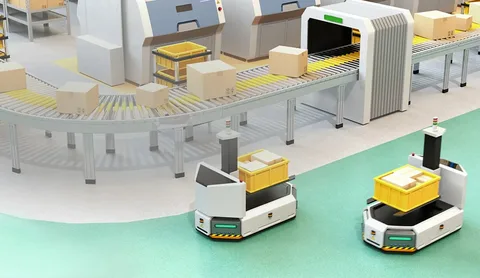
The Automated Guided Vehicles (AGVs) market is set for significant expansion, with an estimated valuation of approximately USD 1.13 billion in 2023, projected to increase to around USD 2.43 billion by 2033. This growth reflects a robust compound annual growth rate (CAGR) of 8% over the forecast period from 2023 to 2033.
The rise in AGV adoption across various sectors—such as logistics, food and beverage, healthcare, and manufacturing—is a key driver of this growth. AGVs are becoming integral to enhancing operational efficiency and optimizing processes within these industries.
According to Future Market Insights (FMI), Europe’s AGV market will see significant leadership from the United Kingdom, which is anticipated to grow at a CAGR of 7% during the forecast period. This presents considerable opportunities for AGV manufacturers in the region.
In the UK, the increasing demand for advanced AGVs in healthcare, aerospace, and e-commerce is propelling market growth. AGVs are being integrated into warehouses to improve operations and meet the rising demands of these industries.
Modern AGVs are adopting cutting-edge technologies, including telematics services and various navigation systems such as laser, magnetic, infrared, and optical methods. The growing use of wireless communication is enhancing the accuracy of position monitoring.
The global push towards industrialization is also fueling the demand for AGVs in sectors such as oil and gas, transportation, and construction. Additionally, advancements in AGV features, including enhanced fuel efficiency and customizable material handling options, are shaping the market.
Compared to fixed equipment, AGVs offer superior scalability. Manufacturers are increasingly favoring fleets of automated guided vehicles over stationary conveyors to minimize operational time and increase production efficiency in response to rising automation demands.
In the historical period from 2018 to 2022, the market increased at a CAGR of 4.6%.
FMI forecasts good growth for automated guided vehicles in the United States, with the industry rising at a 5.7% CAGR through 2033.
Between 2023 and 2033, the market in India is projected to expand at an outstanding 8% CAGR.
According to FMI’s analysis, the United Kingdom is expected to lead Europe’s AGV market, rising at a healthy 7% CAGR during the projection period.
The market’s leading players control roughly 60% of the market
Competitive Landscape
Leading players are focusing on expanding their already extensive product offerings. Increasing expenditure in research to develop improved products is another key strategy for market players to preserve their market position.
In March 2022, Seegrid Corporation, a creator of autonomous mobility robots worked with ROBEX. This collaborative project would assist Seegrid Corporation in growing its operations while also offering Seegrid Corporation products to ROBEX customers. This could also contribute to a great demand for supply chain management automation.
ResGreen Group International, Inc. (OTC PINK: RGGI) (the “Company”), a next-generation smartphone automation and software solutions provider, announced in May 2023, the release of its bidirectional BigBuddy. It is one of the industry’s durable AGVs that uses magnetic strips to transfer masses up to 5,000 pounds.
Key Companies Profiled
JBT Corporation
Kuka AG,
Daifuku Co., Ltd.
Kion Group AG
Omron Adept Technologies, INC.
AGVE Group, Inc.
Murata Machinery
Transbotics Corporation
Oceaneering International Inc.
Seegrid Corporation
Automated Guided Vehicle Market by Category
By Technology Type:
Laser Guidance
Magnetic Guidance
Infrared Guidance
Wire Guidance
Inertial Guided
Optical Guided
By Application Type:
Transportation
Distribution
Storage
By Vehicle Type:
Unit Load Carrier
Pallet Truck
Assembly Line Vehicle
Tow Vehicle
Forklift Truck
Light Load Transporters
By End Use:
Logistics
Healthcare
Automotive
Manufacturing
Food & Beverages
Aerospace
By Region:
North America
Latin America
Europe
South Asia
East Asia
Oceania
The Middle East and Africa
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer, Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
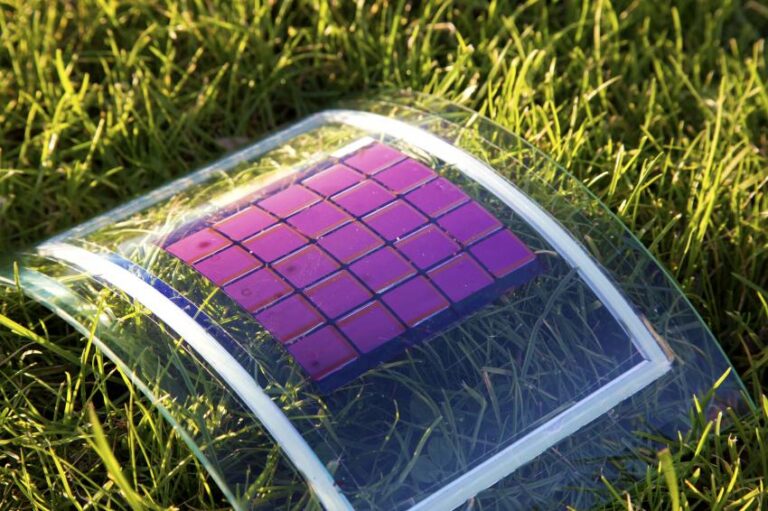
The global polymer solar cell market is on the brink of extraordinary growth, with forecasts indicating it will reach an impressive USD 290 million by 2027, driven by a remarkable compound annual growth rate (CAGR) of 21.5%. This surge presents a transformative opportunity for industry leaders to advance sustainable energy solutions. Here’s why now is the perfect time to act:
Unprecedented Growth: Seize the chance to be at the forefront of the clean energy revolution as the market experiences unparalleled expansion. This is an ideal moment to lead in this rapidly evolving sector.
Versatile Applications: There is growing demand from Building-Integrated Photovoltaics (BIPV), with promising opportunities emerging in consumer electronics and the automotive industry. Innovate to create solutions tailored to these diverse applications.
BIPV Innovation: Building-integrated solar technology is increasingly sought after. Invest in BIPV innovations to help architects and construction professionals design energy-efficient, self-powered buildings.
Consumer Electronics: The consumer electronics sector offers substantial opportunities. Develop advanced polymer solar cells to power the next generation of electronic devices.
Automotive Sector: The automotive industry is embracing sustainable energy solutions. Focus on developing polymer solar cells that can be seamlessly integrated into electric vehicles and other cutting-edge automotive technologies.
Asia Pacific – The Growth Hub: The Asia Pacific region (excluding Japan) is a major market for polymer solar cells, driven by rising incomes and booming electronics consumption. Target this high-growth area for significant market capture.
Explosive Growth in APEJ: The Asia Pacific region is projected to reach a market value of USD 124.5 million by 2027, with a striking CAGR of 24.6%. Engage with this transformative market shift to achieve substantial growth.
The Takeaway: The polymer solar cell market is crucial for a sustainable future. By focusing on diverse applications, advancing BIPV technology, exploring consumer electronics and automotive innovations, and capitalizing on the explosive growth in Asia Pacific, industry leaders can position themselves as pioneers in a cleaner, greener tomorrow.
Global Polymer Solar Cells Market: Dynamics Impacting the Global Market
The main aspects boosting the growth of the global polymer solar cells market is the development of the electronics and electrical industry, rising demand for sources of renewable energy, increasing government support and initiatives, increasing construction activities associated with green buildings along with expanding automobile and the construction industries. Various trends are discussed in the research study, which have an indirect impact on the market’s growth, to name a few, the enhancement of manufacturing techniques of polymer solar cells (which reduce costs and enhance performance), development of electronic devices, improvement in the energy payback time with respect to both finance and energy, focusing on development of new material in order to make photovoltaics as the best alternative to organic fuels, development of new plastic solar cells to minimize energy loss and increasing the life span of organic solar photovoltaic cells.
However the global polymer solar cells market is not without of challenges. High dependency on fossil fuels, high fluctuations in the prices of oil and gas, comparatively less power conversion capacity, higher dependency on hydroelectricity, low stability and strength, availability of alternatives and limited operational life of organic solar cells might pose restraint to the growth of the global polymer solar cells market.
Global Polymer Solar Cells Market: Competition Analysis
The global polymer solar cells market has included several key players involved in the manufacturing and supply of polymer solar cells. The report has profiled companies such as Heliatek GmbH, InfinityPV ApS, BELECTRIC OPV GmbH (OPVIUS GmbH), SUNEW, Solarmer Energy, Inc., Armor Group, Solvay S.A., Eight19 Ltd., SolarWindow Technologies, Inc., and Raynergy Tek Incorporation.
Regional Analysis:
By region, Asia Pacific excluding Japan (APEJ) region is anticipated to dominate the global polymer cells market with respect to high market share during the forecast period. This region is projected to grow at the highest CAGR of 24.6% throughout the period of assessment 2017-2027. The main contributor is China, which shows high potential and is the fastest growing country with a high CAGR of 25.5% during the forecast period. North America, Japan and Western Europe also poised to show significant growth in the coming years
By product type, the multi-junction segment is expected to grow at a higher pace than any other segments during the assessment period. However, the bulk heterojunction segment is estimated to show higher market share thus leading the global polymer solar cells market
By technique, the printing segment is expected to show a high market share and high growth rate than the coating segment, to reach a value a little under US$ 240 Mn and is poised to register a robust CAGR throughout the forecast period
With respect to the application category, the BIPV segment is poised to grow at the highest rate to register a CAGR of 23.3% during the assessment period. It is also anticipated to witness high market share, thus leading the global polymer solar cells market by application
Market Segmentation
Junction Type
Single Layer
Bilayer
Bulk Heterojunction
Multi-junction
Others
Application
BIPV (Building Integrated Photovoltaic)
Consumer Electronics
Automotive
Defence and Emergency
Others
Technique
Printing Technique
Coating Technique
Region
North America
Western Europe
Eastern Europe
Latin America
APEJ
Japan
MEA
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer, Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
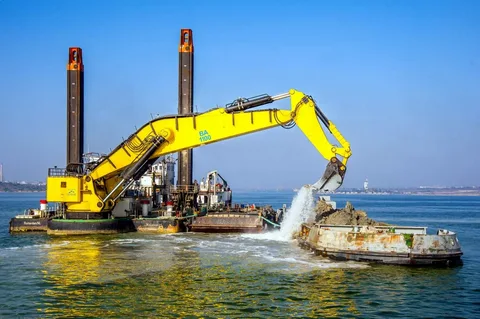
The global dredging market is projected to exceed USD 20,638.92 million by 2034, up from USD 16,684.12 million in 2024, reflecting a steady compound annual growth rate (CAGR) of 2.15% throughout the forecast period, according to Future Market Insights (FMI).
A significant driver of this growth is the One Belt One Road Initiative (OBOR), a major infrastructure project spanning multiple continents. This initiative is creating substantial opportunities for dredging companies, particularly in the development of ports, harbors, and associated infrastructure. As the market capitalizes on these opportunities, it is expected to experience considerable expansion and transformation.
The dredging industry is also set to benefit from increased demand for Gulf Coast restoration projects. Companies are enhancing their operations with advanced dredger monitoring systems and upgraded equipment to boost efficiency and performance.
Additionally, rising government investments in dredging projects across both emerging and developed economies are anticipated to further propel market growth. Governments are focusing on the timely and cost-effective dredging of harbors, channels, and waterways to achieve goals related to environmental preservation, restoration, and improvement.
In terms of customer segmentation, the government sector is anticipated to maintain a substantial market share of 43.6% in 2022, underlining its pivotal role in driving industry demand.
Regarding application, the energy infrastructure segment is poised for a year-on-year growth of 4.6% in 2024, reflecting the sector’s resilience and potential.
Projections for the U.S. dredging market indicate a steady 2% Compound Annual Growth Rate (CAGR) from 2024 to 2034, reaffirming the country’s significant role in the industry.
Notably, Japan is poised to emerge as a lucrative market, with an estimated sales growth of 5.7% CAGR through 2034, showcasing its increasing importance on the global stage.
China’s prominence remains evident, with its market projected to account for a considerable 25% share of the East Asia dredging market in 2022, underlining its strong regional influence.
Steering toward the future, East Asia is expected to capture a commanding share of 32.9% in the global dredging market by 2034, reinforcing its status as a key player.
These insights collectively paint a picture of a dynamic and evolving dredging industry, where technological advancements, government involvement, and regional dynamics will play instrumental roles in shaping its trajectory over the foreseeable future.
Competitive Landscape:
The competitive landscape of the worldwide dredging market exhibits substantial consolidation across Tier I, Tier II, and Tier III entities. Preeminent participants within the market command a noteworthy 50 to 55% collective share in terms of market value.
Key Players
HYUNDAI E&C
Royal IHC
Dredging, Environmental and Marine Engineering NV (DEME)
Great Lakes Dredge & Dock Company, LLC
TOA Corporation
Penta-Ocean Construction Co., Ltd.
National Marine Dredging Company
Amrut Dredging and Shipping Ltd.
CALLAN MARINE, LTD.
CASHMAN DREDGING, INC.
China Communications Construction Company Limited
COTTRELL CONTRACTING CORPORATION
Dredge America
Dredging Africa (Pty) Ltd
Prominent contenders in this industry sphere encompass:
China Communications Construction Company Limited: Renowned for its strategic prowess, it stands as a key driver of market innovation and progress.
Royal Boskalis Westminster N.V.: A stalwart in maritime solutions, its presence contributes significantly to shaping industry benchmarks.
Dredging, Environmental and Marine Engineering NV (DEME): A vanguard in sustainable practices, it plays a pivotal role in environmentally conscious dredging efforts.
Van Oord: Globally recognized for its expertise, it continually raises the bar with its cutting-edge approaches.
Great Lakes Dredge & Dock Corporation: A foremost force in the field, it is instrumental in major projects that redefine maritime landscapes.
Royal IHC: A distinguished name synonymous with innovation, it consistently delivers state-of-the-art solutions.
National Marine Dredging Company: With a strategic approach, it holds a significant position in driving industry advancements.
Key Segments Covered in Dredging Market Analysis:
Customer Type:
Government
O&G Companies
Mining Companies
Renewables
Others
Application:
Trade Activity
Trade Maintenance
Energy Infrastructure
Urban Development
Coastal Protection
Leisure
Region:
North America
Latin America
Europe
East Asia
South Asia and the Pacific
Middle East & Africa
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
According to a report by Future Market Insights (FMI), the process automation and instrumentation market is anticipated to grow at a consistent compound annual growth rate (CAGR) of 5.5% from 2023 to 2033. The market is expected to reach USD 1.72 billion by 2033, up from an estimated USD 1.06 billion in 2023.
Key Drivers and Benefits of the Process Automation and Instrumentation Industry:
Corporate Expansion and Continuous Operations: The demand for operational efficiency and ongoing analysis is fueling market growth. Process automation facilitates round-the-clock operations, enhancing accuracy and productivity.
Increased Productivity: Automation, through both attended and unattended bots, boosts productivity by reducing dependence on paper-based processes. This streamlining of repetitive tasks leads to smoother automation and more efficient operations.
Cost Savings and Error Reduction: By lowering operational costs and minimizing errors, automation contributes to significant cost savings for companies. Improved data management and accuracy further drive the adoption of process automation tools.
Technological Integration: The integration of process automation with emerging technologies such as artificial intelligence and machine learning is broadening the market’s scope. This advancement serves a diverse range of end-users and applications.
Improved Information Flow and Employee Satisfaction: Automation enhances information flow, improves employee satisfaction and retention, and strengthens customer integration. It also reduces labor costs and boosts workplace safety while maintaining consistent productivity.
Key Points from the Process Automation and Instrumentation Market Report:
The United States market leads the North American process automation and instrumentation market in terms of market share in North America. The United States held a market share of 5% in 2022. The factors attributed to the growth are the restoration of corporate infrastructure, new software, and hacks for enhanced productivity in the spaces.
The German process automation and instrumentation market held a healthy market share of 3% in 2022: higher economic activities, product trades, adoption of process automation, and better scalability cause market growth.
The Indian market thrives at a steady CAGR of 8% between 2023 and 2033. The growth is attributed to higher outsourcing businesses, new businesses, and enhanced innovations.
China thrives at a CAGR of 3% between 2023 and 2033.
Based on operation type, the semi-automatic segment held the leading market share of 6% in 2022. Higher consumption, affordable pricing, and increased adoption are rising the segment’s strength.
Based on end use, the automotive segment leads as it held a market share of 5% in 2022.
Competitive Landscape in Process Automation and Instrumentation Market:
The key suppliers focus on better integration of smart technologies, custom design, and better programing. The competitors also merge, acquire, and partner with other companies to increase their supply chain and distribution channel.
Recent Market Developments:
Rockwell Automation Inc. has introduced the instrumentation network services. It includes the FOUNDATION Fieldbus and HART communication protocol.
General Electric Company has launched the life extensions/replacements and lifecycle services.
Yokogawa Electric Corporation has introduced digital transformation, IA2IA, and smart manufacturing. The programs are integrated with AR/VR, the Internet of Things, and Artificial Intelligence.
Key Players Profiled in the Process Automation and Instrumentation Market:
ABB Limited
Emerson Electric Company
Mitsubishi Electric Company
Rockwell Automation Inc.
Siemens AG
Schneider Electric SE
Yokogawa Electric Corporation
Honeywell International Inc.
Pepper Fuchs GmbH.
General Electric Company
Hitachi Ltd
Delta Electronics
Fuji Electric
Koyo Electronics Industries Co., Ltd.
Yokogawa Electric Corporation
Market Key Segmentations:
By Instrument Type:
Transmitters
Flow meters
Analyzers
Controllers
Switches
Recorders
Switches
Vacuum Instruments
By Solution:
PLC
SCADA
DCS
HMI
APC
MES
Safety Automation
By End Use:
Chemical
Metal & Mining
Food & Beverage
Oil & Gas
Pharmaceutical
Pulp & Paper
Wastewater Treatment
Automotive
Others
By Operation Type:
Automatic
Semi-Automatic
Others
By Regions Covered:
North America
United States
Canada
Latin America
Brazil
Mexico
Rest of Latin America
Europe
Germany
United Kingdom
France
Spain
Russia
Rest of Europe
Japan
Asia Pacific Excluding Japan
China
India
Malaysia
Singapore
Australia
Rest of Asia Pacific Excluding Japan (APEJ)
The Middle East and Africa
GCC Countries
Israel
South Africa
Middle East and Africa (MEA)
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global refrigerators market is undergoing a significant transformation, driven by evolving consumer preferences, technological advancements, and shifting economic landscapes. As we look towards the future, the market is set to experience robust growth, the refrigerators marketis anticipated to expand to a valuation of US$ 89.06 billion in 2023 and is predicted to exhibit a CAGR of 6.5% from 2023 to 2033 and reach US$ 167.17 billion in 2033.This growth reflects not only an increase in demand but also a response to new trends and challenges, including the impact of the COVID-19 pandemic.
Refrigerators Market Overview
The refrigerators market encompasses a wide range of cooling appliances designed to preserve food and beverages. This sector has seen continuous innovation, from basic models to high-tech smart refrigerators equipped with advanced features like touch screens, internet connectivity, and energy-efficient technologies. As of 2023, the market is valued at approximately $X billion, and is expected to reach $X billion by 2033, underscoring its pivotal role in modern households and commercial settings.
Trends in the Refrigerators Market
Several key trends are shaping the refrigerators market:
Smart Technology Integration: One of the most notable trends is the integration of smart technology. Modern refrigerators now come with Wi-Fi connectivity, allowing users to control and monitor their appliances remotely. Features like voice control, touch screens, and artificial intelligence (AI) enhance convenience and energy efficiency.
Energy Efficiency: With growing environmental concerns and rising energy costs, there is a strong emphasis on energy-efficient appliances. Refrigerators with higher energy star ratings are becoming increasingly popular as consumers seek to reduce their carbon footprint and lower utility bills.
Customization and Design: Consumers are looking for refrigerators that not only perform well but also complement their kitchen aesthetics. Manufacturers are offering customizable options and a variety of designs to meet diverse tastes and preferences.
Health and Wellness Focus: The focus on health and wellness is influencing refrigerator designs. Features such as advanced filtration systems, humidity control, and separate compartments for different types of food are becoming standard to help maintain food freshness and nutritional value.
Rising Demand in Emerging Markets: Emerging markets, particularly in Asia-Pacific and Latin America, are witnessing increased demand for refrigerators. Growing urbanization, rising disposable incomes, and improving living standards are driving this demand.
The COVID-19 pandemic has had a profound impact on the global refrigerators market. Initially, the market experienced disruptions in supply chains, affecting production and distribution. Lockdowns and restrictions led to a temporary dip in sales as consumers prioritized essential goods over appliances.
However, the pandemic also accelerated certain trends. With more people spending time at home, there was a surge in demand for home appliances, including refrigerators. The focus on health and hygiene led to increased interest in refrigerators with advanced filtration and antimicrobial features.
Moreover, the pandemic highlighted the importance of home cooking and food preservation, further driving demand for high-quality refrigerators. As the world adapts to the new normal, the market is rebounding strongly, with manufacturers innovating to meet the evolving needs of consumers.
Key players in the market include Samsung,
Haier
Electrolux
Sharp
Whirlpool
LG
Godrej
Intex
Voltas
Pansonic
Toshiba
TCL
Hitachi
BSH
Midea
Hisense
Arcelik
Xinfei
Daikin and Meiling.
Regions and Countries Analyzed in the Report
North America (the USA, Canada)
Latin America (Mexico, Brazil, Rest of LATAM)
Europe (Germany, the United Kingdom., France, Italy, Spain, Poland, Russia, Rest of Europe)
East Asia (China, Japan, South Korea)
South Asia (India, Thailand, Malaysia, Vietnam, Indonesia)
Oceania (Australia, New Zealand)
Middle East & Africa (GCC Countries, Turkey, Northern Africa, South Africa)
Author:
Sudip Saha is the managing director and co-founder at Future Market Insights, an award-winning market research and consulting firm. Sudip is committed to shaping the market research industry with credible solutions and constantly makes a buzz in the media with his thought leadership. His vast experience in market research and project management a consumer electronics will likely remain the leading end-use sector cross verticals in APAC, EMEA, and the Americas reflects his growth-oriented approach to clients.
He is a strong believer and proponent of innovation-based solutions, emphasizing customized solutions to meet one client’s requirements at a time. His foresightedness and visionary approach recently got him recognized as the ‘Global Icon in Business Consulting’ at the ET Inspiring Leaders Awards 2022.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
From 2023 to 2033, the corn fiber market is expected to increase at an astounding rate. The global market is predicted to reach a valuation of US$ 0.7 billion in 2023, per the research report released by FMI. By 2033, it’s anticipated to exceed $3.16 billion USD. From 2023 to 2033, the market is anticipated to grow at a CAGR of 14.7%.
Several industries, including textile, pharmaceutical, food & beverages, animal nutrition, and others use corn fiber. A form of soluble fiber called resistant starch found in corn fiber has demonstrated a range of health advantages on consumption. Corn fiber has been found beneficial in blood sugar regulation and lowering cholesterol levels. Its prebiotic qualities lower the risk of heart disease and improve intestinal health. The escalating use of corn fiber in end-use industries is driving market growth. Additionally, the improving income levels and expanding global population contribute to market development.
The concerns of consumers regarding the food they consume are rising globally. Consumers are becoming more aware and are prepared to pay extra for goods that they believe are better made and healthier. The increasing demand for high-quality animal products is predicted to foster growth in the market. Additionally, pet food items that are specifically designed to fulfill the specific nutritional requirements of various sorts of pets are in more demand.
To take advantage of new market trends, the key industry players are investing more money in marketing and research and development operations. Market players are spending more on research and development initiatives to capitalize on increasing trends in the food and beverage sector. They are working on products that follow the most recent dietary trends and properly optimize their marketing campaigns.
Key Takeaways from Corn Fiber Market Report:
In 2018, the global market size stood at nearly US$ 0.23 billion.
The market for corn fiber in Europe is projected to exhibit a CAGR of 10% from 2023 to 2033.
Asia Pacific is anticipated to attain a significant market share during the forecast period. Due to the presence of key pharmaceutical companies. The expanding food and beverage industry and textile sectors are expected to further bolster the region’s market development.
North America is likely to dominate the global market due to the presence of robust pharmaceutical and healthcare industries.
The animal nutrition segment is likely to gain swift growth in the coming years.
In January 2023, Cargill commercialized a soluble maize fiber component. The new bulking ingredient has a minimal impact on the texture and color and has half the calories of sugar.
Novozymes introduced the first enzymatic corn separation technique in November 2022. The new soluble corn fiber may be utilized in dairy products, cereals, drinks, baked goods, pet food, and confectionary items. Because of the discovery, producers are now able to run their corn mills more effectively, which has fundamentally altered the market. The first-generation enzyme, Frontia Fiberwash, assisted plants in producing more starch with less energy and carbon dioxide emissions.
Market Segmentation
Market by Application:
Corn Fiber in Food
Bakery
Breakfast Cereals & Snacks
Confectionery
Dairy
Meat Product
Infant Food
Corn Fiber in Beverages
Corn Fiber in Pharmaceutical
Corn Fiber in Animal Nutrition
Swine
Ruminants
Poultry
Pet
Corn Fiber in Textile
Apparels
Nonwovens
Home Textiles
Industrial Textiles
Market by Region:
Corn Fiber in North America Market
Corn Fiber in Asia Pacific Market
Corn Fiber in Europe Market
Corn Fiber in Latin America Market
Corn Fiber in the Middle East and Africa Market
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global chitosan oligosaccharides market is forecasted to achieve remarkable growth, with its valuation projected to soar from USD 2.5 billion in 2022 to an impressive USD 9.8 billion by 2032. This represents a robust compound annual growth rate (CAGR) of 14% over the forecast period. The significant expansion of this market can be attributed to several key factors, including increased waste from the seafood industry, government support for waste utilization, and a rise in applications across diverse sectors.
The global chitosan oligosaccharides market is set to experience unprecedented growth, driven by sustainability and wide-ranging applications.
Key Market Drivers and Applications
Sustainability and Waste Utilization: The chitosan oligosaccharides market is significantly propelled by the growing volume of waste generated by the seafood industry. Annually, approximately 6 million tons of crab, lobster, and shrimp shell waste are produced globally. This abundant raw material serves as a key driver for the chitosan oligosaccharides market, enabling the production of eco-friendly agricultural materials such as organic fertilizers and inorganic fungicides.
Rise in Demand for Bio-Based Cosmetic Products: The cosmetics industry is experiencing a surge in demand for bio-based products, and chitosan oligosaccharides, with their beneficial properties and availability in both powder and liquid forms, are becoming a favored ingredient. Their excellent solubility, antioxidant, and antimicrobial properties make them ideal for skincare and hair care formulations, driving market growth.
Agricultural Applications: Chitosan oligosaccharides are widely used in the agricultural sector for the preparation of fertilizers, seed treatment products, and plant activators. Their ability to enhance the innate immunity of plants and protect against pathogenic agents boosts their demand. The agricultural industry’s growth, supported by an increasing global population and the need for higher crop yields, further propels the market.
Wastewater Treatment: With rising urbanization and industrialization, particularly in the Asia Pacific region, the demand for efficient wastewater treatment solutions is escalating. Chitosan oligosaccharides, being eco-friendly, play a crucial role in wastewater treatment processes. This drives their sales as an effective treatment chemical, contributing to market expansion.
Regional Outlook
The Asia Pacific region is expected to witness significant growth in the chitosan oligosaccharides market. Rapid urbanization, industrialization, and the need for sustainable wastewater treatment solutions are key factors driving demand. Moreover, the region’s thriving agricultural sector, which extensively uses chitosan oligosaccharides in various applications, further boosts market growth.
Industry Innovations and Future Prospects
Ongoing research and development activities are exploring new applications and uses for chitosan oligosaccharides. The cosmetics industry, wastewater treatment sector, and agricultural industry are likely to see innovative product developments, expanding the market’s scope. Additionally, the Mexican government’s elimination of stringent regulations, which previously restricted the establishment of new manufacturing units, has led to the growth of large-scale pharmaceutical manufacturing facilities. This development is expected to further fuel demand for chitosan oligosaccharides in the region.
Key Market Players
Prominent players in the chitosan oligosaccharides market include:
Kunpoong Bio Co., Ltd
Auro Biotechnologies Pvt. Ltd.
Marshall Marine Products
News-Golden-Shell Pharmaceutical Co., Ltd
T.C. Bio Corporation
Zhejiang Aoxing Biotechnology Co., Ltd
Jinan Haidebei Marine Bioengineering Co., Ltd.
Yaizu Suisankagaku Industry Co., Ltd.
These companies are actively engaging in strategies such as mergers, acquisitions, and partnerships to consolidate their market positions and expand their share in the growing chitosan oligosaccharides market.
Key Segments Profiled in the Chitosan Oligosaccharides Market Survey
By Grade:
Crab
Shrimp
By Form:
Liquid
Powder
By Grade:
Food Grade
Agriculture Grade
Pharmaceutical Grade
Cosmetic Grade
By End Use:
Food and Beverage Industry
Waste Water Treatment
Pharmaceutical Industry
Cosmetic and Personal Care Industry
Agriculture Industry
Textile Industry
Chemical Industry
Animal Feed Supplements
By Region:
North America
Latin America
Europe
East Asia
South Asia
Oceania
Middle East and Africa
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global almond protein market size, which amassed a market value of USD 4.14 billion in 2022, is set to grow at a robust CAGR of 6% over the forecast period from 2022 to 2032, reaching an estimated USD 7.42 billion by 2032. This growth is primarily fueled by the increasing dependency on almond protein by the vegan population, alongside rising health and environmental awareness.
As consumers globally shift towards plant-based and protein-rich diets, almonds are transforming from a luxury to a necessity. This transition is significantly bolstering the growth prospects of nut milk and nut-based meat replacement markets. Almonds, celebrated as a nutritionally dense superfood, are cementing their position in the plant-protein sector. The market’s expansion is further propelled by the growing number of consumers adopting plant-based diets due to changing taste preferences and increasing health and environmental concerns.
Key Market Drivers:
High-Protein Trend: The accelerating consumer demand for high-protein foods is driving manufacturers to differentiate themselves in an increasingly crowded marketplace. This demand is infiltrating various food categories, from snacks to frozen meals. As food manufacturers adapt to the health and cultural factors influencing consumption, the almond protein market is expected to witness sustained demand.
Rise of Vegan Culture: Increasing concerns over animal welfare have led to a rise in veganism and vegetarianism, boosting the demand for plant-based food ingredients. This trend has inundated the food industry with numerous plant-based products, enhancing the application scope of almond proteins. Furthermore, challenges associated with other plant-derived ingredients, such as texture issues with pea protein and allergic reactions to soy, are shifting the spotlight to almond protein.
Optimal Sensory Profile: Almond protein stands out due to its neutral taste and texture, making it a preferred choice for various protein ingredient blends. This ideal sensory profile, coupled with the absence of masking agents, facilitates clean ingredient statements, which align with increasing consumer curiosity about food sourcing.
Technological Advancements: Technological advancements in almond farming methods, including automated management processes and scientific planting approaches, are crucial for meeting the rising demand for almond protein. These advancements reduce management costs and the final product price, attracting consumers, particularly in low- and mid-income countries.
Regional Insights:
North America: North America, especially the U.S., is the largest contributor to the almond protein market, driven by high almond production rates and significant demand in personal care, confectionery, and fitness sectors. The fitness-conscious population’s investment in almond-based protein beverages is further boosting market growth. The region is expected to register a CAGR of 8% during the forecast period.
Asia Pacific: The demand for almond protein in countries like Japan, India, and China is bolstering market growth in the Asia Pacific region. Almond protein is widely used in personal care products and various desserts in these countries. The Asia Pacific region is projected to register a CAGR of 6% from 2022 to 2032.
Market Competition: Key players in the almond protein market include Blue Diamond Ingredients, Noosh Brands, Almond Pro Foods, InovoBiologic Inc., Sabinsa Corporation, and BASF. Blue Diamond Ingredients, for instance, focuses on launching almond protein powders in various flavors, adaptable for different recipes.
Challenges: The almond protein market faces challenges such as the gap between demand and production. Commercialization of almond protein is urgently required, and farmers need to invest in advanced technology to increase production. Global warming and climate crises are also affecting almond production, impacting market growth.
Key Segments Profiled in the Almond Protein Industry Survey
Application :
Beverages
Confectionery & Bakery
Personal Care
Distribution Channel :
Online
Supermarkets/Hypermarkets
Convenience Store
Region :
North America
Latin America
Europe
East Asia
South Asia & Pacific
MEA
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global fermented chymosin market is on a trajectory of robust growth, expected to achieve a substantial revenue milestone of US$ 6.7 billion by 2032, up from US$ 4.6 billion in 2022. With a steady CAGR of 3.5% during the forecast period from 2022 to 2032, this market presents promising investment prospects driven by evolving consumer preferences and technological advancements in cheese production.
The increasing adoption of vegetarian and vegan diets worldwide is a significant driver fueling the demand for fermented chymosin. As per data from Vegetarian Times, approximately 3.2% of adults in the United States adhere to a vegetarian diet, with a growing segment opting for completely animal-free products. This shift is boosting the consumption of plant-based cheese alternatives, thereby augmenting the market for fermented chymosin as a key enzyme in cheese production.
Moreover, the growing awareness of the nutritional benefits of cheese, coupled with rising per capita incomes and improvements in living standards globally, is accelerating the demand for high-quality dairy products. Fermented chymosin plays a pivotal role in enhancing the texture, taste, and nutritional profile of cheese, catering to discerning consumer preferences for healthier, tastier, and sustainably produced food options.
Regional Insights
Asia Pacific emerges as a pivotal region poised for substantial growth in the fermented chymosin market. The region’s burgeoning population, coupled with increasing disposable incomes and a shift towards western dietary habits, is driving robust demand for cheese and dairy products. Countries like China and India are witnessing a surge in vegan populations, further propelling market growth.
In North America and Europe, traditional strongholds of cheese consumption, changing consumer preferences towards healthier and sustainable food choices are reshaping the market landscape. Technological advancements in cheese production methods in countries like the UK, France, and Germany are expected to drive significant demand for fermented chymosin, facilitating innovations in cheese manufacturing processes.
Competitive Landscape
Key players in the fermented chymosin market include Hansen A/S, Koninklijke DSM N.V., Maysa Gida, Mayasan AS, and Nelson-Jameson, among others. These companies are focusing on strategic initiatives such as product innovation, expansion through acquisitions, and partnerships to strengthen their market position. For instance, DSM has dedicated resources to address global food challenges, emphasizing sustainable and innovative solutions in food production.
Key Segments Profiled in the Fermented Chymosin Market Survey
By Form:
Liquid
Granules
By End Use:
Food Processing
Pharmaceutical Industry
Foodservice/HoReCa (Hotels/Restaurants/Café)
Household
By Sales Channel:
Direct Sales
Indirect Sales
Hypermarkets/Supermarkets
Wholesalers
Specialty Stores
Online Retailers
By Region:
North America
Latin America
Western Europe
Eastern Europe
Asia Pacific
Japan
Middle East and Africa
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global egg white cubes market is anticipated to create lucrative growth opportunities over the assessment period by registering a CAGR of 4.2% from 2022 to 2032. The global market was valued at US$ 296.3 Million in 2022 and is expected to surpass a valuation of US$ 541.7 Million in 2032. The growth in the market is attributed to the increasing usage of egg protein within the sports nutrition and bakery industries. Rising health consciousness among consumers is likely to augment sales of egg white cubes in the upcoming years. The surging development of egg protein powder with various flavors, such as strawberry, vanilla, and chocolate is a major factor that is set to push the global market.
Egg-white cubes are known to be innovative food products that allow people to cook several dishes in numerous types of ways, depending upon their taste requirements. In addition to that, these cubes do not contain a fishy odor which is why they can efficiently be used in a wide range of food preparations. Furthermore, egg white cubes are known for low-calorie content and zero cholesterol. These are often included in the daily diets of people. . The demand for egg white cubes is anticipated to surge at a rapid pace owing to their ability to provide amino acids that human bodies cannot produce.
Egg white cubes are gaining significant traction throughout the sports nutrition sector since they comprise high amounts of protein. Propelling the number of health-conscious consumers in both developed and developing countries is a crucial factor that is set to aid growth. Moreover, the launch of novel egg protein products, including health supplements to complement the paleo diet of athletes and health-conscious consumers is another factor that would push sales. Egg white cubes also help in increasing an individual’s muscle gain and initiating weight loss.
Key Takeaways
The rising inclination of consumers toward product labels to get a clear picture of the quality and quantity of fats, nutrients, sugars, and several other ingredients utilized in packaged food items is predicted to bolster growth in the global market.
Manufacturers these days are focusing on utilizing egg protein in both low in fat and nutritious items. Furthermore, the presence of one or more nutrients comprising riboflavin or vitamin D in egg white cubes can appeal to today’s health-conscious consumers.
The creation of ample marketing scope for key players within the market is expected to boost growth over the assessment period. Furthermore, the launch of additive-free and natural egg white cubes by key players to satiate the needs of the sports nutrition sector is also expected to drive growth.
Egg whites offer less choline, which is an essential nutrient required for efficient fat metabolism and cell communication. Whole eggs offer about 35% of the daily choline requirements, while egg whites provide only 2.7% milligrams of choline, which is less than 1% of the recommended regular intake.
Egg whites are anticipated to deliver a small number of essential minerals. The whole egg is expected to provide milligrams of iron, whereas an egg white offers only 0.03 milligrams of iron. Additionally, egg whites lack vitamin B-12 which is otherwise found in whole eggs. Spurred by the aforementioned disadvantages, sales of egg white cubes may decline in the upcoming years.
The global egg white cubes market is highly competitive and fragmented in nature. Attributing to the presence of various large and small-scale companies, the growth of the market is significant over the assessment period. The majority of the prominent companies are focusing on strengthening their presence by engaging in mergers and acquisitions. Some of the other companies are striving to establish partnerships with start-up players to create novel products and gain a competitive edge.
Key Companies Profiled
SKM
Copain
Ovo Fit Eiprodukte
Munax
Key Segments Profiled in the Egg White Cubes Industry Survey
By Distribution Channel:
Hypermarkets & Supermarkets
Online Channel
Indirect Sales
Convenience Stores
Departmental Stores
By Region:
North America
Latin America
Western Europe
Eastern Europe
APEJ
Japan
Middle East and Africa
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
 The global