Global Mini Cranes Market Poised for Significant Growth: Projected to Exceed USD 761 Million by 2033 at a 6.0% CAGR

As per Future Market Insights (FMI), the global mini cranes market value is expected to rise from USD 422.2 million in 2023 to USD 761 million by 2033. Global sales of mini cranes between 2023 and 2033 are projected to rise at a robust CAGR of 6%.

Mini cranes are becoming necessary as a result of the growing construction sector and the rise of urbanization. These cranes provide a versatile solution to material handling problems faced by various sectors.

Growth in the global mini cranes industry is driven by several factors. This includes the quick development of emerging nations and the increasing need for versatile material handling equipment in the construction sector.

Mini cranes are capable of moving and lifting objects in hard-to-access areas. This makes them attractive to end users such as the construction sector. These cranes come with various attachments and accessories, such as different types of hooks, slings, and grabs, allowing them to handle a wide range of materials and tasks.

Mini cranes typically use electric or battery-powered systems, resulting in reduced noise pollution and lower emissions compared to traditional diesel-powered cranes. This eco-friendly approach aligns with sustainable construction practices and regulations, contributing to a greener and more sustainable construction industry.

Key Takeaways from the Global Mini Cranes Market:

  • Global mini crane sales are anticipated to surge at 0% CAGR during the assessment period.
  • Based on type, spider cranes segment is set to exhibit a CAGR of 3% through 2033.
  • By end-use sector, construction segment is expected to progress at 1% from 2023 to 2033.
  • The United States mini cranes market is forecast to reach US$ 73.2 million by 2033.
  • The United Kingdom market is poised to exhibit a CAGR of 0% through 2033.
  • Mini cranes demand in China is expected to rise at 6% CAGR over the projection period.
  • The mini cranes industry in Japan is predicted to reach a valuation of USD 37.6 million by 2033.
  • South Korea mini cranes industry is forecast to thrive at 1% CAGR during the forecast period.

Leading Key Players:

  • Jekko SRL
  • MAEDA SEISAKUSHO CO., Ltd.
  • UNIC-Furukawa Company Ltd.
  • Manitex International, Inc. (Valla)
  • Hoeflon International B.V.
  • Linamar
  • Microcranes, Inc.
  • R&B Engineering

Recent developments:

  • In 2023, Jekko displayed its novel material handling products including the SPX328 crawler crane model and JF235 bi-energy powered model, at the CONEXPO 2023.

Browse Full Report Here:

Global Mini Cranes Market Segmentation:

By Lifting Capacity:

  • Up to 1 ton
  • 1 to 1.8 ton
  • 2 to 2.4 ton
  • 2.5 to 4.9 ton
  • 5 to 10 ton
  • 11 to 22 ton

By Type:

  • Spider Crane
  • Crawler Crane
    • Articulated
    • Telescopic
  • Pick and Carry Cranes

By Operation:

  • Fuel Operated
  • Battery Operated

By End Use Sector:

  • Industrial
    • Foundries
    • Power Plants
    • Others
  • Railway Depots
    • Construction
    • Residential & Commercial
    • Industrial
  • Civic Infrastructure
  • Facility Management
    • Commercial
    • Industrial
  • Marine
  • Timber and Lumber
  • Material handling and logistics

By Ownership:

  • Direct Owned
    • OEM Sales
    • Dealership Sales
  • Rented

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • The Middle East & Africa

About Us

Future Market Insights, Inc. (ESOMAR certified, Stevie Award – recipient market research organization and a member of Greater New York Chamber of Commerce) provides in-depth insights into governing factors elevating the demand in the market. It discloses opportunities that will favour the market growth in various segments on the basis of Source, Application, Sales Channel and End Use over the next 10-years.

Contact:

Future Market Insights Inc.
Christiana Corporate,
200 Continental Drive,
Suite 401, Newark,
Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: sales@futuremarketinsights.com
Large Synchronous Motor Market Gains Momentum, Anticipated Value of USD 11.4 Billion by 2033, With a 5.5% CAGR Growth

The Large Synchronous Motor Market report, unveiled by Future Market Insights—an ESOMAR Certified Market Research and Consulting Firm—presents invaluable insights and meticulous analysis of the Large Synchronous Motor market. Encompassing the research’s scope and essence, this report scrupulously examines the driving factors, market size, and predictive data for Large Synchronous Motor. It furnishes intricate revenue and shipment segmentations, accompanied by a decade-long projection up to 2033. Additionally, the document evaluates key industry players, their market distribution, the competitive scenario, and regional perspectives.

The Large Synchronous Motor Market is poised for substantial expansion in the forthcoming years, driven by a surge in demand for energy-efficient solutions. These motors are widely acknowledged for their exceptional precision at consistent speeds, positioning them as the preferred choice in the industrial sector. As industries actively seek reliable and efficient power solutions, large synchronous motors emerge as a compelling option to meet the growing demands. Their capacity to maintain a stable velocity while delivering superior performance renders them highly suitable for diverse industrial applications.

According to projections, the global large synchronous motor market is expected to attain a valuation of USD 6.5 billion by 2022. Industry players are propelling market growth through the development of technologically advanced large synchronous motors equipped with high-power and high-speed compressors. The market is anticipated to achieve a value of USD 11.4 billion by 2033, with a projected compound annual growth rate (CAGR) of 5.5% from 2023 to 2033. It is estimated to generate revenue of USD 6.7 billion by 2023. This trajectory underscores the increasing significance of large synchronous motors as a pivotal component in addressing the evolving needs of industries for robust and efficient power solutions.

The market is poised for significant expansion over the forecast period, driven by the capacity of large synchronous motors to address the growing need for energy-efficient solutions. Their exceptional precision at consistent speeds establishes them as key assets in the industrial sector. Moreover, the substantial increase in demand for highly efficient machine control motors emerges as a crucial factor propelling the global market for large synchronous motors. These motors are integral to diverse industries, encompassing mining, water treatment, and separation units, among others.

Key Takeaways from the Market Study

  • From 2018 to 2022, the market demand expanded at a CAGR of 4.3%
  • Based on the application, the compressor segment to accumulate a market share of 42.5% in 2023
  • By rated power, the 25 to 40 MW segment dominates the market with a share of 34%
  • North America to emerge as a promising market, capturing nearly 37% of the global market share in 2023
  • Asia Pacific to be an opportunistic market, expected to capture a CAGR of 5.4% during the forecast period.

Competitive Landscape

Prominent players in the large synchronous motors market are ABB, General Electric, WEG, Siemens AG, VEM Group, and Hyundai Electric & Energy System Co Ltd, among others.

Leading players operating in the global large synchronous motor market are focusing on intensive research and development for launching innovative products and services in the market.

Product innovation is the key strategy adopted by market players. Brand consciousness and aggressive marketing by top players however make it challenging for new entrants in this market.

The market players are also emphasizing offering large synchronous motor with high reliability and high performance. The market is benefiting from partnerships with a high focus on innovation.

  • Toshiba Mitsubishi-Electric Industrial Systems Corporation announced that together with Mitsubishi Electric Corporation they have developed an electrical motor-design support system incorporating Mitsubishi Electric’s Maisart®* AI technology to dramatically shorten the time required to produce electrical motor designs that achieve the same performance as conventional design methods deployed manually by skilled engineers.
  • Siemens smart infrastructure added four new devices to its portfolio of Simatic ET 200 SP motor starters, which are used to start electric drivers with power output from 0.1 to 0.4 ampere

Know More about What the Large Synchronous Motor Market Report Covers

Future Market Insights offers an unbiased analysis of the global large synchronous motor market, providing historical data for 2018 to 2022 and forecast statistics from 2023 to 2033.

To understand opportunities in the large synchronous motor market, the market is segmented based on rated power, end-use, and application across five major regions.

Browse Full Report Here:

Key Segments Covered in the Large Synchronous Motor Industry Analysis

By Rated Power:

  • 25 to 40 MW
  • 40 to 60 MW
  • 60 to 80 MW

By Application:

  • Compressor
  • Pump
  • Fans
  • Extruder
  • Mixers
  • Conveyors or Belts
  • Others

By End User:

  • Oil & Gas
  • Metal & Mining
  • Paper & Pulp
  • Chemicals & Petrochemicals
  • Automotive
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • Asia Pacific
  • Middle East and Africa

About Us

Future Market Insights, Inc. (ESOMAR certified, Stevie Award – recipient market research organization and a member of Greater New York Chamber of Commerce) provides in-depth insights into governing factors elevating the demand in the market. It discloses opportunities that will favour the market growth in various segments on the basis of Source, Application, Sales Channel and End Use over the next 10-years.

Contact:

Future Market Insights Inc.
Christiana Corporate,
200 Continental Drive,
Suite 401, Newark,
Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: sales@futuremarketinsights.com
Tritium Light Source Market Poised to Reach USD 8.6 Billion Between 2023 and 2033, with a 2.5% CAGR

The Tritium Light Source Market report, released by Future Market Insights—an ESOMAR Certified Market Research and Consulting Firm—provides invaluable insights and meticulous analysis of the Tritium Light Source market. This comprehensive report thoroughly examines the driving factors, market size, and predictive data pertaining to Tritium Light Source. It offers detailed revenue and shipment segmentations, accompanied by a ten-year projection extending up to 2033. Moreover, the document assesses key industry players, their market distribution, the competitive landscape, and regional perspectives.

The global Tritium Light Source market is poised to attain a substantial valuation of USD 6.6 billion, driven by a consistent supply of advanced Tritium Light Sources that incorporate cutting-edge technologies. The industry is experiencing remarkable growth, with forecasts indicating a projected market value of USD 8.6 billion by 2033. This reflects a Compound Annual Growth Rate (CAGR) of 2.5% from 2023 to 2033, with an anticipated revenue of USD 6.7 billion for the year 2023.

A noteworthy surge in demand for Tritium Light Sources is observed within the military and defense sectors, which are expected to undergo significant expansion in the coming years. Additionally, the increasing emphasis on safety and emergency preparedness across various industries is identified as a key driver for market growth.

The escalating need for reliable and long-lasting light sources across diverse global industries emerges as a pivotal factor stimulating the growing demand for Tritium Light Sources throughout the forecast period. This trend underscores the market’s significance in meeting the evolving requirements of industries worldwide.

The manufacturer is focusing on the development of products in an effective way to prevent discharge and leakage. Also, the manufacturers are providing value-added services to their end-user customers. Technological advances in tritium light source manufacturing drive the demand for tritium light sources globally.

Key Takeaways from the Market Study

  • From 2018 to 2022, the market demand expanded at a CAGR of 2.4%
  • Based on the end-use sector, the defense & aerospace segment to accumulate a market share of 32.5% in 2023
  • By visible color, the green color segment dominates the market with a share of 31.2%
  • North America to emerge as a promising market, capturing nearly 36% of the global market share in 2023
  • Asia Pacific to be an opportunistic market, expected to capture CAGR of 2.1% during the forecast period.

Competitive Landscape

Prominent players in the tritium light source market are Evenlite Inc, Betalight B.V., Cammanga, ITTSAN GTLS, MB Microtech AG, SRB Technologies, Trigalight, and Trijicon among others.

Leading players operating in the global tritium light source market are focusing on intensive research and development for launching innovative products and services in the market.

Product innovation is the key strategy adopted by market players. Brand consciousness and aggressive marketing by top players however make it challenging for new entrants in this market.

The market players are also emphasizing offering tritium light source with high reliability and high performance. The market is benefiting from partnerships with a high focus on innovation.

  • Cammenga is the United States Military’s official compass manufacturer. Tritium Lensatic Compasses have proven themselves repeatedly in almost every kind of environment and situation. Cammenga introduced Tritium Compass 3HCammenga’s.
  • Betalight introduced BETALUX SAFETY SIGNS which are completely independent & maintenance-free. It does not require external power, no additional light source, and batteries.
  • SRB Technology manufactures tritium-based products like exit signs, compasses, and markers. All these are widely used in marine & safety, aerospace, and military.

Know More about What the Tritium Light Source Market Report Covers

Future Market Insights offers an unbiased analysis of the global tritium light source market, providing historical data for 2018 to 2022 and forecast statistics from 2023 to 2033.

To understand opportunities in the tritium light source market, the market is segmented based on visible color, application, end use industry, and region.

Browse Full Report Here:

Key Segments Covered in the Tritium Light Source Industry Analysis

By Visible Light:

  • Green
  • Yellow
  • Orange
  • Red
  • Blue
  • White
  • Purple

By Application:

  • Directional Markers and Navigation Aids
  • Aviation Markers
  • Warning Lights / Markers
  • Firearm Accessories

By End Use Sector:

  • Civil and Commercial
  • Industrial Infrastructure
  • Defence and Aerospace

By Region:

  • North America
  • Latin America
  • Europe
  • Asia Pacific
  • Middle East and Africa

Author By:

Nikhil Kaitwade (Associate Vice President at Future Market Insights, Inc.) has over a decade of experience in market research and business consulting. He has successfully delivered 1500+ client assignments, predominantly in Automotive, Chemicals, Industrial Equipment, Oil & Gas, and Service industries.

His core competency circles around developing research methodology, creating a unique analysis framework, statistical data models for pricing analysis, competition mapping, and market feasibility analysis. His expertise also extends wide and beyond analysis, advising clients on identifying growth potential in established and niche market segments, investment/divestment decisions, and market entry decision-making.

Nikhil holds an MBA degree in Marketing and IT and a Graduate in Mechanical Engineering. Nikhil has authored several publications and quoted in journals like EMS Now, EPR Magazine, and EE Times.

About Us

Future Market Insights, Inc. (ESOMAR certified, Stevie Award – recipient market research organization and a member of Greater New York Chamber of Commerce) provides in-depth insights into governing factors elevating the demand in the market. It discloses opportunities that will favour the market growth in various segments on the basis of Source, Application, Sales Channel and End Use over the next 10-years.

Contact:

Future Market Insights Inc.
Christiana Corporate,
200 Continental Drive,
Suite 401, Newark,
Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: sales@futuremarketinsights.com
Fire Resistant Fabrics Market Insights: Rising at a 6.3% CAGR by 2033, Projected Value of US$ 6.1 Billion

The Fire-Resistant Fabrics Market report, unveiled by Future Market Insights—an ESOMAR Certified Market Research and Consulting Firm—presents invaluable insights and meticulous analysis of the Fire-Resistant Fabrics market. Encompassing the research’s scope and essence, this report scrupulously examines the driving factors, market size, and predictive data for Fire-Resistant Fabrics. It furnishes intricate revenue and shipment segmentations, accompanied by a decade-long projection up to 2033. Additionally, the document evaluates key industry players, their market distribution, the competitive scenario, and regional perspectives.

The Fire-Resistant Fabrics Market is poised for substantial growth, driven by the escalating implementation of stringent safety regulations mandated by governments across diverse sectors, including oil and gas, construction, and manufacturing. These regulations are anticipated to exert a profoundly positive influence on the trajectory of market expansion.

In the year 2023, the global fire-resistant fabrics market is expected to attain a valuation of approximately US$3.3 billion. This growth is primarily propelled by the increasing utilization of these fabrics within the oil and gas industry, further bolstering market expansion. It is estimated that by the year 2033, the market will have achieved a valuation of around US$6.1 billion, reflecting a commendable CAGR of 6.3% from 2023 to 2033.

The demand for fire-resistant fabrics is notably surging within the industrial sector due to the imposition of stricter safety regulations, heightened awareness concerning fire hazards, and an enhanced emphasis on improving worker safety standards. These specialized fabrics are intricately designed to provide comprehensive protection by effectively limiting the ignition and spread of flames, mitigating heat transfer, and minimizing the risk of burn injuries.

Furthermore, the increasing stringency of government safety regulations across various industries, encompassing the prominent sectors of oil and gas, construction, and manufacturing, is expected to play a pivotal role in bolstering the growth trajectory of the fire-resistant fabrics market.

The heightened awareness surrounding the potential risks and hazards associated with fires, whether in industrial or non-industrial contexts, has significantly underscored the importance of prioritizing fire safety measures. One notable facet of this increased emphasis is the widespread utilization of fire-resistant fabrics. These specialized textiles find application across various sectors, encompassing personal protection, interior furnishings, transportation, and numerous other domains.

A conspicuous trend driving the market’s growth is the expanded adoption of fire-resistant apparel, particularly in high-risk activities such as oil and gas exploration, mining, and chemical processing. This surge in demand reflects both industries and individuals recognizing the paramount significance of fire safety in safeguarding lives and property.

In the context of North America, the region is poised to experience substantial growth in the fire-resistant fabrics market during the forecast period. This growth can be primarily attributed to the presence of stringent safety regulations within the industrial sectors, which prioritize the well-being of workers. Moreover, the persistent focus on technological innovation plays a pivotal role in fostering the steady development of the fire-resistant fabrics market in North America.

Concurrently, the robust demand emanating from manufacturing activities in the Asia Pacific region significantly contributes to the overall expansion of the fire-resistant fabrics market. The accelerated pace of industrialization witnessed in developing economies like China and India is expected to further propel market growth in the foreseeable future.

Here are the key takeaways from the market study presented in a more professional format:

  • Steady Demand Growth: The market demonstrated consistent demand growth between 2018 and 2022, achieving a noteworthy Compound Annual Growth Rate (CAGR) of 8.0%.
  • Segment Analysis – Type: Within the market, the treated segment exhibited a notable CAGR of 6.2%, showcasing its sustained relevance and appeal to consumers.
  • Segment Analysis – Application: The apparel segment is poised for steady expansion with a projected CAGR of 6.0% throughout the forecast period, indicating sustained interest and demand within this market sector.
  • Regional Prominence – North America: North America emerges as a promising market, with a substantial CAGR of 6.2%, signifying robust potential for growth and market development in this region.
  • Regional Opportunity – Asia Pacific: Asia Pacific represents an opportune market with a projected CAGR of 6.2% during the forecast period, underscoring the attractiveness of this region for market players seeking to expand their presence and offerings.

 “Growing technological innovation and increased awareness in the industrial sector are expected to drive the market in the forecast period. The increasing demand from defense & public safety services sector globally is projected to play a vital role in strengthening the market”.

Competitive landscape

Prominent players in the fire-resistant fabrics market are DuPont de Nemours, Inc.; Arvind Ltd.; Draper Knitting Company; BGF Industries, Inc.; Agru America, Inc.;

among others.

  • Solvay S.A. a global chemical company produces a range of specialty polymers and fibers, including fire-resistant fabrics. Their fire-resistant fabric brand, Rhovea®, offers high thermal protection and flame resistance. It finds applications in personal protective equipment (PPE) for firefighters, military personnel, and industrial workers.
  • Milliken & Company is a diversified industrial manufacturer that produces a wide range of textiles, including fire-resistant fabrics. They offer various fire-resistant fabric solutions that provide thermal protection and meet industry standards for flame resistance. Their fabrics are used in industries such as oil and gas, welding, and firefighting.

Know More about What the Fire Resistant Fabrics Market Report Covers

Future Market Insights offers an unbiased analysis of the global fire-resistant fabrics market, providing historical data for 2018 to 2022 and forecast statistics from 2023 to 2033.

To understand opportunities in the fire-resistant fabrics market, the market is segmented based on type, end-use, and application across five major regions.

Browse Full Report Here:

Key Segments Covered in the Fire Resistant Fabrics Industry Analysis

By Type:

  • Treated
  • Inherent

By Application:

  • Apparel
  • Non-Apparel

By End-Use:

  • Industrial
  • Defense & public safety Services
  • Transportation
  • Others

By Region:

  • North American
  • Latin America
  • Europe
  • Asia Pacific
  • Middle East and Africa

About Us

Future Market Insights, Inc. (ESOMAR certified, Stevie Award – recipient market research organization and a member of Greater New York Chamber of Commerce) provides in-depth insights into governing factors elevating the demand in the market. It discloses opportunities that will favour the market growth in various segments on the basis of Source, Application, Sales Channel and End Use over the next 10-years.

Contact:

Future Market Insights Inc.
Christiana Corporate,
200 Continental Drive,
Suite 401, Newark,
Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: sales@futuremarketinsights.com
Dual-Axis Solar Trackers Market Targets a Valuation of US$ 24.8 Billion by 2033, Driven by a Robust 14.8% CAGR

The Dual Axis Solar Trackers Market report, unveiled by Future Market Insights—an ESOMAR Certified Market Research and Consulting Firm—presents invaluable insights and meticulous analysis of the Dual Axis Solar Trackers market. Encompassing the research’s scope and essence, this report scrupulously examines the driving factors, market size, and predictive data for Dual Axis Solar Trackers. It furnishes intricate revenue and shipment segmentations, accompanied by a decade-long projection up to 2033. Additionally, the document evaluates key industry players, their market distribution, the competitive scenario, and regional perspectives.

The Dual Axis Solar Trackers Market is currently experiencing substantial growth, driven by increased government emphasis on renewable energy sources and the growing adoption of solar photovoltaic (PV) installations. Governments worldwide are redirecting their focus toward sustainable energy solutions, leading to a significant rise in demand for dual-axis solar trackers. These advanced tracking systems effectively enhance energy generation by dynamically aligning solar panels with the precise path of the sun, thereby optimizing solar exposure throughout the day.

Projections indicate that the global dual-axis solar tracker market is poised to reach a valuation of approximately US$ 6.3 billion by 2023. This growth can be attributed to the growing awareness of renewable energy sources, serving as a key driver for market expansion. Furthermore, estimations suggest that the market will achieve a total value of US$ 24.8 billion by 2033, reflecting a noteworthy compound annual growth rate (CAGR) of 14.8% from 2023 to 2033.

The increasing government focus on renewable energy sources, coupled with the rising deployment of solar PV systems, serves as significant catalysts for the upward trajectory of the dual-axis solar trackers market. Demonstrating their effectiveness, these dual-axis solar trackers are increasingly being embraced in large-scale solar power projects on a global scale. Their ability to yield higher energy output per unit of installed capacity makes them exceptionally well-suited for utility-scale installations and commercial solar farms.

The surge in energy demand has led to an increased need for augmented electricity production. Within this context, the adoption of dual-axis solar trackers is experiencing a significant upswing, especially in extensive solar projects. The increased deployment of these trackers, along with their advanced tracking algorithms, sensor integration, and control mechanisms, has greatly improved their precision and operational efficiency. These technological advancements have also resulted in enhanced reliability, cost efficiency, and seamless integration capabilities for dual-axis solar trackers. This positive trend is expected to drive substantial market growth in the foreseeable future.

The North American region has emerged as a prominent hub for ongoing technological innovation, playing a key role in the development of dual-axis solar tracker systems. These innovations have been instrumental in boosting energy output levels and strengthening system reliability. Consequently, dual-axis trackers have become an increasingly attractive option for solar projects in the region.

Key Takeaways:

  • The period from 2018 to 2022 experienced a substantial surge in demand for dual-axis solar trackers, demonstrating an impressive Compound Annual Growth Rate (CAGR) of 8.8%.
  • When categorized by type, the single-axis segment exhibited remarkable growth, contributing significantly to a CAGR of 14.4%.
  • An in-depth analysis based on application reveals that the utility segment is poised for substantial expansion, with a projected CAGR of 14.1% throughout the forecast duration.
  • The North American region is strategically positioned to emerge as a promising market for dual-axis solar trackers, boasting an anticipated CAGR of 14.7%.
  • Projections indicate that the dual-axis solar tracker industry in the United Kingdom is progressing steadily towards a significant milestone, expected to reach a valuation of US$ 1 billion by the year 2033.
  • Meanwhile, the dual-axis solar trackers market in South Korea is predicted to achieve substantial market revenue of US$ 1.3 billion by 2033.
  • The Asia Pacific region presents itself as an opportunistic market with an estimated CAGR of 14.6% during the projected forecast period.

 “Increased power demand globally and increasing technological innovation are expected to drive the market in the forecast period. The supportive government policies and increased use of renewable energy sources play a vital role in strengthening the market” – comments a lead analyst at FMI.

Competitive landscape:

  • Soitec,
  • First Solar, Inc.,
  • Reutech Radar Systems,
  • Targray Technology International Inc.
  • Trina Solar Co. Ltd.

among others are some of the market players operating in the dual-axis solar tracker market.

  • SunPower: Renowned solar energy enterprise with a notable presence in the dual-axis solar tracker sector.
    • Offers sophisticated dual-axis trackers seamlessly integrated with its premium high-efficiency solar panels.
    • Tracker systems meticulously engineered to optimize energy yield and elevate overall system efficiency.
    • SunPower’s foray into the dual-axis solar tracker domain bolsters the industry with proven expertise and credibility.
  • Arctech Solar: Prominent global manufacturer specializing in solar tracking and racking systems.
    • Recognized for its provision of dual-axis trackers celebrated for exceptional precision and dependable performance.
    • Extensively engaged in large-scale solar ventures across the globe, delivering tailored dual-axis tracking solutions for maximal energy production.

Know More about this Market Report:

Future Market Insights offers an unbiased analysis of the global dual-axis solar trackers market, providing historical data for 2018 to 2022 and forecast statistics from 2023 to 2033.

To understand opportunities in the dual-axis solar trackers market, the market is segmented based on type and application across five major regions.

Browse Full Report Here:

Key Segments:

By Type:

  • Single Axis
  • Dual Axis

By Application:

  • Utility
  • Non-Utility

By Region:

  • North American
  • Latin America
  • Europe
  • Asia Pacific
  • Middle East and Africa

Explore this report from different publication

Dual axis solar tracker Market@ https://www.globenewswire.com/en/news-release/2023/06/08/2684474/0/en/The-Dual-Axis-Solar-Tracker-Market-is-projected-to-reach-a-valuation-of-US-24-8-Billion-by-2033-exhibiting-a-significant-CAGR-of-14-8-from-2023-to-2033-Future-Market-Insights.html

About Future Market Insights (FMI):

Future Market Insights, Inc. (ESOMAR certified, Stevie Award – recipient market research organization and a member of Greater New York Chamber of Commerce) provides in-depth insights into governing factors elevating the demand in the market. It discloses opportunities that will favour the market growth in various segments on the basis of Source, Application, Sales Channel and End Use over the next 10 years.

Contact Us:

Future Market Insights, Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-845-579-5705
LinkedIn | Twitter | Blogs | YouTube
For Sales Enquiries: sales@futuremarketinsights.com

Water Automation and Instrumentation Market Growth: Anticipated 8.1% CAGR with a Projected Value of USD 48 Billion by 2033

A comprehensive analysis by Future Market Insights (FMI), a well-respected market research and consulting firm certified by ESCOMAR, anticipates significant growth in the water automation and instrumentation market. According to the report, the market is poised to reach an impressive valuation of $22 billion by the conclusion of 2023. This remarkable growth is attributed to a substantial transformation in water treatment processes, with a pronounced shift towards automation and instrumentation. These advancements are revolutionizing the industry by facilitating advanced monitoring, control, and optimization capabilities.

Global Water Quality Enhancement through Automation

The water automation and instrumentation sector plays a crucial role in improving water quality across different industries. By incorporating advanced sensors, flow meters, and analyzers, it enables the continuous monitoring of water quality parameters, giving operators valuable information to make informed choices. This technological advancement enables accurate management of chemical dosing, treatment procedures, and the optimization of system efficiency.

Robust Growth Trajectory

According to research conducted by the FMI (Futuristic Market Insights), the water automation and instrumentation market is projected to experience a remarkable Compound Annual Growth Rate (CAGR) of 8.1% from 2023 to 2033. This impressive growth can be attributed to the rising adoption of smart grid technologies in the water sector, which closely parallels the successful transformation seen in the electricity industry. These cutting-edge systems leverage the Internet of Things (IoT) and advanced analytics to enhance various aspects of water management, including optimizing water distribution, detecting and addressing leaks, ensuring water quality, and facilitating efficient water consumption management through the implementation of smart meters.

Global Reach and Impact

Over the last five years, the global water automation and instrumentation market displayed a commendable CAGR of 11.5% (2018-2022). Future Market Insights’ research underscores the critical role advanced instrumentation plays in simplifying water quality monitoring. Swift identification of contaminants, pathogens, and emerging pollutants is facilitated by these instruments, enabling prompt responses to safeguard public health.

Enhanced Aquatic Environment Management

Real-time water quality data is poised to revolutionize the management of aquatic environments and potable water safety. Centralized monitoring and control of water systems, facilitated by remote automation, will streamline operations, reduce emergency response times, and elevate overall system performance. This will be particularly significant in regions where water resource management is a pressing concern.

Technological Advancements and Wastewater Treatment Drive Market Growth

Sensors are the cornerstone of water automation and instrumentation, and recent advancements have yielded sensors capable of accurately measuring parameters such as pH, conductivity, dissolved oxygen, flow rates, pressure, and level. These sensors enable more effective monitoring and control of water systems. Additionally, the rising prominence of big data analytics is expected to transform water management by harnessing insights from vast data streams generated by sensors.

Key Players Driving Innovation

Leading industry players have devoted substantial resources to research and development, resulting in the creation of groundbreaking products. Notable collaborations and mergers within the market have led to the expansion of product portfolios, strengthening industry leadership.

Key Players:

  • ABB Ltd.
  • Jacobs Engineering Group Inc.
  • Emerson Electric Co.
  • Endress+Hauser AG
  • General Electric
  • Mitsubishi Electric Corp.
  • Pepperl Fuchs
  • Rockwell Automation Inc.

Recent Notable Developments

In June 2023, Ontario-Schneider Electric, a global leader in energy management and automation solutions, unveiled EcoStruxureTM Automation Expert V23.0. A trailblazing software-centered industrial automation system, EcoStruxureTM Automation Expert V23.0 empowers industrial automation professionals to decouple software from hardware, revolutionizing system design, operation, and maintenance.

Similarly, ABB and China Telecom jointly established a lab for digitalization and industrial IoT in June 2023. ABB’s collaboration with E Surfing IoT in the smart water networks domain yielded exceptional results, boosting data quality, operational efficiency, and energy conservation by an impressive 20%.

Browse Full Report Here:

Water Automation and Instrumentation Market by Category

By Process Stage:

  • Collection of Water
  • Treatment of Water
  • Distribution of Water
  • Dead End System
  • Radial System
  • Grid System
  • Ring System
  • Method of Water Distribution

By Automation Technology:

  • Distributed Control System – DCS
  • Supervisory Control and Data Acquisition – SCADA
  • Programmable Logic Controller – PLC
  • Human Machine Interface – HMI
  • Manufacturing Execution System – MES
  • Identity & Access Management – IAM
  • Laboratory Information Management System – LIMS

By Instrumentation:

  • Pressure Transmitter
  • Level Transmitter
  • Hydrostatic Operating Principle
  • Ultrasonic Operating Principle
  • Capacitive Operation
  • Guided Wave Radar
  • Electromagnetic Flow Meters
  • Sludge Density Measurement
  • Gas and Liquid Analyzer
  • Leakage Detection Systems
  • Control Valves
  • High and Low AC Drives
  • Others

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, Stevie Award – recipient market research organization and a member of Greater New York Chamber of Commerce) provides in-depth insights into governing factors elevating the demand in the market. It discloses opportunities that will favor the market growth in various segments on the basis of Source, Application, Sales Channel and End Use over the next 10-years.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-845-579-5705
LinkedIn| Twitter| Blogs | YouTube
For Sales Enquiries: sales@futuremarketinsights.com

Pediatric Vaccine Market Set for Robust Growth, Projected to Reach USD 184,706.7 Million by 2033 at a 13.1% of CAGR

Pediatric Vaccine Market

The pediatric vaccine market is poised for extraordinary expansion, with a current valuation of USD 54,130.1 million in 2023. According to recent projections, the market is expected to grow at a remarkable Compound Annual Growth Rate (CAGR) of 13.1%, reaching an estimated USD 184,706.7 million by 2033.

The paediatric vaccine market is a billion-dollar market accounting for a substantial proportion of healthcare expenditure in recent times. The paediatric vaccine market is segmented according to indication, technology and vaccine type. According to the indication, the paediatric vaccine market is sub-segmented into pneumococcal, DTP, rotavirus, influenza, meningococcal, hepatitis B, Hib, MMR and polio. According to technology, the market is further segmented into live or attenuated, inactivated or killed, toxoid, conjugate, subunit and recombinant vaccines. By vaccine type, the global paediatric vaccine market is segmented into monovalent and multivalent vaccines.

A slew of routine immunisation initiatives rolled out by the government and private agencies have broadened the market for paediatric vaccines. A new wave of funds pumped into the market by different government and private players to curb the rise of child deaths across the globe has also opened a new window of opportunity for the paediatric vaccine market. As per the report of WHO (World Health Organization), global spending on immunisation soared from US$21.4 to US$26.9 per infant in 2014. The massive economic boom in some regions of the world is expediting the growth of the paediatric vaccine market.

Key Trends Influencing the Paediatric Vaccines Market:

  • By indication, the pneumococcal segment accounted for a higher revenue share in global paediatric vaccines as compared to other product segments. The pneumococcal segment is expected to reach a value of US$ 31.58 Bn by 2026, reflecting a CAGR of 14.4% over the forecast period. The growth of the pneumococcal segment is attributed to the increasing incidence of infectious diseases.
  • In terms of revenue, the Hib vaccine segment is the second most growing segment and is expected to reach a value of US$ 13.49 Bn by 2026, growing at a CAGR of 13.4%. The hepatitis B and meningococcal segments are expected to show double-digit CAGR growth in the forecast period contributing to the growth of the global paediatric vaccine market.
  • By technology, the conjugate segment accounted for the highest revenue share in the global paediatric vaccine market as compared to the live or attenuated segment. The conjugate segment is expected to reach a value of US$ 32.09 Bn by 2026, reflecting a CAGR of 14.8% over the forecast period. This is expected to be closely followed by the growth of pneumococcal and meningococcal vaccines in this segment
  • By end user, institutional health centres account for higher demand for the paediatric vaccine as compared to other end-user segments such as hospital pharmacies and retail pharmacies. The strong growth in institutional health centres can be attributed to increasing government interventions in immunisation programs to improve vaccine coverage. Institutional health centres are expected to register the highest CAGR of 13.8% over the forecast period.

Regional analysis

By region, North America is dominating the global paediatric vaccine market due to improved healthcare infrastructure in this region. The North American paediatric vaccine market is expected to be valued at US$ 20.15 Bn by 2026 growing at a CAGR of 11.0%. In addition to North America, demand for paediatric vaccines has been significantly growing in Western Europe and APEJ. APEJ is expected to grow at a CAGR of 14.9% over the forecast period and is expected to dominate the market by 2026 by generating revenue of US$ 22.69 Bn and revenues in Western Europe are anticipated to grow by 11.2%. Middle East and Africa are expected to grow at a CAGR of 12.6% and this growth is anticipated by growth government intervention for immunisation by carrying out national-level immunisation campaigns and also disease-specific immunisation campaigns.

Key players in the global paediatric vaccine market include

  • Indian Immunologicals,
  • GlaaxoSmithKline Plc.,
  • Pfizer Inc.,
  • Sanofi, Merck & Co. Inc.,
  • Panacea Biotec,
  • Zydus Cadila,
  • Emergent BioSolutions Inc.,
  • Serum Institute of India Pvt. Ltd.,
  • Bharat Biotech.

Key players in the field, for instance, attribute the growth of the paediatric vaccine market to the development in the research in February 2016, GSK submitted a US regulatory submission for expanding the indication of FLuLaval Quadrivalent, an influenza vaccine, for infants more than 6 months. These developments will boost the growth of the global paediatric vaccine market.

A Full Report – Overview

Market Segmentation

Technology

  • Live or Attenuated Vaccine
  • Inactivated or Killed Vaccine
  • Toxoid Vaccine
  • Conjugate Vaccine
  • Subunit Vaccine
  • Recombinant Vector Vaccine

Indication

  • Pneumococcal Conjugate Vaccine
  • DTP Vaccine
  • Influenza
  • Meningococcal Vaccine
  • Polio Vaccine
  • Rotavirus Vaccine
  • MMR Vaccine
  • Varicella Virus Vaccine

End User

  • Hospital Pharmacies
  • Retail Pharmacies
  • Institutional Health Centres

Vaccine Type

  • Monovalent Vaccines
  • Multivalent Vaccines

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI is the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Portable Oxygen Concentrator Market to Reach USD 4.3 Billion by 2034, Driven by 6.7% CAGR

Portable Oxygen Concentrator Market

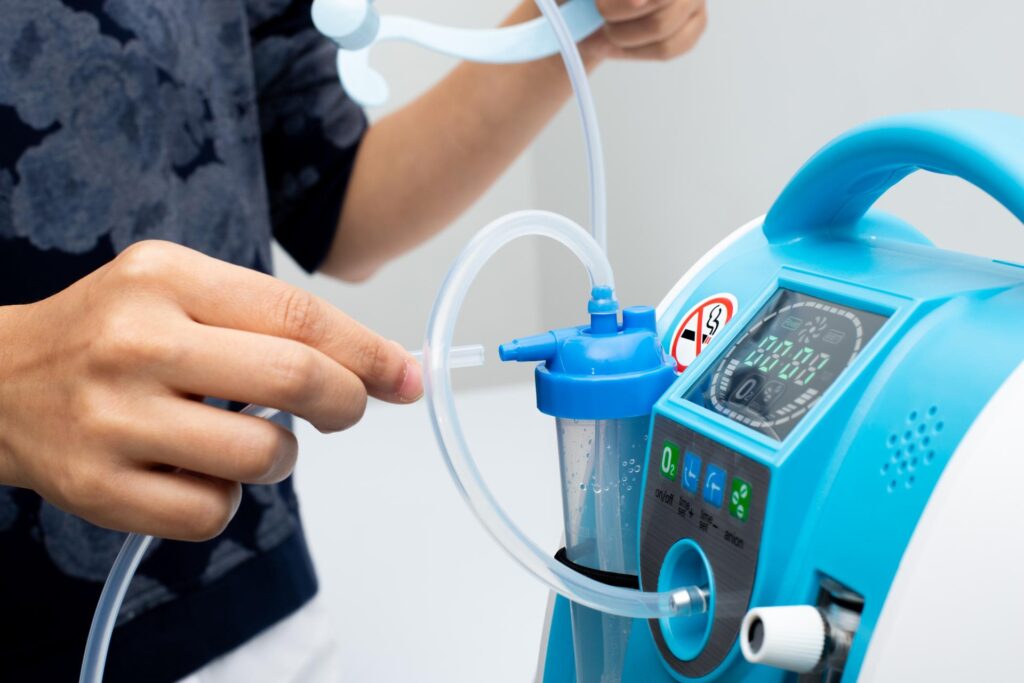
The global portable oxygen concentrator market is on a robust growth path, with projections indicating the market will achieve a value of USD 2.2 billion by the end of 2024. Looking ahead, the market is expected to more than double, reaching an impressive USD 4.3 billion by 2034. This growth reflects a consistent compound annual growth rate (CAGR) of 6.7% over the forecast period.

The increasing demand for portable oxygen concentrators is driven by rising incidences of respiratory disorders, a growing aging population, and advancements in healthcare technology. These devices, which provide patients with greater mobility and improved quality of life, are becoming increasingly essential in both home care and clinical settings.

Manufacturers and stakeholders in the portable oxygen concentrator market can anticipate a promising decade of growth, spurred by innovation and the expanding needs of a health-conscious global population.

Portable oxygen concentrators (POCs) are crucial for providing respiratory support to those with breathing difficulties, enabling them to lead independent and active lives. These lightweight, portable devices are ideal for providing oxygen therapy in a range of settings, including homes, hospitals, and outdoor areas.

Pulse Flow Technology Dominates

Within the portable oxygen concentrator market, the pulse flow segment currently reigns supreme, holding a dominant share of approximately 67.7% (2021). These concentrators deliver bursts of oxygen synchronized with the patient’s inhalation cycle.

Patients can more easily handle portable oxygen concentrators because they are smaller than homecare oxygen concentrators. In addition to patients, mountaineers and tourists utilize POCs when they are in areas with low oxygen levels. The demand for portable oxygen concentrators is predicted to increase due to the growing number of people with respiratory conditions including chronic obstructive pulmonary disease (COPD) around the world.

The World Health Organization (WHO) reports that chronic obstructive pulmonary disease (COPD) is still the third most common cause of death globally, accounting for over 3.23 million fatalities. The disease’s patients frequently need oxygen therapy to raise blood oxygen levels and enhance the oxygen delivered to their organs, therefore portable oxygen concentrator sales are expected to grow at a healthy rate.

Portable oxygen concentrators are also used in the glassblowing industry, skin care products, and non-pressurized airplanes. Over the next ten years, this will increase demand for portable oxygen concentrators.

Similar to this, it is anticipated that the global market for oxygen concentrators would grow as a result of ongoing new product releases and approvals by top manufacturers. Top companies in the portable oxygen concentrators market are launching innovative and effective solutions to capitalize on new prospects.

Competitive Landscape:

In the portable oxygen concentrators market, manufacturers are adopting different strategies such as new product launches, mergers, acquisitions, partnerships, and strengthening of distribution channels to raise their sales and gain a competitive edge in the global market.

Instances of key developmental strategies by the industry players in the portable oxygen concentrators market are given below:

  • In April 2019, Inogen One G5, a light, easy portable oxygen concentrator created to provide oxygen requirements to patients, was launched by Inogen, Inc.
  • In October 2019, Precision Medical announced the launch of its new product, the Live Active Five portable oxygen concentrator. The product was created to help patients with chronic obstructive pulmonary disease and other respiratory diseases.

Key Companies Profiled:

  • Koninklijke Philips N.V.
  • Inogen, Inc
  • Chart Industries, Inc.
  • Resmed, Inc.
  • Invacare Corporation
  • Drive DeVilbiss Healthcare LLC
  • Precision Medical, Inc.
  • Besco Medical Co. Ltd.
  • Oxus America, Inc.
  • Foshan KeyhubElectronic Industries Co. Ltd.
  • O2 Concepts LLC
  • GCE Group

A Full Report – Overview

Key Market Segments Covered in Portable Oxygen Concentrators Industry Research:

By Product:

  • Continuous Flow Portable Oxygen Concentrator
  • Pulse Flow Portable Oxygen Concentrator

By End User:

  • Hospitals
  • Homecare
  • Ambulatory Surgical Centres
  • Travel Agents

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East and Africa (MEA)

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Central Venous Catheter Market to Reach USD 5,314.5 Million by 2033, Anticipated Growth Driven by 5.1% CAGR

Central Venous Catheter
Central Venous Catheter Market

The global central venous catheters market is set to experience substantial growth over the next decade. According to our healthcare analysts, the market size is expected to achieve a valuation of USD 5,314.5 million by 2033, reflecting a compound annual growth rate (CAGR) of 5.1%.

Currently valued at USD 3,238.1 million in 2023, the market’s expansion is attributed to several factors, including advancements in medical technology, increasing prevalence of chronic diseases, and a rising number of surgical procedures that necessitate the use of central venous catheters.

Manufacturers in the central venous catheter industry can anticipate a steady growth trajectory, driven by continuous innovations and an increasing demand for high-quality medical devices. This growth presents lucrative opportunities for stakeholders and underscores the vital role of central venous catheters in modern healthcare.

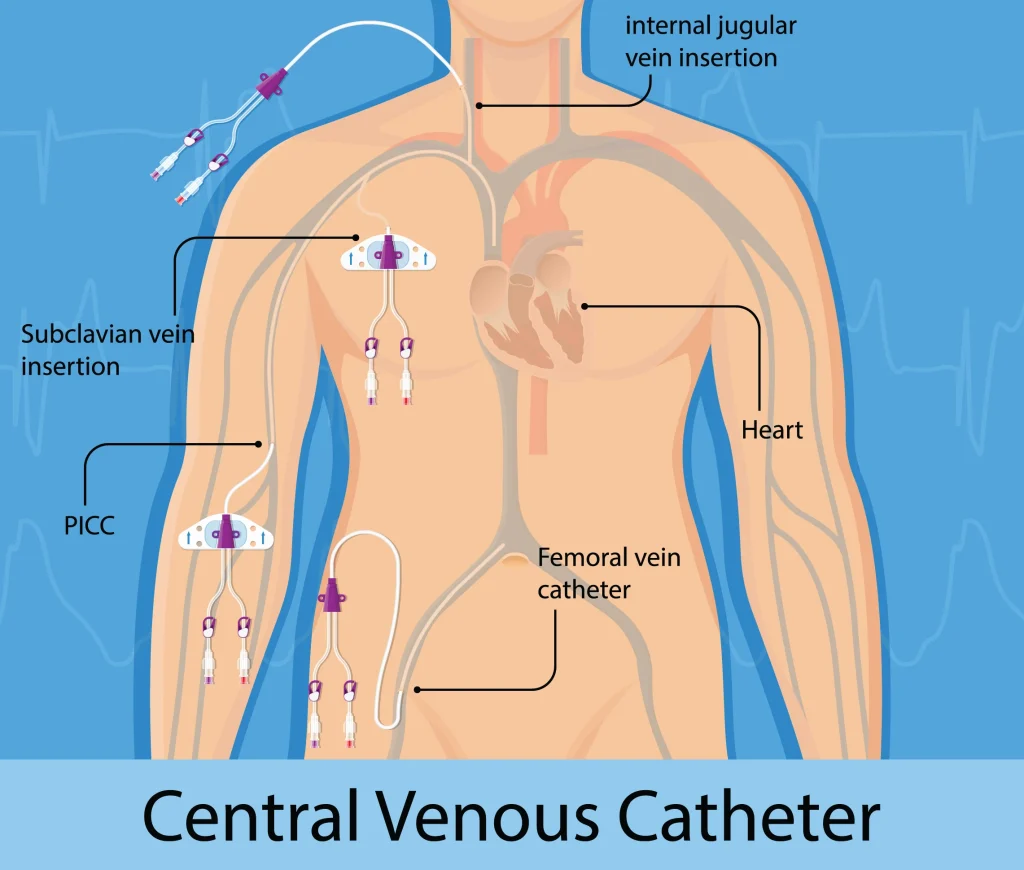
Central venous catheters are vital to medical treatments because they allow for the administration of medications, fluids, and blood products, as well as the measurement of central venous pressure and hemodynamic monitoring. A variety of reasons, such as the growing need for minimally invasive procedures, the increasing incidence of chronic diseases, and advancements in catheter design and material, are projected to drive the growth of the central venous catheter market.

Parenteral nutrition, or intravenous nutrient infusion, is necessary for patients who are unable to acquire enough nutrients through oral or enteral means. This includes those who have had surgery, are receiving treatment for cancer, or have serious gastrointestinal disorders. As more people become aware of the significance of nutrition for both general health and patient rehabilitation, central venous catheters are becoming more and more required to deliver parenteral nutrition therapy.

Key Takeaways from the Central Venous Catheter Market Report:

  • In 2018, the global market size stood at US$ 2,446.9 million.
  • The market size developed at a 4.7% CAGR from 2018 to 2022.
  • In 2022, the global market size stood at US$ 3,074.7 million.
  • In 2022, the non-anti-microbial catheter segment garnered 75.7% of the central venous catheter market shares.
  • In 2022, the double lumen segment gained 63.6% of the central venous catheter market shares.
  • In 2022, the hospitals segment garnered 60.3% of the central venous catheter market shares.
  • The United Kingdom’s central venous catheter market will develop at a CAGR of 9.0% through 2033.
  • Germany’s central venous catheter market will rise at a 3.3% CAGR through 2033.
  • Australia’s central venous catheter market growth will thrive at a 5.1% CAGR through 2033.

Recent Developments Observed by FMI:

  • Coloplast unveiled a novel catheter in the United States in January 2023. The SpeediCath Flex Set catheter is intended for use by those with bladders and urine problems. Triple Action Coating Technology is a feature on all SpeediCath catheters designed to reduce the risk of urethral damage and urinary tract infections (UTIs) for patients with spinal cord injuries (SCI).
  • Braun Medical Inc. (B. Braun), a pioneer in infusion therapy, announced the launch of its new Introcan Safety 2 IV Catheter with one-time blood control in July 2022. The Introcan Safety 2 IV Catheter, the newest invention from B. Braun, makes IV access safer for the clinician by reducing the risk of blood exposure and needlestick accidents.

The CVC market is expected to continue growing as healthcare professionals strive to fulfill patients’ changing expectations and enhance clinical results. Central venous catheters are maturing into essential instruments in contemporary healthcare due to the convergence of cutting-edge technology, patient-centric design, and infection control measures. A dedication to innovation, regulatory compliance, and the search for cost-effective solutions for patients and healthcare systems underpin the market’s growth trajectory,” says an FMI analyst.

Competitive Landscape

A blend of international and regional businesses defines the central venous catheter (CVC) market’s competitive environment. Prominent multinational corporations with sizable market shares include Becton, Dickinson and Company (BD), Teleflex Inc., and C.R. Bard (now acquired by BD). These market leaders use their vast product portfolios, well-developed distribution systems, and strong R&D departments to keep a competitive edge.

Regional players are essential to supplying local markets at the same time. They frequently concentrate on specialized markets, personalization, and affordable fixes while taking into account particular regional tastes and healthcare needs. Global and regional firms frequently use partnerships, mergers, and acquisitions to increase their market share, gain access to new technology, and improve their product offerings.

Recent Developments

  • In January 2023, Coloplast introduced a new catheter in the United States. People with bladder and urine issues are the target market for the SpeediCath Flex Set catheter. All SpeediCath catheters have Triple Action Coating Technology, a choice for people with spinal cord injuries (SCI) and intended to lower the risk of urethral injury and urinary tract infections (UTIs).
  • A pioneer in infusion therapy, B. Braun Medical Inc. (B. Braun) announced the introduction of its new Introcan Safety 2 IV Catheter with one-time blood control in July 2022. The newest innovation from B. Braun makes IV access safer for the clinician by lowering the possibility of needlestick injuries and exposure to blood with the Introcan Safety 2 IV Catheter.

Key Players in the Central Venous Catheter Market:

  • Angio Dynamics
  • C.R. Bard
  • Teleflex Incorporated
  • B. Braun Melsungen AG
  • Kimal Healthcare
  • Come B.V.
  • Medtronic Plc
  • Smiths Medical
  • Vygon (UK) Ltd.
  • Becton, Dickinson, and Company
  • Argon Medical Devices Inc.
  • Boston Scientific Corporation
  • Cook Medical Incorporated
  • Medical Components Inc.
  • Fresenius Kabi AG

Central Venous Catheter Market Segmentation

By Product:

  • Dialysis Catheters
  • Acute Hemodialysis Catheter
  • Chronic Hemodialysis Catheter
  • Peritoneal Dialysis Catheter
  • PICC Catheters
  • Implantable Port
  • CVC Catheters
  • Tunneled Catheters
  • Non-tunneled Catheters

By Property:

  • Anti-microbial Catheter
  • Non-Anti-Microbial Catheter

By Design:

  • Single Lumen
  • Double Lumen
  • Multiple Lumen

By End-user:

  • Hospitals
  • Ambulatory Surgical Centers
  • Dialysis Centers
  • Specialty Clinics
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

North American Vision Care Market Set for Significant Growth, Projected to Reach USD 114,800.8 Million by 2033 at a 5.8% of CAGR

North American Vision Care Market

The demand for vision care products and services in North America is poised for substantial growth, with a projected Compound Annual Growth Rate (CAGR) of 5.8% through 2033. The market, valued at approximately USD 65,326.3 million in 2023, is expected to expand significantly, reaching an estimated USD 114,800.8 million by the end of the forecast period.

This notable growth trajectory reflects increasing consumer awareness about eye health, advancements in vision care technology, and a rising prevalence of vision-related issues. As the population ages and the need for effective eye care solutions intensifies, the demand for comprehensive vision care products and services is set to surge.

One of the key challenges in the industry is the high costs associated with advanced vision care treatments and procedures, limiting accessibility for a significant portion of the population. Additionally, the need for more awareness regarding the importance of regular eye check-ups and preventive measures among specific demographics has contributed to the underutilization of vision care services.

The growing adoption of teleophthalmology services and the integration of digital technologies offer avenues for expanding the reach of vision care services to remote and underserved areas. The rising consumer preference for customized vision care solutions and the increasing focus on value-based care models provide opportunities for market players to innovate and diversify their product offerings.

The integration of artificial intelligence and machine learning in vision diagnostics and treatment planning has revolutionized the sector, enabling more accurate diagnoses and personalized treatment regimens. The rising adoption of wearable vision care devices and the development of advanced nanotechnology-based treatment options are also emerging as prominent trends, shaping the future of the vision care industry in North America.

“The increasing focus on eco-friendly and sustainable vision care products has gained traction, with manufacturers emphasizing the use of biodegradable materials and eco-conscious production processes,” opines Sabyasachi Ghosh, Associate Vice President at Future Market Insights (FMI).

Key Takeaways from the North America Vision Care Market:

  • In 2023, Rx-Lenses dominate the market with a share of 47.1% in the North American vision care industry.
  • Retail Stores establish themselves as the foremost distribution channel in the North American vision care market, securing a significant market share of 61.2% in 2023.
  • Demand for vision care products in Canada exhibits a robust CAGR of 8.2%, expected to persist through 2033.
  • The United States showcases a vigorous demand for vision care products, with an impressive CAGR of 9.9% projected to endure until 2033.

Competition Outlook of North America Vision Care Market:

Key players operating in the vision care industry in North America compete through product diversification, technological advancements, and strategic collaborations to gain a competitive edge and expand their market share. Companies are focusing on enhancing their distribution networks and strengthening their brand presence to stay ahead in the industry.

Many leading players are investing heavily in research and development to introduce innovative products and technologies, catering to consumers’ diverse and evolving needs in the vision care sector. Strategic partnerships and mergers with local and international players enable companies to expand their geographic reach and offer comprehensive solutions to a broader customer base.

New entrants can capitalize on the growing demand for personalized and technologically advanced vision care solutions by introducing innovative products and services tailored to specific consumer segments. Investing in advanced manufacturing capabilities and distribution networks can help new players establish goodwill in the North America vision care industry.

North America Vision Care Market Recent Developments:

  • Alcon (Novartis) launches new PrecisionID technology for LASIK surgery. Alcon, a division of Novartis, has launched a new technology called PrecisionID for LASIK surgery. The new technology uses a laser to create a personalized 3D map of the patient’s eye, which is then used to guide the laser during surgery.
  • CooperVision launches new MiSight contact lenses for myopia control. CooperVision has launched a new line of contact lenses called MiSight. The new contact lenses are designed to slow the progression of myopia, or nearsightedness, in children.
  • Bausch & Lomb launches new ULTRA ONE DAY contact lenses. Bausch & Lomb has launched a new line of daily disposable contact lenses called ULTRA ONE DAY. The new contact lenses are designed to provide all-day comfort and moisture, and they also feature a UV filter to protect the eyes from the sun.
  • Warby Parker launches new Try-On program. Warby Parker, a direct-to-consumer eyewear company, has launched a new Try-On program. The new program allows customers to try on five pairs of glasses for five days at home before they buy.

Key Companies Providing North American Vision Care Market:

  • EssilorLuxottica
  • Johnson & Johnson Vision
  • Alcon (Novartis)
  • CooperVision
  • Bausch & Lomb
  • Warby Parker
  • LensCrafters
  • Visionworks
  • Pearle Vision
  • EyeBuyDirect
  • National Vision

A Full Report – Overview

North America Vision Care Market Key Segments:

By Product Type:

  • Rx-Lenses
  • Frames
  • Contact Lenses
  • Non-Rx Sunglasses
  • Reading Glasses
  • Contact Lens Solutions

By Distribution Channel:

  • Retail Stores
  • E-Commerce
  • Clinics

Author

Sabyasachi Ghosh (Associate Vice President at Future Market Insights, Inc.) holds over 12 years of experience in the Healthcare, Medical Devices, and Pharmaceutical industries. His curious and analytical nature helped him shape his career as a researcher.

Identifying key challenges faced by clients and devising robust, hypothesis-based solutions to empower them with strategic decision-making capabilities come naturally to him. His primary expertise lies in areas such as Market Entry and Expansion Strategy, Feasibility Studies, Competitive Intelligence, and Strategic Transformation.

Holding a degree in Microbiology, Sabyasachi has authored numerous publications and has been cited in journals, including The Journal of mHealth, ITN Online, and Spinal Surgery News.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube