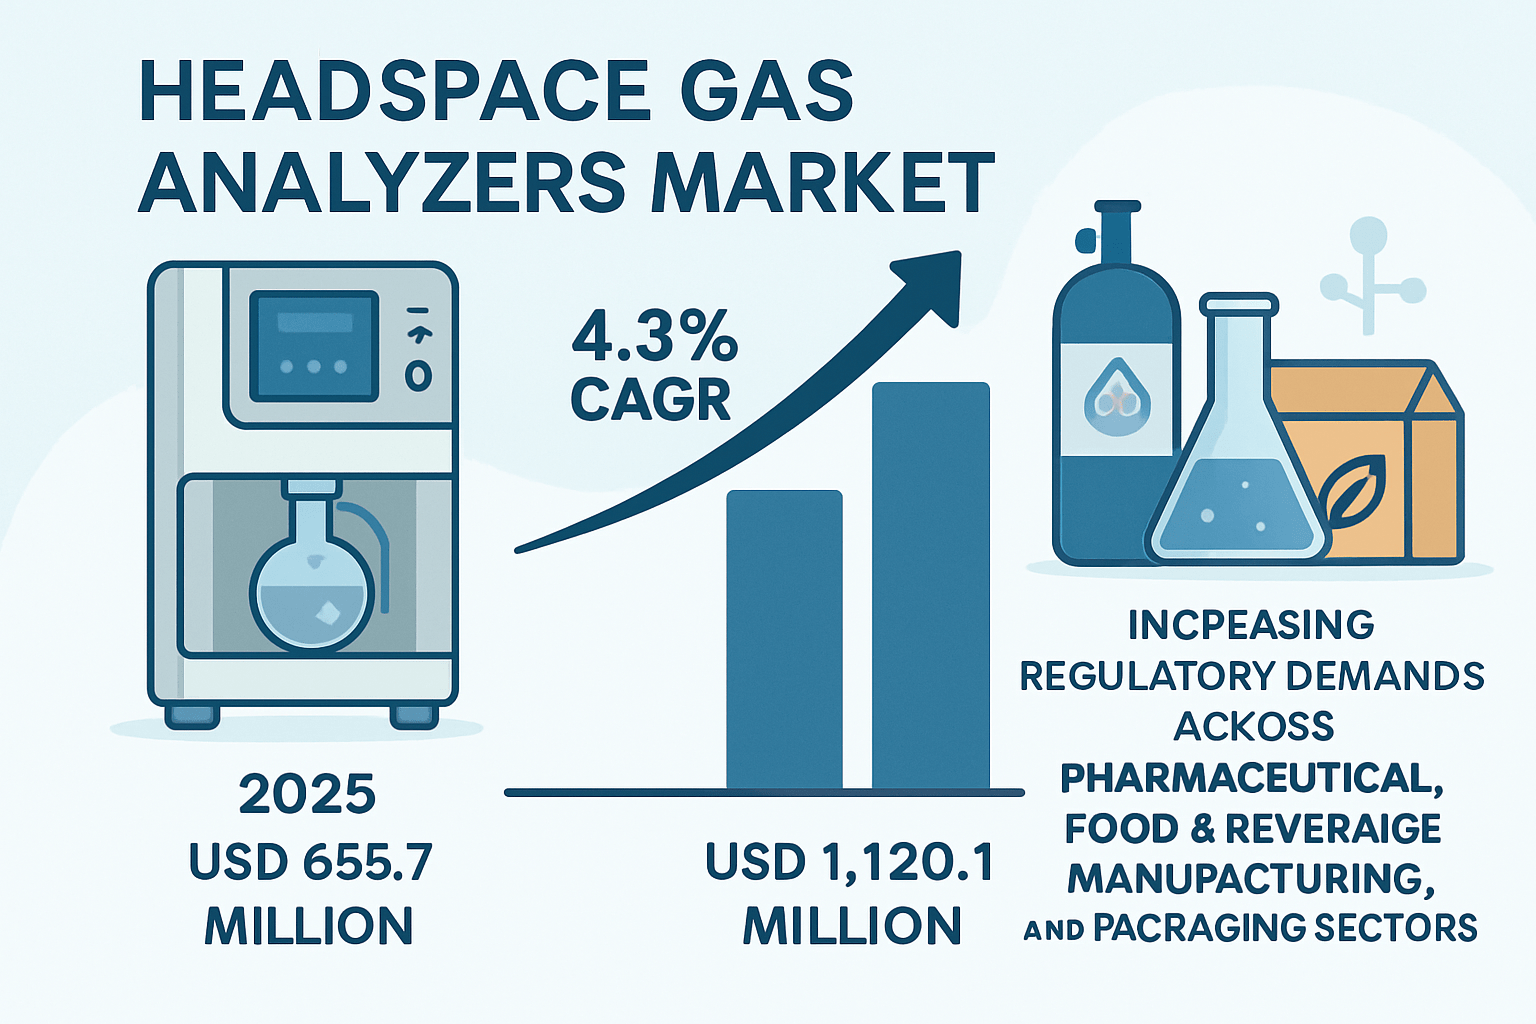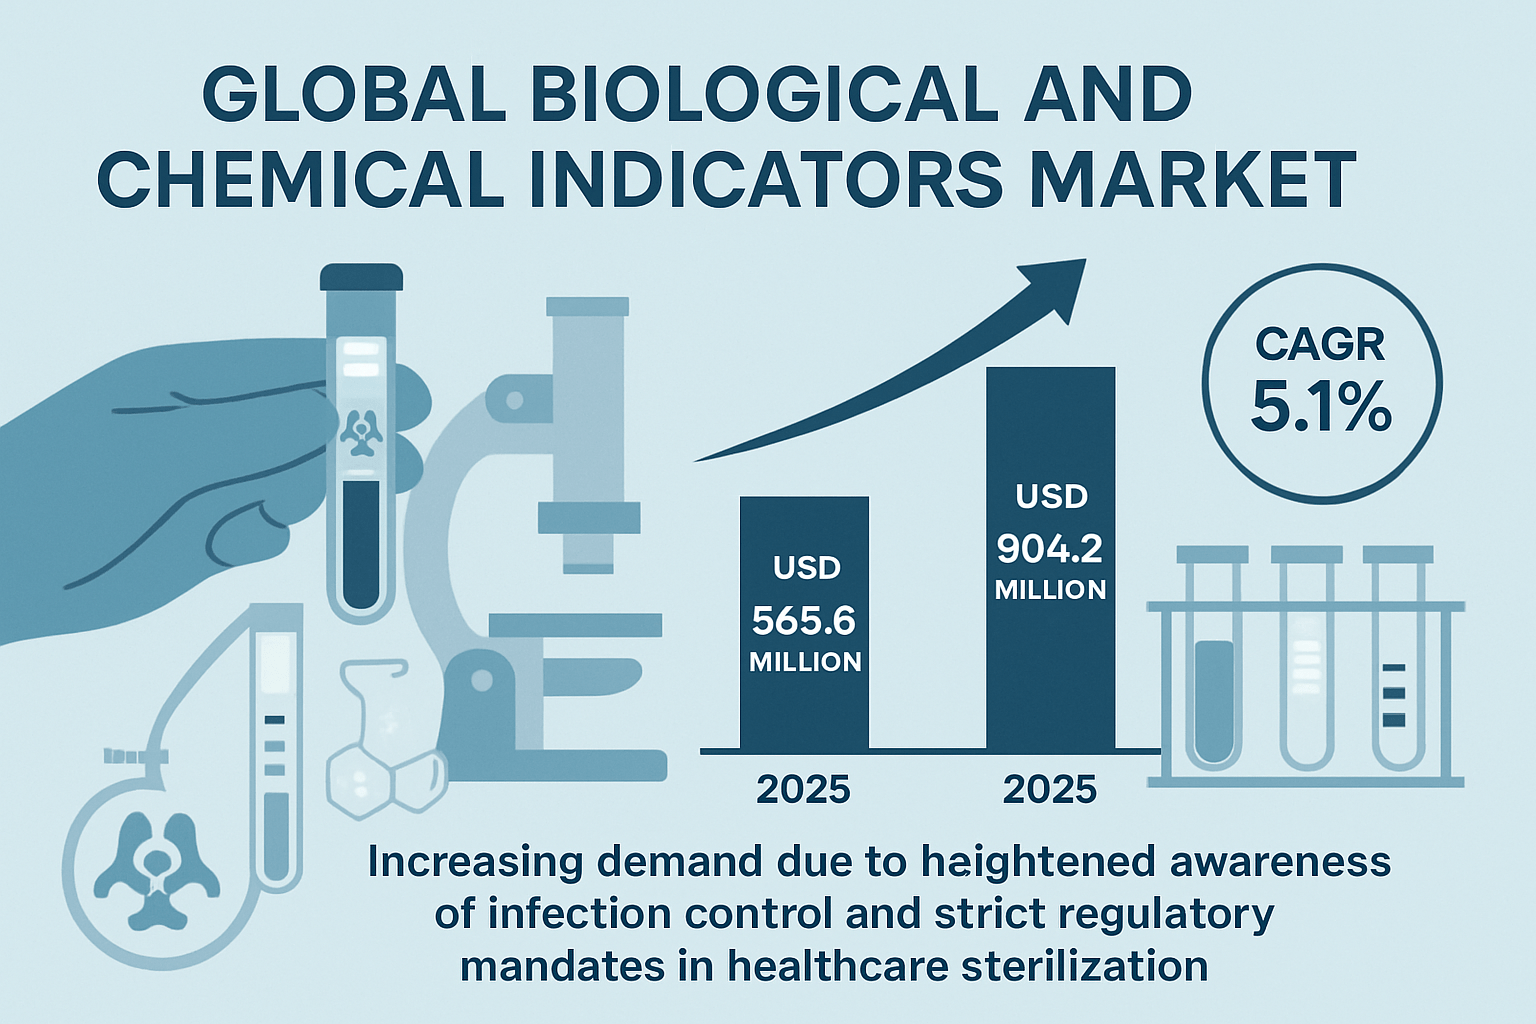
Biological & Chemical Indicators Market to Grow at 5.1% CAGR Through 2035

The global Biological and Chemical Indicators Market is estimated to be valued at USD 549.8 million in 2025 and is projected to reach USD 904.2 million by 2035, registering a compound annual growth rate (CAGR) of 5.1% over the forecast period. The Biological & Chemical Indicators Market is experiencing sustained growth driven by heightened awareness of infection control and strict regulatory mandates in healthcare sterilization.

The Biological & Chemical Indicators Market comprises products used to validate sterilization processes such as steam, ethylene oxide, hydrogen peroxide, and dry heat sterilization. Biological indicators typically contain spores of microorganisms and are used to confirm the effectiveness of a sterilization cycle. Chemical indicators, on the other hand, react chemically to show exposure to one or more of the parameters required for a sterilization process. These products are critical in ensuring compliance with safety regulations in healthcare, pharmaceuticals, and food industries.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-12544

Market Trends

A key trend in the Biological & Chemical Indicators Market is the increasing preference for single-use, disposable indicators that reduce cross-contamination risks. Automation in sterilization processes has also driven the adoption of advanced indicators with real-time monitoring and data logging capabilities. Another trend is the growing awareness around infection control in emerging economies, which is expanding market demand in regions previously underpenetrated.

Driving Forces Behind Market Growth

Several factors are propelling the growth of the Biological & Chemical Indicators Market:

  • Rising Healthcare Infrastructure: Expansion of hospitals and surgical centers is increasing demand for sterilization validation products.
  • Stricter Regulatory Guidelines: Compliance with international sterilization standards is mandatory, boosting the need for reliable indicators.
  • Increasing Surgical Procedures: More surgeries mean more sterilization cycles, which directly fuels the demand for indicators.
  • Public Health Awareness: The global focus on infection prevention, especially post-pandemic, has accelerated market growth.

Challenges and Opportunities

While the Biological & Chemical Indicators Market is growing, it is not without its challenges. High costs of advanced indicators and lack of standardization in some developing countries can restrict market penetration. Additionally, limited awareness among small healthcare facilities about the importance of sterilization monitoring is a hurdle.

However, these challenges open doors for innovation and growth. There’s an opportunity for manufacturers to develop cost-effective and user-friendly products tailored for low-resource settings. Partnerships with governments and NGOs to raise awareness can also improve adoption rates in underdeveloped areas.

Recent Industry Developments

Recent advancements in the Biological & Chemical Indicators Market include the integration of smart technologies in indicators. Newer products now offer visual, digital, and even cloud-based reporting for sterilization cycles. The market has also seen collaborations between global sterilization equipment manufacturers and indicator providers to offer comprehensive sterilization solutions. Mergers and acquisitions continue to shape the competitive landscape, allowing companies to expand their product portfolios and market reach.

Regional Analysis

North America holds the largest share of the Biological & Chemical Indicators Market, thanks to a well-established healthcare system and strict sterilization protocols. Europe follows closely, driven by regulatory compliance and high awareness. The Asia-Pacific region is emerging rapidly due to increased investments in healthcare infrastructure, especially in countries like China and India. Latin America and the Middle East are also showing promising growth, although market maturity in these regions remains moderate compared to developed economies.

Competitive Outlook

The Biological & Chemical Indicators Market is moderately fragmented with a mix of global players and regional participants. Competitive strategies include product innovation, strategic partnerships, and expansion into untapped regions. Companies are also investing in research and development to improve the reliability and ease of use of their indicators. Brand reputation and regulatory approvals play significant roles in determining market leadership.

Top Companies

Several top companies dominate the Biological & Chemical Indicators Market:

  • 3M Company
  • Steris Corporation
  • Getinge AB
  • Mesa Labs, Inc.
  • Terragene S.A.
  • Andersen Products, Inc.
  • Propper Manufacturing Co., Inc.

These organizations are known for their strong R&D capabilities, wide product ranges, and global distribution networks, giving them a competitive edge in the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/biological-and-chemical-indicators-market

Segmentation Outlook

The Biological & Chemical Indicators Market can be segmented based on:

  • Type: Biological Indicators, Chemical Indicators
  • Sterilization Method: Steam, Ethylene Oxide, Hydrogen Peroxide, Dry Heat
  • End User: Hospitals, Pharmaceutical Companies, Clinical Laboratories, Food & Beverage Industry
  • Geography: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa

Each segment offers unique growth opportunities. For instance, steam sterilization indicators are the most widely used due to the prevalence of autoclave systems in hospitals.
 

3D Cell Culture Market to Reach $3.81B by 2035, Growing at 9.8% CAGR

The global 3D Cell Culture Market is estimated to be valued at USD 1,494.2 million in 2025 and is projected to reach USD 3,805.7 million by 2035, registering a compound annual growth rate (CAGR) of 9.8% over the forecast period. The 3D cell culture market is undergoing robust expansion, driven by the escalating demand for physiologically relevant cellular models in drug discovery, toxicology assessment, and regenerative medicine.

The 3D cell culture market is transforming the landscape of biomedical research, drug development, and regenerative medicine. Unlike traditional 2D cultures, 3D cell culture provides a more realistic microenvironment that better replicates human tissue. This has significantly enhanced the accuracy of preclinical studies, offering researchers better insights into cellular behavior. The increasing adoption of advanced cell culture techniques in cancer biology, stem cell research, and personalized medicine has led to a steady rise in demand.

The 3D cell culture market is experiencing robust growth due to ongoing innovation in scaffold-based technologies, organoids, and spheroid cultures. It is being increasingly adopted by pharmaceutical and biotechnology companies to improve efficiency in drug discovery.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-2843

Market Trends

  1. Shift Toward Personalized Medicine
    With the rise of personalized medicine, researchers are turning to 3D cell culture systems to study patient-specific responses to drugs. This trend is contributing significantly to the expansion of the 3D cell culture market.
  2. Increased Use of Organoids
    Organoid cultures are gaining popularity for their ability to mimic organ function. Their use in disease modeling, especially in neurological and gastrointestinal conditions, is expanding the market footprint.
  3. Technological Advancements
    Recent innovations in scaffold fabrication, microfluidics, and 3D bioprinting have opened new possibilities. These advances are making 3D cultures more accessible, reliable, and scalable, thus driving the 3D cell culture market forward.
  4. Collaborations and Funding
    Increased collaboration between academic institutions and commercial entities, along with greater funding for cell-based research, is accelerating market growth.
3D Cell Culture Market

Challenges and Opportunities

  1. High Cost of Setup
    The initial setup cost for 3D cell culture labs remains a major barrier, especially for smaller research facilities and startups. Equipment, maintenance, and skilled personnel requirements can be expensive.
  2. Standardization Issues
    Lack of standardized protocols for 3D cultures often results in inconsistent results, limiting broader adoption. However, this challenge presents an opportunity for companies to develop universal, user-friendly systems.
  3. Regulatory Hurdles
    Regulatory complexities associated with 3D cell culture use in drug testing and medical applications slow down market expansion. Addressing these hurdles through well-defined frameworks could unlock significant growth.
  4. Expanding Applications
    Beyond oncology, 3D cell culture systems are finding new applications in cosmetic testing, toxicology, and infectious disease research. These emerging uses offer long-term growth opportunities in the 3D cell culture market.

Key Points

  1. The 3D cell culture market is primarily driven by its ability to closely mimic human tissue architecture.
  2. Increasing adoption in drug discovery and disease modeling is pushing demand.
  3. Spheroid and scaffold-based models dominate current commercial applications.
  4. Integration of artificial intelligence and 3D imaging is enhancing analytical capabilities.
  5. The market is seeing growing interest from both academia and the private sector.

Key Regional Insights

  1. North America
    North America leads the 3D cell culture market due to strong biotech infrastructure and heavy R&D investment. The U.S. remains a major hub, particularly in oncology research and drug screening.
  2. Europe
    Europe is another strong contributor, with countries like Germany, the UK, and France investing heavily in biomedical research. EU regulations are increasingly favoring non-animal testing methods, indirectly supporting 3D cultures.
  3. Asia-Pacific
    The Asia-Pacific region is rapidly growing due to rising awareness, government initiatives, and increased clinical trials in countries like China, Japan, and India.
  4. Rest of the World
    While currently limited in market share, regions in Latin America and the Middle East are expected to show moderate growth in the coming years.

Competitive Outlook

  1. The 3D cell culture market is highly competitive, featuring a mix of established players and innovative startups.
  2. Companies are focusing on developing advanced culture systems and user-friendly kits to capture market share.
  3. Mergers, partnerships, and acquisitions are common strategies for expanding product portfolios and global reach.
  4. Continuous investment in R&D is helping companies stay ahead of evolving customer needs and technologies.

Top Companies

  1. Thermo Fisher Scientific
  2. Corning Incorporated
  3. Lonza Group AG
  4. Merck KGaA
  5. 3D Biotek LLC
  6. Greiner Bio-One
  7. Insphero AG
  8. Avantor, Inc.
  9. PromoCell GmbH
  10. ReproCELL Inc.

These top companies are contributing to innovation and wider adoption in the 3D cell culture market by offering novel solutions and expanding their global presence.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/3d-cell-culture-market

Segmentation Outlook

  1. By Technology
    • Scaffold-Based
    • Scaffold-Free
    • Bioreactor-Based
    • Microfluidic-Based
  2. By Application
    • Cancer Research
    • Stem Cell Research
    • Drug Development and Testing
    • Tissue Engineering
    • Regenerative Medicine
  3. By End User
    • Pharmaceutical & Biotechnology Companies
    • Academic & Research Institutes
    • Hospitals & Diagnostic Centers


Headspace Gas Analyzers Market Set to Hit $1.12B by 2035 at 4.3% CAGR

The global Headspace Gas Analyzers Market is estimated to be valued at USD 655.7 million in 2025 and is projected to reach USD 1,120.1 million by 2035, registering a compound annual growth rate (CAGR) of 4.3% over the forecast period. Rising regulatory demands across pharmaceuticals, food and beverage manufacturing as well as packaging sectors are driving stringent quality and safety requirements, leading to increased deployment of headspace analyzers.

The headspace gas analyzers market is growing steadily as industries seek better solutions for packaging integrity and product safety. Headspace gas analyzers are critical in measuring the composition of gases within sealed packaging, especially in industries like food, pharmaceuticals, and electronics. These devices help maintain product quality and increase shelf life by detecting oxygen, carbon dioxide, and other gases that could affect the product. The demand for quality assurance, particularly in vacuum and modified atmosphere packaging (MAP), is directly influencing the rise of the headspace gas analyzers market.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-13979

Market Trends

One of the prominent trends shaping the headspace gas analyzers market is the shift toward non-destructive testing methods. Traditional techniques often damaged the packaging, rendering the product unusable. Today’s technology offers advanced laser-based and sensor-based systems that preserve package integrity. Another notable trend is the integration of automation and digital interfaces, allowing operators to perform rapid analysis with minimal training. Additionally, portable and handheld analyzers are gaining popularity for their convenience in on-site testing and real-time analysis.

Headspace Gas Analyzers Market

Driving Forces Behind Market Growth

Several key drivers are fueling the growth of the headspace gas analyzers market:
1. Stringent regulatory requirements across food and pharmaceutical industries are pushing manufacturers to adopt reliable testing solutions.
2. Rising consumer demand for safe and long-lasting packaged products has made quality control an essential part of the production process.
3. Growth in the pharmaceutical sector, especially biologics and vaccines, demands precise environmental control during storage and shipment.
4. Technological advancements are enabling the development of compact, faster, and more accurate analyzers, enhancing operational efficiency.

Challenges and Opportunities

Despite the positive outlook, the headspace gas analyzers market faces a few challenges.
1. High initial costs associated with purchasing and maintaining these devices can deter small-scale manufacturers.
2. Lack of skilled personnel to operate and interpret analyzer results can limit adoption.

However, opportunities abound:
1. Emerging economies with expanding food processing and pharmaceutical sectors present untapped growth potential.
2. The trend toward automation and smart manufacturing offers room for innovation in integrating analyzers into production lines.
3. Increasing awareness about packaging quality in healthcare and food delivery services is opening new avenues for market expansion.

Recent Industry Developments

Recent developments in the headspace gas analyzers market showcase a surge in product innovation and strategic collaborations. Companies are launching multi-gas analyzers capable of measuring multiple gas types simultaneously, enhancing testing efficiency. There has also been a rise in strategic partnerships between analyzer manufacturers and packaging companies to offer integrated quality control solutions. Additionally, the post-pandemic era has driven a higher emphasis on sterile packaging, leading to new investments in quality assurance tools.

Regional Analysis

Geographically, the headspace gas analyzers market shows different dynamics:
1. North America leads in adoption due to strong pharmaceutical and food processing industries and strict regulatory frameworks.
2. Europe follows closely, benefiting from advanced packaging technology and environmental regulations.
3. Asia-Pacific is expected to witness the highest growth due to rapid industrialization, increasing investments in healthcare, and expansion of food supply chains.
4. Latin America and the Middle East & Africa are slowly emerging, driven by infrastructure development and increasing demand for food safety.

Competitive Outlook

The headspace gas analyzers market is highly competitive with several global and regional players. Companies are competing on innovation, pricing, and after-sales support. A strong focus is placed on R&D to deliver faster, more precise, and user-friendly devices. Mergers and acquisitions are common strategies to gain a larger market share and expand product portfolios.

Top Companies

Some of the top players in the headspace gas analyzers market include:
1. Mocon Inc. – Known for its extensive range of MAP testing solutions.
2. Ametek Mocon – Offers high-performance analyzers for various applications.
3. Dansensor – A key innovator in oxygen and carbon dioxide analyzers.
4. WITT-Gasetechnik – Specializes in precision gas analysis equipment.
5. Illinois Instruments – Renowned for portable headspace analysis tools.
6. PAC L.P. – Provides robust lab and field testing solutions.

These companies continue to dominate due to their consistent product development and global presence.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/headspace-gas-analyzers-market

Segmentation Outlook

The headspace gas analyzers market can be segmented by:
1. Technology – Laser-based, sensor-based, and others.
2. Application – Food and beverage, pharmaceuticals, electronics, and others.
3. Packaging Type – Bottles, pouches, vials, and trays.
4. Region – North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.

This segmentation provides a comprehensive view of how the headspace gas analyzers market serves diverse industries with tailored solutions.


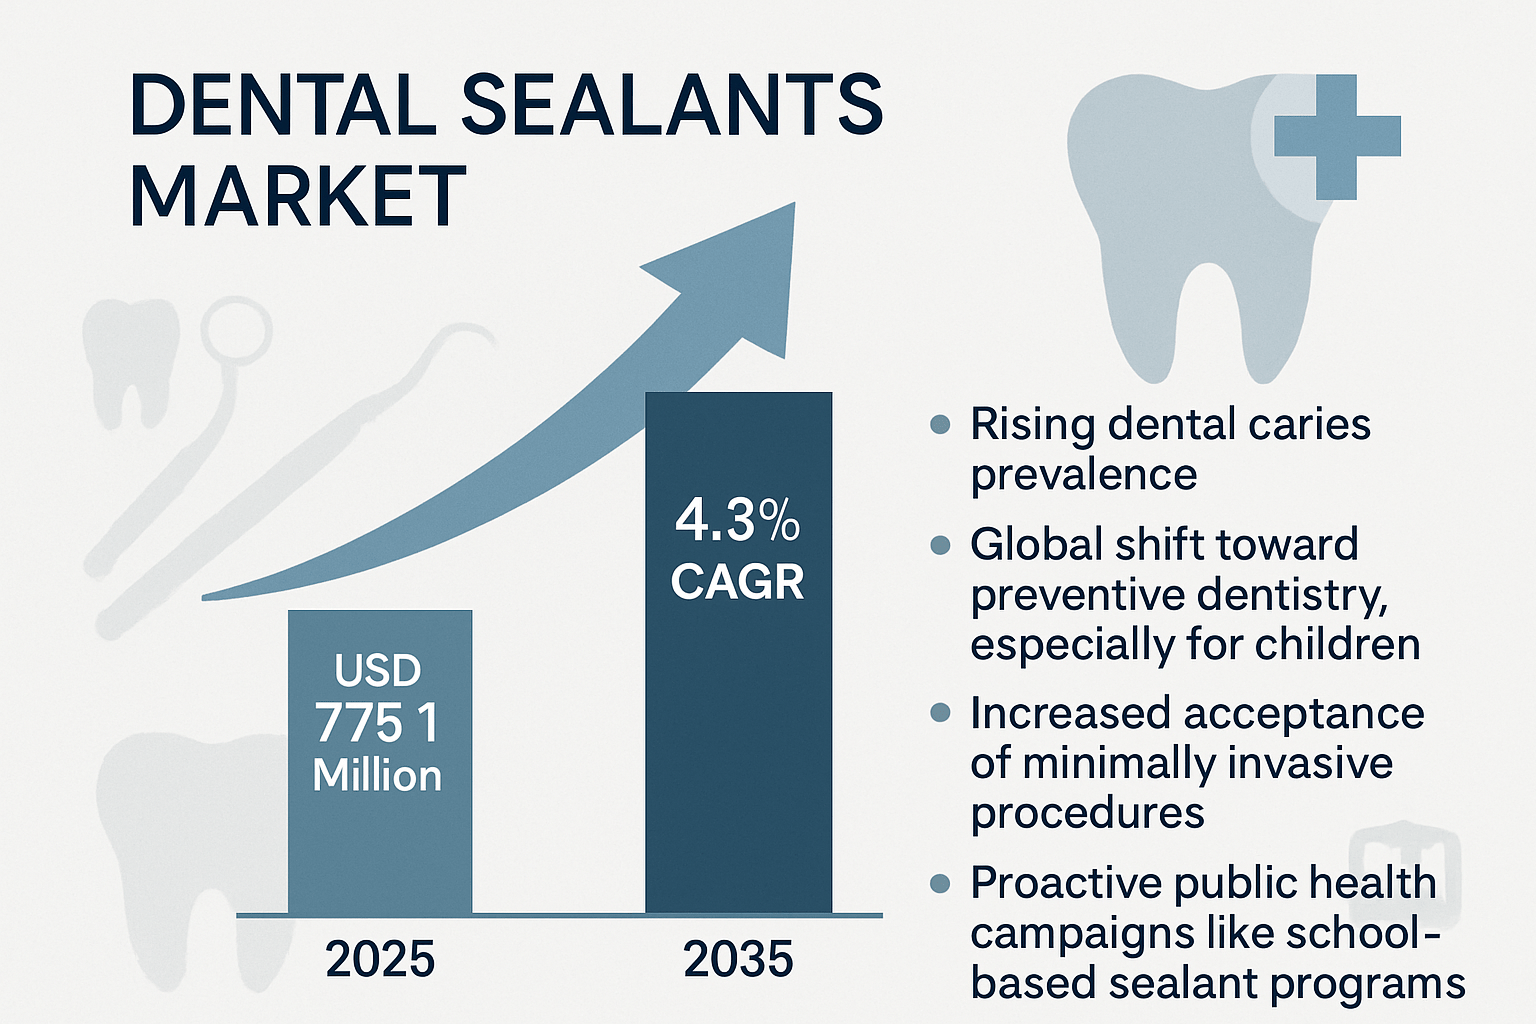
Dental Sealants Market Set for 4.3% CAGR, Hitting $1.18B by 2035

The global Dental Sealants Market is estimated to be valued at USD 775.1 million in 2025 and is projected to reach USD 1,180.9 million by 2035, registering a compound annual growth rate (CAGR) of 4.3% over the forecast period. Continued expansion in the market is driven by rising dental caries prevalence and a global shift toward preventive dentistry, particularly among paediatric and adolescent populations. Demand has been supported by increased acceptance of minimally invasive procedures and proactive public health campaigns that integrate school-based sealant programs.

The dental sealants market is gaining traction worldwide as both patients and healthcare providers increasingly focus on preventive dental care. Dental sealants are thin protective coatings applied to the chewing surfaces of molars and premolars to prevent cavities and tooth decay. This non-invasive procedure is cost-effective and significantly reduces the risk of dental caries, especially in children and adolescents. The dental sealants market is growing steadily due to heightened awareness of oral hygiene and favorable public health policies.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14552

Market Trends

  1. Rising Preventive Dental Practices: There is a global shift toward preventive dentistry, with sealants being widely promoted as a primary defense against cavities.
  2. School-Based Dental Programs: Public health initiatives targeting school children are boosting demand in the dental sealants market, especially in North America and parts of Europe.
  3. Growing Use of Resin-Based Sealants: These materials offer better durability and aesthetics, making them the preferred choice among dental professionals.
  4. Adoption of Teledentistry: Virtual consultations are increasing awareness of sealants among remote and underserved populations, driving further adoption.
Dental Sealants Market

Driving Forces Behind Market Growth

  1. High Incidence of Dental Caries: The global burden of tooth decay, especially among children and young adults, is a major factor fueling the dental sealants market.
  2. Increased Awareness About Oral Health: Educational campaigns and dental awareness initiatives have led to early adoption of preventive care measures like sealants.
  3. Supportive Government Programs: Many countries provide subsidized or free sealant applications under national health schemes, further accelerating market growth.
  4. Advancements in Dental Materials: Ongoing R&D has resulted in more effective, longer-lasting sealant materials that appeal to both patients and practitioners.

Challenges and Opportunities

  1. Limited Access in Rural Areas: Despite its benefits, the dental sealants market faces challenges in reaching remote or low-income populations due to inadequate dental infrastructure.
  2. Lack of Awareness in Developing Regions: In many developing countries, knowledge about preventive dental solutions like sealants is still limited.
  3. Misconceptions Among Adults: Sealants are often perceived as treatments for children only, although adults with a high risk of cavities can benefit as well.
  4. Opportunity in Geriatric Care: As the elderly population grows, there’s a significant opportunity to extend sealant treatments to adults for long-term tooth preservation.
  5. Innovation in Application Techniques: New delivery methods and materials are improving sealant adhesion and reducing procedure time, offering growth opportunities for manufacturers.

Recent Industry Developments

  1. Introduction of BPA-Free Sealants: Responding to consumer demand, many companies now offer BPA-free formulations for enhanced safety.
  2. Laser-Assisted Application: Some dental practices are incorporating laser technology to improve sealant application and curing.
  3. Customized Sealants: Companies are developing personalized sealants designed to cater to individual tooth morphology for improved fit and effectiveness.
  4. Collaborations With NGOs and Governments: Partnerships for large-scale school dental health programs have expanded the reach of the dental sealants market.

Regional Analysis

  1. North America: This region leads the dental sealants market due to high dental care spending, widespread insurance coverage, and extensive awareness programs.
  2. Europe: Western Europe follows closely, with countries like the UK, Germany, and France investing in preventive oral healthcare.
  3. Asia-Pacific: Rapid urbanization, growing middle-class populations, and rising health awareness are making this region a major growth driver.
  4. Latin America and Middle East: These emerging regions are showing potential due to government-backed dental programs and increasing focus on oral hygiene.
  5. Africa: Though still in the early stages, rising awareness and external funding are creating a slow but positive impact on market growth.

Competitive Outlook

  1. Strong Emphasis on Innovation: Key players are investing in research to develop more efficient and longer-lasting sealants.
  2. Focus on Pediatric Dentistry: Companies are targeting pediatric populations with specially formulated products and kid-friendly packaging.
  3. Market Penetration Strategies: Firms are entering untapped regions through partnerships with local dental clinics and mobile health units.
  4. Brand Loyalty Among Dentists: Products with proven efficacy often enjoy repeat business due to dentist recommendations and patient satisfaction.

Top Companies

  1. 3M Company: A global leader with a wide portfolio of dental products, including high-performance sealants.
  2. Dentsply Sirona: Known for its innovative dental materials and global distribution network.
  3. Ivoclar Vivadent: Offers advanced resin-based sealants with enhanced durability and aesthetics.
  4. GC Corporation: A major player in preventive dental solutions with a strong presence in Asia and Europe.
  5. Shofu Dental Corporation: Focuses on quality dental materials and actively participates in dental awareness programs worldwide.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/dental-sealants-market

Segmentation Outlook

  1. By Product Type: The dental sealants market is segmented into resin-based, glass ionomer, and other sealants. Resin-based sealants dominate due to their durability and ease of use.
  2. By Age Group: Pediatric applications lead the market, though adult usage is gaining attention for its preventive value.
  3. By End User: Dental clinics represent the largest share, followed by hospitals and academic institutions involved in public health initiatives.
  4. By Distribution Channel: Products are distributed through direct sales, dental distributors, and increasingly via online platforms targeting practitioners and bulk buyers.


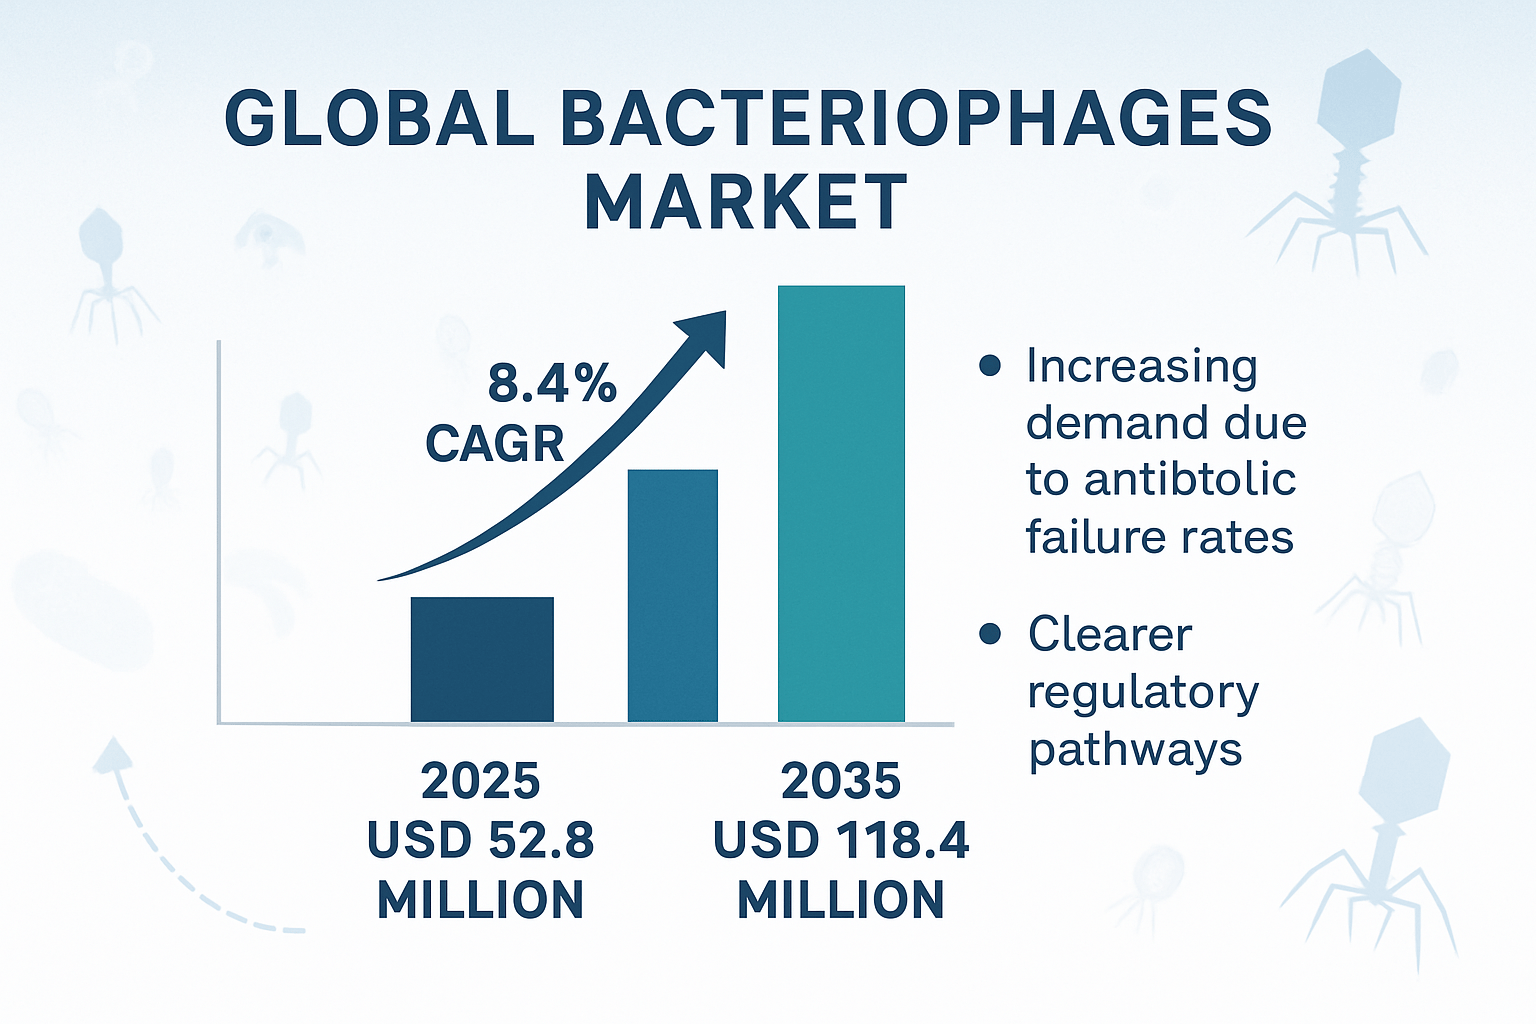
Bacteriophage Market Set for 8.4% CAGR Growth, Hitting $118.4M by 2035

The global Bacteriophages Market is estimated to be valued at USD 52.8 million in 2025 and is projected to reach USD 118.4 million by 2035, registering a compound annual growth rate (CAGR) of 8.4% over the forecast period. Increasing antibiotic failure rates in treating hospital-acquired infections are fueling demand for phage therapy. Regulatory bodies are offering clearer clinical pathways for bacteriophage approvals, enabling wider trial deployment.

The bacteriophage market is gaining considerable momentum as global demand for alternative antibacterial treatments grows. With the rising threat of antibiotic resistance, bacteriophages—viruses that infect and destroy bacteria—have emerged as a promising solution. These microscopic agents offer targeted bacterial control without harming human cells or beneficial microbiota, positioning the bacteriophage market at the forefront of modern therapeutics and biotechnology.

In recent years, medical researchers, pharmaceutical firms, and biotech startups have increasingly explored the potential of phage therapy in treating chronic infections, including those resistant to conventional antibiotics. This has led to heightened investment, clinical trials, and product development, propelling the growth of the global bacteriophage market.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14461

Market Trends

Several key trends are shaping the trajectory of the bacteriophage market. First, there’s a noticeable shift in the pharmaceutical industry toward personalized medicine. Since bacteriophages can be tailored to target specific bacterial strains, they fit well into this evolving treatment model.

Second, the application of bacteriophages is expanding beyond human healthcare into sectors like agriculture, aquaculture, and food safety. In farming, for instance, phages are used to protect crops from bacterial diseases without chemical pesticides. This trend is pushing the bacteriophage market into broader, non-clinical domains, creating new growth avenues.

Third, advancements in genomic sequencing and synthetic biology are enabling faster and more precise phage identification and engineering. This has reduced development times and costs, encouraging more companies to enter the bacteriophage market.

Bacteriophage Market

Challenges and Opportunities

Despite promising growth, the bacteriophage market faces several challenges. Regulatory uncertainty remains a primary concern. Most global regulatory bodies, including the FDA and EMA, lack well-defined frameworks for approving phage-based therapies. This slows down product launches and investor confidence.

Another challenge lies in scalability. Culturing and purifying phages in mass quantities requires significant technological infrastructure and stringent quality controls, which not all companies can afford.

Nevertheless, the bacteriophage market offers immense opportunities. The rising burden of multi-drug-resistant infections, especially in hospitals and care facilities, creates a strong demand for effective non-antibiotic treatments. In addition, phage applications in livestock, food processing, and environmental safety open the door to cross-sectoral expansion.

Key Points

  • The bacteriophage market is driven by the urgent need for alternatives to antibiotics.
  • Phages offer specificity, minimizing collateral damage to healthy cells.
  • Global investments and partnerships in phage R&D are rapidly increasing.
  • Emerging sectors like agriculture and aquaculture are embracing phage solutions.
  • Regulatory progress will be critical for accelerating market adoption.

Key Regional Insights

North America currently leads the bacteriophage market due to strong R&D investments, favorable government funding, and a high prevalence of antibiotic resistance. The United States, in particular, is home to many pioneering biotech firms working on phage therapy.

Europe is also a significant player, especially with countries like Belgium and France supporting phage research through academic and clinical collaborations. Meanwhile, the Asia-Pacific region is expected to see the fastest growth, driven by increasing healthcare expenditures and rising awareness of phage therapy in countries like China, Japan, and India.

Competitive Outlook

The competitive landscape of the bacteriophage market is still evolving, with a mix of startups, academic spin-offs, and established pharmaceutical firms vying for market share. Many companies are focusing on narrow niches, such as wound care, urinary tract infections, or gastrointestinal diseases, to gain traction.

Strategic collaborations between academia and industry are common, allowing smaller firms to access cutting-edge research while universities benefit from commercialization support. Mergers and acquisitions are also expected to shape the bacteriophage market in the coming years.

Top Companies

Several companies are making notable strides in the bacteriophage market:

  • Adaptive Phage Therapeutics: Focused on personalized phage therapy and rapid pathogen matching.
  • Phagomed Biopharma: Specializing in urogenital infection treatments.
  • Intralytix Inc.: A pioneer in phage applications for food safety and agriculture.
  • Eligo Bioscience: Developing CRISPR-enhanced phage solutions.
  • Armata Pharmaceuticals: Working on targeted bacteriophage therapies for hospital-acquired infections.

These companies are leading the way in innovation, trials, and commercial readiness, contributing significantly to the global bacteriophage market growth.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/bacteriophage-market

Segmentation Outlook

The bacteriophage market can be segmented based on application, route of administration, end-user, and geography.

  • By Application: Human therapeutics, veterinary care, agriculture, aquaculture, and food safety.
  • By Route of Administration: Oral, topical, intravenous, and others.
  • By End-User: Hospitals, research institutes, agriculture companies, and pharmaceutical firms.
  • By Geography: North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.


Advanced Empty Capsule Market Set for 7.1% CAGR, Hitting $2.08B by 2035

The global Advanced Empty Capsules Market is estimated to be valued at USD 1,047.7 million in 2025 and is projected to reach USD 2,080.3 million by 2035, registering a compound annual growth rate (CAGR) of 7.1% over the forecast period. The advanced empty capsules market is witnessing substantial growth driven by increased adoption of targeted drug delivery systems and the rise of personalized medicine.

The advanced empty capsule market is gaining significant momentum due to rising demand for personalized medicine, improved drug delivery technologies, and increased focus on dietary supplements. Empty capsules serve as a reliable and effective delivery system for various active pharmaceutical ingredients (APIs). With innovations in capsule composition such as hydroxypropyl methylcellulose (HPMC), pullulan, and gelatin-based materials, manufacturers are addressing the needs of both pharmaceutical and nutraceutical industries. The market is expanding rapidly, driven by consumer preference for plant-based and non-GMO products.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-13243

Size & Trends

  1. The advanced empty capsule market is witnessing strong growth, with consistent expansion across both developed and emerging regions.
  2. The rising trend of self-medication, especially in dietary supplements and functional foods, is fueling demand.
  3. Increasing preference for targeted drug delivery systems that offer better bioavailability is supporting market growth.
  4. Innovations like liquid-filled capsules, delayed-release technologies, and combination fillings are becoming popular.
  5. The market is also seeing growth in non-gelatin capsule variants to cater to vegetarians and those with religious dietary restrictions.

Key Highlights

  1. Pharmaceutical companies are adopting advanced capsule technologies to enhance drug solubility and absorption.
  2. The demand for personalized medication has led to increased use of custom-designed empty capsules.
  3. Stringent regulations regarding capsule safety and composition are prompting companies to adopt higher-quality raw materials.
  4. Plant-based capsules are growing faster than gelatin-based options due to shifting consumer preferences.
  5. North America and Europe lead in technological advancements and regulatory approvals.
Global Advanced Empty Capsules Market
Advanced Empty Capsule Market

Challenges and Opportunities

  1. One major challenge in the advanced empty capsule market is the fluctuating cost of raw materials like gelatin and cellulose.
  2. Technical limitations in capsule filling for hygroscopic or heat-sensitive ingredients pose manufacturing challenges.
  3. However, growing interest in alternative therapies and herbal supplements offers a lucrative opportunity.
  4. Expansion in developing regions such as Asia-Pacific and Latin America presents vast untapped potential.
  5. Collaborations between pharmaceutical companies and capsule manufacturers are accelerating product innovation.

Key Benefits for Stakeholders

  1. Pharmaceutical firms benefit from improved patient compliance and controlled-release functionalities.
  2. Nutraceutical companies can meet clean-label demands with vegetarian and organic capsule options.
  3. Consumers gain access to safer, easy-to-swallow, and visually appealing oral dosage forms.
  4. Manufacturers benefit from scalable production technologies and new capsule-filling equipment.
  5. Investors and R&D teams find promising avenues in bio-enhanced capsules and functional coatings.

Market Share by Geographical Region

  1. North America dominates the advanced empty capsule market due to its robust pharmaceutical industry and consumer awareness.
  2. Europe follows closely, driven by strict regulatory norms and rising demand for vegan capsules.
  3. Asia-Pacific is the fastest-growing region, with expanding healthcare infrastructure and pharmaceutical outsourcing hubs in India and China.
  4. Latin America and the Middle East are emerging markets, experiencing increased investments in healthcare.
  5. Regional market dynamics vary depending on dietary trends, medical advancements, and economic development.

Top Companies

  1. Leading companies in the advanced empty capsule market include Capsugel (a Lonza company), ACG Worldwide, and Qualicaps.
  2. Suheung Co. Ltd. and Roxlor are notable manufacturers focusing on capsule customization and global distribution.
  3. Bright Pharma and HealthCaps India are emerging players with a strong footprint in the Asia-Pacific region.
  4. These companies are investing in R&D to introduce novel capsule types like enteric-coated and dual-chamber capsules.
  5. Strong supply chain networks and regulatory certifications are key differentiators for top market players.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/advanced-empty-capsule-market

Segmentation Outlook

  1. The advanced empty capsule market is segmented by type, including gelatin, HPMC, pullulan, and starch-based capsules.
  2. By functionality, the market includes immediate-release, sustained-release, and delayed-release capsules.
  3. The end-user segmentation includes pharmaceutical companies, nutraceutical firms, and research laboratories.
  4. Distribution channels range from direct sales to third-party suppliers and online platforms.
  5. This segmentation helps companies target specific consumer needs and regulatory environments efficiently.


Dermatology Lasers Market to Hit $4.01B by 2035, Growing at 6.8% CAGR

The global Dermatology Lasers Market is estimated to be valued at USD 2,021.5 million in 2025 and is projected to reach USD 4,013.9 million by 2035, registering a compound annual growth rate (CAGR) of 6.8% over the forecast period. The market will experience a robust growth market driven by the increased prevalence of skin disorders, rising aesthetic awareness, and demand for minimally invasive cosmetic procedures.

The dermatology lasers market is experiencing significant growth as the demand for non-invasive cosmetic procedures rises globally. Dermatology lasers are specialized devices used to treat a range of skin conditions, from acne scars to vascular lesions and unwanted hair. These technologies offer precision, faster recovery, and minimal side effects, making them a popular choice among dermatologists and patients alike. The increasing preference for aesthetic improvements and technological advancements in laser systems are key elements propelling the dermatology lasers market forward.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-12662

Market Trends

  • Shift Toward Minimally Invasive Treatments
    Patients are increasingly opting for minimally invasive skin procedures due to quicker recovery times and less discomfort. This trend has fueled demand for fractional lasers and Q-switched lasers.
  • Rise in Home-Use Laser Devices
    The dermatology lasers market has seen a surge in at-home laser devices that allow consumers to perform basic skin treatments. These devices are cost-effective and convenient, although less powerful than clinical-grade systems.
  • Technological Innovations
    Advances such as picosecond lasers and multi-wavelength platforms are gaining popularity for their ability to treat multiple skin conditions with greater accuracy and safety.
Dermatology Device Market
Dermatology Lasers Market

Driving Forces Behind Market Growth

  • Growing Awareness of Aesthetic Treatments
    Increased public awareness about the availability and benefits of dermatological laser treatments has encouraged more people to seek professional skincare solutions.
  • Aging Population
    As the global population ages, the demand for treatments that reduce wrinkles, fine lines, and age spots has surged, boosting the dermatology lasers market.
  • Rise in Skin Disorders
    The increasing prevalence of skin issues like rosacea, pigmentation, and acne is contributing to the rising demand for dermatology lasers in clinical practices.

Challenges and Opportunities

  • High Cost of Laser Equipment
    The cost of acquiring and maintaining advanced laser systems remains a barrier for many small and mid-sized dermatology clinics, potentially restricting market access.
  • Risk of Side Effects
    If not used properly, laser treatments can lead to skin burns or pigmentation issues. This concern limits adoption, particularly in regions lacking skilled professionals.
  • Training and Certification Gaps
    There is a growing need for specialized training and certification to safely operate laser systems, which presents both a challenge and an opportunity for industry stakeholders.
  • Untapped Markets in Developing Countries
    Emerging economies offer significant growth potential. Rising disposable incomes and increased awareness are creating opportunities for dermatology laser manufacturers.

Recent Industry Developments

  • New Product Launches
    Companies are continually releasing advanced laser systems with better cooling mechanisms and dual-functionality for multi-condition treatment.
  • Regulatory Approvals
    Approval from agencies like the FDA and CE for new dermatology lasers enhances market credibility and encourages adoption in regulated markets.
  • Mergers and Acquisitions
    Strategic mergers are becoming common as companies aim to expand their portfolios and global reach, enhancing the dermatology lasers market landscape.

Regional Analysis

  • North America Dominates the Market
    Due to high healthcare spending, advanced medical infrastructure, and strong demand for cosmetic procedures, North America leads the dermatology lasers market.
  • Asia-Pacific Shows Rapid Growth
    The Asia-Pacific region is witnessing rapid market expansion, driven by a growing middle class, increasing awareness of aesthetic treatments, and medical tourism.
  • Europe Maintains Steady Growth
    European countries continue to adopt advanced dermatology lasers, supported by government healthcare initiatives and rising consumer interest in cosmetic enhancement.

Competitive Outlook

  • Intense Market Competition
    The dermatology lasers market is highly competitive, with numerous players investing in R&D and innovation to differentiate their offerings.
  • Focus on Innovation
    Companies are prioritizing product development and customization to meet the diverse needs of dermatology professionals and patients.
  • Service Expansion Strategies
    Leading players are extending their reach through training programs, post-sales services, and partnerships with dermatology clinics.

Top Companies

  • Cutera Inc.
    Known for innovative platforms, Cutera offers advanced lasers used in hair removal, skin rejuvenation, and vascular treatments.
  • Candela Corporation
    Candela is a global leader providing aesthetic laser-based systems, widely adopted for their reliability and technological strength.
  • Lumenis Ltd.
    A pioneer in laser-based medical treatments, Lumenis holds a strong position in the dermatology lasers market with a diverse product line.
  • Alma Lasers
    Alma Lasers focuses on both aesthetic and surgical solutions, frequently launching versatile and user-friendly systems.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/dermatology-lasers-market

Segmentation Outlook

  • By Product Type
    The dermatology lasers market is segmented into CO2 lasers, Er:YAG lasers, Nd:YAG lasers, and diode lasers, each serving different treatment purposes.
  • By Application
    Applications include acne and scar treatment, skin rejuvenation, vascular lesions, and tattoo removal, with skin rejuvenation being the most in-demand.
  • By End User
    Clinics, hospitals, and home users form the primary end-user segments, with clinics leading due to access to high-end laser technologies.


Ophthalmic Diagnostic Equipment Market to Reach $5.02B by 2035 at 3.5% CAGR

The ophthalmic diagnostic equipment market is expected to grow from USD 3.56 billion in 2025 to USD 5.02 billion by 2035. The market is poised to expand at a 3.5% CAGR during the forecast period. This growth is being propelled by the increasing global burden of eye disorders and the demand for early and precise diagnosis.

The ophthalmic diagnostic equipment market is steadily growing due to the increasing prevalence of eye-related disorders and the aging global population. This market includes various devices such as optical coherence tomography (OCT), fundus cameras, and tonometers used to diagnose eye conditions like glaucoma, cataracts, and retinal diseases.

Technological advancements have enhanced the accuracy and efficiency of these tools, making early detection and treatment more accessible. As awareness of eye health continues to grow, healthcare providers and clinics are investing heavily in upgrading their diagnostic capabilities. The expansion of healthcare infrastructure in emerging regions is also contributing significantly to the ophthalmic diagnostic equipment market.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-771

Market Trends

  1. Rise in Digital Imaging: Digital imaging tools are replacing traditional methods, improving diagnosis precision and reducing the time needed for results.
  2. Integration with AI: Artificial intelligence is increasingly being integrated into diagnostic systems to enhance clinical decision-making.
  3. Home-based and Portable Devices: The development of compact diagnostic tools allows for basic testing outside clinical settings, improving accessibility in remote areas.
  4. Increased Focus on Preventive Eye Care: There is a growing shift toward preventive diagnostics, which is boosting the demand in the ophthalmic diagnostic equipment market.
  5. Cloud-based Data Storage: Storing diagnostic data on cloud platforms ensures faster and more secure access for both patients and healthcare professionals.

Challenges and Opportunities

  1. High Equipment Costs: The upfront cost of advanced diagnostic tools remains a barrier, particularly in low-income regions.
  2. Skilled Workforce Requirement: Many ophthalmic devices require trained professionals to operate, limiting usage in underdeveloped healthcare systems.
  3. Regulatory Hurdles: Approval processes and compliance with local regulations can delay market entry for new products.
  4. Opportunities in Telemedicine: Teleophthalmology is gaining traction, creating new avenues for the ophthalmic diagnostic equipment market.
  5. Potential in Emerging Economies: Countries in Asia-Pacific, Latin America, and Africa present untapped opportunities due to increasing investment in healthcare infrastructure.

Key Points

  1. The ophthalmic diagnostic equipment market is driven by the growing need for early detection of eye diseases.
  2. Innovations in non-invasive imaging technologies are key to market growth.
  3. Demand is rising not just in hospitals but also in clinics and mobile diagnostic centers.
  4. Strategic collaborations between tech firms and healthcare providers are becoming common.
  5. The market is anticipated to continue growing as vision care becomes a higher priority globally.

Key Regional Insights

  1. North America leads the ophthalmic diagnostic equipment market due to its robust healthcare system and high awareness levels.
  2. Europe follows closely, with substantial government support for eye health initiatives and strong reimbursement policies.
  3. Asia-Pacific is witnessing rapid growth fueled by large patient pools, rising disposable income, and expanding healthcare infrastructure.
  4. Latin America shows promise due to improving access to diagnostic services and growing awareness.
  5. Middle East & Africa are in early stages but expected to grow with international support and mobile health solutions.

Competitive Outlook

  1. The ophthalmic diagnostic equipment market is highly competitive, with players focusing on innovation and differentiation.
  2. Companies are investing in R&D to develop faster, more accurate, and user-friendly diagnostic tools.
  3. Strategic mergers and acquisitions are helping companies expand their market presence and technological capabilities.
  4. Partnerships with hospitals and eye clinics are crucial to market penetration.
  5. Competitive pricing strategies and service-based models are emerging to make equipment more accessible.

Top Companies

  1. Carl Zeiss Meditec AG – Known for its high-quality diagnostic imaging devices and continuous innovation.
  2. Topcon Corporation – Offers a wide range of solutions with strong global distribution.
  3. NIDEK Co., Ltd. – Specializes in ophthalmic diagnostic equipment with a focus on user-friendly technologies.
  4. Heidelberg Engineering GmbH – Renowned for its OCT systems and cutting-edge imaging technologies.
  5. Canon Medical Systems Corporation – Provides reliable and advanced ophthalmic diagnostic tools.
  6. Alcon Inc. – Expanding its diagnostics segment through strategic alliances and product launches.
  7. Optovue, Inc. – A leader in OCT technology with a strong presence in the North American market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/ophthalmic-diagnostic-equipment-market

Segmentation Outlook

  1. By Product Type: Includes OCT, fundus cameras, perimeters, refractors, and slit lamps.
  2. By End-User: Hospitals, ophthalmic clinics, ambulatory surgical centers, and research institutes.
  3. By Application: Diagnostics for glaucoma, macular degeneration, diabetic retinopathy, and general eye exams.
  4. By Portability: Fixed and portable/handheld diagnostic equipment.
  5. By Geography: North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa.


IV Pole Market Set to Grow from USD 272.4M in 2025 to USD 497.1M by 2035

The global IV pole market is projected to reach a valuation of USD 272.4 million by 2025 and USD 497.1 million by 2035, expanding at a CAGR of 3.5%. This growth is primarily driven by a rising number of surgical procedures globally, as well as increasing hospital admissions due to chronic illnesses and an aging population.

The IV pole market is experiencing steady growth, driven by the rising demand for advanced healthcare infrastructure and increasing patient admissions worldwide. IV poles are essential hospital accessories used to hold intravenous bags, enabling seamless delivery of fluids and medications to patients. They are used across multiple settings, including hospitals, clinics, ambulatory surgical centers, and home care environments. The increasing prevalence of chronic diseases and the expansion of home healthcare services are playing a vital role in expanding the IV pole market globally.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-6880

Size & Trends

  1. The global IV pole market has shown a consistent upward trajectory over the past few years.
  2. With the increasing number of hospitalizations and surgeries, the demand for IV poles is witnessing strong momentum.
  3. Manufacturers are focusing on introducing innovative designs, such as collapsible and adjustable height IV poles, to enhance convenience and safety.
  4. The trend of portable and lightweight IV poles is gaining popularity due to the growing preference for mobility in patient care.
  5. Moreover, the integration of smart technologies like digital infusion monitoring systems with IV poles is an emerging trend.
IV Poles Market
IV Poles Market

Key Highlights

  1. The IV pole market is supported by the rising geriatric population globally, which leads to increased medical intervention and hospital stays.
  2. Demand is particularly strong in both developed and emerging markets due to healthcare infrastructure expansion.
  3. The shift toward outpatient care and home healthcare services is significantly contributing to market growth.
  4. The availability of poles in multiple materials—such as stainless steel, chrome-plated, and plastic—is providing end-users with flexible choices.
  5. Hospitals remain the dominant end-user segment, but the homecare sector is gaining significant ground.

Challenges and Opportunities

  1. One of the major challenges in the IV pole market is the presence of low-quality and counterfeit products, which can compromise patient safety.
  2. Price sensitivity in low- and middle-income countries often restricts the adoption of high-end IV poles.
  3. Limited product differentiation and intense competition are barriers for new entrants.
  4. However, there are clear opportunities in the form of product customization and integration of advanced features.
  5. Additionally, rising investment in healthcare infrastructure in developing countries opens new doors for expansion.

Key Benefits for Stakeholders

  1. Healthcare providers benefit from improved patient mobility and ease of medication administration.
  2. Manufacturers can leverage growing demand to expand product lines and enhance brand positioning.
  3. Investors gain access to a stable and essential segment of the healthcare industry.
  4. Regulatory bodies and standardization organizations play a critical role in ensuring quality and safety compliance.
  5. Patients enjoy enhanced comfort and efficient medical treatment due to ergonomic IV pole designs.

Market Share by Geographical Region

  1. North America dominates the IV pole market due to its advanced healthcare systems and strong presence of major players.
  2. Europe holds the second-largest market share, driven by robust healthcare funding and widespread hospital networks.
  3. The Asia-Pacific region is emerging rapidly, with countries like China and India investing heavily in healthcare infrastructure.
  4. Latin America and the Middle East are expected to show moderate growth, supported by gradual improvements in medical facilities.
  5. Regional differences in healthcare policies and pricing influence the rate of adoption and product preferences.

Competitive Outlook

  1. The IV pole market is highly competitive with numerous global and regional players.
  2. Key manufacturers are focusing on mergers, acquisitions, and partnerships to expand their reach.
  3. Innovation remains a crucial factor, with companies investing in product design and durability improvements.
  4. Cost efficiency and customer service are also significant competitive factors.
  5. Brand loyalty and distributor networks play a vital role in maintaining market presence.

Top Companies

  1. Leading players in the IV pole market include Medline Industries, 3M Healthcare, and Cardinal Health.
  2. Other notable names are B. Braun Melsungen AG, Baxter International, and Drive DeVilbiss Healthcare.
  3. Many smaller companies and startups are introducing unique IV pole solutions to target niche markets.
  4. Top companies continue to focus on compliance with regulatory standards and expanding their global footprint.
  5. Investment in R&D and customer feedback integration helps top firms stay ahead in a competitive environment.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/iv-poles-market

Segmentation Outlook

  1. The IV pole market can be segmented based on material type, such as stainless steel, aluminum, and plastic.
  2. Based on mobility, the market includes stationary and wheeled IV poles.
  3. Height adjustability and number of hooks are also common segmentation parameters.
  4. In terms of end-users, the segments include hospitals, clinics, ambulatory surgical centers, and homecare settings.
  5. This segmentation helps manufacturers develop products tailored to specific needs and enhances product adoption across different care environments.


Viscosupplementation Industry Analysis in Europe to Reach USD 869.8 Million by 2035

The Europe viscosupplementation market is projected to expand from USD 523.9 million in 2025 to USD 869.8 million by 2035, registering a steady 5.2% CAGR during the forecast period. This growth is being driven by the rising prevalence of osteoarthritis, demographic aging, and the growing preference for non-surgical joint therapies.

The Europe viscosupplementation market is steadily gaining traction, driven by the rising prevalence of osteoarthritis and growing demand for non-invasive pain management solutions. Viscosupplementation is a procedure where hyaluronic acid is injected into the joints to restore lubrication, reduce stiffness, and improve mobility. As Europe’s aging population continues to rise, the need for safe and effective alternatives to surgical interventions is fueling market expansion. Additionally, improvements in healthcare infrastructure and a shift toward outpatient procedures are supporting this market’s momentum.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-eu-1383

Market Trends

  1. Rise in Single-Injection Products: The shift from multiple-injection regimens to single-injection solutions is improving patient compliance and reducing treatment costs.
  2. Adoption of Image-Guided Injections: Ultrasound-guided viscosupplementation is gaining popularity in Europe due to increased precision and reduced discomfort during procedures.
  3. Growing Preference for Natural Hyaluronic Acid Sources: Patients and practitioners are leaning toward products derived from non-animal sources, reflecting a broader trend toward biocompatibility.
  4. Technological Integration in Clinics: Smart devices and electronic injection tracking systems are being integrated into orthopedic practices to improve documentation and patient outcomes.
  5. Home-Based Follow-up Programs: Post-injection telemedicine consultations and remote physical therapy support are enhancing recovery and patient satisfaction.
Russia Viscosupplementation Market
Viscosupplementation Industry Analysis in Europe

Driving Forces Behind Market Growth

  1. Aging Population: Europe’s demographic trend toward an older population is directly increasing the incidence of joint degeneration and osteoarthritis.
  2. Minimally Invasive Treatment Demand: Patients are increasingly opting for procedures that offer pain relief without the risks and downtime of surgery.
  3. Rising Awareness of Joint Preservation: Public health campaigns and medical education are promoting early intervention strategies like viscosupplementation.
  4. Increase in Sports-Related Injuries: Higher participation in sports across all age groups has led to a rise in joint injuries, boosting demand for intra-articular treatments.
  5. Healthcare System Support: Many European healthcare systems now reimburse viscosupplementation procedures, making them more accessible to a broader patient base.

Challenges and Opportunities

  1. Lack of Universal Reimbursement Policies: Variability in reimbursement structures across countries poses a barrier to widespread adoption of viscosupplementation.
  2. Clinical Outcome Variability: Differences in product efficacy and patient response continue to challenge standardized treatment protocols.
  3. Opportunity in Early-Stage Osteoarthritis: Targeting patients in the early stages of joint degeneration could extend the application scope of viscosupplementation therapies.
  4. Need for Stronger Evidence Base: More long-term clinical studies are needed to reinforce viscosupplementation’s position in treatment guidelines.
  5. Regulatory Changes: Adapting to evolving European medical device regulations requires companies to enhance product quality and compliance efforts.

Recent Industry Developments

  1. New Product Launches: Several companies have introduced advanced hyaluronic acid products designed for longer-lasting effects and fewer injections.
  2. Strategic Collaborations: Partnerships between orthopedic clinics and manufacturers are helping to streamline the distribution and application of viscosupplementation therapies.
  3. Growth in Online Sales Channels: Digital pharmacies and e-health platforms are beginning to distribute viscosupplementation kits to certified practitioners.
  4. Clinical Trial Expansions: Numerous trials across Europe are assessing next-generation formulations for both knee and hip joints.
  5. Enhanced Training Programs: Medical training centers are offering specialized certification programs for orthopedic practitioners to improve injection techniques.

Regional Analysis

  1. Germany: As one of the largest healthcare markets in Europe, Germany leads in viscosupplementation procedures due to high awareness and reimbursement support.
  2. France: The market in France is growing due to government initiatives supporting elderly care and chronic disease management.
  3. United Kingdom: Rising cases of osteoarthritis and increasing preference for outpatient care are accelerating market growth in the UK.
  4. Italy and Spain: These countries are seeing moderate growth driven by an aging population and growing private healthcare infrastructure.
  5. Nordic Countries: High healthcare standards and technological adoption are supporting the increased use of image-guided viscosupplementation procedures.

Competitive Outlook

  1. Focus on Innovation: Leading players in the Europe viscosupplementation market are investing in R&D to enhance the durability and effectiveness of hyaluronic acid injections.
  2. Product Portfolio Expansion: Companies are diversifying their offerings to include injections for multiple joints, including hips and shoulders.
  3. Localized Manufacturing: European manufacturers are focusing on localized production to ensure consistent supply and meet regulatory standards.
  4. Marketing and Education: Efforts to educate both healthcare professionals and patients are helping to boost market penetration.
  5. Mergers and Acquisitions: Consolidation trends continue as larger firms acquire niche players to strengthen their position in the viscosupplementation sector.

Top Companies

  1. Anika Therapeutics, Inc.
  2. Ferring Pharmaceuticals
  3. Sanofi S.A.
  4. Bioventus Inc.
  5. Zimmer Biomet
  6. Seikagaku Corporation
  7. Fidia Farmaceutici S.p.A.
  8. Chugai Pharmaceutical Co., Ltd.

These companies lead the Europe viscosupplementation market through extensive distribution networks, product innovation, and strategic partnerships.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/europe-viscosupplementation-market

Segmentation Outlook

  1. By Product Type: Includes single-injection, three-injection, and five-injection formulations. Single-injection types are gaining the most traction.
  2. By Application Site: Knee joints dominate the market, followed by hip, shoulder, and ankle joints.
  3. By End User: Hospitals, orthopedic clinics, and ambulatory surgical centers are the key consumers of viscosupplementation products.
  4. By Country: Germany, France, UK, Italy, and Spain represent the primary country-level markets within the region.