The car battery chargers industryis projected to grow significantly, with its value rising from USD 22.09 billion in 2023 to USD 43.47 billion by 2033. According to FMI, the market is expected to register a robust CAGR of 7.0% during the forecast period.
The car battery chargers industry is gaining significant traction, driven by the increasing adoption of electric vehicles (EVs), rising demand for portable and smart charging solutions, and growing consumer awareness about maintaining battery health. From traditional internal combustion engine vehicles to modern EVs, car battery chargers are essential for ensuring optimal vehicle performance and reliability.
According to recent industry reports, the global car battery charger market is set to experience robust growth over the coming years, fueled by technological advancements and the shift towards sustainable mobility solutions.
Rising Electric Vehicle Adoption:
The surge in EV sales globally has driven the need for advanced chargers capable of managing high-capacity batteries efficiently and sustainably.
Increased Focus on Battery Maintenance:
Awareness of maintaining battery life and performance is pushing consumers to invest in high-quality chargers that support quick and reliable charging.
Technological Advancements:
Smart chargers equipped with features like automatic shut-off, multi-stage charging, and compatibility with multiple battery types are gaining popularity.
Portable and Fast Charging Solutions:
Demand for portable, compact chargers and rapid-charging technologies is growing, catering to the needs of travelers and emergency charging scenarios.
Growth in Aftermarket Services:
As vehicle ownership increases globally, the aftermarket segment, including battery chargers, is expanding, particularly in emerging markets.
Key Takeaways
The global car battery chargers market is projected to grow at a CAGR of 7.0% between 2023 and 2033, reaching a valuation of USD 43.47 billion by the end of the forecast period.
Asia-Pacific dominates the market, driven by high automotive sales and rapid EV adoption in countries like China, Japan, and India. Meanwhile, North America and Europe are experiencing strong growth due to technological innovations and sustainability initiatives.
Key segments driving the market include portable chargers, smart chargers, and solar-powered chargers, reflecting a shift towards convenience and eco-friendly solutions.
Leading industry players such as Schumacher Electric, CTEK, Clore Automotive, and NOCO are focusing on innovation, product diversification, and partnerships to strengthen their market positions.
The integration of IoT-enabled features, such as app-based monitoring and diagnostic tools, is transforming traditional battery chargers into connected, smart devices.
Key Players
CTEK Holding AB
Delphi Automotive
Schumacher Electric Corporation
Clore Automotive LLC
Baccus Global LLC
Robert Bosch GmbH
Current Ways Inc
AeroVironment, Inc.
IES Synergy and Chargemaster Plc
Key segmentations
By Charging Type:
Manual Charging
Automatic Charging
By Charger Type:
Smart/Intelligent Charger
Float Charger
Trickle Charger
By Portability:
Plug-In Charger
Portable Charger
By Battery Capacity:
Up to 12V
12V-48V
Above 48V
By Product Type:
Car Battery Charger
Electric Car Battery Charger
By Application:
Garage
Personal Use
By Region:
North America
Latin America
Western Europe
Eastern Europe
Asia Pacific excluding Japan (APEJ)
Japan
Middle East & Africa (MEA)
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
According to newly released data from Future Market Insights (FMI), the global down and feather market is estimated to reach USD 7,567.3 million in 2023 and is projected to more than double to USD 16,175.3 million by 2033, growing at a robust compound annual growth rate (CAGR) of 7.9% from 2023 to 2033. Notably, the down and feather segment accounts for approximately 30-35% of the broader bedding products market.
Market Insights: Key Drivers of Growth
The down and feather market is experiencing a phase of steady growth, fueled by both technological advancements and shifting consumer demands. The exceptional properties of down and feathers, including outstanding compressibility, recovery, and a high warmth-to-weight ratio, continue to drive their popularity in high-performance bedding and outdoor products. Notably, consumer demand is increasingly driven by sustainability concerns and greater transparency regarding the ethical sourcing of animal-derived materials.
Down and feathers, long valued for their insulation qualities, have historically been used primarily in bedding products. However, recent innovations have expanded their applications into other areas, including outdoor gear, fashion, and home décor. As a result, manufacturers are presented with new growth opportunities in both established and emerging markets.
Key Dynamics in the Market
Augmented Demand for Sustainable Down and Feathers
Increasing awareness among consumers regarding the humane treatment of animals and the environmental impact of synthetic materials is boosting the demand for ethically sourced, sustainable down and feathers. Non-profit organizations such as the Responsible Down Standard (RDS) are actively working to ensure the traceability and humane treatment of animals in the down and feather supply chain.
Growing Popularity of Down and Feather Bedding Products
Bedding products, including pillows, comforters, and duvets, are the largest category within the market. These products are favored for their ability to offer warmth without adding bulk. As consumers opt for more luxurious and sustainable options, demand for down and feather-filled bedding products is expected to grow substantially.
Recycling and Sustainability Initiatives
The recycling of down and feathers is gaining traction as a means to reduce waste and promote sustainability. Recycled down and feathers, cleaned and repurposed from waste by-products, help reduce the environmental footprint of the industry. With growing concerns over environmental sustainability, products made from natural, eco-friendly materials like down and feathers are being recognized for their lower carbon footprint compared to synthetic alternatives.
Technological Advancements in Down and Feather Products
While down and feathers have long been recognized for their thermal insulation properties, ongoing research into their structure and mechanical properties is leading to improved product designs. Innovations in the production of synthetic insulation materials inspired by down and feathers are also expected to transform the market during the forecast period.
Insights on Key Product Segments
Feather vs. Down
In 2022, down accounted for more than 55% of the market share, driven by its superior warmth-to-weight ratio. However, feathers are also growing in demand due to their lower cost and sufficient insulation properties in certain applications.
Duck Origin
Duck down and feathers, which represented more than 25% of global production in 2022, are expected to see the fastest growth, driven by their widespread availability and superior thermal properties compared to other poultry sources.
Bedding Products
Bedding remains the dominant application for down and feathers, comprising over 74% of the market share in 2022. Products such as comforters, pillows, and duvets are becoming increasingly popular among consumers seeking natural and sustainable alternatives to synthetic materials.
Competitive Landscape
Companies in the down and feather industry are actively pursuing strategic alliances and partnerships with other producers to expand their product portfolios and cater to the growing demands of their customer base.
For Instance
In 2020, since a few years ago, Chun Li International Co., Ltd. has collaborated with Ohio Feather Co. The company successfully supplied down and feathers to the Ohio Feather Co. based on the needs of the business.
In 2018, In order to excel its down and feather-based pillow and mattress products in New York, SIMBA, a producer of bedding items, teamed up with Primo International, a distribution of luxury pillows and mattresses in Mexico, South America, the United States, and Canada.
Key Companies Profiled
Pan Pacific Company Ltd.; Allied Feather & Down; Down-Lite International Inc.; Peter Kohl KG; KL Down; Chunli International Co Ltd.; Bettfedern Handelsgesellschaft mbH & Co. KG (Rohdex); Heinrich Häussling GmbH & Co.; Karl Sluka GmbH; Norfolk Feather Company; Feather Industries; Treude & Metz GmbH & Co. KG; Sustainable Down Source; Navarpluma; Shin Joo Won D&G Co.; Others
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The automotive brake system and components industry is estimated to reach a valuation of USD 69,403.5 million in 2023, with projections indicating growth to USD 109,862.1 million by 2033. The market is anticipated to achieve a notable CAGR of 4.7% over the forecast period.
The automotive brake system and components industry is at the heart of vehicle safety and performance, continuously evolving to meet modern driving demands. With innovations in braking technology and increasing emphasis on vehicle safety standards, the industry is poised for robust growth.
According to market insights, the demand for advanced brake systems and components is accelerating due to rising vehicle production, advancements in electrification, and stricter safety regulations globally.
Stringent Safety Regulations:
Governments worldwide are enforcing stricter safety standards, mandating advanced braking systems such as Anti-lock Braking Systems (ABS) and Electronic Stability Control (ESC).
Electrification of Vehicles:
The rise of electric vehicles (EVs) has driven the need for regenerative braking systems, which improve energy efficiency while ensuring superior braking performance.
Technological Innovations:
Advances in braking technology, such as autonomous braking systems, hydraulic-electronic integration, and smart braking solutions, are enhancing the functionality and reliability of brake systems.
Increased Vehicle Production:
Growing automotive production, especially in emerging economies, is fueling the demand for reliable and efficient braking systems across all vehicle segments.
Consumer Demand for Safety:
Rising consumer awareness about vehicle safety and the availability of advanced braking technologies are propelling the adoption of enhanced brake components.
Key Takeaways
The global automotive brake system and components market is projected to grow at a CAGR of 4.7% from 2023 to 2033, reaching a market size of USD 109,862.1 million by the end of the forecast period.
Asia-Pacific remains the largest market, driven by high automotive production in China and India, while North America and Europe see significant growth due to increasing EV adoption and stringent safety norms.
The demand for brake pads, rotors, calipers, and ABS modules is on the rise, with automakers and OEMs focusing on lightweight, durable, and efficient components.
Leading players such as Bosch, ZF Friedrichshafen AG, Brembo, and Continental AG are driving innovation in the industry through investments in R&D, collaborations, and sustainability initiatives.
Integration of IoT and AI in braking systems, including predictive maintenance and adaptive braking, represents the next frontier in the market.
Competitive Landscape
Over the last few years, there has been an increase in acquisitions and growth efforts to surge the supply of automotive brake systems & components. Many leading firms are also working on technology development. Contracts & agreements, new product development, and partnerships are vital strategies renowned firms adopt to maintain their market positions.Continental AG; ZF Friedrichshafen AG; Delphi Automotive PLC; Valeo S.A; Federal-Mogul Holdings Corporation; Nissin Kogyo Co. Ltd; Hitachi Astemo, Ltd.; Akebono Brake Industry Co Ltd.; Magneti Marelli S.p.A; Mando Corporation; Brembo S.p.A.
For Instance,
In March 2022, Nisshinbo Holdings Inc. announced to establish a joint venture company with Continental AG (Continental) in Gurgaon, Haryana, India. The newly established company may produce and sell valve blocks, which are the main component of electronic brake systems (EBS). The joint venture may be capitalized at around JPY 1.9 billion, 60% of which may be owned by Nisshinbo HD and 40% by Continental. They are planning to begin operation in April 2023.
Key Segments Covered in the Automotive Brake System & Components Market Report
By Sales Channel:
OEM
Drum Brake
Disc Brake
Aftermarket
Brake Booster
Master Cylinder
Drum Brake
Drum
Brake Shoe
Wheel Cylinder
Disc Brake
Rotor
Caliper
Brake Pad
By Vehicle Type:
Passenger Car
LCV
HCV
Region:
North America
Latin America
Western Europe
Eastern Europe
Asia Pacific Excluding Japan (APEJ)
Japan
The Middle East & Africa (MEA)
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global hospital-acquired infection control market is on the brink of transformative growth, according to a recent report by Future Market Insights. Valued at USD 6.5 billion in 2023, the market is set to more than double over the next decade, achieving an estimated valuation of USD 12.7 billion by 2033, propelled by a robust compound annual growth rate (CAGR) of 7%.
Hospitals and Intensive Care Units (ICUs) are projected to play a pivotal role in this expansion, with revenue from these critical healthcare settings anticipated to grow at an even higher CAGR of 7.6%.
Key Drivers of Market Growth:
The substantial growth of the HAI control market is driven by a confluence of critical factors:
Frequent Occurrence of Hospital-Acquired Infections: The ongoing prevalence of HAIs underscores the urgent need for effective infection control measures.
Increasing Surgical Procedures: A growing number of surgical interventions necessitate stringent infection prevention protocols to ensure patient safety.
Rising Geriatric Population and Chronic Diseases: The aging global population and the rising incidence of chronic illnesses are heightening the demand for advanced infection control practices.
Advancements in Sterilization Equipment: Breakthroughs in sterilization technologies are enhancing the efficacy and efficiency of infection prevention systems.
Enhanced Hygiene Awareness: Increasing public and institutional awareness about hygiene standards is fostering widespread adoption of infection control solutions.
The adoption of advanced sterilization methods, including e-beam sterilization and the resurgence of ethylene oxide sterilization, is set to revolutionize infection control practices. These innovations are not only improving the reliability of sterilization processes but also aligning with stringent regulatory standards in healthcare.
Future Market Insights highlights the critical role of innovation and heightened awareness in shaping the hospital-acquired infection control market. As global healthcare systems continue to prioritize patient safety and infection prevention, the demand for cutting-edge infection control solutions is expected to soar.
With the HAI control market poised for exponential growth, stakeholders across the healthcare ecosystem must seize this opportunity to invest in technologies and protocols that ensure safer healthcare environments.
Competitive Analysis:
The key players in the market include Steris Plc, Sotera Health Company, Getinge AB, Advanced Sterilization Products, Ecolab Inc., 3M Company, Matachana Group, MMM Group, Belimed AG, and Reckitt Benckiser.
Some of the recent developments of key Hospital-acquired Infection Control providers are as follows:
In 2021, STERIS purchased Cantel, a global provider of infection control products and services, through a U.S. subsidiary to broaden its vast array of sterilization services.
In 2021, Sterigenics S.A.S., a Sotera Health Company subsidiary, increased its European sterilizing capacity by expanding its ethylene oxide factory in Rantigny, France. Getinge introduced the Getinge Solsus 66 steam sterilizer for hospitals as well as surgical instruments in 2020, which has a higher capacity and operational reliability than other sterilizers.
In 2020, Sotera Health Company acquired Iotron, a prominent North American outsourced provider of E-beam sterilization services. The acquisition was intended to help the company expand its electron beam footprint and boost sales of the Sterigenics division.
Market Segments Covered in Hospital-acquired Infection Control Industry Analysis:
By Component:
Equipment
Sterilization Equipment
Disinfection Equipment
Consumables
Disinfectants
Sterilization Consumables
Others (Waste Disposal, PPE)
Services
By End-user:
Hospitals and Intensive Care Units
Ambulatory Surgical and Diagnostic Centers
Other End-users
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global COVID-19 diagnostics market is poised for significant growth, with projections indicating a reach of USD 204.51 billion by 2032. This robust growth is expected to follow a compound annual growth rate (CAGR) of 7.7% throughout the forecast period, with the market’s value estimated to reach USD 97.4 billion in 2022.
Europe is expected to dominate the COVID-19 diagnostics market during this period, driven by advanced healthcare infrastructure, high healthcare spending, and ongoing research and development activities aimed at improving diagnostic accuracy and speed.
As the world continues to adapt to the evolving nature of the pandemic, demand for efficient diagnostic tools and solutions remains critical in the fight against COVID-19. This sustained demand is likely to fuel market growth and innovation in the years to come.
Key Factors Driving Market Growth:
Technological Advancements: Ongoing research and development of new diagnostic technologies, including rapid testing solutions and molecular diagnostics.
Government and Healthcare Investments: Increased investments by governments and private entities to boost diagnostic capabilities and ensure widespread testing.
Continued Pandemic Response: The ongoing need for accurate and fast diagnostics in both symptomatic and asymptomatic individuals across the globe.
As the COVID-19 diagnostics landscape evolves, stakeholders in the medical and healthcare sectors must remain agile to meet the rising demand for diagnostic solutions. With Europe at the forefront of market growth, the future looks promising for the global diagnostics industry.
Key Takeaways from FMI’s Covid-19 Diagnostics Market Study:
Molecular assay holds the largest share right now and the trend is expected to continue till the end of 2020. This could be attributed to the fact that molecular assays have been looked upon as a gold standard to detect novel viral infections
Diagnostic labs contributed to more than 60% of total market share in 2020’s first quarter
“The number of Covid-infected patients have been increasing at an alarming rate every single day. This is bound to drive the Covid-19 diagnostics market exponentially” – says the FMI analyst.
Right now, the challenges faced include lack of information regarding the virus, like genetic information, biologics, duration of immunity in the recovered patients.
Certain treatment options that are expected to be potential game changers include ACE-Mab by Sorrento Therapeutics, HCQ (Hydroxychloroquine and chloroquine), Remdesivir antiviral by Gilead Sciences, and Canakinumab (Ilaris) by Novartis.
Moreover, options like cell-based therapies that involve natural killer cells or Mesenchymal stem cells and plasma therapies are on the verge of providing personalized treatment options.
Key Participant Insights:
The key participants are focusing on acceleration of production as well as new product approval phase. For example – Novacyt Group, in Mar 2020, received EUA for 2-hour Covid-19 test. Also, in Apr 2020, CE approval was received by Abbott for IgG serology blood test for Covid-19.
The other players in the market include Veredus Laboratories, Thermo Fisher Scientific, Inc., Quidel Corporation, Perkin Elmer, Inc., Neuberg Diagnostics, Mylab Discovery Solutions Pvt Ltd., Luminex Corporation, Laboratory Corporation of America Holdings, Hologic Inc., Danaher, Cepheid, bioMérieux SA, Altona Diagnostics GmbH, ALDATU BIOSCIENCES, ADT Biotech Sdn Bhd, and 1drop Inc.
Key Segment:
Product Type:
Instruments
Test Kits
Reagents and Consumables
Sample Type:
Oropharyngeal & Nasopharyngeal Swabs
Blood
Urine
Others
Technology:
PCR
ELISA
POC
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global small kitchen appliances market, valued at approximately USD 105.84 billion in 2023, is poised to grow to an estimated USD 145.0 billion by 2033, reflecting a compound annual growth rate (CAGR) of 3.2% during the forecast period. This growth is largely driven by the rising demand for innovative kitchen solutions, the growing trend of kitchen renovations, and the increased adoption of small, multifunctional appliances across both developed and emerging economies.
Key Market Drivers
Technological Innovation: The emergence of smart kitchen appliances and other technological advancements is set to revolutionize the market. New product innovations, from more efficient food processors to eco-friendly non-stick cookware, are improving both manufacturing processes and consumer experiences.
Growing Disposable Income: Rising disposable incomes, particularly in emerging markets, have led to an increased demand for more efficient, easy-to-use kitchen appliances. Consumers are increasingly investing in high-quality, multifunctional appliances that meet their diverse needs, contributing to the growth of this market.
Kitchen Renovation Boom: The global trend toward kitchen renovations is another key factor driving the small kitchen appliances market. As consumers focus on upgrading their kitchens, there is a surge in demand for stylish, compact, and energy-efficient appliances that can complement modern kitchen designs.
Health & Wellness Movement: As consumers become more health-conscious, there is an uptick in the demand for small kitchen appliances that make preparing home-cooked meals easier and faster. This trend is expected to continue to fuel the demand for food preparation appliances such as blenders, food processors, and air fryers.
Emerging Trends in Small Kitchen Appliances
The rise of multifunctional appliances that combine multiple functions into one device, such as smart ovens, multi-cookers, and all-in-one blenders, is expected to dominate the market. The growing popularity of food preparation devices, including stand mixers and compact food processors, is another factor influencing the market’s upward trajectory.
In addition, there is a rising interest in energy-efficient and environmentally-friendly appliances. Consumers, particularly millennials, are increasingly favoring small kitchen gadgets that use less energy and space while still delivering exceptional performance. This shift has opened up new avenues for manufacturers to introduce advanced, eco-conscious products.
Regional Insights
North America: The United States dominates the North American market, with increasing demand for innovative, energy-efficient small kitchen appliances.
India: India’s small kitchen appliances market is growing rapidly due to rising disposable income, urbanization, and increasing demand for branded products, particularly in rural areas.
Competitive Landscape
The small kitchen appliances market is highly competitive, fueled by the increasing demand for convenient, time-saving cooking solutions. Established brands continually innovate to preserve their market position, while emerging players seek to disrupt the industry with unique products and features.
Major companies rely on their strong brand reputation, extensive distribution networks, and robust R&D capabilities to maintain dominance. At the same time, private label brands from large retailers pose a significant challenge by offering affordable alternatives. E-commerce platforms further heighten competition, enabling smaller brands to directly reach consumers. As customers prioritize durability, quality, and smart features, companies that adapt to shifting preferences and deliver exceptional customer experiences are best positioned for success in this rapidly evolving market.
Product Portfolio
Panasonic Corporation offers a diverse product portfolio encompassing consumer electronics, home appliances, automotive systems, and industrial solutions. From cutting-edge TVs and audio systems to energy-efficient home appliances, Panasonic strives to enrich lives through innovative technologies that enhance everyday experiences.
LG Electronics boasts a comprehensive product portfolio ranging from TVs, smartphones, and home appliances to air conditioning and home entertainment systems. Committed to delivering excellence, LG’s products integrate advanced features and sleek designs, catering to the needs of modern consumers worldwide.
Samsung Electronics leads with a wide-ranging product portfolio, including smartphones, tablets, TVs, home appliances, and smart home solutions. Driven by innovation, Samsung’s offerings combine seamless connectivity, superior performance, and futuristic designs, elevating the digital lifestyle of millions globally.
Key Companies Profiled
Groupe SEB
Electrolux AB
BSH Hausgeräte GmbH
Whirlpool Corporation
Haier Group
Panasonic Corporation
LG Electronics
Dongbu Daewoo Electronics
Samsung Electronics
Breville
Miele
Koninklijke Philips N.V.
Conair Corporation
Get Strategic Guidance from Our Analyst Contact us on: +1-347-918-3531
Market Segmentation
By Product:
Small Cooking Appliances
Food Preparation Appliances
Beverage Making Appliances
By Price Range:
Mass
Premium
By End-Use:
Residential
Commercial
By Sales Channel:
Wholesalers/ Distributors
Hypermarkets/ Supermarkets
Multi-brand Stores
Independent Stores
Online Stores
Others
By Region:
North America
Latin America
Western Europe
Eastern Europe
South Asia and Pacific
East Asia
Middle East & Africa
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The market for pea protein ingredients is anticipated to be worth USD 1.6 billion in 2023 and USD 3.4 billion by 2033. During the predicted period, pea protein ingredient sales expand at a CAGR of 7.9%.
The rising popularity of veganism in countries like the U.S., India, the U.K., and Germany has led to a significant increase in the consumption of plant-based protein products. As a result, the pea protein ingredients market is projected to exceed USD 2.5 billion by the end of 2031.
From 2016 to 2020, the market experienced a robust CAGR of 6.4%. Growing awareness of the health benefits of pea protein, which is rich in lysine and iron, has contributed to this trend, with consumers increasingly opting for pea protein to mitigate the risk of bone-related diseases such as arthritis.
In addition to health benefits, the demand for pea protein ingredients is on the rise among vegans. The escalating rates of cardiovascular diseases are also pushing consumers toward healthier dietary choices, further bolstering the market for pea protein. Moreover, the demand for plant-based proteins in sports nutrition is expected to enhance sales in this segment.
The high incidence of food allergies linked to meat products is another factor driving the demand for pea protein ingredients. According to the National Institute of Allergy and Infectious Diseases, approximately 12.2 million people suffer from food allergies, with around 8% of children and 2% of adults allergic to seafood and meat.
In response to these trends, manufacturers are ramping up their research and development efforts to innovate new product lines centered around pea protein. Given these dynamics, the pea protein ingredients market is anticipated to grow at a CAGR of 7.2% from 2021 to 2031.
“Growing consumer preference for natural and organic food products and increasing concerns pertaining to animal welfare are expected to boost the market. In order to cater to surging requirements, manufacturers are introducing new products, which augmenting sales in the market,” says a FMI analyst.
Key Takeaways from Pea Protein IngredientsMarket Study
North America is expected to account for over 79.2% of pea protein ingredients sales, with the U.S. dominating the market on the back of rising consumption of clean label food products
The U.K. pea protein ingredients market will account for 14% of market share in 2021
China’s pea protein market will surpass USD 64.3 Mn in 2021 on the back of growing demand for sustainable and affordable vegan protein products
In terms of product, isolate pea proteins are expected to hold the lion’s share owing to their high-quality nutrition and growing adoption among lactose-intolerant people
Sales of pea protein ingredients in bakery sector are expected to surge at 9.9% CAGR through 2021.
Key Drivers
Growing demand for plant-based products and increasing trend for vegan lifestyle will accelerate the growth in the market.
Absence of allergen properties in pea-protein ingredients as compared to other conventional plant-based proteins is expected to improve the adoption
Declining consumption of meat products due to intolerance of animal protein is likely to boost the market
Key Restraints
High cost of extraction and processing pea protein ingredients is anticipated to create the challenge for market players
Lack of processing outputs in emerging and low-income economies resulting in limited supply to hamper the sales.
Competitive Landscape
Leading players in the pea protein ingredients market are focusing on introducing new product lines in response to surging demand for clean label and non-GMO plant-based ingredients.
Also, some of the players are extensively investing in research and development activities to introduce new products in the market. Meanwhile, other players are collaborating with food manufacturers and end-users to expand their customer base. For instance:
In October 2021, Ingredion Inc., unveiled its Prista Line of pulse-based ingredient solutions. The line includes Homecraft Prista P 101 pea flour, Vitessence® Prista P 155 pea protein concentrate, and Vitessence Prista P 360 faba bean protein concentrate for plant-protein-based applications including instant and ready-to-eat (RTE) products.
In 2021, Ulrick & Shirt launched a new range of clean label, organic functional starches, and proteins.
In January 2020, Beyond Meat, a leader in plant-based meat, announced a multi-year pea protein supply agreement with Roquette, a leader in plant-based ingredients and a pioneer of plant proteins.
Some of the key players operating in the market profiled by FMI are:
More Valuable Insights on Pea Protein IngredientsMarket
FMI, in its new report, offers an in-depth study of the global pea protein ingredients market, highlighting the growth prospects of the market through 2021 and beyond. The survey reveals demand outlook of pea protein ingredients market with detailed segmentation:
By Product Type:
Isolates
Concentrates
Textured
By Application:
Bakery & Snacks
Dietary Supplements
Beverages
Meat Analogs/Substitutes
Others
By Form:
Powder
Liquid
Others
Frequently Asked Questions
How is the Pea Protein Ingredients Market Growing?
What Drives the Pea Protein Ingredients Market?
What is the Future Scope of Growth for the Pea Protein Ingredients Market?
What is the Pea Protein Ingredients Market Size?
Which Country Leads the Pea Protein Ingredients Market?
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global cell culture market is poised for significant growth, with projections estimating a rise from USD 27,911.3 million in 2024 to USD 44,593.1 million by 2034. According to the latest analysis by Future Market Insights (FMI), the market is expected to grow at a compound annual growth rate (CAGR) of 4.7% from 2024 to 2034. This expansion will be driven by several key factors, including the escalating demand for biopharmaceuticals, advancements in stem cell culture techniques, and the growing emphasis on personalized medicine.
Cell culture technology is becoming indispensable in the production of crucial biopharmaceuticals such as monoclonal antibodies, insulin, and vaccines. With the rise in chronic diseases globally, the demand for these biopharmaceuticals is set to propel the global need for cell culture systems. This trend is expected to continue as healthcare systems seek innovative solutions to address widespread health issues.
In addition to biopharmaceutical production, the rapidly expanding field of personalized medicine is contributing significantly to the growth of the cell culture market. Personalized medicine, which tailors medical treatment based on an individual’s genetic profile, is transforming drug development and disease management. Researchers are now utilizing cell culture to create complex, customized disease models based on patients’ cells, enabling a more accurate analysis of genetic makeup. This precision in drug testing improves treatment outcomes, reduces side effects, and increases the chances of successful therapies.
Furthermore, the increasing demand for vaccines and growing healthcare awareness are expected to support steady market growth. Government initiatives, such as India’s “Nishank” Drug Discovery Hackathon launched in July 2020, are also fostering drug discovery and innovation, further driving the demand for advanced cell culture techniques.
Research into personalized medicine continues to intensify, with oncology emerging as one of the most lucrative areas due to disease heterogeneity and the rising number of approved biomarkers. Immunology and neurodegenerative diseases are also receiving considerable attention from pharmaceutical and biopharma companies, highlighting the pivotal role of cell culture in advancing these fields.
As personalized medicine becomes a cornerstone of modern healthcare, the cell culture market is set to benefit from its integral role in this transformative sector. The market’s growth reflects a broader trend toward precision medicine, with cell culture playing a critical role in driving innovation, improving drug development, and enhancing patient outcomes.
Key Takeaways from the Market Study:
The global market value is estimated to total USD 44,593.1 million in 2034.
By phase, the commercial segment is projected to lead the market, growing at a CAGR of 3.9% during the forecast period.
By end user, the biotechnology and pharmaceutical companies segment is set to grow at 6.0% CAGR through 2034.
North America accounted for a prominent value share of 36.8% in 2023.
The United States is set to record a CAGR of 3.0% through 2034.
Revenue in China is poised to rise at 7.9% CAGR between 2024 and 2034.
“Researchers and biotechnologists are adopting sustainable and animal-free cell culture technologies. This transition aims to reduce reliance on animal-derived products and mitigate the environmental impact of cell culture processes.” – says a lead analyst of Future Market Insights (FMI).
Leading companies are implementing tactical approaches, such as mergers and acquisitions, business extensions, and new product creation, in order to broaden their range of offerings and fortify their position in the market. For instance,
In July 2023, With GS-CHO cell lines, Lonza introduced the TheraPRO CHO Media System, a new platform for cell culture that streamlines procedures and maximizes output and protein quality.
In June 2021, Bio-Rad Laboratories, Inc. collaborated with Seegene, Inc. for the clinical development and commercialization of molecular diagnostic tools for infectious diseases.
Key Companies Profiled:
Thermo Fisher Scientific Inc.
Merck KGaA (Sigma-Aldrich Co., LLC).
Danaher Corporation (Cepheid)
Agilent Technologies, Inc.
Bio-Rad Laboratories
STEMCELL Technologies
Lonza AG
Corning Incorporated
Eppendorf AG
FUJIFILM Irvine Scientific, Inc.
Sartorius AG
Getinge AB
HiMedia Laboratories
Cellexus
Biospherix Ltd.
PromoCell GmbH
Bio-Techne Corporation
Key Market Segments:
By Product:
Consumables
Media
Serum Containing Media
Serum Free Media
Protein Expression Media
Stem Cell Media
Hybridoma Media
Primary Cell Media
Insect Cell Media
Immunology Media
CHO Cell Culture Media
HEK Media
BHK Media
Protein Free Media
Chemically Defined Media
Sera
Fetal Bovine Sera (FBS)
Adult Bovine Sera (ABS)
Other Animal Sera
Reagents
Growth Factors
Supplements
Buffers & Chemicals
Cell Dissociation Reagents
Cryoprotective Agents
Other Reagents
Cell Lines
CHO
HEK
Stem Cells
Hematopoietic (Blood-Forming) Stem Cells (HSC)
Skeletal Muscle Stem Cells
Mesenchymal Stem Cells
iPSCs
Lymphocytes
Dendritic Cells
Pancreatic Islet Cells
CAR-T Cells
Equipment
Supporting Equipment
Filtration Systems
Cell Counters
Carbon Dioxide Incubators
Centrifuges
Autoclaves
Microscopes
Biosafety Cabinets
Other Supporting Equipment
Bioreactors
Static Culture system
Hollow Fiber Bioreactor System
Stirred Bioreactor Systems
Perfusion Bioreactor Systems
Microcarrier Based Systems
Suspension Culture Systems
Storage Equipment
Refrigerators & freezers
Cryostorage Systems
Other Equipment
Cell Isolation System
Automated Cell Processing Systems
Cryopreservation Systems
Cell Characterization & analysis systems
Automated Filling & Packaging Systems
Automated Liquid Handing Systems
Cultureware
Vessels
Roller/Roux Bottles
Cell Stacks
Multiwell Plates
Flasks
Petri Dishes
Accessories
By Application:
Cell Therapy
Gene therapy
Protein Production
Other Applications
By Phase:
Clinical/Research & Development
Research
Pre-Clinical
Clinical
Commercial
By End User:
Biotechnology and Pharmaceutical Companies
Contract Research Development & Manufacturing Organizations (CDMO)
Contract Research Organizations (CROs)
Academic and Research Institutions
By Region:
North America
Latin America
East Asia
South Asia and Pacific
Western Europe
Eastern Europe
Middle East and Africa
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The grass fed beef market is anticipated to secure a valuation of USD 12.4 billion in 2023 and is predicted to reach USD 20.4 billion by 2033. The market is estimated to register a CAGR of 5% during the forecast period.
The grass-fed beef market is anticipated to expand due to a growing awareness of health benefits and the rising popularity of balanced diets, coupled with increased online sales of bulk food ingredients.
However, environmental concerns regarding the ecological impact of grass-fed beef remain significant. While this meat is often regarded as a sustainable option, grass-fed cattle require approximately nine acres of land for grazing—three times more than conventional beef cattle—and consume 35% more water and 30% more land compared to their grain-fed counterparts. Furthermore, producing one pound of grass-fed beef generates 500% more greenhouse gases than conventional beef.
As consumers become more conscious of their eating habits and seek sustainable manufacturing practices in light of escalating carbon emissions, sales of grass-fed beef may face challenges.
Which are the Key Factors Influencing the Global Market?
Health and Nutrition: The increasing demand for healthy alternatives influences the global market. Grass fed beef is rich in omega-3 acids, antioxidants, and lower fat content with rich nutrition.
Sustainability and Animal Welfare: Consumers are concerned about environmental impacts and animal welfare, increasing the demand for grass fed beef. Consumers are regulating strict rules toward animal cruelty and choosing eco-friendly options.
Taste and Quality: Various end users prefer grass-fed beef to conventional beef due to its flavor, taste, and texture. The food sector provides natural flavor, natural taste, and high-quality products to meet consumers’ requirements.
Labeling and Marketing: Food manufacturers are concerned about the marketing and labeling of products. These labels assure them to sell their products to increase revenue. These manufacturers enhance transparency related to their products to their consumers to build trust among them.
Local and Organic Movements: Consumers are growing their interest in organic and local food. Further, they visit local farmers to learn about sustainable agriculture practices and produce eco-friendly products.
These are a few factors flourishing the global market during the forecast period.
Key Takeaways:
The grass fed beef market is estimated to register a CAGR of 5% with a valuation of USD 20.4 billion by 2033.
The United States is anticipated to secure a maximum share of 29.5% during the forecast period.
Germany is capturing a significant share of 14.5% of the global market by 2033.
In the historical period, the market registered a valuation of USD 11.9 billion in 2022 with a CAGR of 2.9%.
The food service sector is leading the global market by capturing a maximum share by 2033.
With a share of 0.9%, Australia is significantly driving the global market by 2033.
How Key Players are Adding Values in the Global Market?
Key players innovate advanced products by investing significantly in research and development activities. These players play a vital role in expanding the global market through several marketing methodologies. These marketing methodologies are mergers, acquisitions, partnerships, product launches, and collaborations.
Key players focus on developing high-quality, sustainable products to reduce carbon emissions and attract consumers’ requirements. They are distributing their products on e-commerce websites, retail shops, and social media platforms to increase their sales volume.
Recent Developments in the Global Market
Clearview Valley Farm is specialized in grass-finished and grass-fed beef. The company offers consumers sustainable and organic farming products to expand their business portfolio.
Strauss Brands produces various beef products such as roasts, ground beef, and steaks to expand its portfolio and enhance the business. They are direct sales and deliver their products from the farm to the consumer’s doorsteps.
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
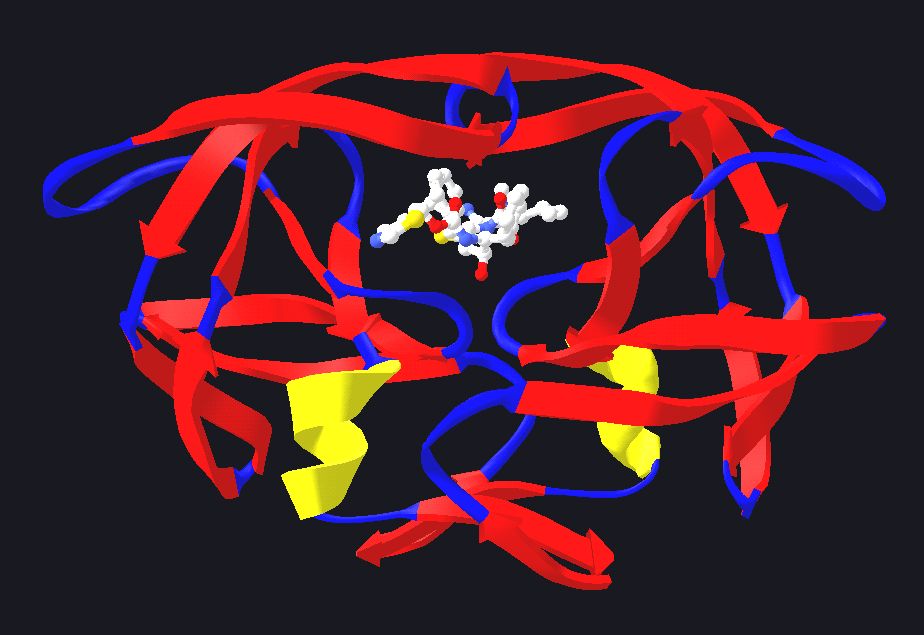
The global protease industry is poised for significant growth, with an estimated market value of USD 2,263.8 million in 2024, and it is projected to reach USD 4,797.6 million by 2034, reflecting a compound annual growth rate (CAGR) of 8.0% over the forecast period from 2024 to 2034. Proteases, a class of enzymes that break down proteins into smaller peptides, are expected to experience rising demand due to their extensive applications across various industries. The food sector, in particular, stands as a major growth driver, with proteases increasingly used to enhance flavor, texture, and nutritional value, while promoting digestive health. As urbanization accelerates and lifestyles become more hectic, the emphasis on gut health will likely push further protease adoption, especially in the food and beverage industry.
Among the diverse proteases, enzymes such as bromelain, ficin, actinidin, papain, and calpain are most commonly utilized in the food industry. These proteases are especially valuable in meat processing, where they improve meat tenderness by breaking down structural proteins in connective tissues. The incorporation of proteases into food products enables the creation of better-textured, more flavorful, and more nutritious food items, making them a preferred choice for food manufacturers and suppliers. Additionally, the growing demand for functional foods and health supplements further enhances the prospects of the protease market, as these enzymes are increasingly sought for their roles in digestion and metabolism support.
The growth potential for protease enzymes in food industry is massive. The massive demand for protease in the food industry is because of its flavour and its ability to enhance the texture. Apart from that, they also aid in improving the metabolism process, improving the nutritional value and solubility of the food. Protease also assists in improving the functional quality, texture, and coagulation of the food products.
Rapid urbanisation is also believed to be one of the major drivers of the market. Owing to busy lifestyle, people hardly get time to concentrate on physical exercise. This gradually leads to increase in weight, and people start developing health complications. The consumption of protease ensures that the gut health remains strong. This might increase the sales of protease during the forecast period.
From the manufacturers point of view, the production of protease is quite an affordable process. Thus, with surge in the awareness of protease, the manufacturers can easily scale up the production through resource optimisation. This would reduce the demand supply gap in the future. The application of protease in non-food sector like pharmaceutical and detergents are also expected to surge the market share
Moreover, protease is witnessing massive demand in the dairy products market. Protease is used to avoid coagulation of milk. Dairy products market represents huge scope for future growth of protease market as diary products market is valued at USD 650 billion as of 2022.
However, the market growth might be challenged owing to the lack of availability of plant and animal protease. Furthermore, lack of awareness regarding the benefits offered by protease might further challenge the market growth. Moreover, the extraction of protease is a costly and time-consuming process, which is also a constraint for the market growth.
North America is expected to be the largest market as per regional analysis. Developed sectors, coupled with large number of people suffering from stomach diseases makes North America an attractive market. Apart from that, the availability of key players in the region also makes North America a huge market. Moreover, the region has been witnessing massive demand for processed food and animal feed, which makes use of protease. Currently, North America is followed by Europe.
However, Asia Pacific is expected to be the fastest growing market during the forecast period. Rapid urbanisation, coupled with change in the consumption patterns and lifestyle are expected to be the major factors surging the market growth. Apart from that, government investments that are majorly focused on physical well-being are expected to surge the market share in the region.
“The protease market is on a solid growth trajectory, driven by advancements in food technology and the growing consumer preference for health-oriented products. As proteases become increasingly vital in food, supplements, and even pharmaceuticals, industry players must focus on enhancing product efficiency while navigating the challenges of production costs and regulatory requirements. Companies that innovate in enzyme applications and production techniques will be well-positioned to capture a significant share of this expanding market,” says Nandini Roy Choudhury, Client Partner at Future Market Insights.
Key Takeaways:
The protease market is set to grow from USD 2,263.8 million in 2024 to USD 4,797.6 million by 2034, with a CAGR of 8.0% during the forecast period.
Proteases play an important role in improving food quality by enhancing flavor, texture, and nutritional content, leading to their increased use in the food and beverage industry.
Key protease types such as bromelain, papain, ficin, actinidin, and calpain are widely used in the tenderization of meat and other food applications.
With the growing focus on gut health and wellness, proteases are gaining traction in dietary supplements and functional foods.
How is improving Meat Tenderization by Protease Creating Scope for Market Growth?
Meat consumers are often worried about the tenderness and quality of the meat they consume. Tenderness in meat is influenced by connective tissue, sarcomere length, and the muscle’s proteolytic potential. Protease enzymes are widely used to ensure the meat is tenderized properly.
Different proteases, such as bromelain, ficin, actinidin, papain, and calpain, are commonly used in the food industry to improve meat tenderness through proteolytic destruction. As protease is vital for decomposing structural proteins in connective tissues, which reduces meat hardness, food vendors and producers are extensively using proteases treatment.
Can Protease play a Pivotal Role in Application in Infant Formula?
The intact proteins denatured by stomach acid and attacked by endogenous proteases in the stomach initiate a digestive process that continues in the small intestine. This eventually leads to the release and complete absorption of amino acids by the intestinal epithelia.
On the other hand, young newborns are still developing minimal stomach acid, and have little protease activity.
A variety of proteases produced by the newborn contribute to catalytic activity, helping newborns to adequately digest and absorb milk proteins.
Protein digestion, specifically, in infants has some crucial implications for baby nutrition. Infants that drink animal-derived milk are more likely to develop allergies as a result of animal contamination. As a result, producers are developing protease for infant formulas, as infants struggle to make enough protease.
For instance, Novozymes’ Formea® is a Kosher/Halal-certified baby formula that is low-allergenic, neutral-tasting, and low-allergenic.
Rising Pharmaceutical and Therapeutic Applications Pushing the Sales
Expansion of the healthcare industry will positively affect the protease market growth because of the numerous benefits they provide. These include boosting the immune system, healing skin burns, preventing inflammatory bowel illnesses, and stomach ulcers.
Industries, such as animal feed, where protease is used to improve nutritional characteristics of fodder and maintain gut health, account for significant portion of market.
For synthesis of many APIs, enzymes have largely replaced traditional chemical-based methods, such as the production of various semi-synthetic antibiotics. There are also effects visible in kinetic resolution of active enantiomers of drugs, synthesis of enantiomerically pure forms of amino acids.
Till date, the Food and Drug Administration (FDA) in the United States has approved 12 protease medicines. A number of next-generation or wholly new proteases are in clinical trials. Protease’s growing popularity and acceptability in the pharmaceutical business is propelling the market forward.
How will Stringent Regulatory Framework affect the Protease Market?
Manufacturers of enzymes like protease, lipase and others need to comply with the regulations imposed by various governing agencies. Some of them are Association of Manufacturers & Formulators of Enzyme Products, Enzyme Technical Association, and EU REACH Regulation.
The food chemicals codex requires the use of enzymes in the food business to follow certain rules. Despite the fact that industrial enzymes are subject to strict restrictions in the Canada, the U.K., and the European Union, there is no unified regulatory system for the use. As a result, manufacturers must adhere to strict labelling, packing, and mixing restrictions before releasing items into the market. This might challenge the wide applications of enzymes.
Growth Drivers:
Several factors are fueling the growth of the protease market. The rising demand for processed and convenience foods, paired with the increasing awareness about health and nutrition, is a major driver. Proteases are valued for their role in improving the digestibility and nutritional properties of food, thus aligning with the global shift toward healthier eating habits. The ongoing trend of personalized nutrition, where consumers seek tailored solutions for digestion and metabolism, is further accelerating the adoption of protease-based products.
Moreover, the growth of the dietary supplement industry, driven by rising consumer interest in functional foods, is expected to be a key factor in boosting protease demand. As individuals become more health-conscious and seek natural ways to improve gut health, proteases, which support the breakdown of proteins in the digestive system, are becoming increasingly popular. The versatility of proteases across various applications—from food production to pharmaceuticals—continues to expand market opportunities.
Industry Challenges:
Despite the promising growth prospects, the protease market faces certain challenges. One of the primary obstacles is the high cost of production, particularly for specialty proteases used in niche applications such as pharmaceuticals and personal care products. Additionally, fluctuations in the availability of raw materials, such as plant sources for certain proteases (e.g., bromelain and papain), can lead to supply chain issues and price volatility. Moreover, stringent regulations concerning enzyme use in food and supplements can limit the pace at which new products are developed and brought to market.
Another challenge is the increasing competition among protease manufacturers, particularly as more players enter the market. While the market is growing, the need for innovation in enzyme production, along with an emphasis on quality, purity, and sustainability, is crucial for companies to maintain a competitive edge. The development of more efficient and cost-effective enzyme production methods, such as fermentation-based processes, may help address some of these challenges.
Competition Landscape
The protease market is experiencing significant growth, driven by key players such as Novozymes, DuPont Nutrition & Biosciences, DSM, BASF SE, Chr. Hansen Holding A/S, Roche CustomBiotech, Amano Enzyme Inc., and others. These companies are actively investing in the development of advanced, stable protease production methods.
A major focus for these companies is the creation of protease through modern, sustainable, and readily accessible technologies, in line with current market demands. Novozymes, a leader in biological solutions, based in Denmark, is renowned for its robust and efficient production methods. The company is meeting the growing demand for conventional protease forms that can be easily integrated into a variety of products.
Examples of recent developments include:
In 2022, leading academic institutions and global enzyme manufacturers collaborated to create a more efficient and novel protease solution. This solution is customizable for use in precision agriculture and biopharmaceutical applications, aiming to overcome challenges in drug formulation and other industries.
In 2021, Novozymes introduced the “Formea” range of ingredients designed for the sustainable production of protein beverages. By incorporating Formea into ready-to-drink protein beverages, the need for synthetic additives was eliminated, while still offering the health benefits similar to whey protein hydrolysates.
Leading Brands
Novozymes
DuPont Nutrition & Biosciences
DSM
BASF SE
Chr. Hansen Holding A/S
Roche CustomBiotech
Amano Enzyme Inc.
Sunson Industry Group Co., Ltd.
Advanced Enzyme Technologies
Specialty Enzymes & Probiotics
AB Enzymes
Bioseutica
Antozyme Biotech
Tex Biosciences
Bestzyme
Infinita Biotech
Shandong Longda Bio-Products Co., Ltd.
Jiangsu Boli Bioproducts Co., Ltd.
Enzyme Solutions
Creative Enzymes
Others
Key Segments of the Report
By Form:
As per form, the industry has been categorized into Liquid, Powder, and Granules.
By Product type:
As per product type, the industry has been categorized into Animal-based [Trypsin, Renin, Pepsin, Others (chymotrypsin, thrombin, elastase, etc.)], Plant-based [Papain, Keratinases, and Others (Ficin, Bromelain, etc.)], Microbial-based [Alkaline, Acid stable, Neutral, and Others (Proteinase K, Peptidase, etc.)].
By End Use Application:
This segment is further categorized into Dairy Products, Brewing, Meat Products and Processing, Bakery & Confectionary (Breads, Cookies & Crackers, Pastries, Waffles, and Others), Baby/Infant Food, Oil & Fats Processing, Starch and Grain Processing, Fruits and Vegetable Processing, Cheese Processing, Dietary Supplements, Pharmaceutical Products, Personal Care Products, and Animal Nutrition.
By Region:
Industry analysis has been carried out in key countries of North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Central Asia, Russia & Belarus, Balkans & Baltic Countries and the Middle East & Africa.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.