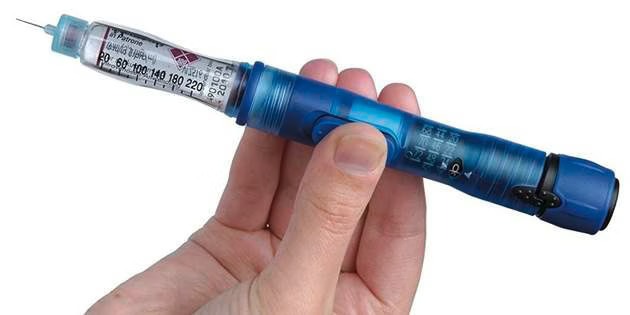
Auto-Injectors Market Set to Reach USD 23.31B with Healthcare Shift

The auto-injectors market is forecast to reach a value of USD 5.71 billion in 2025 and is expected to expand to USD 23.31 billion by 2035, growing at a steady compound annualgrowth rate of 8.2% over the period. The market has gained considerable momentum with rising global incidences of chronic illnesses that require routine, precise drug delivery.

The auto-injectors market is experiencing significant growth, driven by increasing demand for self-administered drug delivery systems. Auto-injectors are medical devices designed to deliver a specific dose of medication via injection, simplifying the process for patients who need regular drug administration. These devices have become particularly important for managing chronic illnesses such as diabetes, rheumatoid arthritis, and multiple sclerosis. With healthcare systems becoming more patient-centric, the popularity of auto-injectors continues to rise, offering both convenience and safety. The market’s expansion is also being influenced by technological advancements that enhance ease of use, reliability, and portability.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1642

Market Trends

A notable trend in the auto-injectors market is the shift toward smart and connected devices. Smart auto-injectors equipped with digital sensors and Bluetooth connectivity are gaining traction as they allow users and healthcare providers to track medication adherence. This technological innovation aligns with the broader digital health movement, which aims to enhance patient outcomes through better monitoring and data collection. Additionally, the demand for disposable auto-injectors is increasing due to their hygiene benefits and ease of use, especially for emergency medications such as epinephrine. Environmentally conscious designs and recyclable materials are also becoming a priority among manufacturers as sustainability becomes a core industry focus.

Driving Forces Behind Market Growth

Several key factors are propelling the growth of the auto-injectors market. One of the primary drivers is the rising prevalence of chronic and life-threatening diseases that require consistent and timely medication. Auto-injectors offer a solution that empowers patients to manage their health conditions at home, reducing the need for frequent hospital visits. Moreover, the aging population and the growing burden on healthcare infrastructure further necessitate the adoption of self-injection technologies. Government initiatives to improve access to biologics and the approval of biosimilars have also contributed to market growth by expanding the range of treatments available in auto-injector form. The convenience offered by these devices is also encouraging pharmaceutical companies to integrate them into their drug delivery strategies.

Challenges and Opportunities

Despite the promising outlook, the auto-injectors market faces several challenges. One of the main hurdles is the high cost associated with auto-injectors, which can limit their accessibility in low- and middle-income countries. Additionally, device malfunctions or user errors can compromise the safety and effectiveness of treatment. There is also regulatory scrutiny concerning device reliability and patient safety, which can delay product approvals. However, these challenges present opportunities for innovation. Manufacturers are investing in user-friendly designs and cost-effective production methods to overcome these barriers. The growing interest in personalized medicine and patient-specific treatment protocols also offers new avenues for customized auto-injector solutions, creating untapped potential in niche therapeutic areas.

Recent Industry Developments

Recent developments in the auto-injectors market reflect a dynamic and competitive landscape. Pharmaceutical companies are collaborating with medical device manufacturers to co-develop integrated drug delivery systems. For instance, the introduction of dual-chamber auto-injectors has improved drug stability and simplified the reconstitution process before injection. Another significant development is the approval of new biologics and biosimilars, which are increasingly being paired with auto-injectors for patient convenience. Regulatory bodies in major markets such as the U.S. and Europe are also streamlining the approval process for combination products, encouraging innovation. Furthermore, the COVID-19 pandemic has accelerated the demand for self-administered treatments, prompting faster development and deployment of auto-injector devices.

Regional Analysis

Geographically, the auto-injectors market demonstrates varied growth patterns across regions. North America holds a dominant share due to advanced healthcare infrastructure, high adoption of novel drug delivery systems, and favorable reimbursement policies. The U.S. in particular remains a leader in terms of both consumption and innovation in auto-injectors. Europe follows closely, driven by a strong focus on chronic disease management and increasing awareness of self-injection benefits. The Asia-Pacific region is emerging as a lucrative market, propelled by a growing patient population, increasing healthcare expenditure, and rising acceptance of self-care medical devices. Countries like China and India are witnessing robust demand for affordable and easy-to-use auto-injectors, encouraging both local and international players to expand their presence.

Competitive Outlook

The competitive landscape of the auto-injectors market is characterized by a mix of established players and innovative startups. Companies are competing based on product reliability, ease of use, drug compatibility, and pricing. Research and development efforts are focused on creating more compact, intuitive, and multi-dose devices. Strategic partnerships, mergers, and acquisitions are common as firms seek to strengthen their portfolios and broaden market reach. Patent protection and proprietary technologies also play a critical role in maintaining competitive advantage. Moreover, companies are increasingly investing in user education and training programs to enhance the adoption of auto-injectors among patients and healthcare providers.

Top Companies

Several prominent companies are shaping the trajectory of the auto-injectors market. These include global pharmaceutical giants and specialized medical device firms. Pfizer Inc., Amgen Inc., and Eli Lilly and Company are leading pharmaceutical companies that offer auto-injectors for various therapeutic applications. On the device manufacturing side, companies like Ypsomed, SHL Medical, and Owen Mumford are known for their advanced and user-centric auto-injector technologies. Emerging players are also entering the market with innovative features such as customizable dose settings, audio-visual cues, and app integrations. Continuous investment in product development and global distribution networks enables these companies to maintain their leadership positions while catering to diverse patient needs.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/auto-injectors-market

Segmentation Outlook

The auto-injectors market can be segmented based on type, application, end user, and distribution channel. In terms of type, the market includes disposable and reusable auto-injectors. Disposable auto-injectors dominate the segment due to their ease of use and minimal maintenance. Reusable auto-injectors, however, are gaining popularity among cost-conscious users who require long-term treatment. By application, the market spans conditions such as anaphylaxis, rheumatoid arthritis, multiple sclerosis, and diabetes. The rising prevalence of these diseases is fueling segment growth. End users primarily include home care settings, hospitals, and clinics, with home care showing the fastest growth. Distribution channels comprise hospital pharmacies, retail pharmacies, and online platforms, with digital sales channels expanding rapidly due to increasing consumer preference for online convenience and privacy.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
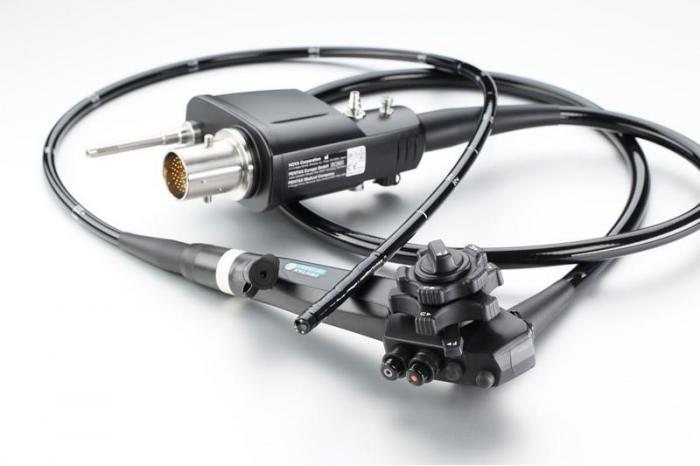
 

Flexible Endoscopes Market to Hit USD 18.6B by 2035

The global flexible endoscopes market is estimated to be valued at USD 10,186.6 million in 2025 and is projected to reach USD 18,589.8 million by 2035, registering a compound annual growth rate (CAGR) of 6.2% over the forecast period. The current market is driven by the rising prevalence of gastrointestinal, respiratory, and urological diseases alongside heightened demand for minimally invasive diagnostic and therapeutic procedures.

The flexible endoscopes market has emerged as a critical segment within the global medical devices industry. These instruments are essential for diagnostic and therapeutic procedures across various medical fields, including gastroenterology, pulmonology, and otolaryngology. Unlike rigid endoscopes, flexible variants offer enhanced maneuverability and access to difficult anatomical regions, leading to improved patient outcomes and procedural efficiencies. The market is driven by technological innovations, an aging population requiring more frequent diagnostic interventions, and the rising prevalence of gastrointestinal and respiratory diseases.

Healthcare providers are increasingly adopting flexible endoscopes due to their minimally invasive nature, which reduces recovery time, surgical complications, and hospitalization duration. These instruments are instrumental in performing endoscopic retrograde cholangiopancreatography (ERCP), bronchoscopy, colonoscopy, and other critical procedures. Furthermore, growing demand for outpatient endoscopic procedures is expanding the scope and reach of the flexible endoscopes market, propelling it into a period of significant growth.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14361

Market Trends

Several key trends are shaping the trajectory of the flexible endoscopes market. One of the most prominent developments is the integration of advanced imaging technologies, such as high-definition (HD) video and narrow band imaging (NBI), which allow for more precise diagnostics. These innovations are helping healthcare professionals detect early-stage cancers and other conditions that may not be visible through traditional imaging methods.

Another notable trend is the increasing shift toward single-use flexible endoscopes. These disposable instruments are gaining traction as they eliminate the risk of cross-contamination and infection, which remains a concern with reusable devices despite stringent sterilization protocols. In addition, they offer convenience and cost-effectiveness in high-volume clinical settings.

Artificial intelligence (AI) is also beginning to influence the flexible endoscopes market. AI-powered software solutions are being developed to assist in real-time diagnosis, automate image interpretation, and reduce human error. This emerging technology has the potential to drastically improve clinical decision-making and overall diagnostic accuracy. Moreover, tele-endoscopy and remote diagnostics are also on the rise, especially in underserved regions and during public health emergencies, enhancing accessibility and scalability.

Challenges and Opportunities

Despite its robust growth, the flexible endoscopes market faces a number of challenges. One of the primary hurdles is the high cost associated with acquiring and maintaining endoscopic equipment. Hospitals and clinics, particularly in developing nations, often struggle to justify the capital expenditure required for advanced flexible endoscopes and their associated software and accessories.

Sterilization and reprocessing are other significant issues. Reusable flexible endoscopes require meticulous cleaning and disinfection to prevent healthcare-associated infections. Any lapses in this process can lead to serious consequences, including regulatory penalties and loss of patient trust. Although single-use devices are a viable alternative, their higher per-unit cost and environmental impact are concerns that manufacturers must address.

Nevertheless, these challenges present opportunities for innovation. Companies investing in cost-efficient manufacturing methods and sustainable materials for disposable endoscopes can capture a growing market segment. Similarly, offering comprehensive service packages and financing options can help healthcare providers overcome budget constraints. Emerging markets also present untapped potential, as improving healthcare infrastructure and growing medical tourism are likely to boost demand for flexible endoscopic procedures.

Key Regional Insights

The flexible endoscopes market exhibits distinct regional dynamics, influenced by healthcare infrastructure, patient demographics, and regulatory frameworks. North America remains a leading market, supported by a well-established healthcare system, strong reimbursement policies, and a high prevalence of chronic diseases. The United States, in particular, continues to invest heavily in medical technology, including endoscopic innovations and AI integration.

Europe is another significant contributor to the global flexible endoscopes market. Countries like Germany, the United Kingdom, and France are at the forefront of adopting minimally invasive surgical techniques, fueling demand for advanced endoscopic tools. Additionally, supportive government policies and a growing aging population are key factors driving market expansion in the region.

Asia-Pacific is emerging as the fastest-growing market for flexible endoscopes. Rapid economic development, urbanization, and increased healthcare spending are creating a fertile environment for market growth. Japan and South Korea are early adopters of medical technology, while China and India are witnessing rising demand due to expanding hospital networks and greater health awareness among their populations. Meanwhile, Latin America, the Middle East, and Africa offer long-term growth opportunities as international manufacturers expand their presence in these underpenetrated regions.

Competitive Outlook

The flexible endoscopes market is highly competitive, characterized by constant innovation and strategic partnerships. Leading players are focusing on developing technologically advanced products that enhance diagnostic accuracy and procedural efficiency. To maintain a competitive edge, companies are investing in research and development, often collaborating with academic institutions and hospitals for clinical trials and product testing.

Mergers and acquisitions are another common strategy within the industry, enabling companies to broaden their product portfolios and enter new geographic markets. Additionally, manufacturers are increasingly emphasizing after-sales services, such as maintenance contracts and staff training, to build long-term relationships with healthcare providers.

New entrants are also finding opportunities in niche areas, particularly in the single-use segment and AI-enabled diagnostics. By focusing on specific unmet needs and offering competitive pricing, smaller companies can carve out a share of the flexible endoscopes market, although they face barriers in terms of regulatory approvals and brand recognition.

Top Companies

The flexible endoscopes market is dominated by a number of well-established players known for their technological excellence and global reach. Olympus Corporation is widely recognized as a pioneer in endoscopic technology, offering a comprehensive portfolio that spans gastrointestinal, urological, and respiratory applications. The company consistently invests in R&D to maintain its leadership position.

Another major player is Karl Storz, which has a strong reputation for delivering high-quality endoscopic instruments and imaging systems. Its commitment to innovation and customer service has made it a trusted name in both hospital and outpatient settings. Boston Scientific is also a key participant in the market, particularly in the gastrointestinal segment, where its minimally invasive solutions are widely used.

Pentax Medical, a division of Hoya Corporation, continues to make strides in digital imaging and flexible endoscopy, with a focus on user-friendly designs and infection prevention. Fujifilm Holdings Corporation is gaining traction through its advanced imaging technologies and expanded product offerings. Other notable companies include Ambu A/S, which is a market leader in single-use endoscopes, and Smith & Nephew, known for its contributions to minimally invasive surgery.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/flexible-endoscopes-market

Segmentation Outlook

The flexible endoscopes market can be segmented based on product type, application, end-user, and geography. By product type, the market includes video endoscopes, fiberoptic endoscopes, and others. Video endoscopes are currently the most dominant segment, driven by superior imaging capabilities and increased usage across specialties.

In terms of application, the market is divided into gastrointestinal, respiratory, urological, and ENT procedures, among others. Gastrointestinal applications account for the largest share due to the high incidence of colorectal cancer, ulcers, and related conditions. The respiratory segment is also expanding rapidly with the growing prevalence of chronic obstructive pulmonary disease (COPD) and lung cancer.

End-users of flexible endoscopes primarily include hospitals, ambulatory surgical centers, and specialty clinics. Hospitals remain the largest user base owing to their ability to invest in advanced equipment and provide comprehensive care. However, ambulatory surgical centers are witnessing a surge in demand due to their convenience, lower costs, and shorter wait times.

Geographically, segmentation reflects varying growth rates and market maturity across regions. While developed markets continue to dominate in terms of revenue, emerging regions are expected to offer the highest growth rates over the next few years, supported by favorable demographics and increasing healthcare investments.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
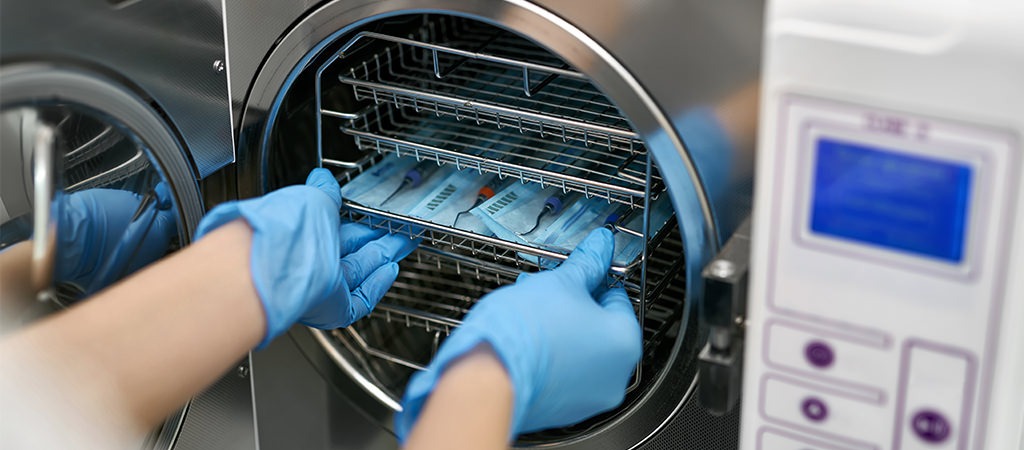
 

Dental Autoclaves Market Expands at 5.2% CAGR Through 2035

The global dental autoclaves market is estimated to be valued at USD 335.9 million in 2025. It is projected to reach USD 557.7 million by 2035, registering a compound annual growth rate (CAGR) of 5.2% over the forecast period.

The dental autoclaves market plays a pivotal role in modern dental practices by ensuring the sterilization of instruments and preventing the spread of infections. As dental hygiene and patient safety continue to receive heightened attention, the demand for high-quality sterilization solutions is rising. Dental autoclaves use high-pressure steam to sterilize tools, eliminating bacteria, viruses, and other pathogens. Their role is crucial not only in dental clinics but also in hospitals and specialized laboratories. The increasing emphasis on cross-contamination prevention and compliance with strict health regulations has significantly bolstered the adoption of dental autoclaves globally.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14569

Size & Trends

The dental autoclaves market has been witnessing steady growth, driven by the global rise in oral health awareness and the expansion of dental care infrastructure. Technological advancements are another major contributor, leading to the development of energy-efficient and user-friendly autoclaves. A growing number of dental procedures, both restorative and cosmetic, is increasing the volume of instruments that require sterilization, thereby driving demand. Another trend is the rising adoption of portable and compact autoclave units, especially in small clinics and mobile dental units. Furthermore, the integration of automation and digital monitoring capabilities into autoclaves is helping dental professionals ensure optimal performance and reliability.

Key Highlights

Among the key highlights of the dental autoclaves market is the shift towards eco-friendly sterilization solutions. Manufacturers are focusing on reducing the carbon footprint of these devices by improving energy efficiency and water usage. Additionally, the demand for Class B autoclaves, known for their superior sterilization capabilities, is increasing significantly. These autoclaves offer better performance, especially for hollow instruments and wrapped items. Innovations such as touch-screen interfaces, programmable cycles, and real-time performance tracking are becoming common in newer models. The increased focus on infection control in the aftermath of the COVID-19 pandemic has further emphasized the need for advanced sterilization devices, contributing to heightened market awareness and growth.

Challenges and Opportunities

Despite its promising growth, the dental autoclaves market faces several challenges. The high initial cost of advanced autoclave units remains a barrier for smaller dental practices and clinics, particularly in developing regions. Maintenance and calibration costs also add to the operational burden. Additionally, improper usage or overloading of autoclaves can lead to ineffective sterilization, posing a threat to patient safety and clinic reputation. However, these challenges also open up opportunities for innovation. There is potential for developing cost-effective models without compromising on performance, especially tailored to the needs of small and mid-sized clinics. Moreover, increasing investments in dental health infrastructure across emerging economies provide a fertile ground for market expansion. Training programs that educate practitioners about optimal sterilization practices can also enhance product usage and market penetration.

Key Benefits for Stakeholders

The dental autoclaves market offers a variety of benefits for stakeholders across the healthcare spectrum. For dental practitioners, the use of autoclaves ensures compliance with safety regulations and enhances patient trust. Clinics and hospitals benefit from the reduced risk of cross-infection and improved operational efficiency. For manufacturers, the evolving demand landscape offers opportunities to innovate and cater to both high-end and cost-sensitive segments. Distributors and suppliers also stand to gain from the steady increase in demand for autoclaves and associated maintenance services. Furthermore, patients indirectly benefit from safer treatment environments and reduced chances of infection transmission. Regulatory bodies also find it easier to implement and monitor infection control protocols when reliable sterilization technologies are widely adopted.

Market Share by Geographical Region

Geographically, the dental autoclaves market exhibits varying growth patterns across regions. North America holds a prominent share, owing to its advanced healthcare infrastructure, high awareness levels, and stringent regulatory standards. The presence of leading manufacturers and continuous technological advancements also support market growth in the region. Europe follows closely, with countries such as Germany, the UK, and France prioritizing dental hygiene and sterilization practices. The Asia-Pacific region is emerging as a high-growth market, driven by increasing dental tourism, expanding healthcare infrastructure, and rising awareness about infection control. Countries like China, India, and Japan are witnessing a surge in dental clinics and cosmetic dentistry, fueling demand for autoclaves. Meanwhile, Latin America and the Middle East & Africa show moderate growth but present untapped potential for future expansion.

Competitive Outlook

The dental autoclaves market is characterized by strong competition among established players and new entrants striving to introduce innovative products. Leading companies are investing in research and development to improve sterilization efficiency, reduce cycle times, and enhance user experience. Strategic partnerships, mergers, and acquisitions are commonly observed, enabling companies to strengthen their product portfolios and expand their market presence. Customization options, such as autoclaves with multiple chamber sizes and programmable settings, are being used as differentiators to attract various customer segments. The competitive landscape also sees a focus on after-sales services, including maintenance contracts, training programs, and calibration support, which are crucial in retaining customer loyalty. As market dynamics evolve, companies that offer comprehensive solutions tailored to the practical needs of dental professionals are expected to lead.

Top Companies

Several key players dominate the dental autoclaves market by offering innovative and reliable sterilization solutions. These companies focus on delivering technologically advanced products that cater to a broad spectrum of customer needs. Leading names include Midmark Corporation, which is known for its compact and efficient autoclaves suited for small to medium practices. Melag is another prominent player, recognized for its robust portfolio of Class B autoclaves that combine performance and energy efficiency. Tuttnauer is a globally respected brand offering autoclaves with advanced safety and monitoring features. Other significant companies include W&H Group, SciCan, and Runyes Medical Instrument Co., all of which are expanding their product offerings and distribution networks to capture larger market shares. These companies emphasize compliance with international sterilization standards and often provide integrated software tools for tracking and documentation, adding value for dental professionals.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/dental-autoclaves-market

Segmentation Outlook

The dental autoclaves market can be segmented based on product type, technology, end-user, and geography. In terms of product type, tabletop autoclaves are the most commonly used due to their space-saving design and suitability for small to medium-sized practices. Vertical autoclaves are also popular in settings that require higher sterilization volumes. When segmented by technology, Class B autoclaves are preferred for their advanced sterilization capabilities, followed by Class N and Class S units. The end-user segmentation includes dental clinics, hospitals, academic institutions, and dental laboratories. Dental clinics form the largest consumer base, attributed to the routine need for instrument sterilization. Hospitals and dental schools also represent a significant share, often requiring autoclaves with larger capacity and enhanced features. Regional segmentation, as previously discussed, highlights the diverse adoption patterns and emerging opportunities across different markets.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Softgel Capsules Market to Hit USD 2.21B by 2035 at 5.9% CAGR

The global softgel capsules market is estimated to be valued at USD 1,245.3 million in 2025 and is projected to reach USD 2,209.2 million by 2035, registering a compound annual growth rate (CAGR) of 5.9% over the forecast period.

The softgel capsules market is experiencing a remarkable surge in demand due to the increasing preference for convenient and easy-to-swallow pharmaceutical dosage forms. These capsules are widely used across the pharmaceutical, nutraceutical, and cosmetic industries owing to their versatility and superior bioavailability. Softgel capsules are composed of a gelatin-based shell that encloses a liquid or semi-liquid fill, offering better protection for sensitive ingredients and improved patient compliance. The market continues to expand as consumers and healthcare professionals alike seek more effective and palatable alternatives to traditional tablets and hard capsules.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-15724

Market Trends

One of the most prominent trends shaping the softgel capsules market is the shift toward plant-based and vegan-friendly capsules. As the demand for cruelty-free and vegetarian products rises, manufacturers are investing in the development of gelatin alternatives sourced from seaweed, starch, and other plant derivatives. This innovation aligns with the broader consumer movement toward clean-label and sustainable health products.

In addition, technological advancements in encapsulation processes are enabling the development of multi-phase softgels that can deliver a combination of ingredients with varied release profiles. These advancements enhance therapeutic efficacy and broaden the application scope of softgel capsules in complex treatment regimens. The rise of personalized medicine has also led to a demand for custom-formulated softgels tailored to individual health needs, further influencing the evolution of the market.

Driving Forces Behind Market Growth

Several key factors are propelling the growth of the softgel capsules market. Firstly, the aging global population and the rising incidence of chronic diseases are driving the demand for user-friendly drug delivery systems. Softgel capsules, due to their ease of ingestion and rapid onset of action, are increasingly preferred by elderly patients and individuals with swallowing difficulties.

Secondly, the booming dietary supplement industry is contributing significantly to market expansion. Consumers are becoming more health-conscious and are turning to supplements to maintain wellness and prevent disease. Softgel capsules are a popular choice in this sector due to their aesthetic appeal, longer shelf life, and ability to mask unpleasant tastes or odors.

Moreover, pharmaceutical companies are leveraging softgel capsules for the delivery of lipid-soluble drugs, which are difficult to formulate in solid dosage forms. The enhanced absorption and bioavailability offered by softgels make them a favorable option for new drug development and reformulation of existing medications.

Challenges and Opportunities

Despite the promising outlook, the softgel capsules market faces several challenges. One of the primary concerns is the reliance on animal-derived gelatin, which poses issues for vegetarian and religiously observant populations. Although plant-based alternatives are being explored, they often come with higher production costs and technical limitations that may affect the scalability and stability of formulations.

Another challenge lies in the stringent regulatory landscape that governs the pharmaceutical and nutraceutical industries. Companies must navigate complex approval processes and adhere to rigorous manufacturing standards, which can delay product launches and increase development costs.

However, these challenges also open up new opportunities. The growing emphasis on research and development offers potential for the discovery of innovative encapsulation materials and techniques. Companies investing in sustainable practices and ethical sourcing are likely to gain a competitive edge. Additionally, the expansion of e-commerce and direct-to-consumer models is facilitating broader market access, especially in emerging economies where traditional distribution networks may be limited.

Recent Industry Developments

Recent developments in the softgel capsules market underscore the industry’s dynamic nature. Several leading manufacturers have announced strategic partnerships and acquisitions aimed at expanding their production capabilities and geographic reach. Investments in new production facilities equipped with advanced encapsulation technologies are enabling faster turnaround times and greater customization options.

Furthermore, regulatory approvals for novel softgel formulations are increasing, paving the way for innovative therapies to enter the market. Companies are also focusing on sustainability by adopting eco-friendly manufacturing practices, such as using renewable energy sources and reducing water consumption during production.

In the nutraceutical sector, there’s been a notable increase in the use of softgels for delivering cannabinoids, omega-3 fatty acids, and herbal extracts. These ingredients benefit greatly from the protective and absorption-enhancing properties of softgel capsules, making them a preferred delivery method in this fast-growing segment.

Regional Analysis

The softgel capsules market exhibits varied growth patterns across different regions. North America holds a significant share, driven by the presence of leading pharmaceutical companies, advanced healthcare infrastructure, and high consumer awareness regarding dietary supplements. The United States, in particular, is a major contributor due to its large geriatric population and strong demand for innovative drug delivery systems.

Europe also demonstrates substantial growth, with increasing investments in research and the growing trend of self-medication. Countries like Germany, the UK, and France are prominent markets for both prescription and over-the-counter softgel products.

Asia-Pacific is emerging as a lucrative region due to its expanding middle-class population, rising disposable incomes, and growing health consciousness. Countries such as China, India, and Japan are experiencing a surge in demand for nutraceuticals and pharmaceuticals, boosting the regional softgel capsules market. Moreover, the availability of cost-effective manufacturing facilities makes Asia-Pacific an attractive hub for production and export.

In Latin America and the Middle East & Africa, the market is witnessing gradual growth, driven by improving healthcare systems, increasing prevalence of chronic diseases, and greater access to health supplements.

Competitive Outlook

The competitive landscape of the softgel capsules market is characterized by intense rivalry among key players, each striving to enhance their market presence through innovation and strategic collaborations. Companies are focusing on expanding their product portfolios by introducing new formulations that cater to diverse consumer needs, such as sugar-free, gluten-free, and allergen-free variants.

Brand differentiation is becoming increasingly important as consumers seek products that align with their values, including sustainability and transparency. As a result, companies are investing in brand-building and marketing strategies that emphasize quality, safety, and efficacy.

Mergers and acquisitions are also shaping the competitive dynamics, with larger players acquiring specialized firms to gain access to proprietary technologies and niche markets. This consolidation trend is helping companies streamline operations and enhance their global footprint.

Top Companies

Several companies dominate the global softgel capsules market, leveraging their expertise, R&D capabilities, and robust distribution networks. Notable players include Catalent Inc., which is renowned for its advanced drug delivery technologies and contract manufacturing services. Another key player, Aenova Group, offers a wide range of softgel solutions for pharmaceuticals and dietary supplements.

Other prominent companies include Sirio Pharma, BASF SE, Lonza Group, and EuroCaps Ltd., each contributing significantly to the development and expansion of the market. These companies are actively investing in innovation, sustainability, and capacity expansion to meet the growing global demand for softgel capsules.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/softgel-capsules-market

Segmentation Outlook

The softgel capsules market can be segmented based on type, application, and end-user. In terms of type, the market is broadly divided into gelatin-based and non-gelatin-based softgels. While gelatin-based capsules currently dominate, non-gelatin alternatives are gaining traction due to their suitability for vegan and vegetarian consumers.

By application, the market includes pharmaceuticals, nutraceuticals, and cosmetics. Among these, the pharmaceutical segment holds the largest share due to the widespread use of softgels for delivering prescription medications. However, the nutraceutical segment is growing rapidly, fueled by increasing health awareness and demand for preventative healthcare solutions.

In terms of end-users, the market is segmented into hospitals, clinics, and home care settings. With the rise in self-medication and over-the-counter purchases, home care usage of softgel capsules is becoming increasingly prevalent.

As the softgel capsules market continues to evolve, its trajectory will be shaped by technological innovation, consumer preferences, and regulatory shifts. Companies that prioritize adaptability, sustainability, and consumer-centric strategies are likely to thrive in this dynamic landscape.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Niacin and Niacinamide Market Sees Strong Growth to 2035

The global niacin and niacinamide market demonstrates robust growth momentum, with market valuation reaching USD 1,435.9 million in 2025 and projected to reach USD 2,361.3 million by 2035 at a CAGR of 5.1%. The market outlook remains positive, driven by increasing health consciousness and rising prevalence of lifestyle-related disorders necessitating vitamin B3 supplementation.

The niacin and niacinamide market has witnessed consistent growth due to their increasing utilization in pharmaceuticals, food fortification, and cosmetic products. As essential forms of vitamin B3, niacin and niacinamide play a crucial role in converting food into energy and maintaining healthy skin, nerves, and digestion. With their wide-ranging applications, these compounds are gaining attention from industries focusing on health and wellness. The market’s expansion is driven by a growing awareness of vitamin deficiencies, particularly in developing regions, and a rising demand for functional foods and supplements.

Niacin and niacinamide are often used interchangeably, though they differ slightly in their chemical structure and physiological effects. Niacin, also known as nicotinic acid, is commonly used to manage cholesterol levels, while niacinamide is preferred in skincare products due to its anti-inflammatory properties. Their versatile functionality is prompting manufacturers to explore innovative uses, especially in the cosmeceutical and nutraceutical sectors. As lifestyles become more health-conscious, the demand for vitamin-enriched products continues to rise, providing a significant push to the niacin and niacinamide market.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-4521

Market Trends

Several notable trends are shaping the trajectory of the niacin and niacinamide market. One of the key trends is the surge in dietary supplement consumption. With consumers placing more emphasis on preventive healthcare, vitamins and minerals are being adopted widely to support overall well-being. Niacin and niacinamide are integral ingredients in multivitamins, driving their demand among health-conscious individuals.

Additionally, the cosmetic industry’s interest in niacinamide is growing due to its effectiveness in reducing hyperpigmentation, fine lines, and inflammation. Skincare brands are increasingly incorporating niacinamide into serums, moisturizers, and creams. This shift toward beauty-from-within products has bolstered the compound’s popularity, especially in North America and Asia-Pacific, where beauty and wellness often intersect.

Another trend is the increasing fortification of processed foods with niacin and niacinamide. Governments and food agencies in several countries mandate the addition of these vitamins in staple food products like flour and cereals to combat malnutrition. The niacin and niacinamide market also benefits from innovations in delivery formats such as gummies, effervescent tablets, and functional beverages, which make supplementation more appealing to younger demographics.

Challenges and Opportunities

Despite the market’s growth, several challenges persist. Regulatory hurdles and quality standards imposed by health authorities require strict compliance, especially in pharmaceutical and food applications. Manufacturers must adhere to precise dosage requirements and safety assessments, which can delay product development and market entry. Additionally, the risk of side effects, such as liver toxicity with high niacin doses, raises consumer concerns and may influence purchasing behavior.

However, these challenges also create avenues for innovation and opportunity. For instance, ongoing research into personalized nutrition and bioavailability is opening new doors for the application of niacin and niacinamide. Companies are investing in advanced formulations to improve absorption and minimize side effects. As technology evolves, microencapsulation and slow-release mechanisms are gaining popularity, allowing for more controlled and effective delivery of these nutrients.

Emerging markets present another significant opportunity. With rising incomes and improved healthcare infrastructure, regions such as Latin America, Southeast Asia, and Africa are experiencing increased demand for nutritional supplements and fortified foods. This offers potential for market players to expand their footprint and cater to untapped populations.

Key Regional Insights

The niacin and niacinamide market displays a varied regional landscape, influenced by local dietary habits, healthcare systems, and consumer preferences. North America leads the market, supported by a mature supplement industry, high healthcare awareness, and an aging population. The United States, in particular, has a strong demand for niacin-based products, driven by both preventive healthcare trends and the popularity of skincare formulations.

Europe follows closely, with countries such as Germany, France, and the UK emphasizing functional foods and wellness-driven consumption. Stringent regulations in the European Union encourage the development of high-quality, research-backed products. The region’s preference for natural and clean-label ingredients aligns well with the market’s core offerings.

Asia-Pacific is emerging as the fastest-growing region in the niacin and niacinamide market. Countries like China, India, Japan, and South Korea are witnessing rising demand due to increasing disposable incomes and growing interest in nutrition and beauty. In particular, the Korean beauty industry has significantly boosted the use of niacinamide in skincare, influencing global trends. Governments in Asia are also promoting food fortification programs to address micronutrient deficiencies, further stimulating market growth.

Latin America and the Middle East & Africa are relatively smaller markets but hold substantial potential. Improved healthcare policies, urbanization, and expanding retail channels in these regions are likely to foster greater adoption of niacin and niacinamide products over time.

Competitive Outlook

The niacin and niacinamide market is characterized by the presence of several global and regional players competing to capture market share through product innovation, strategic partnerships, and regional expansion. The competitive landscape is marked by continuous investment in research and development, particularly to improve product efficacy, stability, and bioavailability.

Players are increasingly collaborating with pharmaceutical and food companies to co-develop formulations tailored to specific consumer needs. In addition, e-commerce platforms have emerged as important channels for market penetration, enabling direct-to-consumer sales and broader product visibility.

Sustainability is becoming a key differentiator among manufacturers. Companies are focusing on environmentally responsible sourcing and production methods to appeal to eco-conscious consumers. Clean-label claims and transparency in ingredient sourcing are also influencing purchasing decisions, pushing companies to align with green manufacturing practices.

Top Companies

Several top companies dominate the niacin and niacinamide market by leveraging their global presence, advanced production capabilities, and diverse product portfolios. Lonza Group, a prominent player, offers a wide range of nutritional ingredients and maintains a strong presence in both pharmaceutical and consumer health sectors. Jubilant Life Sciences is another major manufacturer known for its high-quality vitamin B3 products and global distribution network.

BASF SE is recognized for its innovative approach and robust R&D in nutrition and personal care. DSM Nutritional Products also stands out for its focus on science-based solutions and sustainability-driven manufacturing. Other notable companies include Foodchem International Corporation, Vertellus Holdings LLC, and Zhejiang NHU Company Ltd., which serve as key suppliers in the global value chain.

These companies are engaged in continuous efforts to strengthen their market position through mergers, acquisitions, and strategic collaborations. Their ability to offer customized solutions and maintain supply chain efficiency plays a crucial role in maintaining competitiveness.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/niacin-and-niacinamide-market

Segmentation Outlook

The niacin and niacinamide market can be segmented based on form, application, and end-use industry. By form, the market includes powder, liquid, and granular variants. Powdered niacin and niacinamide are the most widely used due to their stability and ease of formulation across supplements and food products.

In terms of application, the market spans across pharmaceuticals, dietary supplements, animal nutrition, and personal care. Pharmaceuticals represent a significant share due to niacin’s role in managing cholesterol and cardiovascular health. Dietary supplements are growing rapidly, propelled by preventive healthcare trends. The animal nutrition segment also utilizes niacin to improve growth and metabolic health in livestock, particularly poultry and swine.

The personal care segment is experiencing a surge in demand, especially for niacinamide in skincare formulations. Products aimed at improving skin texture, tone, and hydration are increasingly incorporating niacinamide due to its proven dermatological benefits.

From an end-use industry perspective, health & wellness, beauty & personal care, and food & beverage sectors are the primary consumers. These industries are expanding their offerings to include functional and fortified products that meet evolving consumer demands.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Patient Lateral Transfer Market Grows to USD 2.95B by 2035 at 8.5% CAGR

The global patient lateral transfer market is estimated to be valued at USD 1,304.1 million in 2025 and is projected to reach USD 2,948.5 million by 2035, registering a compound annual growth rate (CAGR) of 8.5% over the forecast period. The market growth is being supported by rapid expansion in the elderly and bariatric patient populations, elevated incidence of chronic conditions demanding mobility assistance, and stringent safety regulations governing caregiver handling techniques. Developers are prioritizing air-assisted transfer systems, sensor-based monitoring, and ergonomic design enhancements as key advancements.

The patient lateral transfer market is gaining considerable traction as healthcare facilities across the globe emphasize patient safety, caregiver ergonomics, and infection control. This market revolves around devices and systems that allow healthcare providers to move patients from one surface to another—typically from beds to stretchers or operating tables—without requiring strenuous manual handling. The growing need for efficient and safe patient mobility solutions has led to increased adoption of these transfer systems in hospitals, ambulatory surgical centers, and home care settings.

Healthcare professionals face risks of musculoskeletal injuries due to frequent manual patient handling. With increasing awareness of workplace safety, there is a push towards adopting patient lateral transfer devices to reduce caregiver injuries. The patient lateral transfer market is also supported by advances in technology that enhance the ease of use, reusability, and portability of transfer aids. As healthcare systems become more patient-centric, reducing trauma and discomfort during transfers becomes a top priority, boosting market growth.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-12381

Size & Trends

The patient lateral transfer market is experiencing steady growth, fueled by the rising prevalence of chronic illnesses and the aging global population. Older adults often require frequent repositioning and transfers during hospitalization, making them prime beneficiaries of lateral transfer systems. Additionally, the shift towards value-based healthcare, which emphasizes patient outcomes and staff safety, has underscored the importance of investing in such technologies.

Another trend shaping the market is the introduction of advanced materials in the design of transfer aids. Manufacturers are developing air-assisted transfer devices and single-patient use products to prevent cross-contamination. These innovations align with infection control protocols and are especially valuable in intensive care units and isolation wards. Moreover, growing healthcare expenditure and infrastructure development in emerging economies are creating new opportunities for market expansion.

Key Highlights

The patient lateral transfer market is characterized by the emergence of technologically advanced products that combine functionality, hygiene, and cost-effectiveness. Notably, the adoption of air-assisted lateral transfer systems is on the rise, as they significantly reduce friction between surfaces, thereby minimizing the effort required by caregivers. These systems also enhance the patient experience by reducing movement-related discomfort.

The pandemic has also acted as a catalyst, intensifying the focus on infection control and occupational health in hospitals. As a result, disposable lateral transfer devices have seen heightened demand, especially in high-risk and emergency areas. Furthermore, manufacturers are investing in research and development to produce products that cater to the varying needs of acute care, rehabilitation, and long-term care facilities.

Challenges and Opportunities

While the patient lateral transfer market is growing, it is not without challenges. One of the major barriers to widespread adoption is the cost associated with high-quality transfer systems. Many healthcare institutions, especially in low-income regions, operate under tight budgets and may be reluctant to invest in what they consider auxiliary equipment. Additionally, lack of awareness and training among healthcare staff can hinder the effective use of transfer aids.

Despite these challenges, the market presents numerous opportunities. The increasing incidence of obesity worldwide is creating a demand for bariatric patient transfer solutions. Hospitals are recognizing the importance of ergonomically designed devices that can safely transfer heavy or immobile patients. There is also growing support from regulatory bodies and occupational health agencies advocating for safe patient handling practices, which is expected to positively impact market growth.

Moreover, as the demand for home healthcare rises, manufacturers are exploring lightweight, foldable, and easy-to-use patient transfer devices. These products are ideal for non-clinical settings and empower caregivers to provide safe, comfortable transfers in home environments.

Key Benefits for Stakeholders

The patient lateral transfer market offers a range of benefits for stakeholders across the healthcare continuum. For hospitals and healthcare providers, these systems lead to a reduction in workplace injuries, particularly among nurses and caregivers. This results in lower absenteeism, decreased compensation claims, and improved staff morale. Enhanced safety also translates into better patient care, as transfers can be performed with minimal discomfort or risk.

Manufacturers and suppliers benefit from the increasing demand for both reusable and disposable transfer products, especially as healthcare standards become more stringent. Innovation and product differentiation present avenues for competitive advantage. Insurance companies and policymakers, on the other hand, benefit from the broader impact of safer patient handling on healthcare costs and quality of care metrics.

Patients themselves are key beneficiaries. Effective lateral transfer systems minimize the need for physical exertion, prevent skin shearing, and reduce the psychological stress associated with manual transfers. In turn, this contributes to better patient outcomes and satisfaction levels.

Market Share by Geographical Region

The patient lateral transfer market exhibits regional variations in adoption, influenced by healthcare infrastructure, policy frameworks, and investment levels. North America holds a significant share of the market due to well-established healthcare facilities, stringent safety regulations, and high awareness among caregivers. The U.S., in particular, has been at the forefront of integrating patient safety technologies in hospitals.

Europe follows closely, with countries like Germany, the U.K., and France adopting advanced patient handling equipment to comply with occupational health standards. Asia-Pacific is emerging as a key growth region, fueled by rising healthcare expenditure, expanding medical tourism, and a growing elderly population in countries such as Japan, China, and India. However, market penetration in this region is still evolving and varies widely between urban and rural healthcare settings.

Latin America and the Middle East & Africa are expected to witness moderate growth. These regions are gradually adopting patient transfer systems as part of broader hospital modernization initiatives. International aid and partnerships with global healthcare organizations are also playing a role in introducing these solutions to underdeveloped healthcare sectors.

Competitive Outlook

The competitive landscape of the patient lateral transfer market is characterized by a mix of global players and regional manufacturers. Key market participants are focusing on expanding their product portfolios through innovation and strategic partnerships. Mergers, acquisitions, and collaborations are commonly seen as companies strive to enhance their market reach and technological capabilities.

Competition is also intensifying in terms of sustainability and user-centric design. Leading players are increasingly offering eco-friendly materials and devices that are intuitive and easy to operate. Product reliability, regulatory compliance, and pricing remain critical factors influencing purchasing decisions in this market.

Moreover, companies are investing in customer education, offering training programs for healthcare staff to ensure proper use and maintenance of transfer systems. This not only enhances product utilization but also strengthens brand loyalty and customer retention.

Top Companies

Several companies have made notable contributions to the growth and innovation of the patient lateral transfer market. Firms like Stryker Corporation, Hill-Rom Holdings (now part of Baxter), and Arjo are recognized leaders in this space. These organizations offer a diverse range of transfer systems tailored to various clinical settings and patient needs.

Other prominent players include Handicare, Samarit Medical, Blue Chip Medical Products, and Haines Medical. Each of these companies brings unique value propositions to the market, ranging from reusable air-assisted systems to disposable slide sheets. Their global distribution networks and commitment to R&D position them well to capitalize on emerging market opportunities.

Smaller and niche manufacturers are also entering the fray, particularly in emerging markets where customized solutions and price competitiveness are crucial. The growing number of participants is likely to spur innovation and reduce costs, making patient transfer systems more accessible worldwide.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/patient-lateral-transfer-market

Segmentation Outlook

The patient lateral transfer market can be segmented based on product type, usage, end user, and geography. By product, the market includes air-assisted lateral transfer systems, slide sheets, and transfer boards. Air-assisted systems are gaining popularity due to their efficiency and ergonomic advantages, while slide sheets remain a cost-effective solution for many healthcare providers.

In terms of usage, both reusable and single-patient use products are available. The former is favored in settings with established cleaning protocols, whereas the latter is preferred in environments prioritizing infection control. End-user segments include hospitals, ambulatory surgical centers, and home care facilities. Hospitals represent the largest share due to the high volume of daily patient transfers and the need for consistent safety practices.

Geographically, market segmentation helps companies tailor their strategies based on regional healthcare needs and resource availability. Understanding these segments is essential for stakeholders to develop targeted products, marketing approaches, and distribution strategies that align with the diverse demands of the global healthcare ecosystem.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Stool Management System Market Grows Steadily to USD 650.6M by 2035

The stool management system market is expected to be valued at USD 484.1 million in 2025. It is projected to reach USD 650.6 million by 2035, growing at a moderate compound annual growth rate (CAGR) of 3.0% during the forecast period. Among regional markets, India is forecasted to be the fastest-growing with a CAGR of 6.5%, driven by an expanding patient population and improvements in healthcare infrastructure.

The stool management system market is witnessing a steady rise in demand as healthcare providers emphasize effective bowel management solutions for critically ill and immobilized patients. These systems are designed to contain and manage fecal incontinence, minimizing skin breakdown, preventing the spread of infection, and improving patient comfort. Hospitals, long-term care facilities, and rehabilitation centers increasingly recognize the clinical benefits of these systems, especially in intensive care units (ICUs). With healthcare systems across the globe moving toward patient-centric care and enhanced hygiene practices, the stool management system market is positioned for consistent growth in the coming years.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-3568

Market Trends

A major trend in the stool management system market is the shift toward closed-end systems that limit the risk of cross-contamination and hospital-acquired infections. Manufacturers are focusing on innovations that make systems more user-friendly and efficient, such as the integration of sensors and improved catheter materials. Another emerging trend is the incorporation of eco-friendly and biodegradable components in product designs to reduce the environmental impact of disposable systems.

Additionally, telemedicine and remote monitoring technologies are influencing product development. There is growing interest in integrating smart monitoring tools that can alert clinicians in real-time to complications such as leakage or catheter dislodgement. With the aging population and the rising prevalence of conditions like spinal injuries and neurological disorders, the demand for advanced stool management solutions is becoming a vital component of critical care strategies.

Driving Forces Behind Market Growth

Several key factors are driving the growth of the stool management system market. First and foremost is the increasing geriatric population worldwide. Elderly patients are more prone to conditions that result in bowel incontinence, making stool management systems a crucial aspect of elder care. The growing number of ICU admissions and extended hospital stays also contribute to the rising demand for such systems, as managing fecal output is a critical issue for bedridden or immobile patients.

Furthermore, the rise in awareness about hygiene and infection control in healthcare facilities has prompted hospitals to adopt advanced stool management systems. These systems not only enhance patient comfort but also reduce the workload on healthcare staff, thereby improving operational efficiency. Additionally, the increasing incidence of chronic diseases such as colorectal cancer, multiple sclerosis, and spinal cord injuries is boosting the need for long-term stool management solutions.

Technological advancements are also playing a significant role. Modern systems come with features that minimize skin damage and promote quicker healing, which aligns with hospitals’ goals to enhance patient recovery rates. Moreover, healthcare reimbursement policies in several developed countries now cover stool management systems, further encouraging their adoption.

Challenges and Opportunities

Despite its promising growth, the stool management system market faces several challenges. One of the primary hurdles is the high cost of advanced systems, which may limit their adoption in low-income regions and small healthcare facilities. Budget constraints and limited awareness, particularly in underdeveloped markets, continue to impede the widespread use of stool management technologies.

Another challenge lies in the occasional complications associated with prolonged use, such as rectal bleeding, mucosal damage, or discomfort. These concerns make healthcare professionals cautious about deploying such systems for extended durations, impacting overall market penetration.

Nevertheless, opportunities abound. There is significant room for innovation in product design, especially in creating cost-effective and patient-friendly alternatives. Expansion into emerging economies, where healthcare infrastructure is improving rapidly, presents a lucrative opportunity for manufacturers. Educational campaigns and training programs for clinicians on the proper use and benefits of stool management systems can also drive market expansion. Partnerships with healthcare providers and government bodies to promote hygiene and infection control can further fuel market growth.

Recent Industry Developments

The stool management system market has seen several notable developments in recent years. Leading companies are focusing on research and development to launch next-generation products with enhanced safety features and comfort. For example, some manufacturers have introduced systems with dual balloon catheters for better retention and minimal leakage. Others have developed systems made from hypoallergenic materials to reduce skin irritation and allergic reactions.

Mergers and acquisitions are also shaping the market landscape. Companies are collaborating to strengthen their product portfolios and expand their global footprint. In addition, there has been an uptick in regulatory approvals, allowing new players to enter the market and compete with established brands.

Government health agencies in various countries are supporting infection prevention programs, which include the use of stool management systems. These initiatives have led to increased procurement of such devices in public hospitals and long-term care facilities. The growing emphasis on value-based healthcare delivery has further bolstered investments in tools that promote patient dignity and clinical efficiency.

Regional Analysis

Geographically, North America dominates the stool management system market due to its advanced healthcare infrastructure, strong presence of key players, and favorable reimbursement policies. The United States, in particular, is a major contributor to regional growth, with a high rate of ICU admissions and increasing awareness of fecal incontinence management.

Europe holds the second-largest market share, driven by rising healthcare expenditure, aging population, and increasing adoption of advanced medical technologies. Countries like Germany, the United Kingdom, and France are at the forefront of market development, with public health systems investing in infection control solutions.

The Asia-Pacific region is witnessing rapid growth, fueled by improving healthcare facilities, rising disposable income, and increased focus on patient hygiene. Emerging economies such as India and China offer vast untapped potential, particularly as their hospital sectors continue to modernize.

Latin America and the Middle East & Africa are also expected to show gradual progress. Though currently limited by economic constraints and low awareness, these regions are benefiting from global health initiatives and increasing investments in public health infrastructure.

Competitive Outlook

The stool management system market is moderately competitive, with a mix of established players and emerging entrants striving to gain market share. Leading companies are focusing on expanding their global presence through strategic partnerships, distribution agreements, and acquisitions. Innovation remains a key competitive strategy, with firms investing heavily in R&D to offer differentiated and improved solutions.

Brand reputation and product reliability play a crucial role in shaping customer preferences. Companies that can demonstrate clinical effectiveness, ease of use, and cost-efficiency tend to gain a competitive edge. Additionally, offering robust customer support and training services can help vendors build strong relationships with healthcare providers and ensure repeat business.

As competition intensifies, price wars may emerge, especially in cost-sensitive markets. However, companies that prioritize quality, patient outcomes, and regulatory compliance will likely sustain long-term success.

Top Companies

Several prominent companies are leading the stool management system market. These include names like Becton, Dickinson and Company, ConvaTec Group PLC, Hollister Incorporated, and Medtronic plc. Each of these companies offers a range of solutions tailored to different clinical needs and patient populations.

BD is known for its focus on infection prevention technologies and has developed user-friendly systems that align with hospital protocols. ConvaTec continues to lead with its extensive product portfolio in wound and fecal incontinence management. Hollister, with its customer-centric approach, provides products that emphasize comfort and clinical effectiveness. Medtronic leverages its broad healthcare technology expertise to offer integrated stool management systems designed for critical care environments.

These companies are continually improving their offerings, expanding into new geographies, and reinforcing their presence in both developed and emerging markets through digital marketing, direct sales, and hospital partnerships.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/stool-management-systems-market

Segmentation Outlook

The stool management system market can be segmented based on product type, patient type, end-user, and geography. Product-wise, the market is categorized into catheter-based systems, fecal management kits, and accessories. Catheter-based systems dominate due to their widespread use in ICUs and high clinical reliability.

In terms of patient demographics, the market is segmented into adult and pediatric patients, with adult patients comprising the larger share due to higher prevalence of incontinence-related conditions in the elderly.

Among end-users, hospitals hold the largest market share, given their critical role in managing severe and prolonged cases of incontinence. Long-term care centers and home healthcare settings are also emerging as significant segments as patient care shifts toward more personalized and at-home solutions.

Geographically, the segmentation reflects a diverse landscape, with North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa each contributing uniquely to the overall market dynamics.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Pharmaceutical Intermediates Market to Hit USD 57.03B by 2035 at 4.5% CAGR

The pharmaceutical intermediates market is poised for steady growth over the next few years, with its value expected to increase significantly from USD 36.62 billion in 2025 to USD 57.03 billion by 2035. This growth corresponds to a CAGR of 4.5%, reflecting a consistent expansion driven by rising demand in the pharmaceutical sector.

The pharmaceutical intermediates market plays a crucial role in the global healthcare industry. These intermediates are chemical compounds that serve as the building blocks for the production of active pharmaceutical ingredients (APIs). They are essential for the synthesis of a wide range of medications used in the treatment of various diseases. Pharmaceutical companies rely heavily on these intermediates to maintain the efficiency, quality, and cost-effectiveness of drug manufacturing processes.

The demand for pharmaceutical intermediates continues to rise, driven by the increasing prevalence of chronic diseases, growing awareness about health and wellness, and the expanding geriatric population. Additionally, the market is being supported by the rising need for innovative and more effective therapeutic solutions. The growth in research and development activities in the pharmaceutical sector also contributes to the growing consumption of pharmaceutical intermediates, as new drug formulations often require specialized intermediates.

The pharmaceutical intermediates market is influenced by various factors, including regulatory frameworks, technological advancements, and supply chain dynamics. As regulatory authorities become stricter in terms of drug safety and efficacy, the demand for high-quality pharmaceutical intermediates is also growing. This necessitates the development of advanced production methods and stringent quality control measures.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-4515

Market Trends

Several key trends are shaping the pharmaceutical intermediates market. One prominent trend is the increasing shift toward green chemistry and sustainable manufacturing practices. Environmental concerns and regulatory pressure are driving manufacturers to adopt eco-friendly production techniques that reduce waste and energy consumption. This trend not only improves the environmental footprint of pharmaceutical production but also enhances the marketability of products among environmentally conscious consumers.

Another trend is the growing reliance on contract manufacturing organizations (CMOs) for the production of pharmaceutical intermediates. Outsourcing allows pharmaceutical companies to focus on core competencies like research and innovation while leveraging the expertise and infrastructure of CMOs. This approach also enables companies to reduce operational costs and gain flexibility in production scaling.

The rise of personalized medicine is also influencing the pharmaceutical intermediates market. As drug therapies become more targeted and individualized, there is a greater demand for specialized intermediates tailored to specific therapeutic needs. This trend is driving innovation in intermediate synthesis and customization.

Moreover, the integration of digital technologies such as artificial intelligence (AI) and machine learning (ML) in drug development is improving the efficiency and precision of pharmaceutical intermediate production. These technologies help in predicting molecular interactions and optimizing chemical pathways, leading to better outcomes and reduced time-to-market.

Challenges and Opportunities

Despite its growth potential, the pharmaceutical intermediates market faces several challenges. One major challenge is the high cost of raw materials and the volatility of their prices. These fluctuations can impact the profitability of manufacturers and create uncertainties in the supply chain. Additionally, the complexity of regulatory approvals for new intermediates can slow down innovation and market entry.

Intellectual property issues also pose a challenge in the pharmaceutical intermediates market. The development of intermediates often involves proprietary technologies, and disputes over patent rights can hinder collaboration and product development. Furthermore, concerns about quality control, particularly in emerging markets, raise questions about the reliability and consistency of intermediate supplies.

On the other hand, the market offers numerous opportunities for growth and innovation. The increasing demand for generic drugs opens up a wide range of possibilities for intermediate manufacturers. As patents for several blockbuster drugs expire, generic manufacturers are ramping up production, thereby increasing the need for cost-effective and high-quality intermediates.

Another opportunity lies in the biopharmaceutical sector. The rise of biologics and biosimilars has created demand for new types of intermediates that cater to complex biological molecules. Manufacturers that can adapt to these changing requirements will be well-positioned to capture new market segments.

Key Regional Insights

Geographically, the pharmaceutical intermediates market is expanding across several key regions. North America holds a significant share due to its well-established pharmaceutical industry, advanced research capabilities, and robust regulatory framework. The presence of major pharmaceutical companies and academic institutions supports the ongoing demand for pharmaceutical intermediates in this region.

Europe also represents a substantial market, with strong emphasis on innovation, quality standards, and sustainability. Countries like Germany, Switzerland, and the United Kingdom are prominent players in the pharmaceutical sector, contributing to the growth of the intermediates market through technological advancements and a skilled workforce.

Asia-Pacific is emerging as a dynamic region in the pharmaceutical intermediates market. Nations such as India and China are major producers and exporters of pharmaceutical intermediates, thanks to their cost advantages, large manufacturing bases, and favorable government policies. The increasing focus on healthcare infrastructure and the rising demand for affordable medications are further boosting market growth in this region.

Latin America and the Middle East & Africa are also witnessing gradual growth, supported by improving healthcare access and rising pharmaceutical investments. While these regions face infrastructure and regulatory challenges, the long-term outlook remains positive as they continue to integrate into the global pharmaceutical supply chain.

Competitive Outlook

The pharmaceutical intermediates market is highly competitive, with numerous players operating at global, regional, and local levels. Companies compete based on factors such as product quality, pricing, innovation, and customer service. The emphasis on research and development is a critical differentiator, as companies strive to offer unique intermediates that meet evolving pharmaceutical needs.

Mergers, acquisitions, and strategic collaborations are common in this market. These activities help companies expand their product portfolios, gain access to new technologies, and enter untapped markets. Collaborations between pharmaceutical companies and contract manufacturers also enable the development of specialized intermediates that align with specific drug formulations.

The increasing demand for regulatory compliance and quality assurance is pushing companies to invest in advanced manufacturing technologies and quality control systems. This trend is fostering competition based on technological capability and operational efficiency.

Top Companies

Several prominent companies dominate the pharmaceutical intermediates market, leveraging their global presence, technological expertise, and extensive product offerings. These companies are known for their strong R&D pipelines, strategic partnerships, and commitment to compliance with international quality standards.

Firms that have established a robust supply chain and maintain strong relationships with pharmaceutical manufacturers are particularly well-positioned. Their ability to deliver consistent and high-quality intermediates at competitive prices gives them an edge in the market.

In addition, many leading companies are diversifying their product portfolios to include both chemical and biological intermediates. This diversification allows them to address the growing complexity of drug development and cater to a wider range of therapeutic areas.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/pharmaceutical-intermediates-market

Segmentation Outlook

The pharmaceutical intermediates market is segmented based on type, application, and end user. In terms of type, the market includes bulk drug intermediates and custom intermediates. Bulk drug intermediates are produced on a large scale and used in the synthesis of a wide range of drugs, while custom intermediates are tailored to specific client needs and drug formulations.

By application, the market covers areas such as cardiovascular drugs, oncology drugs, antibiotics, anti-diabetic drugs, and more. The increasing prevalence of these health conditions is driving demand for corresponding pharmaceutical intermediates, with oncology and cardiovascular segments showing particularly strong growth.

From an end-user perspective, the market is segmented into pharmaceutical companies, research laboratories, and contract manufacturing organizations. Pharmaceutical companies represent the largest end-user segment, given their role in drug development and production. However, contract manufacturers are gaining prominence as outsourcing becomes a more attractive option for many drug companies.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Artificial Intelligence in Healthcare Market as Global Growth Reaches 18.2% CAGR

The artificial intelligence in healthcare market is valued at USD 17.2 billion in 2025 and is projected to reach USD 77.5 billion by 2035, expanding at a strong CAGR of 18.2%. Among major regions, the United States leads the market, backed by deep-rooted AI research ecosystems and fast-paced regulatory approvals for AI-enabled medical devices.

The artificial intelligence in healthcare market is experiencing transformative growth, revolutionizing how medical data is analyzed, how diagnoses are made, and how personalized treatments are delivered. As healthcare becomes more data-driven and patient-centric, artificial intelligence is emerging as a core enabler of technological advancement. This market comprises a wide range of AI-powered tools and systems used to improve clinical outcomes, streamline operations, and enhance patient engagement. From predictive analytics and diagnostic algorithms to robotic surgeries and virtual health assistants, artificial intelligence is embedded in almost every facet of modern healthcare.

Healthcare providers are leveraging artificial intelligence to process large datasets quickly and accurately. This enables real-time decision-making, more efficient resource management, and early detection of diseases. Machine learning algorithms can detect patterns in medical imaging that may be invisible to the human eye, supporting radiologists in providing more precise diagnoses. Similarly, natural language processing is being used to extract critical insights from unstructured medical records, assisting clinicians in forming comprehensive patient profiles. As digital transformation accelerates, the artificial intelligence in healthcare market is expected to play a central role in shaping the future of global medical services.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-4168

Market Trends

Several significant trends are shaping the trajectory of the artificial intelligence in healthcare market. One of the most prominent is the growing integration of AI in clinical decision support systems. These systems assist healthcare professionals by offering evidence-based recommendations, reducing the margin for error, and increasing the efficiency of treatment protocols. With the rise in chronic conditions such as cancer, diabetes, and cardiovascular diseases, healthcare providers are adopting AI-driven models for more accurate risk assessment and treatment planning.

Another key trend is the rapid development of AI in medical imaging. Artificial intelligence is being extensively used in radiology, pathology, and ophthalmology to analyze scans and images. AI algorithms can interpret X-rays, MRIs, and CT scans with speed and precision, aiding in early diagnosis and reducing the workload on healthcare professionals. Furthermore, AI is being integrated into wearable health technology, enabling continuous monitoring of vital signs and providing real-time alerts for abnormal health parameters. This trend is especially valuable in remote patient monitoring and telehealth, both of which are gaining popularity worldwide.

Personalized medicine is also becoming a major driver in the artificial intelligence in healthcare market. AI algorithms are capable of analyzing genetic data, lifestyle factors, and clinical history to tailor treatments to individual patients. This is transforming the traditional one-size-fits-all approach into a more customized and effective model of care. Pharmaceutical companies are also utilizing AI to accelerate drug discovery, reduce research costs, and predict compound behavior during the early stages of drug development.

Challenges and Opportunities

Despite the immense potential of artificial intelligence in healthcare, the market faces several challenges. One of the most pressing issues is data privacy and security. With sensitive patient data being processed and stored digitally, there are growing concerns about cybersecurity threats and unauthorized data access. Ensuring compliance with data protection regulations such as HIPAA and GDPR is essential for fostering trust in AI-powered solutions.

Another challenge is the lack of standardization in AI applications across healthcare systems. Variations in data formats, clinical protocols, and infrastructure can hinder the seamless implementation of AI solutions. Additionally, there is a knowledge gap among healthcare professionals regarding the effective use of AI tools. Many clinicians require specialized training to interpret AI-generated insights and apply them in patient care, which can slow down adoption.

However, these challenges also present opportunities. As awareness and understanding of AI in healthcare improve, more institutions are investing in training programs and collaborative research. The development of standardized frameworks and interoperability solutions is expected to enhance the scalability and compatibility of AI technologies. Governments and private entities are increasingly funding AI-driven healthcare initiatives, recognizing their potential to improve outcomes and reduce costs. The ongoing digital transformation in emerging markets further expands the opportunities for the artificial intelligence in healthcare market to thrive globally.

Key Points:

Artificial intelligence in healthcare is not just a technological upgrade—it represents a shift in how healthcare is conceptualized and delivered. AI-driven innovations are empowering healthcare providers to transition from reactive treatment to proactive prevention. By enabling early detection of diseases, AI reduces the burden on healthcare systems and improves patient survival rates. The ability of AI to analyze large volumes of data also supports evidence-based practices, making treatments more reliable and consistent.

In hospitals and clinics, AI systems are automating administrative tasks such as patient scheduling, billing, and medical coding. This reduces clerical errors and allows staff to focus more on patient care. Chatbots and virtual assistants, powered by AI, are improving patient interaction by providing immediate responses to queries, scheduling appointments, and offering medical advice for minor symptoms. This enhances patient satisfaction and accessibility to care, especially in underserved areas.

Furthermore, AI plays a vital role in public health monitoring. During disease outbreaks or pandemics, AI systems can track infection patterns, predict hotspots, and guide public health strategies. These applications underscore the broad impact and long-term value of artificial intelligence in healthcare.

Key Regional Insights

Geographically, the artificial intelligence in healthcare market exhibits dynamic growth patterns across different regions. North America is currently leading the market, driven by advanced healthcare infrastructure, strong funding support, and early adoption of AI technologies. The United States, in particular, has been a major hub for AI innovation, with numerous startups and established companies developing cutting-edge healthcare applications.

Europe follows closely, with countries like Germany, the United Kingdom, and France investing significantly in digital health initiatives. The European Union’s regulatory frameworks are also fostering responsible AI adoption, focusing on data privacy and ethical considerations. Collaborative projects between healthcare institutions and technology companies are accelerating AI deployment across the region.

In the Asia-Pacific region, rapid urbanization, growing healthcare needs, and increasing government support are fueling market expansion. Countries such as China, India, and Japan are making substantial investments in AI research, particularly in medical imaging, telemedicine, and disease prediction. The vast and diverse populations in these regions offer rich datasets, further driving AI development and deployment.

Latin America and the Middle East & Africa are also beginning to explore the potential of artificial intelligence in healthcare. Although adoption is still in the early stages, growing digitalization and healthcare reforms in these regions are expected to create new opportunities for AI integration in the coming years.

Competitive Outlook

The artificial intelligence in healthcare market is highly competitive, with both established tech giants and emerging startups vying for dominance. Companies are focusing on innovation, strategic partnerships, and mergers to strengthen their market position. The race to develop proprietary AI algorithms and secure large datasets is intensifying, as data quality and quantity are critical for the effectiveness of AI models.

Many companies are adopting a platform-based approach, offering integrated solutions that combine data analytics, patient management, and clinical decision support. Cloud computing is being leveraged to provide scalable and flexible AI solutions that can be accessed remotely. Customization and user-friendly interfaces are also key areas of focus, as healthcare providers seek intuitive systems that require minimal training.

Another competitive aspect is regulatory compliance. Companies that prioritize ethical AI development and adhere to international healthcare standards are gaining the trust of healthcare providers and regulatory bodies. Continuous investment in R&D and a commitment to transparency are essential for long-term success in this evolving market.

Top Companies

Several major players are at the forefront of the artificial intelligence in healthcare market. These include tech giants such as IBM, Microsoft, and Google, all of which have invested heavily in AI healthcare platforms. IBM’s Watson Health, for example, has been widely adopted for cancer treatment planning and data analysis. Microsoft’s AI offerings are integrated with cloud solutions, making them highly adaptable for healthcare environments.

Google, through its subsidiary DeepMind, has developed advanced AI systems for medical imaging and eye disease detection. Other key players include Siemens Healthineers, GE Healthcare, and Philips, which are integrating AI into their diagnostic imaging and patient monitoring systems. Startups such as Zebra Medical Vision, PathAI, and Tempus are also gaining attention for their innovative approaches and specialized AI applications in radiology, pathology, and genomics.

These companies are continuously expanding their capabilities through acquisitions, partnerships, and global outreach, further contributing to the growth of the artificial intelligence in healthcare market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/artificial-intelligence-in-healthcare-market

Segmentation Outlook

The artificial intelligence in healthcare market can be segmented based on technology, application, end-user, and region. In terms of technology, the market includes machine learning, natural language processing, computer vision, and context-aware computing. Machine learning is widely used due to its ability to analyze vast datasets and improve outcomes through continuous learning.

Applications of artificial intelligence in healthcare include medical imaging, drug discovery, virtual assistants, robot-assisted surgeries, and clinical decision support. Medical imaging holds a significant share due to its critical role in early diagnosis and disease management. Virtual assistants and chatbots are gaining traction in outpatient care and mental health services.

End-users of AI in healthcare comprise hospitals, clinics, pharmaceutical companies, research institutions, and diagnostic labs. Hospitals are the largest adopters, driven by the need for operational efficiency and improved patient care. Pharmaceutical companies use AI for faster drug development, while research institutions leverage it for predictive modeling and genomic analysis.

As AI continues to mature, its integration into healthcare systems is expected to become more seamless, driving better health outcomes, operational efficiency, and patient satisfaction. The artificial intelligence in healthcare market holds vast potential, and its evolution will significantly shape the future of global health services.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


3D Bioprinting Market to Hit USD 8.42B by 2035 with 12.7% CAGR Growth

The global 3D bioprinting market is estimated to be valued at USD 2.55 billion in 2025 and is projected to reach USD 8.42 billion by 2035, registering a compound annual growth rate (CAGR) of 12.7% over the forecast period. The 3D bioprinting market is witnessing accelerated growth driven by the convergence of precision manufacturing, biomaterials science, and regenerative medicine. Significant investments into tissue engineering and organ regeneration are catalyzing new adoption cycles.

The 3D bioprinting market is rapidly evolving as a transformative force in the field of medical and life sciences. This advanced technology involves the layer-by-layer construction of biological materials, including living cells, to create tissue-like structures that mimic natural human anatomy. The growing interest in personalized medicine, regenerative therapies, and organ transplantation has driven significant attention toward this emerging market. With the increasing demand for organ and tissue regeneration, the 3D bioprinting market is set to revolutionize healthcare delivery across the globe.

One of the most promising aspects of 3D bioprinting is its potential to eliminate the reliance on donor organs, which are often in short supply. Instead of waiting for a compatible organ, patients may soon benefit from customized tissue solutions built specifically for their needs. This innovation not only enhances patient outcomes but also significantly reduces transplant rejection rates. As technological advancements continue to accelerate, the 3D bioprinting market is expected to experience sustained growth, driven by its vast potential in both clinical and research settings.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-808

Market Trends

Several key trends are shaping the trajectory of the 3D bioprinting market. One of the most notable trends is the integration of artificial intelligence and machine learning into bioprinting systems. These advanced technologies help optimize the precision and efficiency of bioprinting processes by analyzing vast datasets and improving the accuracy of printed tissues. Additionally, the rising focus on developing complex tissue structures, such as vascularized tissues and functional organs, is propelling research and development efforts within the market.

Another significant trend involves the increasing use of 3D bioprinting in pharmaceutical and cosmetic testing. Companies are moving toward bioprinted tissues as alternatives to animal testing, providing more ethical and accurate testing platforms. Furthermore, collaborations between academic institutions and industry players are fostering innovation and expanding the practical applications of 3D bioprinting technologies. The evolution of biomaterials, such as bio-inks that closely resemble human tissue properties, is also a major driver that is reshaping the landscape of the 3D bioprinting market.

Driving Forces Behind Market Growth

The 3D bioprinting market is primarily driven by the growing demand for organ transplantation and the need for efficient tissue regeneration methods. With an aging global population and increasing prevalence of chronic diseases, the burden on healthcare systems is intensifying. 3D bioprinting offers a viable solution to address these challenges by enabling the production of customized tissues and organs that are tailor-made for individual patients.

Additionally, significant investments from both public and private sectors are fueling the market’s expansion. Governments and research organizations are allocating substantial funding for bioprinting projects, recognizing their potential to transform medical care. The rise of personalized medicine is another crucial factor, as 3D bioprinting supports the creation of patient-specific models for drug testing and treatment planning. Moreover, the advancement of stem cell research and tissue engineering techniques has provided a strong foundation for the growth of the 3D bioprinting market.

Challenges and Opportunities

Despite its immense potential, the 3D bioprinting market faces several challenges that must be addressed. One of the primary obstacles is the complexity of replicating fully functional organs. While researchers have made strides in printing simple tissues like skin and cartilage, the creation of organs with intricate vascular networks and dynamic biological functions remains a significant hurdle.

Regulatory concerns also present a barrier to market growth. Since 3D bioprinted products involve living cells and biological materials, they fall under stringent regulatory scrutiny. Approvals from medical authorities are often slow and require extensive validation, which can delay product commercialization. However, these challenges also present opportunities for innovation. Companies that can develop standardized procedures, reliable bio-inks, and scalable production techniques will gain a competitive advantage in this dynamic market.

Recent Industry Developments

The 3D bioprinting market has witnessed several exciting developments in recent years. Advancements in multi-material printing capabilities have enabled the fabrication of more complex tissue structures, paving the way for improved clinical applications. Startups and established companies alike are launching innovative bioprinters capable of printing multiple cell types with high precision and speed.

Collaborative efforts between academic institutions and industry leaders have resulted in successful trials of bioprinted tissues for transplantation and drug screening. For instance, researchers have recently demonstrated the potential of bioprinted corneal tissues, skin grafts, and cartilage for therapeutic use. These breakthroughs highlight the increasing readiness of 3D bioprinting technologies for real-world applications. Furthermore, companies are actively filing patents and entering partnerships to strengthen their positions within the 3D bioprinting market, signaling robust confidence in its long-term viability.

Regional Analysis

Geographically, the 3D bioprinting market is experiencing strong growth across North America, Europe, Asia-Pacific, and other emerging regions. North America currently dominates the market due to its advanced healthcare infrastructure, high investment levels in biotechnology, and strong presence of key players. The United States, in particular, has become a hub for bioprinting research, supported by academic collaborations and favorable government initiatives.

Europe also holds a significant share of the 3D bioprinting market, driven by its emphasis on ethical testing alternatives and substantial funding in regenerative medicine research. Countries like Germany, the United Kingdom, and the Netherlands are leading innovation in this sector. Meanwhile, the Asia-Pacific region is showing rapid growth potential, fueled by increasing healthcare needs, expanding medical tourism, and supportive government policies. China, Japan, and South Korea are emerging as important contributors to the global bioprinting ecosystem, making regional diversity a key factor in the market’s evolution.

Competitive Outlook

The 3D bioprinting market is highly competitive, with numerous companies striving to establish leadership through innovation, strategic partnerships, and technological advancement. The competitive landscape is marked by continuous R&D efforts aimed at improving the fidelity, scalability, and speed of bioprinting technologies. Companies are also focusing on developing proprietary bio-inks, software, and printing platforms that cater to specific medical applications.

As competition intensifies, mergers, acquisitions, and collaborations have become common strategies to enhance product portfolios and expand market reach. Intellectual property rights and patent protection are crucial in maintaining a competitive edge, as they allow companies to safeguard their innovations. Overall, the dynamic nature of the 3D bioprinting market ensures that companies with robust R&D capabilities, strong distribution networks, and a commitment to regulatory compliance are best positioned for long-term success.

Top Companies

Several prominent companies are at the forefront of the 3D bioprinting market. Organizations such as Organovo, CELLINK (now part of BICO), Allevi, and 3D Systems have played a pivotal role in driving innovation and commercialization in this space. These firms offer a range of bioprinting solutions, from desktop printers for research laboratories to advanced systems for clinical applications.

Startups are also making a significant impact by introducing novel technologies and targeting niche segments within the market. Companies like Aspect Biosystems, Prellis Biologics, and BioBots are gaining recognition for their contributions to developing human-like tissues and accelerating the translation of research into practice. With increasing competition, both established players and new entrants are investing in next-generation solutions that promise to reshape the future of the 3D bioprinting market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/3d-bio-printing-market

Segmentation Outlook

The 3D bioprinting market can be segmented based on technology, application, material type, and end-user. From a technology perspective, inkjet-based, extrusion-based, laser-assisted, and magnetic levitation bioprinting methods are commonly used, each offering distinct advantages for specific applications. Extrusion-based printing holds a significant market share due to its ability to print high-viscosity bio-inks and its scalability.

In terms of application, tissue engineering, drug testing, regenerative medicine, and organ transplantation are the primary domains driving adoption. Among these, tissue engineering and drug testing represent the most immediate use cases, as fully functional organ printing remains a long-term goal. The choice of materials, including natural polymers, synthetic polymers, and hydrogels, also plays a crucial role in the success of bioprinting efforts.

Lastly, the market serves diverse end-users, including hospitals, pharmaceutical companies, research institutions, and academic laboratories. Each segment has unique requirements, which influence the design and functionality of bioprinting systems. As the industry matures, the demand for customized solutions tailored to these user groups will continue to grow, further propelling the 3D bioprinting market into mainstream adoption.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube