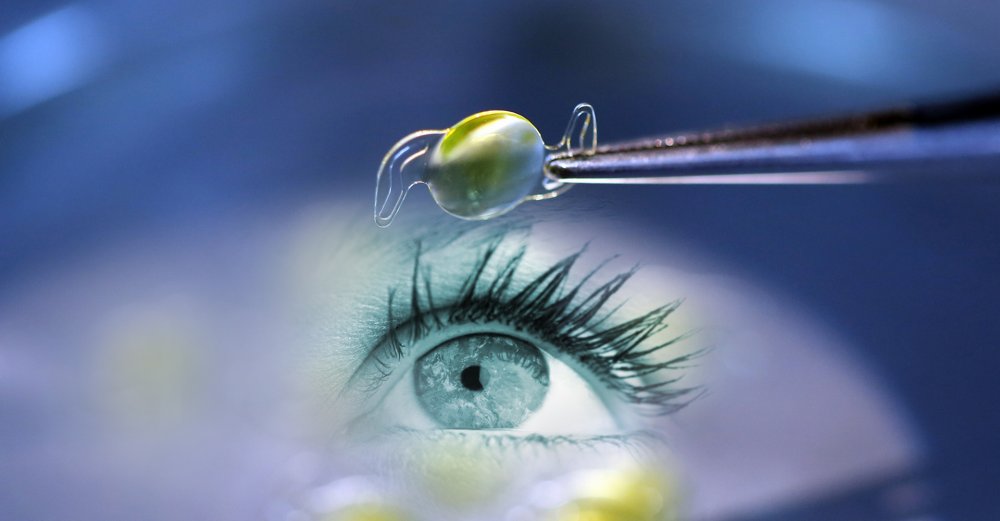
Phakic Intraocular Lenses (PIOL) Market Set for Strong Growth USD 897.4 Million at a 8.1% CAGR Amid Rising Myopia Cases

Intraocular Lens Market
Phakic Intraocular Lenses (PIOL) Market

The global phakic intraocular lenses (PIOL) market is poised for substantial growth, driven by the rising prevalence of myopia and the growing demand for effective refractive correction options. The market, which was valued at US$ 344.4 million in 2021, is expected to reach US$ 377.1 million in 2022 and US$ 412.9 million in 2023. Future projections indicate the market will expand at a compound annual growth rate (CAGR) of 8.1% from 2023 to 2033, reaching a valuation of approximately US$ 897.4 million by the end of the forecast period.

The increasing incidence of myopia worldwide has elevated the importance of phakic intraocular lenses as a preferred treatment option for refractive correction. Unlike traditional corrective methods, PIOLs are surgically implanted in the eye, either in the anterior or posterior chamber, without removing the natural lens. This approach allows for clear, uncorrected vision as light focuses more accurately on the retina. Given their reversibility and the preservation of accommodative function, phakic IOLs are seen as a compelling alternative to laser-based refractive surgeries.

Posterior chamber phakic IOLs currently dominate the market, accounting for approximately 68% of the total market share in 2021. The trend is expected to continue as this type of lens offers significant benefits, including high optical quality, retinal magnification, and minimal dependence on corneal thickness. These factors make them an appealing option for both patients and refractive surgeons, as they provide quick visual recovery and stable refraction following implantation.

A Full Report Overview – https://www.futuremarketinsights.com/reports/phakic-intraocular-lenses-iol-market

Key Takeaways:

  • The global phakic intraocular lenses (PIOL) market is projected to grow at a CAGR of 8.1% from 2023 to 2033, reaching a valuation of US$ 897.4 million by 2033.
  • The market grew from US$ 344.4 million in 2021 to an estimated US$ 412.9 million by 2023, reflecting steady growth in response to rising myopia rates.
  • Posterior chamber phakic IOLs lead the market, accounting for about 68% of the total share in 2021, and this dominance is expected to continue through the forecast period.
  • PIOLs are seen as a superior option for refractive correction, offering benefits like high optical quality, retinal magnification, and fast visual recovery, all while preserving accommodative function.

Key Drivers of Market Growth

  1. Rising Myopia Incidence: The increasing prevalence of myopia globally has heightened the demand for effective refractive correction solutions like phakic intraocular lenses. As more individuals seek alternatives to glasses and contact lenses, PIOLs become a more attractive option.
  2. Technological Advancements: Continuous innovations in lens design and materials are improving the optical quality and safety of PIOLs, making them more appealing to both patients and surgeons. These advancements enhance visual acuity and reduce complications associated with traditional refractive surgeries.
  3. Minimally Invasive Procedure Preference: PIOL implantation is considered a reversible refractive technique that preserves the natural lens and accommodative function, which appeals to patients seeking less invasive options compared to laser surgeries.
  4. Growing Acceptance Among Surgeons: As more refractive surgeons become familiar with PIOL technology and its benefits, the adoption rate is expected to increase, contributing to market growth.
  5. Patient Awareness and Education: Increased awareness among patients regarding the benefits of PIOLs over traditional corrective methods is driving demand. Educational initiatives by healthcare providers are helping to inform potential candidates about their options.
  6. Reimbursement Policies: Favorable reimbursement policies in certain regions are enhancing accessibility to PIOL procedures, encouraging more patients to consider this option.

Competitive Landscape

Some of the prominent players profiled in the global market are-

  • STAAR SURGICAL
  • Care Group
  • Ophtec BV/Abbott
  • Johnson & Johnson
  • Ambu
  • Boston Scientific
  • Olympus
  • Verathon Inc
  • Duomed
  • PENTAX Medical
  • Neoscope Inc

Some of the important developments of the key players in the market are:

  • In July 2020, STAAR Surgical Company received CE Mark approval from its European Notified Body, DEKRA, for their new commercial product offering EVO Viva.
  • In December 2019, Johnson & Johnson received the USA FDA approval and launched of TECNIS Toric II 1-Piece Intraocular Lens (IOL).
  • In December 2022, Johnson & Johnson took another step forward in establishing two independent, market-leading companies with the announcement of Kenvue as the name for the planned New Consumer Health Company. The new corporate brand comes to life through a compelling purpose and a timeless visual brand.

Key Companies Profiled

  • STAAR SURGICAL
  • Care Group
  • Ophtec BV/Abbott
  • Johnson & Johnson
  • Ambu
  • Boston Scientific
  • Olympus
  • Verathon Inc
  • Duomed
  • PENTAX Medical
  • Neoscope Inc

Key Market Segments Covered in Phakic Intraocular Lenses Industry Research

By Product:

  • Posterior Chamber Phakic IOL
  • Anterior Chamber Phakic IOL

By Indication:

  • Myopia
  • Hyperopia
  • Astigmatism

By End User:

  • Hospitals
  • Ophthalmology Clinics
  • Ambulatory Surgical Centers

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • The Middle East and Africa
Explore FMI’s Related Ongoing Coverage on Healthcare Market Insights Domain:

Author By:

Sabyasachi Ghosh (Associate Vice President at Future Market Insights, Inc.) holds over 12 years of experience in the Healthcare, Medical Devices, and Pharmaceutical industries. His curious and analytical nature helped him shape his career as a researcher.

Identifying key challenges faced by clients and devising robust, hypothesis-based solutions to empower them with strategic decision-making capabilities come naturally to him. His primary expertise lies in areas such as Market Entry and Expansion Strategy, Feasibility Studies, Competitive Intelligence, and Strategic Transformation.

Holding a degree in Microbiology, Sabyasachi has authored numerous publications and has been cited in journals, including The Journal of mHealth, ITN Online, and Spinal Surgery News.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531

For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Global Glycolic Acid Market Set for Strong Growth, Projected to Reach USD 782.9 Million by 2034

Glycolic Acid Market

In 2024, the global Glycolic Acid Market size is estimated at USD 499.4 million. By 2034, the market is forecasted to grow to USD 782.9 million, reflecting a CAGR of 4.6%. This growth is not limited to the cosmetics industry; glycolic acid also finds applications in industrial settings such as textiles, polymers, and cleaning agents. The increasing adoption of glycolic acid in chemical peels and anti-aging products is further accelerating its demand.

The Glycolic Acid Market is poised for steady growth in the coming decade, primarily driven by rising demand from the cosmetic and skincare sectors. Glycolic acid, a popular alpha hydroxy acid (AHA), is widely used in exfoliants and skincare products due to its ability to gently remove dead skin cells, improve skin texture, and promote collagen production. The growing consumer preference for high-quality skincare products is one of the key factors propelling the market’s expansion.

The trend towards more natural and eco-friendly cosmetic products has also positively impacted the Glycolic Acid Market. Companies are investing in research to produce bio-based glycolic acid, offering a more sustainable alternative to the synthetic variants, aligning with the growing demand for greener skincare solutions.

Additionally, the growing awareness regarding glycolic acid’s versatility in industrial applications is expected to support market growth. The compound’s ability to act as a cleaning agent in electronics and automotive industries adds to its broad range of applications, ensuring a steady demand across sectors.

“The growth of the Glycolic Acid Market is largely driven by its increasing application in the cosmetics and skincare sectors. As consumer awareness about skincare ingredients rises, glycolic acid’s role in delivering visible skin benefits has made it a sought-after component in many beauty formulations. Moreover, its growing use in industrial applications is opening new opportunities for market players,” says Nikhil Kaitwade, Associate Vice President at Future Market Insights (FMI)

Drivers and Opportunities

The primary driver for the Glycolic Acid Market is the rising demand from the cosmetics and personal care industries, where it is widely used in anti-aging creams, exfoliants, and chemical peels. The increasing awareness of skincare and the growing number of consumers looking for products that promote healthy, radiant skin is propelling the market forward.

Opportunities are also emerging from the industrial sector, where glycolic acid is used in applications such as cleaning agents, textile dyeing, and polymers. With the growing emphasis on sustainability, there is a rising demand for bio-based glycolic acid, presenting manufacturers with a chance to expand their market share by offering eco-friendly alternatives.

Key Takeaways from Market Study

  • The Glycolic Acid Market is expected to grow at a CAGR of 4.6% from 2024 to 2034.
  • The market size is forecasted to increase from USD 499.4 million in 2024 to USD 782.9 million by 2034.
  • The cosmetics and personal care industries are the largest consumers of glycolic acid, driving significant market growth.
  • Industrial applications such as cleaning agents and polymers are also contributing to the increasing demand for glycolic acid.
  • The shift towards bio-based and sustainable glycolic acid is a key trend shaping the market’s future.

Shape Your Strategy with In-Depth Insights from the Glycolic Acid Market Report!

Leading companies in the Glycolic Acid Market include:

  • Chemours Company
  • DuPont
  • Sigma-Aldrich Corporation (Merck)
  • China Petrochemical Corporation (Sinopec)
  • CABB Group
  • CrossChem
  • Phibro Animal Health Corporation
  • Hebei Chengxin Co., Ltd
  • Shandong Xinhua Pharma Co., Ltd
  • Zhonglan Industry Co., Ltd
  • Alfa Aesar (Thermo Fisher Scientific)
  • Parchem fine & specialty chemicals
  • Haihang Industry Co., Ltd
  • Avid Organics
  • Mehul Dye Chem Industries
  • Griffin International
  • Chauhan Pharmachem Pvt. Ltd
  • Shanxi Jinjin Chemical Co., Ltd
  • Triveni Chemicals

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries. Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Hyaluronic Acid Market: Redefining Beauty Trends and Expanding into Fitness and Joint Health Applications

Hyaluronic Acid Market


The global hyaluronic acid market size is projected to experience robust growth, maintaining a steady CAGR of 6.3% through 2034. Valued at USD 9,694.6 million in 2024, the market is anticipated to reach an impressive USD 17,927 million by 2034. This bullish trend is driven by increasing applications of hyaluronic acid in various sectors, including cosmetics, pharmaceuticals, and dietary supplements, owing to its benefits in skin hydration, joint health, and wound healing. The rising demand for minimally invasive aesthetic procedures and advancements in biotechnology further contribute to the market’s expansion, underscoring its significant potential for sustained growth over the next decade.

The rising prevalence of skin-related issues such as dryness, wrinkles, and fine lines due to factors like pollution and stress is fueling the demand for hyaluronic acid-based skincare products. Thirdly, the growing aging population worldwide, especially in countries like Japan and South Korea, is contributing to the expansion of the anti-aging skincare market, where hyaluronic acid plays a crucial role in maintaining skin hydration and elasticity. Lastly, advancements in biotechnology and formulation techniques are enhancing the efficacy and safety of hyaluronic acid products, driving their adoption across various applications in the pharmaceutical, cosmetic, and medical sectors.

The hyaluronic acid industry faces certain challenges that could hinder its progress. One significant restraint is the high cost associated with the production and purification of hyaluronic acid, making the final products relatively expensive for consumers. This pricing barrier may limit market penetration, particularly in emerging economies where affordability is a major concern. Additionally, regulatory hurdles and stringent approval processes for hyaluronic acid-based medical devices and pharmaceuticals pose challenges for manufacturers, leading to delays in product launches and market entry.

The growing consumer interest in natural and organic skincare products is driving demand for plant-based and bio fermented hyaluronic acid formulations, offering opportunities for manufacturers to diversify their product portfolios. Additionally, collaborations and partnerships between industry players and research institutions can accelerate innovation in hyaluronic acid technology, leading to the development of novel formulations with enhanced properties and functionalities.

The hyaluronic acid industry is witnessing several emerging trends that are shaping its future trajectory. One notable trend is the rise of customized skincare solutions tailored to individual skin concerns and preferences. Companies are leveraging advanced technologies such as artificial intelligence and machine learning to analyze consumers’ skin conditions and formulate personalized hyaluronic acid-based products.

Another trend is the growing popularity of combination skincare formulations that combine hyaluronic acid with other active ingredients such as vitamins, peptides, and antioxidants to target multiple skin concerns simultaneously. Moreover, there is increasing demand for sustainable and eco-friendly hyaluronic acid products, driving the adoption of green manufacturing practices and biodegradable packaging materials. Lastly, the integration of hyaluronic acid into ingestible beauty supplements and nutricosmetics is gaining traction, offering consumers an alternative approach to achieving radiant and youthful-looking skin from within.

“The hyaluronic acid industry presents several opportunities for growth and innovation. One such opportunity lies in expanding the application of hyaluronic acid beyond traditional skincare and cosmetic uses. The pharmaceutical sector, for instance, is exploring the potential of hyaluronic acid in drug delivery systems and tissue engineering, opening up new avenues for therapeutic applications.” Says an FMI Analyst.

Key Takeaways from the Market Study

  • China’s hyaluronic acid sector is set to witness rapid expansion with a CAGR of 7.1% from 2024 to 2034.
  • India’s hyaluronic acid demand is rising with a forecast CAGR of 9.4% through 2034.
  • The hyaluronic acid sector in the United Kingdom is forecast to expand at a moderate CAGR of 2.5% through 2034.
  • The United States has long had a developed market for hyaluronic acid, and a CAGR of 3.6% estimated for the sector indicates a stable increase.
  • Germany’s hyaluronic acid industry is projected to experience a steady growth with a CAGR of 3% from 2024 to 2034.
  • Pharmaceutical grade hyaluronic acid dominates the sector in 2024, holding a substantial 52.9% share.
  • Dermatology clinics & cosmetic surgery centers leads among end users capturing a significant 58.1% share.

Navigate the Hyaluronic Acid Market Landscape with Expert Findings in the Complete Report!

Competition Outlook of the Hyaluronic Acid Market  

In the competitive landscape of the hyaluronic acid industry, key players are intensifying their efforts to maintain and expand their market presence through strategic initiatives. Established giants like Roche, Novartis, and Allergan continue to dominate, leveraging their robust research and development capabilities and global distribution networks. Roche, renowned for its innovative biopharmaceutical solutions, remains at the forefront with its flagship hyaluronic acid products. The company emphasizes product differentiation through advanced formulations and delivery mechanisms, aiming to address evolving consumer needs in the healthcare sector. Novartis, with its extensive portfolio of pharmaceutical and dermatological products, strategically diversifies its hyaluronic acid offerings to cater to a wide range of medical and cosmetic applications.

Emerging players such as Galderma and Anika Therapeutics are challenging the dominance of established brands with innovative product offerings and agile business strategies. Galderma, a prominent player in the dermatology and aesthetics space, capitalizes on its expertise in skincare solutions to introduce novel hyaluronic acid-based products. The company emphasizes market penetration through targeted marketing campaigns and partnerships with dermatology clinics and cosmetic surgery centers. On the other hand, Anika Therapeutics focuses on technological advancements and research collaborations to develop next-generation hyaluronic acid formulations.

Leading Companies in the Hyaluronic Acid Industry

  • Allergen Plc
  • Contipro A.S
  • Symatese Group
  • Zhonglan Industry Co.
  • Altergaon Italia Srl
  • Fidia Farmaceutici S.P.A
  • Bioiberica S.A.U
  • Kewpie Corporation
  • Seikagaku Corporation
  • Anika Therapeutics
  • Kikkoman Biochemifa Company
  • Tiansheng Bio

Key Segments of Market Report

By Grade:

The hyaluronic acid industry is segmented by grade into food grade, pharmaceutical grade, and dietary grade.

By End Use:

By end use, the industry is categorized into the pharmaceutical industry, dermatology clinics & cosmetic surgery centers, food industry, and personal care.

By Region:

Region wise segmentation includes North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries. Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
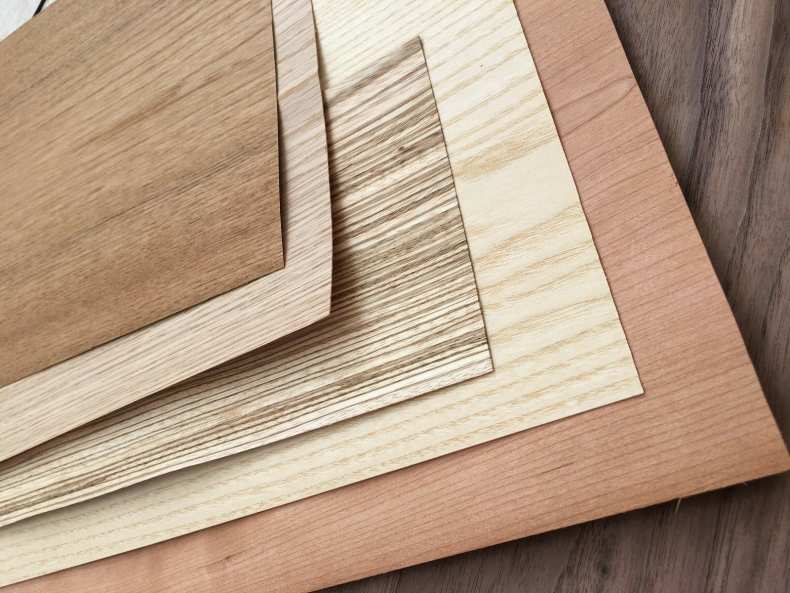
Teak Veneer Sheet Market in USA and Canada to Reach USD 86.0 Million by 2033: FMI Report

USA and Canada Teak Veneer Sheet Market

The demand for teak veneer sheets in the USA and Canada is projected to thrive at a steady CAGR of 3.6% between 2023 and 2033. This growth is driven by increasing applications in furniture, interior design, and decorative paneling due to teak’s aesthetic appeal, durability, and resistance to moisture. Rising consumer preference for high-quality, sustainable wood products is further fueling the market expansion. By the end of 2033, the total market valuation is anticipated to reach approximately USD 86.0 million, highlighting promising opportunities for manufacturers and suppliers across the region.

Teak or Tectona Grandis is one of the renowned tropical hardwood tree species. It is durable, extremely water-resistant, and resistant to rots, pests, and others. Thus, it is widely used for building boats, yachts, outdoor furniture, and others.

Veneer sheets are thin layers of wood logs. They are used for different purposes as they maintain the same natural feel and give an aesthetic appeal to the object.

Yacht/boat is the leading application segment. Teak veneer sheets are being increasingly used during boat/yacht building owing to their various qualities. They find applications in boat decks, cabinets, etc. Hence, widening usage of teak veneer sheets in shipbuilding applications will boost sales.

Similarly, high usage of teak sheer sheets in the building sector will elevate demand through 2033.

Teak is considered to be one of the most superior materials for interior applications. Veneer sheets made from teak are gaining wider popularity in building sector due to their various advantages.

In building & construction, teak veneer sheets are used for flooring, kitchen cabinets, staircase, pillar, and others (window frames, shower tables, bookshelves, tables, walls, and doors). It is used for interiors as it provides a premium feel.

Growing usage in home decor for aesthetic looks will uplift teak veneer sheet demand across the USA and Canada.

Key Takeaways from Teak Veneer Sheet Market Study

  • The USA and Canada teak veneer sheet market is set to expand at 6% CAGR through 2033.
  • By grade, a grade segment will generate significant revenues over the next ten years.
  • By application, yacht/boat segment will thrive at a steady pace through 2033.
  • The USA teak veneer sheet industry will reach a valuation of US$ 51.8 million by 2033.
  • Teak veneer sheet sales revenue in Canada is likely to reach US$ 34.3 million by the end of 2033.

“Booming building and boating industries will continue to bolster teak veneer sheet sales across the USA and Canada. Teak Veneer Sheet manufacturers will find significant opportunity in streamlining their production lines for A grade teak veneer. Not only are these of superior quality, but its functionality helps it sell for high prices for use in boats and furniture.” says a lead FMI analyst.

Competitive Landscape

Greenlam Industries Ltd., Tank Group, GL Veneer, Inc., Oakwood Veneer Company, Natural Veneers, FormWood Industries, Lenderink Technologies Inc., Central India Veneer Private Limited, Century Ply, Sauers & Company Veneers, Veneer Technologies Inc., M.P. VENEERS PVT. LTD., Starwood Veneers Pvt. Ltd., and Duroply Industries Limited are few of the leading teak veneer sheet manufacturers profiled in the report.

These market participants are focusing on increasing their production capacities to cater to the rising demand from end users. They are also launching new products and special production techniques, as well as reducing prices to expand their customer base.

Recent Developments:

  • In 2020, Crown Veneer announced the expansion of their production capabilities, including the installation of a new veneer splicing line and a new veneer dryer.

It also introduced a new line of sustainable teak veneer sheets, which are produced using only FSC-certified teak from responsibly managed forests.

Gain Detailed Understanding by Reviewing the Complete Report!

USA and Canada Teak Veneer Sheet Market Segmentation

By Grade:

  • A Grade
  • B Grade
  • SB Grade
  • C/Utility Grade

By Application:

  • Yacht/Boat
    • Deck and Deck Panels
    • Cabinets
    • Others
  • Building
    • Flooring
    • Kitchen Cabinets
    • Staircase
    • Pillars
    • Others
  • Others

By End Use:

  • Commercial
  • Residential

By Country:

  • USA
  • Canada

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries. Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Rising Industrial Demand Drives USA and Canada Alumina Market to USD 5,491.3 Million by 2032

USA and Canada Alumina Market

The USA and Canada alumina market is poised for steady growth, with sales expected to witness a CAGR of 5.1% over the forecast period from 2022 to 2032. Driven by increasing demand across various industries such as automotive, construction, and electronics, the market is projected to reach a valuation of USD 5,491.3 million by the end of 2032. Factors such as advancements in manufacturing processes, rising adoption of alumina in industrial applications, and investments in infrastructure development are further fueling market expansion. Additionally, the growing emphasis on sustainable materials and innovations in alumina-based technologies are expected to create lucrative opportunities for market players in the coming years.

Aluminum is considered to be the primary raw material for a wide range of industries, especially for automotive, aerospace, and defense sectors. During World Wars I and II, about 90% of USA aluminum production went into defense and military uses. The metal remains essential to several components of modern warfare and owing to this, there is a high demand for alumina for the production of aluminum.

The ongoing Russia-Ukraine war would create a new growth opportunity for key players for the manufacturing of military and defense weapons as the USA is a leading supplier of weapons to Ukraine. There will hence be huge demand for aluminum production across the country. Canada’s aluminum production is mainly exported to the USA and it is projected to further create a lucrative opportunity for alumina production in the United States and Canada during the assessment period.

Key Takeaways from United States and Canada Alumina Market Study

  • Based on application, the aluminum production segment is projected to generate a share of around 1% in the United States and Canada alumina market by 2032.
  • Canada is a prominent importer of alumina with an estimated import volume of 6,225 kilotons.
  • Central Canada and South United States are likely to together capture about 2% of the alumina market share.
  • The United States and Canada alumina market is estimated to witness a CAGR of around 1% on the basis of value.
  • The United States and Canada alumina industry is estimated to reach a valuation of US$ 5,491.3 million in 2032.

“Increasing demand for electronic components and home appliances such as laptops, refrigerators, television panels, smartphones, and washing machines is projected to drive sales of alumina across the United States and Canada. Key electronics manufacturers are set to use aluminum for manufacturing their in-house products to maintain cost-effectiveness and offer high performance,” says a lead analyst at Future Market Insights.

Competitive Landscape: United States and Canada Alumina Market

The market for alumina across the USA and Canada is set to be a consolidated industry, where key players are anticipated to hold a prominent share. Few of the renowned manufacturers in the market include REFRACTRON TECHNOLOGIES CORP., USA Electrofused Minerals, Inc., Washington Mills North Grafton, Inc., Great Lakes Minerals, LLC, Calix Ceramic Solutions, Illinois Valley Minerals (IVM), Cer-Met, Inc., Aluchem of Little Rock and Metal Exchange Corporation., and Nature Works LLC among others.

Key players are focusing on expanding their production capacities to improve their geographic footprint all over the globe, as well as to compete with their rivals. Few of the key companies are aiming to invest huge sums in alumina production backed by a significant surge in terms of demand from the automotive and defense industries.

Unlock Comprehensive Insights by Reading the Full Report Now!

Alumina Market Segmentation

By Grade:

  • Metallurgical Grade
  • Refractory Grade
  • Grinding Grade
  • Others

By Application:

  • Aluminium Production
  • Abrasives
  • Ceramics
  • Refractories
  • Others
  • Air Treatment

By Country:

  • USA
  • Canada

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries. Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

USA and Canada Potassium Sulfate Market to Reach USD 564.4 Million by 2032: FMI Study

USA and Canada Potassium Sulfate Market

The USA and Canada potassium sulfate market is projected to experience steady growth, reaching a valuation of USD 564.4 million by 2032. This growth is driven by increasing demand for potassium sulfate, particularly in the agricultural sector, where it is widely used as a premium fertilizer to enhance crop yield and quality. With a projected CAGR of 2.8% between 2022 and 2032, the market’s expansion is supported by rising awareness of nutrient-rich fertilizers, growing adoption of sustainable farming practices, and the need for chloride-free alternatives to potassium chloride in sensitive crops. The U.S. and Canada’s robust agricultural output and focus on improving productivity further position potassium sulfate as a critical input for farmers across the region.

Changing preferences towards less toxic and chlorine-free fertilizers across booming agriculture industry and increasing need for improving crop yields are some of the key factors driving the U.S. and Canada Potassium Sulfate market.

Significant production volume of crops across the North America is consuming enormous volumes of fertilizers like potassium chloride and Potassium Sulfate. However, FMI predicts the consumption of Potassium Sulfate to increase at a significant pace as it does not contain chloride, which can be harmful to some crops. This will accelerate growth in the U.S. and Canada Potassium Sulfate industry.

Similarly, the need for potassium and sulfur nutrients for healthy growth of crops is prompting farmers across North American countries to use Potassium Sulfate. Fertilizers such as sulphate of potassium (SOP fertilizer) support plant growth and increases crop yield. Hence, growing focus on increasing crop yield will elevate Potassium Sulfate demand across the U.S. and Canada.

Key Potassium Sulfate companies are focusing on increasing their market presence by enhancing their production capacities and by acquisition of small and medium-sized market participants. Several end users and distributors import Potassium Sulfate from other countries to meet the growing demand in the country and also due to low prices. Increasing presence in the untapped market is also a key growth strategy of the players.

Subsequently, the Potassium Sulfate market is significantly influenced by research and development in environment-friendly fertilizers, multi-nutrient fertilizers. Based on these factors significant investment has been made in developing Potassium Sulfate from eco-friendly materials and processes, which is expected to fuel the demand for Potassium Sulfate in the forecast period.

“Farming process in the North America is growing in terms of technology as well as sustainability, where environment-friendly crop nutrients like Potassium Sulfate are being preferred as compared to their counterpart fertilizers from the end users,” says an FMI analyst.

Explore the Full Report for Detailed Insights!

Key Takeaways:

  • The global market of Potassium Sulfate is projected to witness a CAGR of magnitude 2.8% during the forecast period of 2022 and 2032.
  • By product form, granular Potassium Sulfate is estimated to account for about 65% of the overall market size.
  • Based on application, tree nuts segment is expected to capture a significant portion of the U.S. and Canada Potassium Sulfate market during the forecast period.
  • The U.S. remains the leading consumer of Potassium Sulfate across the North America and the trend is expected to continue during the forecast period.
  • Canada’s Potassium Sulfate market is likely to grow at a moderate CAGR during the forecast period.

Who is Winning?

The market of Potassium Sulfate is estimated to be a consolidated market, where key players are expected to account for more than 50% share of the market. Compass Minerals International, Inc., The Mosaic Company, SOPerior Fertilizer Corp., Tessenderlo Kerley, Inc., Interpid Potash, Inc., K+S North America Corporation, and many others are some of the manufacturers of Potassium Sulfate profiled in the full version of the report.

Key players are focusing on expanding their production capacity to meet the growing market demand and strengthening their distribution network to increase their market presence all over the region and to gain maximum traction in the market. Further top players are also investing significantly in innovation in the product series.

Potassium Sulfate Industry Segmentation

By Product Form:

  • Granular
  • Powder
  • Liquid

By Application:

  • Tree nuts
  • Fruits
  • Vegetables
  • Tobacco
  • Others

By Country:

  • USA
  • Canada

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries. Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Naturally Derived Sweeteners Market to Grow at 5.9% CAGR Through 2032, Predicts FMI

Naturally Derived Sweeteners Market

The Naturally Derived Sweeteners Market refers to the industry that deals with the production, distribution, and consumption of sweeteners derived from natural sources. These sweeteners are typically obtained from plants or other natural sources and are used as alternatives to artificial sweeteners, such as aspartame or saccharin.

The naturally derived sweeteners market is anticipated to develop at a CAGR of 5.9% from 2022 to 2032, reaching a worth of USD 9.6 billion in 2022 and surpassing USD 17 billion in 2032.

In recent years, the global natural sweeteners market has seen increasing trends. The growth of this industry is primarily driven by an increase in consumer health consciousness, which encourages demand for healthier food options, an increase in demand for natural sweeteners due to a shift in consumer preferences toward organic products, and a growing demand for alternatives of sugar in a variety of food and beverage applications.

Ascending consumer awareness about the consumption of naturally derived food ingredients is expected to continue underpinning the demand for naturally derived sweeteners over the upcoming years. Being perceived as a potential replacement to conventional sugars, naturally derived sweeteners are likely to demonstrate promising consumption through the next decade. High traction for plant-based sweeteners or those sweetening agents that contain only naturally sourced ingredients is expected to create several opportunities in the consolidated marketplace of naturally derived sweeteners. Furthermore, several governments are extending financial support to encourage natural ingredient cultivation, creating a favorable scenario for farmers especially in developing countries.

Competition Landscape: Top Modified Naturally Derived Sweeteners Manufacturers

According to the market research E. I. du Pont de Nemours Company, Archer Daniels Midland Company, Merisant Company, Tate & Lyle PLC, Cargill, Madhava Natural Sweeteners, PureCircle Limited, Herboveda India Pvt. Ltd.

GLG Lifetech Corporation Wisdom Natural Brands (SweetLeaf Stevia), are among the key players in the naturally derived sweeteners market.

Because of the rising prevalence of diabetes and obesity among consumers around the world, there is a significant increase in demand for low-calorie and sugar-free products, which is expected to boost the growth of the Naturally Derived Sweeteners Market.

Global Naturally Derived Sweeteners Market Segmentation

By Product Type:

  • Stevia
  • Palm Sugar
  • Coconut Sugar
  • Honey
  • Maple Syrup
  • Monk Fruit Sugar
  • Agave Syrup
  • Lucuma Fruit Sugar
  • Molasses
  • Natural Sweetener Blends

By Form:

  • Powder
  • Liquid
  • Crystals

By Nature:

  • Organic
  • Conventional

By End Use:

  • Food
    • Bakery Goods
    • Sweet Spreads
    • Confectionery
    • Dairy Products
    • Canned Food
    • Others
  • Beverages
    • Powdered Drinks and Mixes
    • Carbonated Drinks
    • Fruit Drinks & Juice
    • Others
  • Personal Care
  • Pharmaceuticals
  • Tabletop Sweetener

Sales Channel:

  • Offline Sales Channel
    • Supermarkets/Hypermarkets
    • Departmental Stores
    • Convenience Store
    • Other Sales Channel
  • Online Sales Channel
    • Company Website
    • E-commerce Platform

Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • Middle East and Africa

Download the full report for in-depth insights. https://www.futuremarketinsights.com/reports/naturally-derived-sweeteners-market

Frequently Asked Questions

  • How much is the naturally derived sweeteners market current worth?
  • At what CAGR is the market expected to grow?
  • How was the performance in the last five years?
  • What is boosting naturally derived sweeteners sales?
  • How are market players reacting to the new developments in the market?
  • How much share does the top 5 companies hold?
  • Which are the major countries driving demand for naturally derived sweeteners?
  • Who are the major players in naturally derived sweeteners market?
  • What outlook does East Asia provide?
  • At what rate will the U.S. naturally derived sweeteners market grow?

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
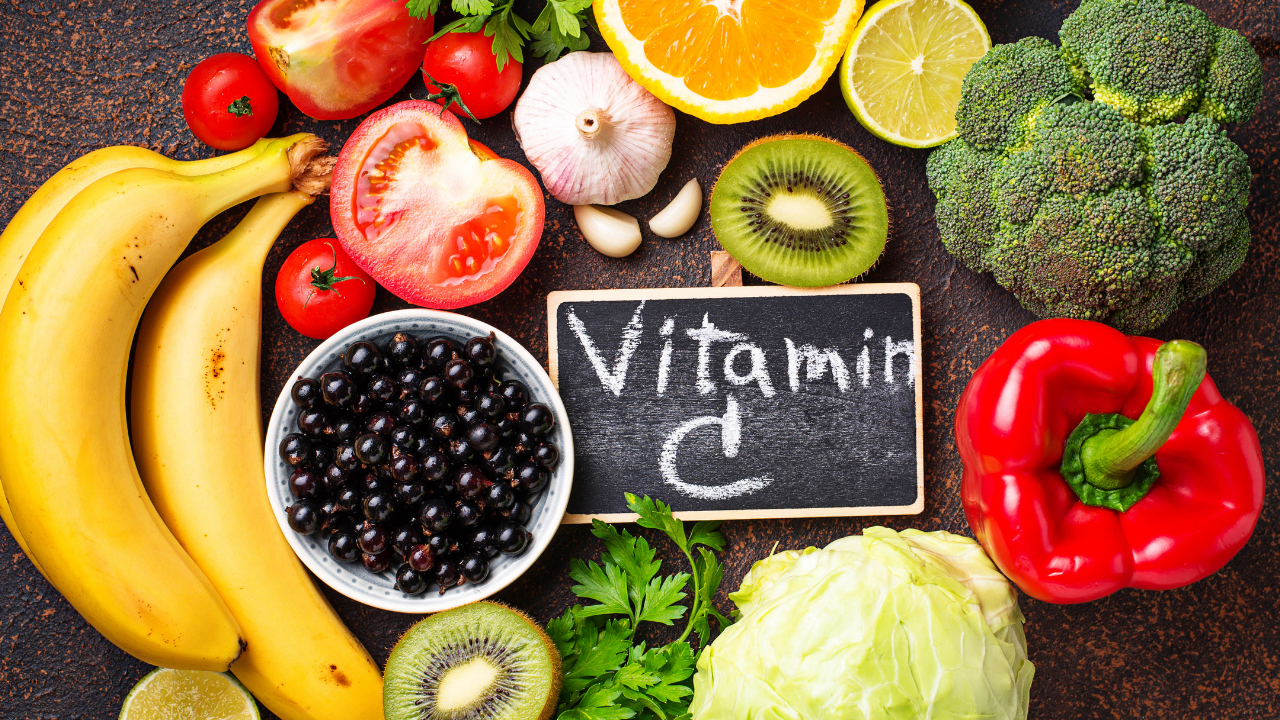
Health-Conscious Consumer Demand Fuels Vitamin C Ingredients Market Growth at 5.6% CAGR by 2033

Vitamin C Ingredients Market

According to an industry report, the vitamin C ingredients Market is expected to generate USD 2,704 million by 2023. Estimates indicate the market is forecast to reach USD 4,657.5 million between 2023 and 2033, representing a CAGR of 5.6%. The rising incidence of cardiovascular diseases and increasing demand for skin care products are expected to drive the market for vitamin C ingredients.

Companies that manufacture food, beverages, and dietary supplements may experience fluctuations in demand due to changes in consumer preferences, health trends, and research on its benefits. Since Vitamin C is a well-known antioxidant and contributes to the immune system, it has historically been in high demand.  Water-soluble vitamins like this need to be replenished regularly through diet or supplements in order for the human body to store them. In addition to being found in many fruits and vegetables, vitamin C is also commonly found in food and beverage products, cosmetics, and dietary supplements.

Several studies have suggested that vitamin C can be beneficial to heart health, especially when consumed in moderation. In addition to lowering blood pressure and reducing LDL cholesterol, it improves endothelial function, the key to a healthy circulatory system. Increasing stress levels and the occurrence of cancers are expected to grow the demand for vitamin C ingredients in the market. In studies, it has been proven that high doses of vitamin C could reduce the body’s stress response and reduce overall cortisol production.

Key Takeaways from the Market Study

  • Between 2023 and 2033, the vitamin C ingredients market is likely to experience a CAGR of 5.6%.
  • Based on the report, the vitamin C ingredients market experienced a growth rate of 2.4% between 2018 and 2022.
  • The United States held 22.8% of the vitamin C ingredients market share in 2022.
  • With strong growth over the past few years, China accounted for a 7.9% CAGR in 2022.
  • According to estimates, Japan held a market share of 3.6% in 2022.
  • A 4% share of the global market for vitamin C ingredients was contributed by the German market in 2022.
  • By 2022, the United Kingdom represented a 3.8% revenue share in the vitamin C ingredient sales in the market.

“With chronic diseases on the rise and new products entering the market, the market is expected to see a growth in demand for vitamin C ingredients. Increasing demand for natural food ingredients combined with an increase in pharmaceutical and cosmetics demand will drive the market to grow,” says an FMI analyst.

Competitive Landscape

Vitamin C ingredients companies are engaging in various partnerships and collaborations to expand their business and gain synergistic benefits. As vitamin C ingredients are mostly used in bakery products, jams, and medicine along with sports nutrition, players in the vitamin C ingredients market are focusing their product offerings on food and beverage and pharmaceutical companies.

  • In April 2023, Unilever introduced a topical formula that uses vitamin C and olivine extract to promote youthful, vibrant skin. Unilever claims that the leave-on formula contains vitamin C dissolved in sodium ascorbyl phosphate and a olivine mineral extract that improves skin tone, skin brightness, and masks visible signs of aging. Formulas could be manufactured as liquids, lotions, creams, foams, and sticks, but serums and essences were ideal.

Know More about What the Vitamin C Ingredients Market Report Covers

Future Market Insights offers an unbiased analysis of the global vitamin C ingredients market, providing historical data for 2018 to 2022 and forecast statistics from 2023 to 2033.

To understand opportunities in the vitamin C ingredients market, the market is segmented based on product type, form, source, process, and end-use industry type across six major regions.

Download the full report for in-depth insights. https://www.futuremarketinsights.com/reports/vitamin-c-ingredients-market

Vitamin C Ingredients Market by Category

By Product Type:

  • Ascorbic Acid
    • Ascorbic Acid 90% Granulation
    • Ascorbic Acid 95% Granulation
    • Ascorbic Acid 97% Granulation
  • Sodium Ascorbate
  • Calcium Ascorbate
  • Coated Vitamin C
  • Others

By Form:

  • Powder
  • Granules
  • Others

By Source:

  • Natural
  • Synthetic

By Process:

  • Reichstein Process
  • Two-Stage Fermentation Process

By End-Use:

  • Food & Beverages
  • Cosmetics & Personal Care Products
  • Pharmaceuticals
  • Animal Feed

By Region:

  • North America
  • Latin America
  • Western Europe
  • Eastern Europe
  • South Asia and Pacific
  • East Asia

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Phycocyanin Market Expected to Reach USD 1.49 Billion by 2033, Says FMI

Phycocyanin Market

The anticipated value of the worldwide phycocyanin market in 2022 was USD 754.40 million. The market is anticipated to reach USD 1,487.7 million, growing at a CAGR of 7% from 2023 to 2033 due to shifting customer preferences toward natural food-grade substances.

Phycocyanin is a natural blue pigment derived from certain species of blue-green algae, also known as cyanobacteria. It is widely used in various industries, including food and beverages, pharmaceuticals, cosmetics, and agriculture, due to its unique properties and potential health benefits.

The benefits of phycocyanin, a substance produced from spirulina, in terms of nutrition and color are driving tremendous expansion in the food and beverage industry. The pigment is mostly used as a natural coloring addition in the food industry. Its use as an additive for food coloring has received permission from the U.S. Food and Drug Administration (FDA).

The organically produced pigment can be used as a nutraceutical component since it has antioxidant activity both in vitro as well as Vivo. Many countries forbid the import and export of items that include artificial food colors, which is assisting the phycocyanin industry’s growth.

Phytocyanin is one of the few naturally generated blue hues acknowledged in Europe, Asia and North America. Its use as coatings for pharmaceuticals and nutritional supplements was also permitted a few years ago. Spirulina extract is exempted from certification by the U.S. FDA Code of Federal Regulations since it has been approved as a color additive. It is produced by sifting spirulina platensis dry biomass and separating it with water.

Increasing the patent manufacturing process of these substances to ensure a stable supply of pigments, strengthening distribution channels, and increasing consumer awareness of the various benefits of natural components, particularly in emerging markets, may further contribute to worldwide expansion.

Key Takeaways from the Market Study

  • Global phycocyanin market is expected to be valued at US$ 785 million by 2023
  • From 2018 to 2022, the market demand expanded at a CAGR of 2.7%.
  • From 2023 to 2033, the United States market for phycocyanin is projected to account for about 20% of global market share.
  • By form type, the powder segment was estimated to acquire 76.9% share in 2022.
  • On the basis of grade, the E18 food grade segment acquired a 56.9% market share in 2022.

“The phycocyanin products are gaining traction due to its natural origin, health benefits and application across a wide range of sectors.” Remarks an FMI analyst.

Competitive Landscape

Prominent players in the phycocyanin market are Cyanotech Corp, DDW Inc., DIC Corporation, Dongtai City Spirulina Bio-Engineering Co., Ltd., Fuqing King Dnarmsa Spirulina Co., Ltd., GNT Holding B.V., Sensient Technologies Corp., Parry Nutraceuticals Limited, Döhler GmbH, Naturex S.A., Naturalin Bio-Resources Co., Ltd, Far East Bio-Tec Co., Ltd., Fraken Biochem Co., Ltd. and others.

Some key developments of the leading companies in this market are:

  • A cooperative study into the impacts of the naturally occurring blue pigment phycocyanin obtained from DIC-cultivated Spirulina will be launched in 2022, according to an announcement made by DIC Corporation, Leave a Nest Co., Ltd and Innoqua Inc.
  • Innoqua’s core “environmental transfer technology,” which enables the recreation of particular marine ecosystems in enclosed environments (aquariums), will be used by DIC and Innoqua to raise corals and evaluate the efficacy of phycocyanin in preventing coral bleaching with the help of Leave a Nest.
  • The research will examine whether phycocyanin’s antioxidant qualities and its ability to block particular wavelengths of light when dispersed in seawater are effective in preventing coral bleaching, in addition to whether corals that absorb phycocyanin produce red fluorescence and do so in order to reduce the stress caused by solar radiation.

Download the full report for in-depth insights. https://www.futuremarketinsights.com/reports/phycocyanin-market

More Valuable Insights Available

Future Market Insights offers an unbiased analysis of the global phycocyanin market, providing historical data for 2018 to 2022 and forecast statistics from 2023 to 2033. The following are the key segments profiled in the Global Phycocyanin Market Report.

By Nature:

  • Organic
  • Conventional

By Form:

  • Powder
  • Liquid

By Grade:

  • Phycocyanin E18
  • Phycocyanin E25
  • Phycocyanin E3.0

By Application:

  • Food & Beverage
  • Cosmetics & Personal Care
  • Nutraceuticals
  • Animal Feed
  • Aquaculture

By Region:

  • North America
  • Latin America
  • Europe
  • Asia Pacific
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Texturized Vegetable Protein Market Poised for Rapid Growth with Record CAGR by 2031

Picture background
Texturized Vegetable Protein Market

The Texturized Vegetable Protein market is a rapidly growing segment of the food industry that offers a plant-based alternative to meat-based protein sources. Texturized Vegetable Protein, also known as textured soy protein or textured plant protein, is derived from soybeans and other plant-based ingredients. It is widely used as a meat substitute due to its high protein content, texture, and versatility in various food applications.

The global TVP market has witnessed significant growth in recent years, driven by several factors. Firstly, the increasing consumer demand for plant-based and vegetarian/vegan diets has propelled the market forward. As people become more health-conscious and environmentally aware, they are seeking alternatives to traditional meat products. TVP provides a sustainable and ethical option by reducing reliance on animal protein.

The rising awareness among consumers about a multitude of health benefits of plant-based sources of protein has been aiding the market for texturized vegetable protein. Future Market Insights (FMI) in a new study has forecast the market to exhibit 6.5% CAGR by 2031. Growth forecasts continue to remain positive for the market, thanks to increasing number of vegetarian population worldwide.

Continuously increasing demand for food & beverage products which provide nutritional benefits with sensory taste is one of the major factor driving the demand for texturized vegetable protein. Due to increasing awareness regarding animal cruelty and environmental damages caused by excessive consumption of might the demand for texturized vegetable protein is expected to increase.

These protein sources also contain lower amount of saturated fat and cholesterol as compared to meat products hence are considered to have more health benefits. Among products available, the demand for soy protein is expected to be the highest. As per FMI, the soy protein segment is forecast to account for over 80% of the market through 2031.

Key Takeaways from the Texturized Vegetable Protein Market Study

The North American texturized vegetable protein market leads in terms of market size and accounts for 30.1% of the global texturized vegetable protein market in 2021. The Soy Protein texturized vegetable protein market is expected to have a market share of 70.0% of the global texturized vegetable protein market in 2031. In the nature segment, Conventional holds 97.9 % of the texturized vegetable protein market.

In the end-user segment, Industry holds the maximum market share of 76.1% in 2021 of texturized vegetable protein market where Meat Analogues holds 42.8% globally in 2021. Soy protein has a major share by product type and is anticipated to grow significantly over the forecast period. North America have a large number of companies and thus, majority of companies are emphasizing on offering non-GMO products, which are processed through extrusion-based technology, with enhanced functional properties so that their product can comply with strict requirements of clean label products.

“Benefits of opting vegan proteins are now gaining popularity due to which many big companies are investing in the production and innovation of texturized vegetable protein. Several manufacturers are acquiring or merging with key companies to expand their product portfolio and increase their market share. E-commerce and online stores are easing entry barriers and distribution costs. These factors are expected to make competition fiercer within the market” said a lead analyst at FMI

Who is Winning?

The global population is increasing at a rapid rate and it is expected that the population will be around 9.5 Bn by 2050 from 7 Bn in 2017. The situation is set to put quite a strain on the food and supply of raw material, resulting in the need for alternate protein sources. Key players operating in the market are adopting various strategies, which include expansion of production capacity and launch of various products.

A few of the leading players operating in the texturized vegetable protein market are Archer Daniels Midland Company, CHS Inc., Roquette Frères, Beneo GmbH, Danisco A/S, Vestkron A/S, Cargill Inc., FUJI OIL CO., LTD., Puris Proteins, LLC., MGP Ingredients, Inc., Crown Soya Protein Group, Sotexpro SA, Wilmar International Ltd., Gushen Biotechnology Group Co., Ltd., Ingredion Inc.

Download the full report for in-depth insights. https://www.futuremarketinsights.com/reports/texturized-vegetable-protein-market

Texturized Vegetable Protein Market Key Segments

Product Type

  • Soy Protein
  • Wheat Protein
  • Pea Protein
  • Rice Protein

Nature

  • Organic
  • Conventional

Form

  • Chunks
  • Slice
  • Flakes
  • Granules

End Users

  • Household
  • Commercial
  • Industry
    • Food Industry
      • Bakery
      • Snacks
      • Ready Meals
      • Sports Nutrition
      • Clinical Nutrition
      • Baby Food
      • Meat Analogues
      • Others
    • Animal Feed

Distribution Channel

  • Direct
  • Indirect
    • Store Based
    • Hypermarket
    • Convenience St.
    • Traditional Store
    • Online Retails

Region

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Middle East and Africa (MEA)
  • Oceania

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Nonetheless, specific solutions may require various management instructions, so it is critical to read the cardiform vélemények going along with medication guide.