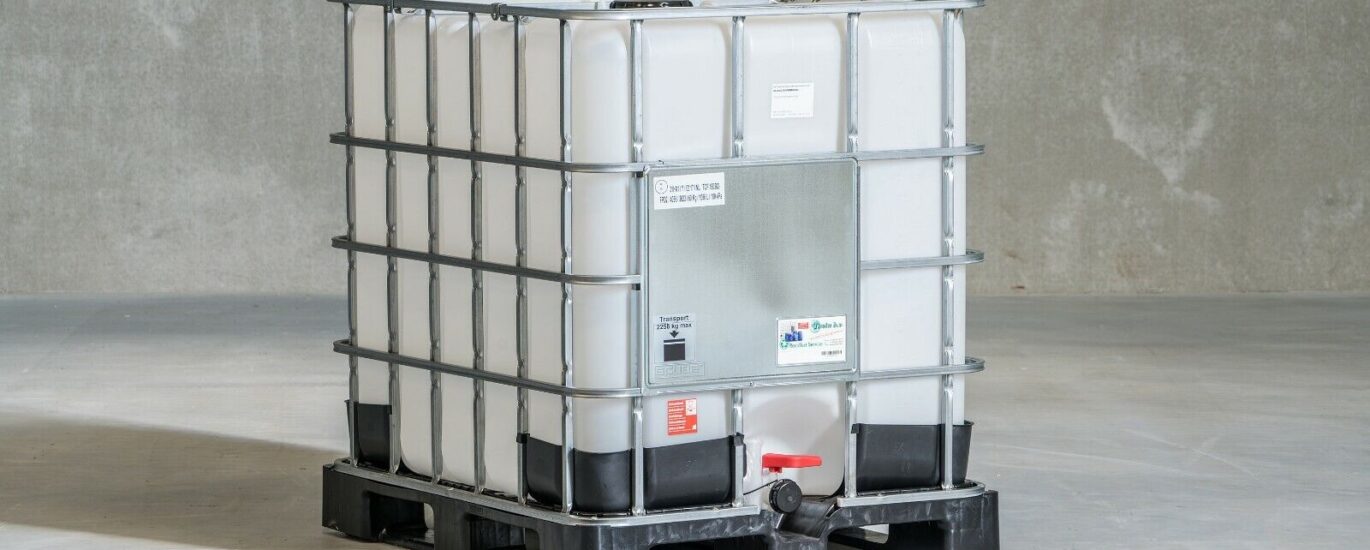
Global Reconditioned IBC Market Set to Reach USD 8,724.8 Million by 2034, Driven by Sustainable Solutions

The global reconditioned Intermediate Bulk Container (IBC) market is projected to witness robust growth, reaching a valuation of USD 5,295.3 million in 2024 and expanding to an impressive USD 8,724.8 million by 2034. This growth trajectory corresponds to a CAGR of 5.1% over the forecast period. In 2023, the industry recorded revenue of USD 4,971.8 million, and year-on-year growth for 2024 is anticipated at a strong 6.1%.

Among various product types, composite IBCs are set to dominate the market, accounting for more than 80% of the market share in terms of volume. Composite IBCs are projected to grow at a CAGR of 4.2% throughout the forecast period, reflecting their increasing popularity across industries.

Find Out More—Read the Complete Report for Full Insights!

Key Advantages Driving Composite IBC Demand:

  • Durability and Cost Efficiency: Reconditioning enhances the lifecycle of composite IBCs, offering a cost-effective and sustainable packaging solution.
  • Reduced Material Wastage: The ability to reuse the metal cage and replace the inner container significantly minimizes material costs and environmental impact.
  • Sustainability Focus: The eco-friendly nature of reconditioned composite IBCs aligns with global sustainability goals, further boosting adoption.

Understanding the Reconditioned IBC

A Reconditioned Intermediate Bulk Container (IBC) refers to a previously used IBC that has undergone a cleaning and refurbishing process to restore it for safe and functional reuse. These containers are commonly used for storing and transporting bulk liquids, chemicals, or other materials.

Prominent Drivers of the Reconditioned IBC Market

  • Cost-Effectiveness: Reconditioned IBCs are significantly cheaper than new ones, making them an attractive option for businesses looking to reduce packaging costs without compromising quality or reliability.
  • Environmental Sustainability: The growing focus on sustainability and waste reduction has driven demand for reconditioned IBCs. By reusing and repurposing containers, companies contribute to the circular economy, reducing environmental impact and promoting eco-friendly practices.
  • Rising Demand in Packaging and Logistics: The global growth in industries like chemicals, food and beverages, pharmaceuticals, and oils has led to an increased need for bulk packaging solutions. Reconditioned IBCs provide a cost-efficient and reliable solution for transporting and storing these materials.
  • Regulatory Compliance and Safety Standards: Reconditioned IBCs often meet rigorous industry standards and regulations, which makes them a viable option for industries requiring safe and compliant packaging solutions, particularly in the chemical and hazardous material sectors.
  • Durability and Reusability: Reconditioned IBCs maintain their strength, reliability, and performance after being refurbished, offering businesses a durable packaging solution with a longer lifecycle, reducing the need for frequent replacements.

Key Takeaways: Reconditioned IBC Market

  • The global reconditioned IBC industry achieved a CAGR of 3.2% from 2019 to 2023.
  • The market reached a valuation of USD 4.9 billion in 2023, reflecting positive growth.
  • Germany’s reconditioned IBC market is projected to grow at a CAGR of 2.9% from 2024 to 2034, reaching over USD 455 million by 2034.
  • North America is expected to expand at a CAGR of 4.5% during the forecast period, with the market size projected at USD 1.7 billion by 2034.
  • China is a key focus for manufacturers, with an estimated CAGR of 5.9% throughout the forecast period.
  • The metal IBCs segment leads the market, contributing 55% of revenue in 2024.
  • The industrial chemicals segment is anticipated to generate over USD 3.2 billion in revenue by 2034.

Competitive Landscape

Key players in the refurbished IBC market are investing in innovative reconditioning facilities and forming alliances. Key reconditioned IBC providers have also been purchasing smaller competitors to expand their footprint and reach the refurbished industry in numerous locations.

Recent Industry Developments in Reconditioned IBC Market

  • Grief Inc. established a cooperation with CDF Corporation in March 2024 to work on redesigning its GCUBE IBC Flex for the transportation of very sensitive goods and liquid fluids.
  • In January 2024, ENVA announced the opening of a new reconditioning and recycling facility at its Dunniflats location in Ayrshire. The factory will be able to process approximately 25,000 units each year.
  • Grief stated in April 2023 that it had completed an all-cash transaction of USD 145 million to raise its shareholding of Centurion Container from 9% to 80%.

Key Players of Reconditioned IBC Industry

  • Mauser Group B.V
  • Greif, Inc.
  • Schutz Container Systems, Inc
  • Rahway Steel Drum Co. Inc
  • Clouds Drums Dubai LLC
  • Varilsan Packaging
  • TPL Plastech Limited
  • Accon Group AS
  • Precision IBC, Inc
  • Recontainers Ltd
  • Obal Centrum s.r.o.
  • North Coast Container (Container Management Services)
  • Metano IBC
  • IBC Tanks
  • Delta Containers
  • The Cary Company
  • Mitchell Container Services, Inc.

Key Segments of Reconditioned IBC Industry

By Material:

In terms of material, the industry is divided into metal IBCs and composite IBCs.

By Capacity:

In terms of capacity, the industry is segregated into standard and customized capabilities. The standard segment has been further segregated into 1,040 liters (275 US gal), and 1,250 liters (330 US gal).

By End-use:

The industry is classified by end use industries as industrial chemicals, petroleum & lubricants, paints, inks & dyes, food & beverages, waste disposal/recycling & silage, and others.

By Region:

Key countries of North America, Latin America, Europe, East Asia, South Asia, Middle East and Africa (MEA), and Oceania have been covered in the report.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Eco-Friendly Inks Market to Reach USD 7.5 Billion by 2032, Driven by Rising Environmental Awareness

The eco-friendly inks market is predicted to be worth USD 4.55 billion in 2023 and rise to USD 7.5 billion by 2032. Demand is expected to increase at a CAGR of 5.8% during the projected period.

The key drivers of market growth are rising environmental concerns in the printing industry. As a result, there is a significant market for green printing technologies like digital printing, 3D printing, and UV printing.

As water-based inks are being used more frequently, the sector is predicted to grow. Periodicals, labels, and packaging are just a few examples of the many uses for water-based inks, which are also free of toxic chemicals.

Governments globally are establishing stringent regulations to decrease the harmful impacts of ink manufacturing and consumption on the environment. Businesses looking for ways to follow these regulations have increased the demand for eco-friendly inks.

See All the Details—Click Here for Full Report Information!

In response to the increased sales of eco-friendly inks, several businesses are investing in research and development projects to develop new goods. The need for organic inks is expected to increase as a new trend. Many different applications, including consumer goods, use inks made of organic ingredients like soybeans.

Key Takeaways

  • By 2032, the United States is likely to dominate the eco-friendly inks market, with a share of 19.4%.
  • The demand for eco-friendly inks increased at a 3.5% CAGR between 2018 and 2022, citing FMI’s study.
  • The expansion in the United Kingdom is anticipated to expand at an adequate CAGR of 4.4% by 2032. The market is likely to generate a share of USD 169.9 million by 2032.
  • Japan’s eco-friendly inks market is expected to grow with a share of 35.8%, and a CAGR of 6.7% by 2032.
  • Between 2023 and 2032, the eco-friendly inks market is likely to increase in India at 7.8% CAGR, respectively.
  • The expansion in China is anticipated to expand at an adequate CAGR of 6.2% by 2032. The market is expected to generate a share of USD 835.8 million by 2032.
  • Germany’s market is expected to reach USD 178.9 million, and a CAGR of 3% by 2032.
  • With sustainability in mind, the market growth rate is expected to be around 1.8x by 2032.

Competitors Utilizing Their Potential for Improved Market Share

Green printing strategies have been adopted by manufacturers as a result of growing environmental concerns. The initial expansion of the eco-friendly inks market is also being driven by the rising demand for water-based and UV-curable inks.

Eco-friendly Inks producers now generate inks that are more effective and affordable due to the development of new eco-friendly ink compositions. The market is expanding as a result of the rising demand for digital printing and an increase in the number of businesses providing green printing services.

Kao Collins Corporation, Sun Chemical, Living Ink Technologies, Siegwerk Druckfarben AG & Co. KGaA, INX International Ink Co., Wikoff Color corporation, STS Inks, Flint Group, EPTANOVA, Kwang Myung Ink Co. Ltd, Gans Ink & Supply, Toyo Ink India Private Limited, Huber Group, Marabu Printing Inks, Magna Colours Ltd. are some of the major players in the global eco-friendly inks market.

Latest Developments

  • For $48 million in July 2021, Magna Colors teamed up with Avient Corporation, a major supplier of specialized and environmentally friendly material solutions.
  • Energy-efficient printing inks with a low carbon footprint presented by Marabu, an ink manufacturer, at glasstec 2022 in July 2022. The business also displays inks for the glass industry’s use in screen printing, digital printing, and pad printing.
  • At Printpack India 2022 in May, Huber Group Print Solutions presented its sustainable folding carton portfolio.

Key segments

By Color:

  • Four Color
  • Monochrome Printing

By Origin of Bio Pigments:

  • Flint Ink
  • Algae Inks
  • Animal Origin
  • Vegetable-based Ink

By Type:

  • Gums
  • Resins
  • Waxes
  • Solvent-based
  • Water-based
  • Oil-based

By Printing:

  • Flexography
  • Lithography
  • Gravure
  • Offset
  • Screen Printing
  • Digital

By Packaging:

  • Food & Beverage
  • Pharmaceutical & Medical Devices
  • Consumer Goods
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia Pacific
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Europe and the Middle East and Africa Retail Glass Packaging Market | Growth, Trends Analysis Report 2032

The Europe, Middle East and Africa (EMEA) retail glass packaging market is predicted to be worth USD 10.1 billion in 2023, and rise to USD 14.8 billion by 2032.

Retail glass packaging is expected to be in high demand in EMEA as consumers’ preferences for eco-friendly, health & wellness, enticing, and affordable packaging options grow. Recently, companies actively developed unique retail glass packaging solutions while collaborating closely with their customers and industrial suppliers.

By compiling information on consumer trends and preferences, businesses may design packaging that is specially tailored to the requirements of their target customers. In established regions like Europe, the luxury packaging market is primarily driven by the volume of launches in the food, beverage, and alcohol industries.

Get the Complete Story—Read More About Our Latest Report!

Glass dominates the market for luxury packaging among all other material types, with a market share of more than 50%. The retail glass packaging sectors in EMEA are seriously threatened by the plastic and metal packaging industries.

In the food and beverage sector, glass packaging has suffered a reduction in market share, but it still has advantages over alternative materials. Key causes of this loss include the high cost of production, heavyweight, and fragility of glass containers.

Key Takeaways

  • Demand for retail glass packaging in Europe is expected to increase at a CAGR of 4.1% during the projected period.
  • Demand for retail glass packaging in MEA is expected to increase at a CAGR of 6.2% during the projected period.
  • By 2032, the United Kingdom is likely to dominate the Europe retail glass packaging market, with a CAGR of 5.3%.
  • The adoption of retail glass packaging in Europe increased at a 2% CAGR between 2018 and 2022, citing FMI’s study.
  • The adoption of retail glass packaging in MEA increased at a 2.7% CAGR between 2018 and 2022, citing FMI’s study.
  • Poland’s retail glass packaging market is expected to expand at a CAGR of 4.9% by 2032.
  • Based on packaging format, the bottle segment is likely to lead the Europe market with a CAGR of 5% by 2032.
  • Based on end use, the personal care & cosmetics segment is expected to dominate the Europe retail glass packaging with a CAGR of 6.2% by 2032.
  • Europe offers an incremental opportunity worth USD 4,111.1 million between 2022 and 2032, while MEA has an incremental opportunity worth USD 1,561.0 million.

Competitors Utilizing Their Potential For Improved Market Share

The EMEA retail glass packaging market is predicted to experience significant start-up growth over the projection period. The primary factors causing the rise are the demand for high-quality and safe packaging, rising disposable incomes, and an expanding retail industry.

Due to the initiatives taken by various governments to promote the use of sustainable packaging materials, the industry expanded further. The growing popularity of e-commerce presents new opportunities for the EMEA retail glass packaging sector.

Key players

  • O-I Glass, Inc.
  • Ardagh Group SA
  • Gerresheimer AG
  • Schott AG
  • Bormioli Rocco S.p.A.
  • Vetropack Holding AG
  • Vidrala SA
  • Vitro Packaging, LLC
  • Wiegand-Glas GmbH
  • Heinz-Glas GmbH & Co. KGaA.
  • Stölzle-Oberglas GmbH
  • SGD Pharma
  • MEG

Recent Developments

  • PepsiCo’s product line includes a wide range of delicious meals and drinks, including a variety of illustrious brands with expected annual retail sales of more than $1 billion apiece.
  • Beginning in May 2022, the Coca-Cola Europacific Partners (CCEP) brands Fuze Tea, Tropico, Sprite, Fanta, and Minute Maid are sold in France. They come in a standard 250 ml bottle that may be used in hotels, restaurants, and cafés-returned, cleaned, and replenished.

Key Segments

By Packaging Formats:

  • Bottles
  • Jars
  • Vials
  • Ampoules
  • Syringes
  • Cartridges
  • Others

By Grade:

  • Type I
  • Type II
  • Type III
  • Type IV

By Capacity:

  • Up to 50 ml
  • 51 to 250 ml
  • 251 to 750 ml
  • Above 750 ml

By End Use:

  • Food
  • Beverages
  • Personal Care & Cosmetics
  • Pharmaceuticals
  • Other Industrial

By Region:

  • Europe
  • The Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
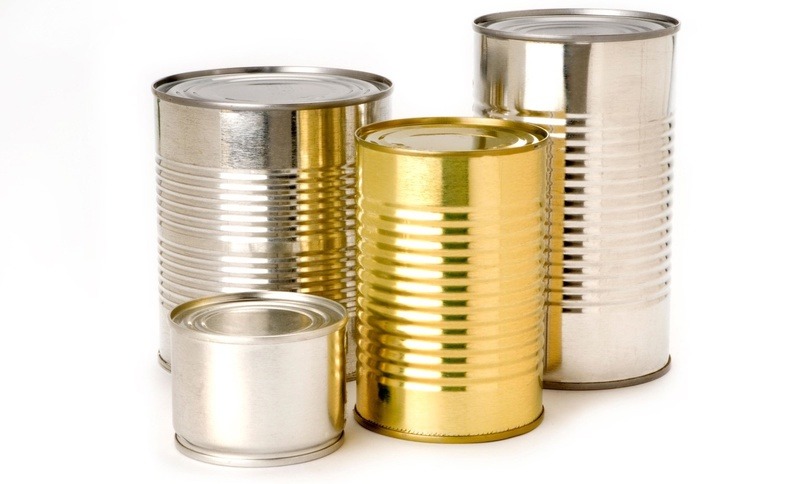
Specialty Tin Cans Market Projected to Reach USD 899.4 Million by 2032, Driven by Demand for Health Drinks and E-commerce Growth

The global specialty tin cans market, valued at USD 566.2 million in 2022, is set to experience steady growth, with a projected compound annual growth rate (CAGR) of 4.8% from 2022 to 2032. The market is expected to reach a valuation of USD 899.4 million by the end of the forecast period in 2032.

A major factor driving the growth of the specialty tin cans market is the increasing demand for sucralose juices, health beverages, health drinks, and carbonated soft drinks, particularly among millennials and Gen Z consumers. These trends are anticipated to positively influence the sales of specialty tin cans, as these packaging solutions are increasingly favored by beverage companies for their convenience, durability, and sustainability.

Explore In-Depth Analysis—Click Here to Access the Report!

Key industry players are expected to shape the development of the global specialty tin cans market, with focused efforts on research and development, as well as aggressive promotional campaigns. As consumer demand for health-conscious products rises, manufacturers are expected to continue innovating to meet evolving preferences.

The retail and food industries are expected to remain the dominant consumers of specialty tin cans, with the expansion of superstores and grocery chains, coupled with the growth of distribution networks by leading food manufacturers, driving demand for these packaging solutions. Additionally, the rise of micro families is expected to increase the demand for smaller packaging sizes, boosting the market for specialty tin cans.

The growing trend of e-commerce, with many companies enhancing their presence on online platforms, is another key factor expected to drive sales. Consumers are increasingly purchasing canned food products online, often at discounted rates, leading to higher sales volumes in the coming years.

Owing to busy lifestyles of the working population, demand for metal cans is anticipated to surge in developed countries. Millennials are set to incline toward wholesome food items that are ready to eat and can be prepared in a short period as they have hectic schedules.

By providing foods that are ready to use and in convenient packaging, canned food is likely to accomplish this particular goal. The ability of tin cans to keep food items fresh for a long time is another crucial factor that would accelerate specialty tin cans sales in the next ten years.

Key Takeaways from the Specialty Tin Cans Market Report.

  • The global specialty tin cans market experienced a moderate CAGR of 2.7% between 2017 and 2021.
  • The USA specialty tin cans market in North America is expected to surpass USD 217.7 million by 2032.
  • The United Kingdom’s specialty tin cans market is projected to exceed USD 29.6 million by 2032.
  • Demand for beaded tin cans, based on product type, is anticipated to reach a valuation of USD 342.9 million by 2032.
  • The beverage segment, as an end-use application, is estimated to attain a valuation of approximately USD 259.6 million by 2032.

“Increasing demand for specialty tin cans for the packaging of premium and luxury products such as tea, coffee, and cookies is projected to drive sales in the market. Key companies are expected to launch innovative tin cans with unique designs to expand their portfolios.” says a lead analyst at Future Market Insights, Inc.

Competition Landscape: Specialty Tin Cans Market

The top manufacturers of the specialty tin cans market are Ardagh Group S.A., Allstate Can Corporation, Crown Holdings, Inc., Colep Packaging, Toyo Seikan Group Holdings, Ltd., Hindustan Tin Works Ltd, Silgan Containers LLC, Kian Joo Can Factory Berhad, Wilkinson Containers Ltd, CAN-PACK S.A., Swastik Tins Private Limited, Massilly Holding, Gruppo ASA, Litoichap S.L., Falco S.p.A., Teksan Tin House, LK-PremiumPack GmbH, C.L. Smith Company and others.

The global specialty tin cans market is highly fragmented with the presence of numerous local and international companies. They are mainly participating in organic and inorganic strategies such as collaborations, joint ventures, and acquisitions to compete with their rivals.

Recent Development

  • In May 2021, Nestle’s Milo brand introduced three new limited-edition 1kg tins in Australia. The tins showcase cricket, basketball, and football with bright pictures. The company aims to help kids in Australia to remain active and encourage them to participate in sports activities.

Specialty Tin Cans Market Outlook by Category

By Product Type:

  • Slim Tin Can
  • Beaded Tin Can

By Closure:

  • Penny Lever Lids
  • Sanitary Lids
  • Easy Open Lids
  • Full Aperture Lids

By Capacity:

  • Less than 200 ml
  • 200 ml to 500 ml
  • 501 ml to 750 ml
  • More than 750 ml

By End Use:

  • Food
    • Processed Food
    • Edible Oil
    • Dry Fruits
    • Bakery & Confectionery
    • Tea & Coffee
    • Dairy Products
    • Baby Food
  • Beverages
  • Pharmaceutical & Nutraceuticals
  • Chemicals
  • Personal Care & Home Care

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Porous Ceramics Market to Reach USD 7,812.3 million by 2033, Driven by Rising Demand in Healthcare and High-Performance Applications

The porous ceramics industry share is predicted to be worth USD 4,084.5 million in 2023 and rise to USD 7,812.3 million by 2033. Demand was initially expanding at a market CAGR of 4.5% between 2018 and 2022.

Demand for porous ceramic filtration products is anticipated to rise as a result of the industrial sector’s use of filtration and separation technologies. However, the high cost of manufacturing is due to high capital expenditure and the price of raw materials, which impedes the global market.

It is projected that the considerable rise in global population raises the demand for goods that lead to better production efficiency. These goods include:

  • Infrastructure
  • Food and beverage items
  • Industrial goods.

According to FMI, this is likely to make it more necessary to use filtering and separation technologies, which benefit the sales of porous ceramics.

Key Takeaways in Porous Ceramics Market Research Report:

  • By 2033, the porous ceramics market in the United Kingdom is likely to expand, with a CAGR of 6.3%.
  • In 2023, the United States is expected to develop in the porous ceramics sector, with a share of 28.4%.
  • The porous ceramics market was significantly expanding, with a size of USD 3,897.4 million in 2022.
  • By 2033, the porous ceramics sector in China is likely to dominate the Asia Pacific region, with a CAGR of 7.4%.
  • In 2023, Germany is anticipated to expand significantly in the porous ceramics business, with an expected share of 7.5%.
  • The porous ceramics sector is expected to develop at a USD 4,961.2 million valuation by 2026, due to the wide range of applications.
  • By 2033, India is projected to expand significantly in the porous ceramics market, with a share of 7.9%.
  • Japan’s porous ceramics industry share is expected to expand significantly, with a 6.9% share in 2023.
  • In 2023, ceramic foam is likely to hold a top spot in the market with a share of 47%. It is expected to dominate the market by 2033 owing to the variety of applications in the end-user industry.
  • Based on the end-user industry, the chemical sector is expected to dominate the market with a share of 42.3% in 2023.

To Gain More Insights about this Research, Visit!

Adapting the Changing Competitive Landscape

The key market participants are vying with one another based on product quality and price. The primary goal is to broaden the product’s application potential in industries like oil and gas, aerospace, and mining.

Porous ceramics businesses are spending a lot of money on research and development to create goods with higher durability. Products made of porous ceramic are in greater demand, which has prompted their manufacturers to release new ones.

Recent Developments in the porous ceramics Sector

  • Mott Corporation, a United States-based provider of precision filtration, purchased Asco Filtri S.p.A. in January 2022. To handle international projects and supply mission-critical filtration products, Mott Corporation now has a stronger presence in North America, Europe, South America, the Middle East, Africa, and Asia as a result of the purchase of Asco.
  • CeramTec introduced porous ceramic membranes for cross-flow membrane filtration in August 2021. These multi-channel tubes are composed of alumina and are utilized in the biotechnology and pharmaceutical sectors, among others for micro, ultra, and nanofiltration.

The Top Key Players are:

  1. Saint-Gobain S.A.
  2. Porvair Plc
  3. 3M Company
  4. Johns Manville

Key Segments in the Porous Ceramics Market: 

By Product Type:

  • Ceramic Honeycombs
  • Ceramic Foam
  • Ceramic Membranes
  • Others

By End Use:

  • Chemical
  • Oil & Gas
  • Environmental
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • Middle East & Africa (MEA)

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Qatar Cement Market Share Set to Surge: Projected Valuation of USD 1,550.9 million by 2032 Amid Robust Infrastructure Growth

According to a research study conducted by Future Market Insights on the Qatar cement industry, demand for cement is expected to reach a valuation of USD 1,550.9 million by 2032.

Rising demand for residential and commercial buildings owing to increasing population and urbanization will boost the Qatar cement market. Demand for residential buildings has increased as the population has surged.

Civic infrastructure and tourism infrastructure are also expected to add positive elements to the cement industry. This has further increased the demand for cement around the world along with Qatar and other regions.

Expansion of the construction industry has a direct impact on the cement industry as cement is one of the essential elements for the construction industry. Cement plays a vital role in the building and construction industry.

Cement is a commonly utilized construction material that is vital to the industry. Expansion of the construction industry is a prominent element that may have an impact on the market.

As the number of construction and infrastructure projects grows, so does the demand for cement.

Increasing government spending on such initiatives will help the cement market to expand. Qatar’s cement market has witnessed a significant growth rate during the past five years due to government initiatives for flourishing its tourism sector.

The country has also invested in infrastructure and commercial buildings such as hotels and staycations. This is attributed to the country’s preparation to host the FIFA World Cup 2022.

The event has added positive elements to Qatar’s economy. Travel & tourism have increased and government officials have announced more budget for innovating the tourism infrastructure.

Key Takeaways from the Qatar Cement Market Study

  • The Qatar cement market is estimated to witness a CAGR of 5.2% on the basis of value between 2022 and 2032.
  • Doha and Al Khor are expected to collectively hold around 45% of the Qatar cement market share by 2032.
  • The residential and commercial buildings segment by end use is expected to surge at a CAGR of 5.1% over the forecast period.
  • The civic infrastructure segment is anticipated to escalate at a CAGR of 5.5% during the estimated time frame.
  • Doha cement market was valued at USD 365.5 million in 2021 and it is projected to surge at a CAGR of 5.1% during the assessment period.

“Increasing civic infrastructure developments across Doha is one of the key factors pushing cement sales in Qatar. Key companies are hence investing in the innovation of tunnels, bridges, ports, and roads to increase Qatar’s exposure and visibility,” says a lead analyst at Future Market Insights.

Browse the Complete Report!

Competitive Landscape: Qatar Cement Market

The cement market in Qatar is moderately fragmented, with big corporations commanding substantial chunks of it. A significant number of medium- and business owners would be advantageous for the market.

Big producers are devoted to expanding their market share and avoiding trade barriers. To guarantee long-term material supply and profit, these manufacturers are also establishing agreements and contracts with other sectors.

They are working on research and development projects for new product creation.

A few of the top manufacturers include

  1. Southern Province Cement Company
  2. Yanbu Cement Company
  3. Yamama Cement Company
  4. Qatar National Cement Company
  5. Arabian Cement Company
  6. Najran Cement Company
  7. Al Khalij Cement Company
  8. United Gulf Cement Company
  9. ALJABOR CEMENT INDUSTRIES CO – HOLCIM

For instance,

  • In July 2022, Ol-Trans, a dominant player in the Polish ready-mix concrete sector, with Holcim Ltd. announced a commitment to the ownership of Ol-Trans’ 5 concrete plants. The manufacturer argues that this acquisition will broaden its network of local ready-mix concrete vendors and reduce its carbon footprint.
  • In 2022, the Saudi National Bank secured assistance from Yamama Cement Co. in the sum of US$ 426 million to boost the production capacity of its new complex in Northern Halal, Al-Kharj.

Get More Insights into the Qatar Cement Market Report

In its latest report, Future Market Insights offers an unbiased analysis of the Qatar cement market, providing historical data from 2017 to 2021 and forecast statistics for the period 2022 to 2032.

To understand the global market potential, growth, and scope, the market is segmented based on product type (ordinary Portland cement, Portland Pozzolana cement, sulfate-resistant Portland cement, blended cement, white cement, Portland slag cement, super grade cement, hydrophobic Portland cement), end use (residential & commercial buildings, civic infrastructure, industrial & marine construction), and region.

Qatar Cement Market Outlook by Category

By Product Type:

  • Ordinary Portland Cement
  • Portland Pozzolana Cement (PPC)
  • Sulfate Resistant Portland Cement
  • Blended Cement
  • White Cement
  • Portland Slag Cement (PSC)
  • Super Grade Cement
  • Hydrophobic Portland Cement

By End Use:

  • Residential and Commercial Buildings
    • Drainage System
    • Beams and Pillars
    • Stairs
    • Roofs and Walls
    • Foundations
    • Others
  • Civic Infrastructure
    • Dams and Ports
    • Roads
    • Bridges
    • Tunnels
    • Culverts and Sewers
    • Power Plants
  • Industrial and Marine Construction

By Country:

  • Al Shamal
  • Al Khor
  • Al Sheehaniya
  • Umm Salal
  • Al Dhaayen
  • Doha
  • Al Rayyan
  • Al Wakrah

Source: FMI Estimates Qatar Cement Market to Witness US$ 1,550.9 Million Revenue Opportunity by 2032, Hosting FIFA 2022 to be a Turning Point for Qatar

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Europe Fine Chemical Market Share Set to Surpass USD 53,714.2 million by 2032, Driven by Pharmaceutical Demand

At the end of the projected year (2032), demand is anticipated to reach a worth of USD 53,714.2 million, according to research on the Europe fine chemical market by Future Market Insights. Production of pharmaceuticals and agrochemicals is expected to continue to be a leading element driving the market’s expansion.

A key portion of the overall consumption in Europe is being catered through the import of various fine chemicals from East Asia. Germany and the United Kingdom are key consumers of fine chemicals in the region owing to the strong presence of prominent end-use industries. Pharmaceuticals remain a prominent end-use industry for fine chemicals followed by the agriculture sector, with the medicine industry consuming active pharmaceutical ingredients which account for a key part of the fine chemical industry.

With the rising population and decreasing agricultural product supply from Ukraine and Russia, demand for agrochemicals is witnessing significant growth to foster the surging requirement for high-yield crops. Boosting demand for pharmaceuticals is expected to propel the consumption of active pharmaceutical products and drugs in the next ten years.

Key companies are establishing new divisions which focus on developing specific drugs for certain events such as hematological oncology and solid tumors. Ongoing research and development activities to develop advanced products with better performance in oncology therapy are also expected to favor demand over the forecast period.

Key Takeaways from Europe Fine Chemical Market Study

  • Fine chemicals are estimated to witness a growth forecast of 9% CAGR on a value basis in the Europe market.
  • Germany and France are expected to collectively account for around 1% of the overall fine chemical market share in Europe.
  • The pharmaceutical segment by product type is expected to create an absolute dollar opportunity of USD 13,686 million between 2022 and 2032 in Europe fine chemical market.
  • Germany is a key importer of fine chemicals with an estimated import volume of 9,711.1 tons in 2021.
  • The Europe market for fine chemicals is estimated to reach a valuation of USD 33,612.1 million in 2022.

“Increasing demand for fine chemicals for the manufacturing of peptides & proteins, active pharmaceutical ingredients, alkaloids, excipients, and steroids would drive sales in the market. Fine chemicals are set to be used for the treatment of cancer and cardiovascular disease,” says a lead analyst at Future Market Insights.

To Gain More Insights about this Research, Visit!

Competitive Landscape: Europe Fine Chemical Market

The Europe fine chemical market is estimated to be a consolidated industry, where key players are expected to account for a prominent share.

A few of the key manufacturers including

  1. Sumitomo Chemicals
  2. BASF SE
  3. GlaxoSmithKline plc
  4. ChemadaIndustries Ltd.
  5. Syntor Fine Chemicals Ltd.
  6. Lonza
  7. Boehringer-Ingelheim International GmbH
  8. Pfizer Inc
  9. Johnson Matthey
  10. Royal DSM N.V
  11. Merck and Co.
  12. Lanxess
  13. Albemarle Corporation
  14. Weylchem International GMBH
  15. Novartis International AG
  16. Borregaard AS
  17. Solvay SA
  18. Evonik Industries AG
  19. Toray Fine Chemicals Co. Ltd
  20. Nippon Fine Chemical Co. Ltd
  21. NOURYON
  22. HUNTSMAN INTERNATIONAL LLC
  23. CLARIANT AG
  24. BAYER AG
  25. Ashland Global Holdings Inc.

To expand their geographic reach globally and acquire traction in the industry, key players are concentrating on raising their production capabilities. Due to the increasing demand for fine chemicals from the pharmaceutical industry, a few prominent businesses are concentrating on investing in their manufacture. The growth strategies of the key market participants also involve contract production for fine chemicals on a merchant basis.

Europe Fine Chemical  Market Segmentation

By Product Type:

  • Pharmaceuticals
  • Agrochemicals
  • Construction Chemicals
  • Additives
  • Specialty Polymers
  • Pigments and Dyes
  • Flavors and Fragrance Ingredients
  • Water Treatment Chemicals
  • Surfactants
  • Others

By Manufacturing Type:

  • Captive
  • Merchant

By End Use:

  • Pharmaceuticals and Nutraceuticals
  • Agriculture Industry
  • Cosmetics and Personal Care
  • Petrochemicals and Plastic Industry
  • Food and Beverages
  • Electronics
  • Paints and Coatings
  • Building and Construction
  • Lubricants and Oil
  • Textiles
  • Others

By Country:

  • Germany
  • Italy
  • France
  • United Kingdom
  • Spain
  • BENELUX
  • Russia
  • Rest of Europe

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Copper’s Role in Construction and Electronics Fuels Market Growth: USA and Canada Expected to Reach USD 32,773.0 million by 2032

According to the study on the USA and Canada copper industry, Future Market Insights (FMI) opines demand for copper is expected to reach USD 32,773.0 million by 2032. Sales of copper in both countries are expected to surge at a CAGR of 5.1% from 2022 to 2032.

Demand for copper from energy transition end markets is expected to surge at a robust pace due to ‘Net-Zero’ emission policies by 2050. Demand from non-energy markets such as electrical & electronics, building & construction, and data processing is also anticipated to expand during the projected period.

Copper is a widely used commercial metal that is extensively adopted all over the world due to its mechanical and structural properties. It also has excellent thermal and electrical conductivity. Copper can resist corrosion owing to its high malleability and ductility, making it easy to shape and manufacture.

Building and construction are set to be one of the most prominent industries for copper, followed by electrical and electronic products. High demand for electronic appliances is expected to boost demand for copper.

As the population and per capita income have increased across Canada and the USA, so has the demand for electronic devices such as laptops, phones, and tablets. In electronics, printed circuit boards are used to connect several components, transfer electrical signals, and maintain the circuit. The market for printed circuit boards has expanded rapidly as a result of increased demand for electrical equipment, resulting in the establishment of the copper industry.

Key Takeaways from the USA and Canada Copper Market Study

  • The USA and Canada copper market is estimated to witness a CAGR of 1% on a value basis between 2022 and 2032.
  • Central Canada is expected to hold around 3% of the copper market share during the assessment period.
  • The building and construction segment by end-use industry is expected to witness a CAGR of 2% in the USA and Canada copper market during the projected period.
  • The West USA copper market is set to witness a CAGR of 6% during the forecast period.
  • During the historical period from 2014 to 2021, the USA and Canada copper market exhibited a CAGR of 7%.

“Increasing demand for electric vehicles in the USA and Canada is estimated to drive copper demand in the next ten years. Copper is set to be extensively used in batteries and wirings of electric vehicles owing to their excellent electrical and thermal conductivity,” says a lead analyst at Future Market Insights.

To Gain More Insights about this Research, Visit!

Competitive Landscape: USA and Canada Copper Market

The market for copper in the USA and Canada is estimated to be highly consolidated, where key players are expected to account for a prominent share. A few of the top manufacturers including

  • Electric Materials Company
  • Madison Metals Limited
  • Mitsubishi Materials Corporation
  • Mehta Tubes Ltd
  • Krishna Engineering Industries
  • Anglo American plc
  • Concast Metal Product Co.
  • Saru Copper Alloy Semis Pvt. Ltd
  • KME Germany GmbH
  • Bright Metals Pvt Ltd
  • Glencore plc
  • Sipi Metals Corp.
  • Belmont Metals Inc.
  • Mueller Industries, Inc.
  • Finkelstein Metals USA

Key players are aiming to broaden their manufacturing capacities to improve their presence all over the globe. They are also striving to gain impetus over their rivals. Few leading companies are focusing on investing huge sums in copper production owing to significantly increasing demand from the building, construction, and electronics industries. The focus of several leading players is on improvised production techniques to get a high yield of pure copper to get maximum benefits.

Get More Insights into the USA and Canada Copper Market Report

In its latest report, Future Market Insights offers an unbiased analysis of the USA and Canada copper market, providing historical data from 2017 to 2021 and forecast statistics for the period 2022 to 2032.

To understand the USA and Canada market potential, growth, and scope, the market is segmented based on end-use industry (building & construction, electrical & electronics products, transportation, consumer & general products, industrial machinery & equipment) & country.

USA and Canada Copper Market Outlook by Category

By End-use Industry:

  • Building and Construction
  • Electrical and Electronic Products
  • Transportation
  • Consumer and General Products
  • Industrial Machinery and Equipment

By Country:

  • The USA
  • Canada

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Ethoxylates Market Expansion: Key Trends Driving a USD 17.4 Billion Valuation in 2033 and Beyond

The global ethoxylates industry size is valued at USD 12.1 billion in 2022 and it is anticipated to achieve a market valuation of USD 12.7 billion in 2023. It is expected to reach a market valuation of USD 17.4 billion by the end of the forecast period while exhibiting a CAGR of 3.2%.

Ethoxylates are utilized across a broad range of applications such as lubricants, cosmetics, soaps & detergents, cleaning chemicals, and solvents. Product consumption in the home & personal care sector is increasing constantly owing to attributes such as rapid surface-wetting, excellent detergency, and low-foaming properties.

The financial stability of the middle class has also increased spending ability for high-quality personal care products. Growing consumer demand for cosmetics, in addition to rising disposable income, will increase the adoption of ethoxylates in the coming years.

The market is expected to be driven by the consumption of ethoxylates across various industries, including personal care, pharmaceutical, industrial, and household cleaning. The product is extensively used as a foaming and wetting agent in detergent and cosmetic product formulations.

Key Takeaways from the Market Study

  • Europe will account for the highest revenue generator in the Ethoxylates market during the forecast period.
  • Asia Pacific is anticipated to be the fastest-growing region while exhibiting a CAGR of 4.5% by 2033.
  • By product type, Alcohol ethoxylates will dominate the segment while registering the highest CAGR.
  • The Alcohol ethoxylates segment is anticipated to be worth USD 13.1 billion by the end of 2033.
  • By Application type, household, and personal care is expected to dominate the segment during the forecast period.
  • The demand and consumption of ethoxylates across various industries, including personal care, pharmaceutical, industrial, and household cleaning will drive the ethoxylates market.

“The market’s expansion may be linked to a paradigm shift toward workflows and process automation across a wide range of businesses and industrial verticals. Enterprises all over the world are eager to embrace effective and smooth business processes that can be executed regardless of location, which is propelling this industry ahead.” comments a Future Market Insights analyst.

To Gain More Insights about this Research, Visit!

Competitive Landscape

The global ethoxylates market is consolidated with few large and medium-sized players accounting for most of the market revenue. Major players are deploying various strategies, entering into mergers and acquisitions, strategic agreements, and contracts, developing testing, and introducing more effective ethoxylates solutions.

Some of the major companies included in the global ethoxylates market report are-

  • Dow Chemical Company
  • BASF
  • Royal Dutch Shell PLC
  • Petroliam Nasional Berhad
  • Ecogreen Oleochemicals
  • PT Polychem Indonesia Tbk
  • Stepan Company
  • Clariant
  • Sasol Limited
  • India Glycols Ltd
  • Ineos Group Ltd.
  • Solvay
  • Oxiteno
  • Galaxy Surfactants
  • Nouryon
  • SABIC
  • Evonik
  • Mitsui Chemicals Inc.
  • PCC Exol
  • Arkema Group

Some of the recent key developments among key players are:

  • On 26 May 2022, BASF, which is a Germany-based chemical company announced the BASF hub program in collaboration with AHK Romania. The hub will bring together start-ups and innovators from 11 central and southeast European nations, including Romania. The project’s objective is to serve as a launching pad for new businesses, promoting the best ideas and providing financial assistance.
  • On 12 May 2022, Royal Dutch Shell, a UK-based oil, and gas chemical signed an agreement with Lukoil to sell lubricants and retail businesses in Russia. The deal includes 411 retail stations mostly in Russia’s northwestern and central regions as well as the lubricants lending factory in Torzhok, located around 200 kilometers north of Moscow. The purchase of the shell’s high-quality business in Russia is in line with LUKOIL’s goal to expand its key sales channels, including retail and the lubricant business.

More Valuable Insights

Future Market Insights, in its new offering, presents an unbiased analysis of the global ethoxylates market, presenting a historical analysis from 2018 to 2022 and forecast statistics for the period of 2023-2033.

Key Segments Profiled in the Ethoxylates Market Survey

By Application:

  • Household and Personal Care
    • Laundry & Dishwashing Detergent
    • Industrial & Institutional Cleaning
    • Personal Care
  • Agrochemicals
    • Herbicides
    • Fungicides
    • Insecticides
  • Oil and Gas
    • Foam-Control & Wetting Agents
    • Lubricants & Emulsifiers
  • Pharmaceuticals
  • Other Applications

By Product:

  • Alcohol
    • Natural Alcohol Ethoxylates
    • Synthetic Alcohol Ethoxylates
  • Fatty Amine
  • Fatty Acid
  • Methyl Ester
  • Glyceride

By Region:

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East and Africa (MEA)

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Sustainable and Durable: Composite Cardboard Tube Packaging Market Trends and Future Outlook

According to Future Market Insights (FMI), the global composite cardboard tube packaging market is on track for significant growth, with a valuation of USD 1.7 Billion in 2022 and a projected CAGR of 5.4%, culminating in a market size of USD 2.9 Billion by 2032. The growth trajectory underscores the increasing demand for sustainable and versatile packaging solutions across industries.

Growth Drivers: The market’s robust growth is fueled by increasing consumer preference for eco-friendly packaging solutions and the versatility of composite cardboard tubes in protecting products during transit. Their lightweight, recyclable nature, and ability to support diverse branding and customization needs make them a preferred choice among industries ranging from cosmetics to food and beverages.

Request a Report Sample:  https://www.futuremarketinsights.com/reports/sample/rep-gb-4464

Core Concepts in the Composite Cardboard Tube Packaging Industry

  • 2021 Market Value : The global Composite Cardboard Tube Packaging market reached US$ 1.6 billion in 2021.
  • Historic Growth Rate : The market expanded at a CAGR of 3.6% from 2015 to 2021.
  • 2032 Market Projection : By 2032, the market is projected to reach US$ 2.9 billion.
  • 2022-2032 Growth Rate : From 2022 to 2032, the market is anticipated to register a CAGR of 5.4%.
  • Future Growth Outlook : The market is estimated to grow 1.8 times its current value during the forecast period.
  • Leading Can Diameter Segment : The 50mm-100mm segment by can diameter is expected to lead the market during the forecast period.
  • Demand Drivers : Increasing demand for rigid packaging for packed food is driving the demand for composite cardboard tube packaging.
  • Key Players : Key players in the global market include Smurfit Kappa Group Plc, Mondi Group Plc, Sonoco Products Company, Canfab Packaging Inc., and COREX Group.
  • India Market Growth : The Indian composite cardboard tube packaging market is projected to grow at a CAGR of 8.2% from 2022 to 2032, according to FMI analysis.

Market Dynamics

Rising Demand for Eco-Friendly Packaging: Consumer preferences are shifting towards sustainable packaging solutions due to heightened environmental awareness. Composite cardboard tube packaging, known for its recyclability and protective properties, is gaining traction as a replacement for plastic tube packaging.

Key Growth Drivers

Innovative Packaging Formats: Manufacturers are increasingly adopting composite cardboard tube packaging for its ability to offer excellent barrier properties and extend shelf life, particularly in the food and beverage sectors. This shift is driven by regulatory pressures and consumer demand for environmentally responsible packaging solutions.

Country-Specific Insights

1. Germany: The German market for composite cardboard tube packaging is expected to grow at a CAGR of 4.5%, driven by the rising consumption of packaged foods. Germany ranks among the top markets for packed foods globally, spurring demand for reliable and sustainable packaging solutions.

2. United States: In North America, the USA is poised to dominate the composite cardboard tube packaging market, capturing approximately 81% of the regional market share by the end of the forecast period. The use of cardboard tubes for premium packaging of wine bottles is particularly significant, aligning with the country’s status as the largest consumer of wine globally.

Regional Outlook: 

Based on geography, the global composite cardboard tube packaging market is segmented into North America, Latin America, Europe, Middle East & Africa, and Asia Pacific. North America is currently leading the global composite cardboard tube packaging market as the North American population has a comparatively high standard of living and are willing to pay for efficient packaging types.

High disposable income of the consumers in North America and Europe is also one of the prime factor driving the demand of composite cardboard tubes in the region. Latin America is expected to witness stagnant growth over the forecast period due to a down turning economy.

Latin America serves as a low cost manufacturing source for products to supply its North American counterparts. Asia pacific countries like India and China are expected to witness steady growth in the composite cardboard tube packaging market due to increase in the urban class and rising retail sector.

Key players: 

Some of the key players operating in the global composite cardboard tube packaging market are Smurfit Kappa Group, CBT Packaging, Visican Ltd., Darpac P/L, and Humber Print & Packaging Limited

The research report presents a comprehensive assessment of the market and contains thoughtful insights, facts, historical data, and statistically supported and industry-validated market data. It also contains projections using a suitable set of assumptions and methodologies. The research report provides analysis and information according to categories such as market segments, geographies, type of product and applications.

Access Full Report: https://www.futuremarketinsights.com/reports/composite-cardboard-tube-packaging-market

Composite Cardboard Tube Packaging by Category

By Closure Type, Composite Cardboard Tube Packaging is Segmented as:

  • Caps
  • Lids

By Can Diameter, Composite Cardboard Tube Packaging is Segmented as:

  • Less than 50 mm
  • 50 mm to 100 mm
  • Above 100 mm

By End Use, Composite Cardboard Tube Packaging is Segmented as:

  • Food & Beverages
  • Household
  • Cosmetics & Personal Care
  • Other Consumer Goods

By Region, Composite Cardboard Tube Packaging is Segmented as:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Middle East & Africa (MEA)
  • Oceania

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer, Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:       

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube