Surgical Instruments Tracking System Market to Hit USD 1.4 Trillion by 2035 at 13.9% CAGR

The surgical instruments tracking system market is set to witness substantial growth between 2025 and 2035, driven by the increasing need for efficient surgical instrument management, compliance with regulatory mandates, and the adoption of advanced tracking technologies. The market is projected to expand from USD 320,000 million in 2025 to USD 1,400,000 million by 2035, reflecting a compound annual growth rate (CAGR) of 13.9% over the forecast period.

The surgical instruments tracking system market has emerged as a vital component in modern healthcare infrastructure. As hospitals and surgical centers strive for higher levels of patient safety, operational efficiency, and regulatory compliance, the need for reliable instrument tracking solutions has grown significantly. This market revolves around the deployment of advanced technologies such as RFID, barcodes, and real-time location systems (RTLS) to monitor surgical instruments throughout their lifecycle—from sterilization and storage to usage and inventory management. These systems not only help prevent errors during surgical procedures but also reduce the loss and misplacement of high-value instruments, thereby lowering overall operational costs.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14251

Healthcare institutions globally are becoming increasingly aware of the need to improve workflow transparency and enhance traceability. This awareness has created substantial demand within the surgical instruments tracking system market. Hospitals are now investing heavily in automation technologies to improve their compliance with international regulatory standards such as those from the FDA and Joint Commission, which mandate detailed records of surgical instrument usage and sterilization histories. As a result, the integration of surgical instruments tracking systems is rapidly becoming a standard best practice in the healthcare industry.

Market Trends

One of the key trends shaping the surgical instruments tracking system market is the growing adoption of cloud-based platforms. These systems allow hospitals to store and manage large volumes of tracking data with increased accessibility and reduced infrastructure costs. Moreover, cloud solutions facilitate real-time updates and interoperability across multiple hospital departments, enhancing communication and decision-making.

Another significant trend is the integration of artificial intelligence (AI) and machine learning algorithms. These technologies are being used to predict instrument demand, track maintenance schedules, and analyze usage patterns to optimize resource allocation. Additionally, mobile applications and smart dashboards are increasingly being used by medical staff to monitor the status of surgical instruments remotely, providing greater flexibility and control.

The shift toward disposable surgical instruments in some settings is also influencing market dynamics. While this trend may reduce the need for tracking reusable tools, it increases the necessity of accurately tracking disposable inventory for cost and compliance purposes. Therefore, companies in the surgical instruments tracking system market are adapting their solutions to cater to both reusable and single-use surgical devices.

Driving Forces Behind Market Growth

Several driving forces are fueling the growth of the surgical instruments tracking system market. A primary factor is the rising volume of surgical procedures worldwide. With aging populations and an increase in chronic diseases, the demand for surgical interventions continues to grow. This surge places added pressure on hospitals to manage their surgical instruments more efficiently, pushing the need for robust tracking systems.

Regulatory compliance is another strong driver. Government bodies across various regions are enforcing stringent standards to ensure patient safety. Regulations now require hospitals to maintain detailed logs of instrument usage, cleaning cycles, and sterilization records. Failing to meet these standards can result in legal consequences, financial penalties, and reputational damage. Hence, healthcare providers are increasingly turning to tracking systems to meet these demands.

Operational efficiency and cost reduction also play a significant role. Tracking systems help reduce instrument misplacement, lower surgical delays, and minimize unnecessary procurement of duplicate tools. These efficiencies lead to significant cost savings, particularly in large healthcare facilities with extensive instrument inventories. As such, financial and operational benefits are strong incentives for market adoption.

Challenges and Opportunities

Despite its many advantages, the surgical instruments tracking system market faces several challenges. One of the primary barriers is the high initial cost of implementation. For many hospitals, particularly in low- and middle-income countries, the upfront investment in tracking hardware, software, and staff training can be prohibitive. Additionally, integration with legacy hospital information systems can be complex and time-consuming, leading to delays and increased costs.

Another challenge is data security. As more systems move to the cloud, concerns around patient data privacy and compliance with data protection regulations such as HIPAA have become increasingly important. Companies must ensure their solutions are secure and compliant with evolving legal requirements.

Nonetheless, these challenges also present opportunities. The growing awareness of these issues is pushing vendors to develop more cost-effective and user-friendly solutions. Cloud-based subscription models, modular system designs, and scalable platforms are becoming more prevalent. Moreover, partnerships between tracking solution providers and healthcare organizations are driving innovation and better product-market fit.

Recent Industry Developments

Recent developments in the surgical instruments tracking system market have focused on expanding functionality and enhancing usability. Many companies have launched next-generation solutions that incorporate AI and analytics to provide predictive maintenance alerts, utilization reports, and compliance dashboards. These innovations offer healthcare providers deeper insights into their operations, enabling proactive decision-making.

In addition, mergers and acquisitions have become more common as established players seek to strengthen their product offerings and expand their geographic reach. For instance, leading tracking system providers have acquired barcode and RFID technology firms to integrate end-to-end solutions under one umbrella. This consolidation trend is likely to continue as the market matures and competition intensifies.

Standardization efforts have also advanced. Industry bodies are working to create uniform tracking protocols and data formats to improve interoperability among different systems. Such standardization is expected to reduce integration complexity and foster broader adoption, particularly in multi-hospital systems.

Regional Analysis

The surgical instruments tracking system market exhibits regional variations driven by healthcare infrastructure, regulatory environments, and economic conditions. North America currently holds a dominant position due to the presence of advanced healthcare facilities, stringent regulatory mandates, and high adoption rates of healthcare IT solutions. The United States, in particular, has been a frontrunner in implementing surgical tracking technologies due to FDA guidelines requiring Unique Device Identification (UDI).

Europe follows closely, with countries like Germany, the UK, and France showing strong growth. Regulatory compliance, rising healthcare expenditure, and government initiatives promoting digital health transformation have contributed to regional market expansion.

The Asia-Pacific region is poised for significant growth, driven by rapidly expanding healthcare systems in countries like China, India, and Japan. Increasing surgical volumes, government investments in healthcare infrastructure, and growing awareness of patient safety are key factors driving adoption in this region. However, the cost of implementation remains a challenge in some parts of Asia, particularly in rural areas.

In contrast, Latin America and the Middle East & Africa are still in the early stages of adoption. Although these regions present untapped potential, limited healthcare budgets and infrastructure challenges may slow the pace of growth in the near term.

Competitive Outlook

The surgical instruments tracking system market is moderately fragmented, with several key players competing based on technology innovation, service quality, and pricing. Companies are increasingly focusing on developing comprehensive solutions that combine hardware, software, and support services into an integrated offering.

Competition is also intensifying in the mid-tier and smaller hospital segments. Vendors are targeting these customers with more affordable, modular solutions that can be scaled according to the institution’s needs. As pricing becomes a differentiator, companies offering value-driven solutions with strong customer support are gaining market share.

Innovation remains a key competitive strategy. Companies are investing in research and development to enhance system capabilities, improve user interfaces, and enable mobile and remote access. These advancements help providers stay ahead of evolving customer needs and industry regulations.

Top Companies

Several prominent companies are leading the surgical instruments tracking system market. These include STANLEY Healthcare, Becton, Dickinson and Company (BD), Getinge Group, Key Surgical, and STERIS Corporation. Each of these companies offers a diverse portfolio of tracking solutions tailored to different hospital requirements and budgets.

STANLEY Healthcare is recognized for its advanced RTLS technology and comprehensive tracking solutions, while BD focuses on seamless integration with hospital management systems. Getinge and STERIS offer robust sterilization and workflow management tools integrated with tracking capabilities. Key Surgical specializes in sterile processing and instrument care, offering tracking systems that enhance compliance and operational oversight.

Startups and niche players are also emerging with specialized offerings, particularly in the areas of mobile tracking apps, cloud platforms, and AI-based analytics. These new entrants are bringing fresh innovation and driving competition within the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/surgical-instruments-tracking-system-market

Segmentation Outlook

The surgical instruments tracking system market can be segmented based on technology, component, end-user, and geography. In terms of technology, barcode and RFID solutions dominate, with RTLS gaining traction in high-end applications. RFID, in particular, is preferred for its automation and bulk scanning capabilities.

Component-wise, the market includes hardware (tags, readers), software (tracking platforms, analytics), and services (consultation, training, support). Software is expected to witness the fastest growth due to increasing demand for data-driven insights and predictive analytics.

By end-user, hospitals are the largest segment due to the high volume of surgical procedures and the need for strict compliance. Ambulatory surgical centers and specialty clinics are also adopting tracking systems to enhance efficiency and reduce costs.

Geographically, the market is expanding across all major regions, with North America and Europe leading in adoption, and Asia-Pacific presenting significant future opportunities. As the healthcare industry continues to digitize and streamline its operations, the demand for surgical instruments tracking systems will continue to grow across diverse healthcare settings.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
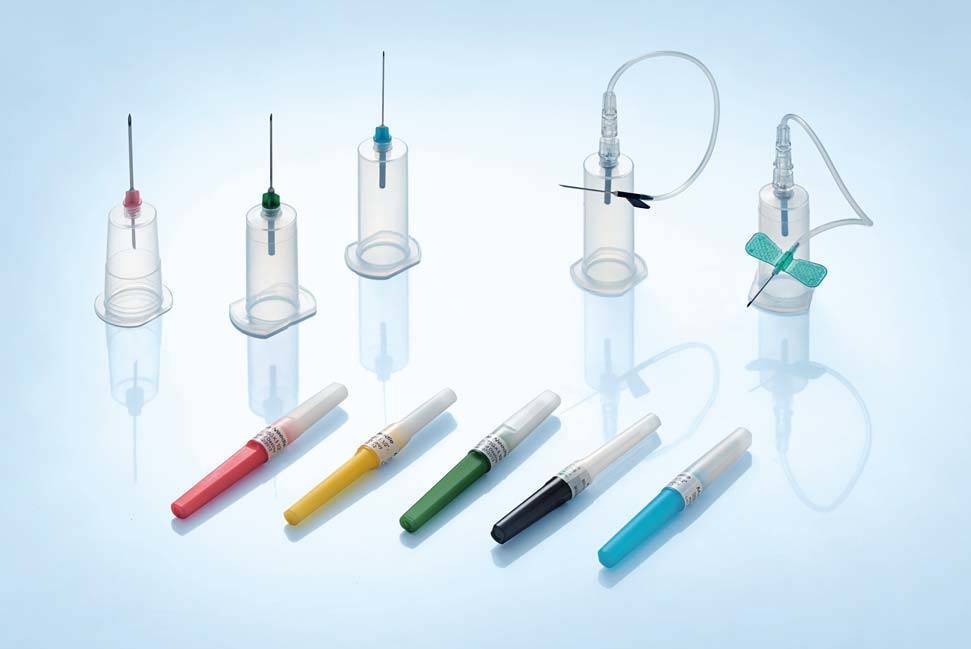
 

Blood Collection Devices Market Expands to USD 16.37B by 2035 with 6.5% CAGR

The blood collection devices market will experience steady expansion from 2025 to 2035 through growing demand for diagnostic testing, chronic disease escalation, and increased medical technology progress. The industry will grow from USD 8.72 billion in 2025 to reach USD 16.37 billion by 2035, attaining a compound annual growth rate (CAGR) of 6.5% during this period.

The blood collection devices market plays a pivotal role in the broader healthcare and diagnostics industry. As diagnostic testing and disease detection become increasingly vital for global health management, the demand for efficient and safe blood collection techniques continues to grow. Blood collection devices are essential for obtaining blood samples for clinical testing, blood donation, and transfusion purposes. These devices ensure that blood is collected with minimal discomfort to the patient and with reduced risks of contamination or infection.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14249

The evolution of healthcare technologies and the growing prevalence of chronic diseases have further driven the adoption of advanced blood collection devices. Hospitals, clinics, diagnostic laboratories, and blood banks all rely heavily on these tools to maintain accuracy and efficiency in sample collection. With the rise of minimally invasive procedures and a heightened focus on patient safety, manufacturers are continually innovating to meet the demands of healthcare professionals and regulatory bodies alike. As a result, the blood collection devices market is undergoing steady expansion and technological transformation.

Market Trends

One of the most noticeable trends in the blood collection devices market is the growing preference for safety-engineered devices. These include tools designed to prevent needlestick injuries and reduce exposure to bloodborne pathogens. The push for safety is especially strong in developed nations, where strict occupational health regulations have led to a surge in demand for single-use and retractable needle systems.

Another emerging trend is the integration of automation in blood collection processes. Automated blood collection systems enhance efficiency in high-volume laboratories and ensure consistency in sample handling. These innovations not only minimize manual errors but also improve turnaround times in diagnostics, making them invaluable in time-sensitive testing environments.

The increasing prevalence of diseases such as diabetes, cancer, and cardiovascular disorders has also contributed to higher testing volumes. This, in turn, drives the need for reliable and scalable blood collection solutions. Moreover, growing awareness among patients about early disease detection is encouraging regular health check-ups, further boosting the blood collection devices market.

Technological advancements in capillary blood collection, especially for point-of-care testing, are also shaping the market. Devices designed for home use and remote diagnostics are gaining popularity, especially in the wake of recent global health events that highlighted the need for decentralized testing solutions.

Challenges and Opportunities

While the blood collection devices market is poised for growth, it is not without its challenges. One of the main obstacles is the variability in regulatory standards across different regions. Manufacturers must navigate a complex landscape of compliance requirements, which can delay product approvals and market entry. The cost of compliance, coupled with the need for continuous innovation, can strain the resources of smaller market players.

In addition, the high cost of advanced blood collection systems can be a barrier to adoption in low-income and middle-income countries. In these regions, healthcare infrastructure may not be robust enough to support the widespread use of sophisticated devices, leading to continued reliance on traditional tools. This creates a gap in global market penetration that companies must address to maximize their reach.

However, the challenges also present opportunities. Increasing healthcare investments in emerging economies, coupled with the rising burden of chronic diseases, offer a fertile ground for market expansion. Companies that can provide cost-effective and scalable solutions have the potential to tap into underserved markets. Strategic partnerships with local healthcare providers and governments can also accelerate adoption and build long-term market presence.

Another opportunity lies in the growing trend toward personalized medicine and targeted diagnostics. As the healthcare industry shifts toward precision-based care, there is a rising demand for specialized blood collection techniques that can support complex genetic and molecular tests. Companies that can innovate in this direction are likely to gain a competitive edge in the blood collection devices market.

Key Regional Insights

Geographically, the blood collection devices market displays significant diversity in terms of demand and growth potential. North America remains a dominant force, primarily due to its advanced healthcare infrastructure, high patient awareness, and favorable reimbursement policies. The United States, in particular, leads in innovation and adoption of safety-engineered devices, contributing significantly to the region’s market share.

Europe also holds a substantial portion of the market, with countries like Germany, France, and the United Kingdom playing key roles. The region benefits from stringent healthcare regulations and a strong focus on patient safety, which supports the widespread adoption of advanced blood collection technologies. Additionally, rising health screening initiatives across the European Union contribute to the market’s steady growth.

Asia-Pacific is emerging as a lucrative region for the blood collection devices market. Countries like China, India, and Japan are witnessing rapid advancements in healthcare infrastructure, rising healthcare expenditures, and increasing awareness about early disease diagnosis. The large patient population and growing medical tourism sector further enhance the region’s market potential.

Latin America and the Middle East & Africa are showing gradual improvement in market performance. While these regions face infrastructure and economic challenges, ongoing healthcare reforms and investments by international health organizations are beginning to bridge the gaps. These regions represent untapped opportunities for companies looking to expand their global footprint.

Competitive Outlook

The blood collection devices market is highly competitive, with several established players and a growing number of new entrants vying for market share. Innovation remains a key differentiator, as companies invest heavily in research and development to bring new and improved devices to market. Features such as ergonomic design, enhanced safety mechanisms, and compatibility with automated systems are increasingly becoming standard expectations.

Mergers, acquisitions, and strategic collaborations are common as companies seek to enhance their product portfolios and expand their geographic reach. Partnerships with hospitals, diagnostic chains, and health ministries are also vital in securing contracts and promoting long-term adoption.

Furthermore, companies are focusing on sustainability in manufacturing and packaging processes to align with global environmental goals. The move toward eco-friendly and recyclable materials is gradually gaining traction, especially in regions with stringent environmental regulations.

Top Companies

Several key players dominate the blood collection devices market, offering a broad range of products tailored for different applications. These companies are known for their innovation, strong distribution networks, and ability to adapt to changing market demands. Many of them have diversified their offerings to include not only blood collection needles and tubes but also accessories like holders, lancets, and safety devices.

Companies with a strong presence often enjoy long-standing relationships with healthcare institutions, giving them a competitive advantage. They invest significantly in training and customer support services, ensuring that end-users are equipped to handle their devices efficiently and safely.

The global presence of these companies also enables them to benefit from economies of scale, allowing for competitive pricing strategies. However, regional players are gaining ground by offering locally manufactured, affordable alternatives that cater to specific regional needs.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/blood-collection-devices-market

Segmentation Outlook

The blood collection devices market can be segmented based on product type, application, end-user, and geography. By product type, the market includes needles and syringes, blood collection tubes, lancets, and other accessories. Among these, vacuum blood collection tubes are gaining popularity due to their convenience and safety features.

In terms of application, the market serves clinical diagnostics, blood donation, and therapeutic procedures. Diagnostic applications dominate the market due to the increasing need for laboratory tests in disease detection and management.

When segmented by end-user, hospitals and diagnostic laboratories account for the largest share. However, the home healthcare and point-of-care testing segments are growing rapidly, driven by technological advancements and a shift toward decentralized care.

Geographically, segmentation allows for targeted marketing strategies and helps companies cater to the unique demands of each region. Tailoring product offerings and pricing strategies to regional preferences and capabilities is essential for success in the global blood collection devices market.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
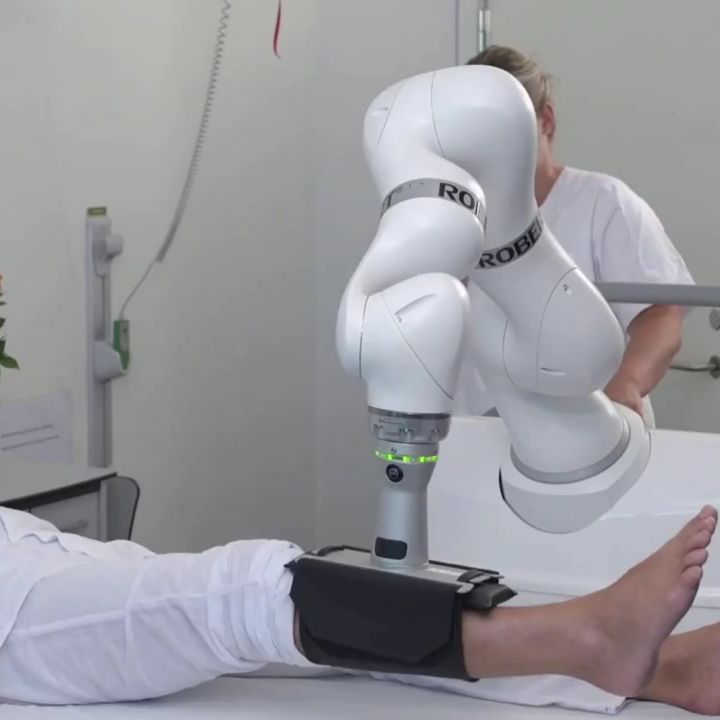
 

Medical Rehabilitation Robotics Market Grows from USD 570.2M in 2025 to USD 2.36m by 2035 at 15.3% CAGR

The medical rehabilitation robotics market is steadily transforming the landscape of post-acute care and physical therapy. With a focus on assisting patients with mobility impairments, these robotic solutions are enabling faster, safer, and more efficient rehabilitation processes. The integration of robotics into medical rehabilitation not only enhances patient outcomes but also aids healthcare professionals in delivering consistent and repetitive therapies that are often difficult to achieve manually. These systems are increasingly being adopted in hospitals, outpatient centers, and home care settings, contributing to the ongoing modernization of healthcare services.

The market is expected to reach USD 570.2 million in 2025 and is projected to grow to USD 2,367.6 million by 2035, registering a compound annual growth rate (CAGR) of 15.3% over the forecast period. One of the major drivers of this market is the increasing adoption of robotic rehabilitation solutions in post-stroke and spinal cord injury treatments.

As global healthcare systems continue to emphasize patient-centric solutions, the demand for advanced technologies in rehabilitation is surging. Medical rehabilitation robotics offer a perfect amalgamation of mechanical precision and personalized therapy. Their ability to collect real-time data and monitor patient progress ensures that rehabilitation plans are adaptable and tailored, improving recovery timelines. This technological evolution is crucial for treating patients with neurological disorders, spinal cord injuries, strokes, and musculoskeletal issues.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14242

Size & Trends

The medical rehabilitation robotics market has witnessed substantial growth in recent years due to increasing awareness and the growing prevalence of chronic conditions. The expanding geriatric population, which is more susceptible to physical disabilities, further fuels the need for robotic-assisted therapy. Technological innovations such as AI-powered exoskeletons, sensor-integrated systems, and remote monitoring capabilities are shaping current market trends.

The adoption of rehabilitation robots is not limited to developed countries. Emerging economies are gradually investing in healthcare infrastructure that includes robotic technologies. Moreover, there is a notable trend toward the development of compact and affordable robotic rehabilitation devices tailored for home use. This shift allows patients to continue therapy beyond clinical settings, ultimately contributing to sustained market expansion.

Key Highlights

One of the key highlights of the medical rehabilitation robotics market is the integration of artificial intelligence and machine learning. These technologies empower robotic systems to adapt to individual patient needs, making therapy sessions more effective. Another significant advancement is the incorporation of virtual and augmented reality, enhancing user engagement and motivation during therapy exercises.

Collaborations between technology companies and healthcare providers are becoming more common, leading to innovative product development and improved therapeutic protocols. Additionally, insurance providers in some regions are beginning to cover robotic-assisted rehabilitation, which enhances market accessibility. These milestones indicate strong momentum and confidence in the growth and utility of robotic rehabilitation.

Challenges and Opportunities

Despite its promising growth, the medical rehabilitation robotics market faces several challenges. High initial costs of robotic systems often deter small and medium healthcare providers from adopting them. Moreover, a lack of skilled professionals who can operate and maintain these advanced machines limits their usage. Some regions still face regulatory hurdles that delay product approvals and implementation.

However, these challenges are counterbalanced by several opportunities. The growing focus on personalized medicine and precision healthcare creates room for innovation in robotic design and functionality. Educational programs and certifications for healthcare workers in robotic operations are also gaining traction, which will support future market adoption. Furthermore, increasing investments in research and development are likely to yield cost-effective and versatile solutions, broadening the potential user base.

Key Benefits for Stakeholders

For stakeholders across the healthcare ecosystem, the medical rehabilitation robotics market offers a range of advantages. Healthcare providers benefit from reduced physical strain, enhanced therapy efficiency, and improved patient outcomes. For patients, robotic systems offer consistent and measurable rehabilitation experiences, which are especially beneficial for those requiring long-term care or dealing with chronic conditions.

Manufacturers and technology developers gain access to a growing market with numerous possibilities for innovation. Government agencies and insurers are also realizing the long-term cost-saving potential of robotic-assisted therapy, especially as it reduces hospital readmissions and promotes quicker recovery. Collectively, these benefits contribute to the rising integration of robotics into mainstream rehabilitation protocols.

Market Share by Geographical Region

Geographically, the medical rehabilitation robotics market shows strong penetration in North America and Europe, attributed to well-established healthcare systems and early adoption of advanced medical technologies. These regions also benefit from government support and significant investments in healthcare R&D. The presence of key market players further strengthens their dominance.

Asia-Pacific is emerging as a significant growth area due to its rapidly aging population, rising healthcare expenditure, and increasing adoption of automation in the medical field. Countries like China, Japan, and South Korea are leading the region in terms of technological innovation and implementation. In contrast, Latin America and the Middle East & Africa show moderate growth, mainly driven by improvements in healthcare infrastructure and increasing awareness of robotic rehabilitation.

Competitive Outlook

The medical rehabilitation robotics market is characterized by intense competition and rapid technological advancements. Established players are continuously investing in research and partnerships to maintain their market position and deliver innovative solutions. New entrants are also making strides by offering niche and cost-effective products tailored to specific rehabilitation needs.

Innovation is a key differentiator in this competitive landscape. Companies are focusing on making their devices more user-friendly, portable, and connected, aligning with the increasing trend toward remote healthcare. Mergers, acquisitions, and strategic collaborations are common as businesses aim to expand their geographical reach and product portfolios. Regulatory compliance, product efficacy, and pricing strategies play crucial roles in shaping competitive dynamics.

Top Companies

Several leading companies are spearheading the development and commercialization of rehabilitation robotics. These include both long-standing medical device manufacturers and specialized robotic firms. Their commitment to improving healthcare through automation and innovation has led to a wide range of products catering to different patient demographics and rehabilitation requirements.

These top players often leverage advanced technologies such as AI, cloud computing, and sensor fusion to enhance the performance and accuracy of their systems. Their strong distribution networks, combined with comprehensive customer support, enable them to maintain a robust presence in both developed and developing markets. Ongoing product launches and patent filings reflect their continuous drive for advancement in this dynamic market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/medical-rehabilitation-robotics-market

Segmentation Outlook

The medical rehabilitation robotics market can be segmented based on product type, application, end-user, and geography. Product types generally include exoskeletons, therapeutic robots, and assistive robots. Each category serves unique purposes—from restoring motor function to supporting daily activities for physically challenged individuals.

In terms of application, these robotics are widely used for neurological rehabilitation, orthopedic rehabilitation, and cardiovascular therapy. Neurological applications, particularly for stroke and spinal cord injury patients, dominate the market due to the high prevalence and long recovery periods associated with such conditions. End-users primarily include hospitals, rehabilitation centers, and homecare settings, with home-based robotics showing rising adoption due to convenience and cost-efficiency.

Geographical segmentation reveals a varied adoption pattern, largely influenced by healthcare infrastructure, economic conditions, and technological readiness. Tailoring solutions to regional needs and ensuring compliance with local regulatory standards are critical for companies looking to capitalize on diverse markets.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
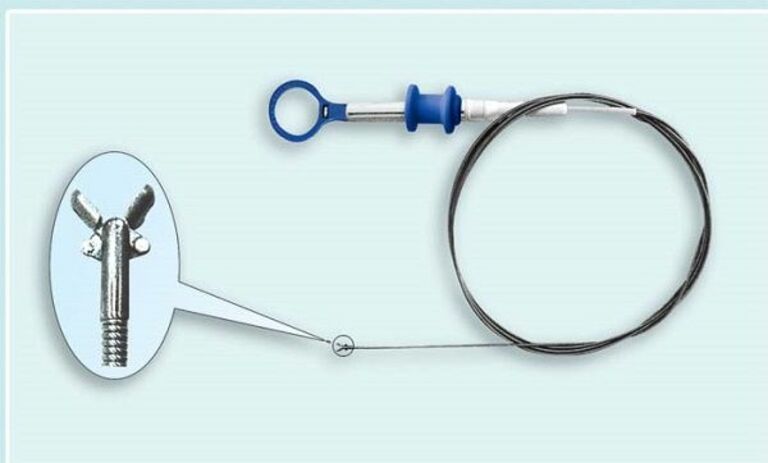
 

Cold Disposable Biopsy Forceps Market to Hit USD 1.57M by 2035, Growing at 7.8% CAGR

The cold disposable biopsy forceps market has gained substantial momentum in recent years, driven by the rising demand for efficient and safe endoscopic biopsy tools. These medical instruments are essential in collecting tissue samples during endoscopic procedures, particularly when heat application is not preferred. Unlike hot biopsy forceps, cold variants are designed to extract tissue samples without causing thermal damage, reducing the risk of complications such as bleeding and tissue charring. As healthcare systems globally strive to enhance diagnostic accuracy and patient outcomes, the use of cold disposable biopsy forceps continues to grow across multiple specialties, including gastroenterology, pulmonology, and urology.

In 2025, the global cold disposable biopsy forceps market is projected to reach approximately USD 742.9 million, with expectations to grow to around USD 1,574.4 million by 2035, reflecting a Compound Annual Growth Rate (CAGR) of 7.8% during the forecast period.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14240

Market Trends

One of the most prominent trends in the cold disposable biopsy forceps market is the transition from reusable to disposable instruments. This shift is largely driven by concerns over cross-contamination and infection control. Hospitals and clinics are increasingly opting for disposable tools to minimize the risks associated with inadequate sterilization. Moreover, improvements in design and material science have enabled the production of more effective and cost-efficient disposable forceps, which offer comparable performance to their reusable counterparts.

Another noteworthy trend is the rising integration of ergonomics into forceps design. Manufacturers are focusing on user-friendly handles and enhanced tip precision, facilitating better control for physicians and improved tissue sample quality. Additionally, advancements in minimally invasive techniques have led to a higher frequency of endoscopic procedures, indirectly fueling demand in the cold disposable biopsy forceps market.

Driving Forces Behind Market Growth

Several factors are driving the expansion of the cold disposable biopsy forceps market. First and foremost is the increasing prevalence of chronic diseases such as gastrointestinal cancers and inflammatory bowel disease. The growing need for early diagnosis and regular monitoring has led to a surge in endoscopic procedures, which require reliable and sterile biopsy instruments.

Technological advancements in endoscopy equipment and accessories also contribute significantly to market growth. Innovations in imaging and navigation systems enhance the accuracy of biopsy procedures, making it crucial for the supporting tools, like biopsy forceps, to maintain high performance and reliability. Furthermore, the global emphasis on healthcare infrastructure development, especially in emerging economies, has increased access to advanced diagnostic tools, including cold disposable biopsy forceps.

An aging population is another key driver. As the global demographic shifts towards a higher percentage of elderly individuals, the incidence of age-related conditions requiring diagnostic interventions is on the rise. This demographic change has created a sustained demand for endoscopic diagnostics and, by extension, for the cold disposable biopsy forceps market.

Challenges and Opportunities

Despite its growth, the cold disposable biopsy forceps market faces certain challenges. One of the most pressing issues is the environmental impact associated with disposable medical devices. The increased use of single-use tools has raised concerns about medical waste and its disposal. Regulatory agencies and healthcare institutions are under pressure to implement sustainable practices, which may affect the adoption rate of disposable products unless environmentally friendly alternatives are developed.

Cost constraints also pose a barrier, particularly in developing regions where healthcare budgets are limited. While disposable forceps offer safety and convenience, their recurrent cost can be a burden for facilities with high patient volumes. This opens up opportunities for manufacturers to innovate with affordable yet high-quality options tailored for cost-sensitive markets.

On the opportunity front, the rising adoption of telemedicine and mobile health services in rural and underserved areas presents new growth avenues. Portable endoscopic solutions, coupled with disposable biopsy tools, can enable real-time diagnostics in non-traditional settings, thereby expanding the reach of the cold disposable biopsy forceps market.

Recent Industry Developments

The cold disposable biopsy forceps market has witnessed several notable developments in recent years. Many companies have launched new product lines featuring improved cutting mechanisms and enhanced maneuverability. These innovations aim to provide superior specimen quality while reducing procedure time and patient discomfort.

Additionally, several strategic collaborations and acquisitions have taken place, with key players aiming to strengthen their market position and broaden their product portfolios. Investment in research and development is also on the rise, with a strong focus on creating devices that meet both clinical and regulatory standards across various regions.

Regulatory approvals have also shaped the market landscape, with newer models receiving clearance from authorities like the FDA and CE. These approvals not only validate product safety and efficacy but also pave the way for wider distribution and adoption across global markets.

Regional Analysis

Regionally, North America holds a dominant share in the cold disposable biopsy forceps market, largely due to advanced healthcare infrastructure, high awareness levels, and early adoption of new medical technologies. The United States, in particular, is a significant contributor, supported by a strong network of hospitals and diagnostic centers.

Europe follows closely, with countries like Germany, the UK, and France showing robust demand for disposable biopsy tools. The focus on hygiene standards and infection control has led to widespread adoption in European healthcare facilities.

The Asia-Pacific region is emerging as a high-growth area, driven by population growth, increasing healthcare expenditure, and government initiatives to improve diagnostic capabilities. Countries like China, India, and South Korea are witnessing a rise in endoscopic procedures, which directly supports the growth of the cold disposable biopsy forceps market.

Latin America and the Middle East & Africa regions, although still developing, are gradually embracing modern diagnostic tools. Efforts to modernize healthcare services in these areas are expected to provide significant growth opportunities in the coming years.

Competitive Outlook

The competitive landscape of the cold disposable biopsy forceps market is characterized by the presence of several established players, along with a number of emerging companies aiming to capture market share through innovation and cost efficiency. Leading companies are investing heavily in product development, clinical trials, and marketing to differentiate themselves in a competitive environment.

Market players are also engaging in strategic partnerships, mergers, and acquisitions to enhance their geographic reach and technological capabilities. Companies are increasingly focusing on tailoring their offerings to meet the specific needs of different regions, taking into account local regulations, pricing sensitivities, and procedural preferences.

Customer support, training programs for clinicians, and after-sales services are additional areas where companies are competing to gain loyalty and trust among healthcare providers.

Top Companies

Several companies have established a strong foothold in the cold disposable biopsy forceps market. These include major medical device manufacturers known for their innovation, quality, and global distribution networks. Companies such as Boston Scientific, Olympus Corporation, and Cook Medical are among the top-tier players, offering a wide range of biopsy forceps with various specifications to cater to diverse clinical requirements.

Other notable players include CONMED Corporation, Medtronic, and Pentax Medical, each bringing unique product features and strengths to the market. Smaller firms and regional manufacturers are also making significant contributions, particularly by offering competitively priced alternatives and niche solutions.

As the market continues to evolve, the role of these companies will be crucial in shaping the trajectory of innovation, accessibility, and sustainability in the cold disposable biopsy forceps segment.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/cold-disposable-biopsy-forceps-market

Segmentation Outlook

The cold disposable biopsy forceps market can be segmented based on product type, application, end-user, and region. By product type, the market includes oval, alligator jaw, and other tip designs that cater to specific procedural needs. Each type offers different advantages in terms of grip, precision, and tissue retrieval.

In terms of application, the market spans gastroenterology, pulmonology, urology, and other endoscopic fields. Gastrointestinal applications dominate the segment, owing to the high volume of colonoscopy and endoscopy procedures performed worldwide.

End-users primarily include hospitals, ambulatory surgical centers, and specialty clinics. Hospitals remain the largest end-user group due to their capacity to handle a wide range of diagnostic and therapeutic procedures under one roof.

Regional segmentation, as previously discussed, highlights the differing levels of adoption and growth potential across various parts of the globe. Understanding these segments is critical for manufacturers aiming to design products that align with local market needs and healthcare dynamics.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
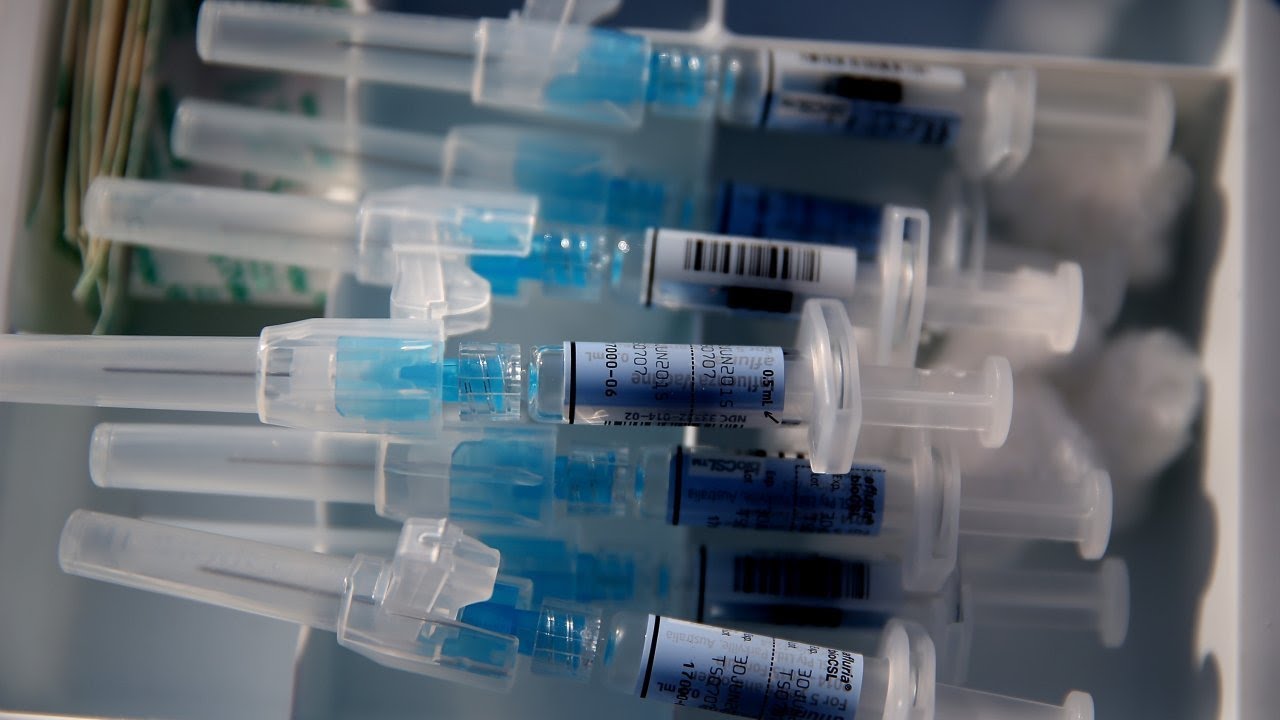
 

Small-Molecule Injectable Market to Reach USD 301M by 2035 at 7.1% CAGR

The safety and efficacy profiles of these classes of therapeutics are continuously being enhanced by the development of novel drug formulations, or innovative drug delivery technologies, etc. In addition, the growing focus on targeted therapies and personalized medicine is increasing the application range of small-molecule injectables, driving the market growth. The market is projected to grow at a compound annual growth rate of 7.1% from USD 151,630 Million in 2025 to reach USD 301,078.6 Million in 2035.

The small-molecule injectable market is gaining significant momentum as healthcare systems worldwide continue to evolve and prioritize targeted, fast-acting therapies. Small-molecule injectables are critical in treating a range of diseases, including cancer, infections, and cardiovascular conditions. These injectables are typically administered directly into the bloodstream, allowing for rapid onset of action, enhanced bioavailability, and more precise drug delivery compared to oral medications.

Unlike large-molecule biologics, small-molecule injectables are chemically synthesized and easier to manufacture in a cost-effective manner. This makes them a popular choice in various clinical settings, particularly in emergency and acute care. Pharmaceutical companies are leveraging advanced drug delivery systems and reformulation technologies to develop more efficient and patient-friendly injectable drugs. As a result, the small-molecule injectable market is witnessing substantial expansion in both developed and emerging regions.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14117

Market Trends

A growing inclination toward targeted therapy is one of the dominant trends influencing the small-molecule injectable market. With an increasing number of personalized treatment regimens being introduced, small-molecule injectables are playing a key role due to their ability to interact with specific molecular targets. This trend is particularly prominent in oncology, where injectable chemotherapy and immunomodulatory drugs have become standard components of treatment protocols.

Another important trend is the development of long-acting injectable formulations that reduce the frequency of administration. This enhances patient compliance and quality of life, especially in chronic conditions such as schizophrenia or HIV. Furthermore, there is a rise in the outsourcing of manufacturing processes to contract development and manufacturing organizations (CDMOs), allowing pharmaceutical companies to reduce costs and accelerate time-to-market.

Additionally, innovations in packaging and storage, such as prefilled syringes and auto-injectors, are contributing to the growth of the small-molecule injectable market. These user-friendly formats cater to both clinical and at-home administration, expanding the application range of injectable therapies and offering more convenience to patients and healthcare providers alike.

Challenges and Opportunities

Despite its promising outlook, the small-molecule injectable market faces several challenges. Regulatory hurdles and stringent quality control standards can delay product approvals and increase development costs. Maintaining sterility and ensuring the stability of injectable formulations over time requires specialized manufacturing environments, which can be capital-intensive for new entrants.

Moreover, the risk of adverse reactions due to incorrect administration or formulation errors can pose significant safety concerns. Patient apprehension toward needles and injections can also impact the widespread adoption of injectable treatments, especially when alternatives such as oral or transdermal formulations are available.

However, the market also offers multiple opportunities for growth. The rising prevalence of chronic and infectious diseases globally creates a sustained demand for effective injectable therapies. Advances in nanotechnology and microneedle-based delivery systems could transform the landscape by offering pain-free, minimally invasive administration methods. In emerging economies, the increasing investment in healthcare infrastructure and growing awareness among patients are further boosting demand for injectable treatments.

Additionally, biosimilar development and patent expirations of branded small-molecule drugs are opening avenues for generic injectable manufacturers to gain market share. This competition drives innovation and leads to more cost-effective treatment options for patients across various regions.

Key Regional Insights

Geographically, the small-molecule injectable market shows a diverse growth pattern, with North America leading due to its advanced healthcare infrastructure, strong pharmaceutical industry, and extensive R&D investments. The presence of major market players and favorable reimbursement policies further support market expansion in the region.

Europe follows closely, with countries like Germany, France, and the UK adopting cutting-edge injectable treatments for chronic diseases. Regulatory harmonization across the EU region facilitates faster market access and commercialization of new injectable drugs.

Asia-Pacific represents one of the fastest-growing regions in the small-molecule injectable market, driven by a large patient population, increasing healthcare spending, and growing pharmaceutical manufacturing capabilities. Countries such as China, India, and Japan are making significant contributions to the market through both domestic consumption and global exports.

In Latin America and the Middle East & Africa, the market is gradually gaining traction as governments focus on strengthening healthcare infrastructure and addressing unmet medical needs. The rise in medical tourism and improved access to advanced treatments are also supporting market growth in these regions.

Competitive Outlook

The small-molecule injectable market is highly competitive, with numerous companies vying for market share through product innovation, strategic collaborations, and mergers and acquisitions. Established pharmaceutical giants are investing heavily in R&D to develop new formulations and extend their product portfolios. At the same time, generic drug manufacturers are making strides by launching cost-effective versions of off-patent injectable drugs.

Innovation remains a key competitive strategy. Companies are exploring novel delivery systems, such as liposomal formulations and depot injections, to enhance therapeutic efficacy and patient compliance. Collaborations with research institutes and academic organizations further help in discovering new small-molecule compounds that can be developed into injectable drugs.

Another key aspect of the competitive landscape is regulatory compliance. Companies with a strong track record of meeting regulatory standards and maintaining high-quality manufacturing practices are better positioned to capitalize on market opportunities. Furthermore, the ability to scale manufacturing processes quickly and efficiently gives companies a distinct advantage in meeting the growing global demand for injectable therapies.

Top Companies

Several leading players dominate the small-molecule injectable market, offering a diverse range of products across therapeutic categories. These companies benefit from strong distribution networks, robust R&D pipelines, and strategic alliances that enable them to expand their global presence.

Major global pharmaceutical firms are known for their extensive product lines and commitment to innovation in injectable drug development. Their focus on oncology, anti-infectives, and cardiovascular treatments underscores the market’s clinical importance. In addition to large multinationals, several mid-sized and specialty pharmaceutical companies have carved out niches in the market by focusing on specific therapeutic areas or advanced drug delivery technologies.

Partnerships between biotechnology companies and traditional pharmaceutical manufacturers also play a crucial role in driving product development. By combining expertise in molecule discovery and large-scale production, these collaborations accelerate the path from laboratory to commercial product, enhancing the availability of cutting-edge injectable treatments.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/small-molecule-injectable-market

Segmentation Outlook

The small-molecule injectable market can be segmented based on various factors, including therapeutic area, route of administration, and end-user. Each segment reveals unique dynamics that contribute to the overall market structure and growth potential.

Therapeutic segmentation highlights the dominant role of oncology, infectious diseases, and cardiovascular disorders, which collectively account for a substantial share of injectable drug demand. These conditions often require rapid and effective treatment, making injectable formulations an essential component of the therapeutic arsenal.

In terms of administration route, intravenous (IV) injections remain the most widely used due to their rapid onset and high bioavailability. However, intramuscular and subcutaneous routes are gaining popularity, especially for long-acting and self-administered formulations. The adoption of advanced delivery systems tailored for these administration methods is enhancing treatment efficiency and user convenience.

From an end-user perspective, hospitals and specialty clinics represent the largest segment, given their critical role in administering complex therapies. However, there is a rising trend toward at-home care and self-injection, driven by innovations in prefilled syringes and wearable injectors. This shift not only reduces the burden on healthcare facilities but also empowers patients to manage their own treatment regimens effectively.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Manometry System Market Set to Grow at 5.2% CAGR, Reaching USD 339.68M by 2035

The manometry system market is gaining traction across the global healthcare landscape, driven by increasing awareness of gastrointestinal and esophageal disorders. Manometry systems are medical devices used to evaluate pressure and motor function within the gastrointestinal tract. These devices play a pivotal role in diagnosing conditions such as achalasia, esophageal spasms, and chronic constipation. As healthcare infrastructure expands and diagnostic capabilities improve, the demand for advanced diagnostic tools like manometry systems is steadily increasing.

Hospitals, specialty clinics, and diagnostic centers are integrating manometry systems into their routine practice to offer more accurate and less invasive diagnostics. Technological innovations in manometry systems, including high-resolution manometry and portable systems, are improving the diagnostic experience for both clinicians and patients. These systems are not only more precise but also provide faster results, enabling quicker treatment decisions.

In 2025, the manometry system market was valued at approximately USD 204.60 million. By 2035, it is projected to reach USD 339.68 million, expanding at a compound annual growth rate (CAGR) of 5.2%. Growth is attributed to technological advancements, increasing adoption of wireless and portable manometry systems, and rising investments in gastrointestinal health research.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14110

Size & Trends

The manometry system market has experienced steady growth over the past few years. Increasing cases of gastrointestinal and motility disorders, driven by dietary habits, aging populations, and stress-related health concerns, are major contributors to this upward trend. A growing preference for minimally invasive diagnostic procedures is also accelerating the market’s expansion.

In addition, high-resolution manometry (HRM) is becoming the gold standard in esophageal motility testing. This trend is likely to continue as clinicians and researchers favor data-rich systems for better insights into motility disorders. Integration with artificial intelligence and cloud-based data analysis platforms is another evolving trend that will shape the future of the manometry system market.

Key Highlights

One of the key highlights in the manometry system market is the growing shift from conventional to high-resolution manometry. These systems allow for better spatial and temporal resolution, resulting in more accurate and reproducible diagnostic results. Another major development is the miniaturization of devices, which enhances portability and accessibility, especially in remote or resource-limited settings.

Moreover, increasing collaborations between healthcare providers and device manufacturers are fostering innovation in system design and usability. Research institutions are also contributing by validating newer technologies, ensuring they meet clinical standards. Additionally, awareness programs initiated by healthcare organizations and governmental bodies are contributing to the early diagnosis and treatment of gastrointestinal disorders, thereby boosting market growth.

Challenges and Opportunities

Despite its growth, the manometry system market faces certain challenges. High costs associated with advanced manometry systems can be a barrier for smaller healthcare facilities and clinics. Additionally, the lack of trained professionals capable of interpreting manometry data correctly can limit the utility of these systems in certain regions.

However, these challenges also open doors to significant opportunities. There is a growing demand for cost-effective systems tailored for emerging markets. Companies investing in affordable and easy-to-use devices are likely to gain a competitive edge. Moreover, online training programs and certifications are addressing the skills gap, helping clinicians become more proficient in using these diagnostic tools.

Technological advancements such as wireless data transmission and AI-powered diagnostics offer untapped potential for growth. As telemedicine gains traction, manometry systems integrated with digital platforms can facilitate remote diagnosis and patient monitoring, further enhancing market reach.

Key Benefits for Stakeholders

The manometry system market offers substantial benefits for a wide range of stakeholders. For healthcare providers, these systems enable precise diagnosis of complex gastrointestinal disorders, resulting in better patient outcomes. Accurate and early diagnosis helps reduce the need for invasive surgical procedures, leading to lower healthcare costs and improved patient satisfaction.

For patients, manometry systems offer a safer, quicker, and less invasive method for identifying motility issues. The enhanced comfort and reduced recovery time associated with these tests contribute to a more positive healthcare experience. Policymakers and public health agencies also benefit from the increased diagnostic capabilities, allowing for better disease surveillance and resource allocation.

Manufacturers and investors find lucrative opportunities within the market, especially as demand for innovative and user-friendly devices continues to grow. As the global burden of digestive health issues rises, the value proposition of manometry systems becomes even stronger.

Market Share by Geographical Region

Geographically, the manometry system market displays varying levels of adoption and growth. North America holds a significant share, driven by a strong healthcare infrastructure, high prevalence of gastrointestinal disorders, and advanced diagnostic capabilities. The presence of leading manufacturers in the region further fuels market expansion.

Europe follows closely, with countries such as Germany, the UK, and France investing in state-of-the-art diagnostic tools. Government support for healthcare research and development also contributes to the region’s market strength.

Asia-Pacific is emerging as a key growth region. Rapid urbanization, improving healthcare infrastructure, and increasing awareness of gastrointestinal health are key factors driving market adoption. Countries like China, India, and Japan are witnessing a surge in demand for advanced diagnostic technologies, making the region highly attractive for market players.

Other regions, including Latin America and the Middle East & Africa, are gradually adopting manometry systems. While the growth rate may currently be slower, the increasing focus on healthcare modernization and disease awareness is expected to accelerate market penetration in these regions.

Competitive Outlook

The competitive landscape of the manometry system market is shaped by innovation, partnerships, and strategic acquisitions. Leading players are focusing on developing systems that offer superior diagnostic accuracy while being user-friendly and cost-effective. High-resolution capabilities, integrated software solutions, and ergonomic designs are major differentiators in the competitive space.

Companies are also investing in regional expansion and localization strategies to tap into emerging markets. Collaborations with hospitals, diagnostic labs, and academic institutions help strengthen product credibility and market presence. After-sales services, including training and support, are becoming key differentiators, especially in regions with less technical expertise.

Intellectual property rights and regulatory approvals also play a critical role in determining competitive positioning. Companies that can efficiently navigate the regulatory landscape and bring compliant, high-quality products to market are more likely to sustain long-term success.

Top Companies

Several prominent players dominate the manometry system market. These companies are known for their strong R&D capabilities, global distribution networks, and customer-centric approach. They offer a wide portfolio of diagnostic solutions, often complemented by training and support services.

Many top companies are also diversifying their offerings to include manometry systems as part of broader diagnostic platforms. This integrated approach helps clinicians manage a variety of gastrointestinal conditions using a single system. Continuous investment in product development, clinical trials, and partnerships enables these companies to stay ahead of the competition.

Startups and mid-sized enterprises are also contributing to market dynamism by introducing innovative and affordable solutions. Their agility in responding to emerging needs makes them important stakeholders in the manometry system market ecosystem.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/manometry-system-market

Segmentation Outlook

The manometry system market can be segmented based on product type, application, end-user, and geography. By product type, the market includes conventional and high-resolution manometry systems. High-resolution systems are witnessing rapid adoption due to their superior diagnostic capabilities.

In terms of application, the market is categorized into esophageal, anorectal, and antroduodenal manometry. Esophageal manometry accounts for a significant share, given the rising incidence of swallowing disorders and acid reflux issues.

The end-user segment includes hospitals, diagnostic centers, and specialty clinics. Hospitals dominate the segment, but diagnostic centers are rapidly expanding their role due to increasing decentralization of diagnostic services.

Geographically, the segmentation aligns with regional healthcare development and disease prevalence. Developed regions exhibit high adoption of advanced systems, while developing regions present opportunities for cost-effective and scalable solutions.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Nasal Antihistamines Market Projected to Reach USD 3.34 Billion by 2035

The nasal antihistamines market is gaining significant momentum due to the increasing prevalence of allergic rhinitis and related nasal allergies across the globe. Nasal antihistamines are specialized medications designed to relieve symptoms such as nasal congestion, sneezing, and runny nose by blocking the effects of histamines, which are chemicals released by the immune system during an allergic reaction. Unlike oral antihistamines, nasal sprays act locally in the nasal passages, offering faster and more targeted relief with fewer systemic side effects. As consumer awareness of allergic conditions continues to grow, the demand for effective and fast-acting treatments like nasal antihistamines is rising steadily.

The market is expected to expand from USD 2253.8 Million in 2025 to USD 3336.2 Million by 2035 growing at a CAGR of 4.0% in the forecast period. Factors such as the growing incidence of perennial and seasonal allergies, urban pollution, and allergens associated with climate change are expected to boost the demand. Market growth is further augmented by several advancements in formulation technologies, combination therapies, and newer drug delivery mechanisms.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-13708

Market Trends

A notable trend shaping the nasal antihistamines market is the shift toward over-the-counter (OTC) availability. Increasingly, pharmaceutical companies are seeking regulatory approval to market nasal antihistamines as OTC products, enabling broader consumer access without the need for prescriptions. This shift aligns with a growing consumer preference for self-medication and convenience in managing mild to moderate allergic conditions.

In addition, advancements in formulation technologies are contributing to the market’s expansion. Manufacturers are focusing on developing nasal sprays with longer durations of action, minimal dosing frequency, and improved delivery mechanisms that enhance patient compliance. Another trend includes the integration of combination therapies, where nasal antihistamines are blended with corticosteroids to offer comprehensive symptom control.

Driving Forces Behind Market Growth

Several key factors are propelling the growth of the nasal antihistamines market. One of the primary drivers is the rising incidence of respiratory allergies due to increasing air pollution, pollen exposure, and changing climate conditions. Urban environments with poor air quality have seen a surge in allergic rhinitis cases, thereby increasing the reliance on nasal antihistamines for symptom relief.

Moreover, growing health consciousness and access to medical information through digital platforms have led to a more informed consumer base. Patients are now more likely to recognize symptoms early and seek appropriate treatment options, including nasal antihistamines. Additionally, the expanding geriatric population, which is more prone to respiratory ailments, is contributing to the increased demand for effective allergy treatments.

Another contributing factor is the strengthening of healthcare infrastructure in emerging economies. With better access to pharmacies, increased affordability of medications, and public health initiatives focused on allergy awareness, these regions are experiencing accelerated adoption of nasal antihistamines.

Challenges and Opportunities

Despite promising growth, the nasal antihistamines market faces several challenges. One major hurdle is the risk of side effects such as nasal dryness, irritation, and occasional drowsiness, which can discourage regular use among some patient groups. Furthermore, the market is subject to strict regulatory requirements, particularly when transitioning a product from prescription-only to OTC status.

Market competition also poses a challenge, especially with the presence of numerous generic alternatives that can undercut pricing strategies of branded medications. However, this competitive environment also presents opportunities for innovation. Companies can differentiate their products through novel formulations, user-friendly applicators, or by targeting niche segments such as pediatric or geriatric populations.

Another area of opportunity lies in telehealth and e-pharmacy platforms. As digital healthcare becomes mainstream, pharmaceutical companies can leverage these channels to reach a wider audience and provide direct-to-consumer access to nasal antihistamines. Partnerships with e-commerce giants and healthcare providers can also boost product visibility and sales.

Recent Industry Developments

In recent years, the nasal antihistamines market has witnessed several notable developments. Pharmaceutical companies are increasingly investing in research and development to introduce advanced formulations with fewer side effects and enhanced therapeutic benefits. There has been a marked rise in clinical trials focused on evaluating the efficacy of newer molecules that act faster and last longer.

Some firms have launched combination nasal sprays that pair antihistamines with decongestants or corticosteroids, offering a dual-action approach to treating allergic rhinitis. Additionally, strategic collaborations and acquisitions are shaping the competitive landscape. Larger firms are acquiring smaller biotech companies to integrate innovative technologies and expand their product portfolios.

Regulatory milestones have also played a significant role. The FDA’s approval of OTC nasal antihistamines has opened new avenues for market expansion in the United States, encouraging other regions to follow suit. This regulatory flexibility is promoting increased availability and consumer adoption of these products.

Regional Analysis

Geographically, the nasal antihistamines market shows varied growth patterns. North America holds a substantial share due to its well-established healthcare system, high prevalence of seasonal allergies, and strong presence of key market players. The United States, in particular, benefits from widespread OTC drug availability and consumer awareness.

Europe follows closely, with countries such as Germany, France, and the UK witnessing consistent demand driven by an aging population and rising pollution levels. Government initiatives promoting allergy management also contribute to the region’s market stability.

In the Asia-Pacific region, the nasal antihistamines market is expanding rapidly. Factors such as increasing urbanization, growing disposable income, and improving healthcare infrastructure are fueling demand. Countries like China, India, and Japan are seeing a surge in allergic conditions, prompting higher usage of nasal sprays for immediate relief.

Latin America and the Middle East & Africa represent emerging markets with untapped potential. While healthcare access and awareness are still developing in these regions, the growing burden of respiratory ailments suggests a promising future for nasal antihistamines.

Competitive Outlook

The nasal antihistamines market is highly competitive, with both multinational pharmaceutical companies and local players vying for market share. Innovation, pricing, and distribution strategies are critical components of competitive advantage in this sector. Companies that invest in novel drug delivery systems and differentiated formulations often stand out in an otherwise saturated market.

Moreover, strong marketing and branding strategies play a pivotal role in influencing consumer preference, especially in OTC segments. Firms are focusing on direct-to-consumer advertising and digital marketing to boost product visibility and consumer engagement. In markets where prescription drugs still dominate, building strong relationships with healthcare professionals remains essential.

Mergers, acquisitions, and strategic alliances are commonly employed tactics to broaden product lines and enhance geographic reach. As companies aim to scale their operations globally, these collaborations help in navigating regulatory landscapes and tapping into regional expertise.

Top Companies

Several major players dominate the nasal antihistamines market through extensive research, broad product offerings, and global distribution networks. Companies such as GlaxoSmithKline, Johnson & Johnson, Bayer AG, Novartis, and Sanofi are recognized for their longstanding presence and robust product portfolios. These organizations continuously invest in R&D to enhance product efficacy and reduce adverse effects.

Emerging biotech firms and generic drug manufacturers also play an important role by offering cost-effective alternatives and niche solutions. Companies like Cipla, Teva Pharmaceuticals, and Dr. Reddy’s Laboratories are making significant inroads in emerging markets by offering competitively priced nasal antihistamines.

These top companies are also leveraging digital tools for consumer outreach, post-launch product support, and pharmacovigilance. Their ability to scale operations while maintaining quality and regulatory compliance contributes to their continued dominance in the market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/nasal-antihistamines-market

Segmentation Outlook

The nasal antihistamines market can be segmented based on drug type, distribution channel, end-user, and geography. In terms of drug type, azelastine and olopatadine are among the most widely used active ingredients. These drugs offer rapid relief and are commonly prescribed for both seasonal and perennial allergic rhinitis.

Distribution channels include hospital pharmacies, retail pharmacies, and online platforms. The rise of e-commerce and digital pharmacies has significantly influenced the retail landscape, especially in urban centers. Among end-users, adults constitute the largest segment, although there is a growing demand for pediatric formulations tailored for children.

Geographically, segmentation reveals different consumer behaviors, regulatory environments, and market readiness, which companies must consider when formulating regional strategies. Understanding these distinctions helps businesses tailor marketing, distribution, and product development initiatives accordingly.

As the nasal antihistamines market continues to evolve, innovation, accessibility, and patient-centered care will remain critical to sustained growth. Companies that anticipate and respond to changing consumer needs, regulatory shifts, and technological advancements are best positioned to succeed in this dynamic landscape.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Headspace Gas Analyzers Market Grows at 4.3% CAGR to Reach USD 1.12 Billion by 2035

The global Headspace Gas Analyzers Market is estimated to be valued at USD 655.7 million in 2025 and is projected to reach USD 1,120.1 million by 2035, registering a compound annual growth rate (CAGR) of 4.3% over the forecast period. Rising regulatory demands across pharmaceuticals, food and beverage manufacturing as well as packaging sectors are driving stringent quality and safety requirements, leading to increased deployment of headspace analyzers.

The headspace gas analyzers market has gained considerable attention in recent years due to the growing demand for accurate and efficient packaging quality control across various industries. These analyzers are designed to measure the composition of gases in the headspace of sealed packages, ensuring that the product inside maintains its intended quality, shelf life, and safety. Commonly used in food and beverage, pharmaceuticals, and industrial packaging, headspace gas analyzers play a vital role in maintaining packaging standards and compliance with regulations.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-13979

In the pharmaceutical industry, for instance, headspace gas analyzers are essential in monitoring oxygen and carbon dioxide levels in vial headspaces. This helps in preserving drug efficacy by preventing oxidation. Similarly, the food industry uses these analyzers to assess modified atmosphere packaging (MAP) conditions to maintain freshness. As consumer safety and regulatory compliance become more stringent, the importance of headspace gas analyzers is further amplified. These devices offer non-destructive testing, speed, and accuracy, making them indispensable for quality control labs and production lines.

Market Trends

Several market trends are shaping the growth trajectory of the headspace gas analyzers market. One prominent trend is the shift toward automation and digitalization of quality control processes. Manufacturers are investing in smart headspace gas analyzers equipped with wireless connectivity, real-time data logging, and cloud integration to enhance traceability and process efficiency. These advanced features provide insights into packaging performance and allow timely interventions in case of deviations from the desired gas composition.

Another significant trend is the increased use of portable and handheld devices. As quality assurance moves closer to the point of packaging, there is a growing need for compact and mobile analyzers. These devices are designed to offer fast analysis without compromising accuracy, catering especially to small and medium enterprises that require cost-effective quality control solutions.

Sustainability initiatives are also influencing the market. As industries adopt eco-friendly packaging materials, headspace gas analyzers are being used to test how these new materials affect gas permeability and product preservation. This trend is pushing manufacturers to innovate and develop analyzers that can adapt to evolving packaging technologies.

Challenges and Opportunities

Despite the promising outlook, the headspace gas analyzers market faces several challenges. One major hurdle is the high initial cost of advanced analyzers, which may deter adoption among small-scale manufacturers. Additionally, the requirement for skilled operators to manage and interpret data from these devices can limit their deployment, particularly in developing regions where technical expertise is scarce.

Another challenge is the presence of alternative methods for gas analysis, such as chemical testing kits. While these alternatives may lack the precision of headspace gas analyzers, their lower cost can be attractive for budget-conscious users.

However, these challenges also present opportunities for innovation and market expansion. The growing awareness of food safety and regulatory compliance in emerging economies is driving demand for reliable quality control tools. Manufacturers can capitalize on this trend by offering cost-effective, easy-to-use models tailored to the needs of small and mid-sized enterprises.

The integration of artificial intelligence and machine learning in gas analysis represents another opportunity. AI can enhance the accuracy and predictive capabilities of headspace gas analyzers, reducing the margin of error and enabling automated quality control workflows. These advancements could revolutionize packaging inspection and open new avenues for market growth.

Key Regional Insights

The headspace gas analyzers market exhibits varied dynamics across different regions. North America holds a significant share, driven by stringent food and pharmaceutical packaging regulations. The presence of major industry players and a well-established quality control infrastructure further boosts the market in this region.

In Europe, the emphasis on sustainable packaging and environmental regulations has led to widespread adoption of headspace gas analyzers. Countries like Germany, the UK, and France are at the forefront of implementing advanced packaging technologies, thereby driving demand for sophisticated gas analysis tools.

The Asia-Pacific region is emerging as a lucrative market for headspace gas analyzers, fueled by rapid industrialization and the growth of the pharmaceutical and food sectors. Countries such as China and India are experiencing increased investments in manufacturing and packaging facilities, resulting in a greater need for reliable and efficient gas analyzers.

Latin America and the Middle East & Africa regions are witnessing gradual growth, with expanding awareness of packaging standards and improving economic conditions. While the market in these regions is still developing, they offer significant potential for expansion as demand for packaged products continues to rise.

Competitive Outlook

The headspace gas analyzers market is highly competitive, with numerous players striving to offer innovative and cost-effective solutions. The competitive landscape is characterized by frequent product launches, strategic partnerships, and technological advancements. Companies are focusing on enhancing the speed, accuracy, and user-friendliness of their devices to gain a competitive edge.

Research and development activities are central to maintaining market leadership. Many players are investing heavily in R&D to introduce AI-powered and IoT-enabled analyzers that can seamlessly integrate with modern production environments. Additionally, firms are expanding their global footprint through mergers, acquisitions, and collaborations with local distributors to tap into emerging markets.

Pricing strategies also play a crucial role in shaping competition. While premium models offer advanced features and automation, there is a growing demand for budget-friendly options that deliver basic functionality without compromising accuracy. Companies that can strike the right balance between performance and affordability are well-positioned to succeed in this dynamic market.

Top Companies

Several prominent companies are contributing to the development and expansion of the headspace gas analyzers market. These companies are known for their technological innovation, global reach, and strong customer service networks.

Some of the leading names in the industry include manufacturers specializing in analytical instrumentation and process control systems. Their product portfolios feature a wide range of gas analyzers catering to different industry needs, from laboratory testing to high-speed production environments.

These top companies often lead the way in developing cutting-edge technologies such as non-invasive sensors, real-time monitoring systems, and cloud-based analytics platforms. Their commitment to quality, innovation, and compliance with international standards has earned them a strong reputation among customers across the globe.

In addition to established players, a number of emerging firms are entering the market with niche products and services. These startups are leveraging new technologies and agile development approaches to offer tailored solutions that meet specific customer requirements.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/headspace-gas-analyzers-market

Segmentation Outlook

The headspace gas analyzers market can be segmented based on technology, end-user, and application. In terms of technology, the market includes oxygen analyzers, carbon dioxide analyzers, and combined gas analyzers. Each type serves specific functions depending on the nature of the product being packaged and the requirements for shelf life and safety.

By end-user, the market is broadly divided into food and beverage, pharmaceuticals, and industrial packaging. The food and beverage segment represents the largest share, driven by the growing demand for MAP and the increasing importance of preserving freshness and quality. The pharmaceutical segment is also expanding rapidly, supported by the need for sterile packaging and strict regulatory mandates.

When segmented by application, the market includes quality control laboratories, research institutions, and production lines. Quality control labs are the primary users, employing headspace gas analyzers for batch testing and validation. Production lines also represent a growing segment, as in-line gas analyzers become more common for real-time monitoring and process optimization.

This segmentation outlook underscores the versatility of headspace gas analyzers and their wide-ranging applications across various sectors. As the market continues to evolve, manufacturers are expected to develop more specialized devices tailored to specific industry needs and operational environments.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Active Humidifier Devices Market Demand & Forecast 2025 to 2035

The active humidifier devices market has emerged as a critical component in various industries, especially in healthcare settings. These devices are designed to maintain optimal humidity levels in controlled environments, playing an essential role in patient care and well-being. Active humidifiers are particularly useful in mechanical ventilation systems, where proper humidification of the airways is vital to prevent respiratory complications. Beyond healthcare, they are also used in industrial applications and even consumer electronics, ensuring that delicate systems are not compromised by overly dry air.

The demand for active humidifier devices has witnessed steady growth over the years due to rising awareness of air quality and respiratory health. With urban environments becoming more polluted and climate-controlled settings more prevalent, there is an increasing need to regulate air humidity effectively. This demand is being fueled by growing investments in medical infrastructure and advancements in humidification technologies.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-13929

Size & Trends

The active humidifier devices market has been expanding consistently, supported by both innovation and necessity. One of the most influential trends driving the market is the integration of smart technology into humidification systems. Many modern devices now come equipped with IoT features, enabling real-time monitoring, remote control, and predictive maintenance. These technological improvements not only enhance efficiency but also cater to the needs of modern medical and industrial applications.

In terms of size, the market is experiencing growth across several sectors, including neonatal and adult intensive care units. The increasing number of hospital admissions requiring respiratory support has prompted a higher uptake of advanced humidification systems. Moreover, trends such as home-based healthcare and portable humidifiers are opening new avenues for expansion. The transition from passive to active humidification in clinical practices is another notable trend reshaping the market landscape.

Key Highlights

One of the key highlights of the active humidifier devices market is its expanding role in critical care environments. Hospitals and clinics are now more reliant on sophisticated humidification systems to ensure patient safety during ventilation therapy. Active humidifiers help in maintaining airway moisture, reducing the risk of complications like mucosal drying and infections.

The market has also been impacted by recent global health crises, such as the COVID-19 pandemic, which underlined the importance of advanced respiratory care equipment. This scenario significantly accelerated the adoption of active humidifier devices in intensive care units around the world. Additionally, the growing geriatric population and increasing prevalence of chronic respiratory conditions have further underscored the necessity of these devices in medical settings.

Technological innovation is another highlight, with companies investing in research and development to introduce compact, user-friendly, and energy-efficient models. These advancements not only enhance the clinical performance of the devices but also make them more accessible in varied settings, including homes and remote healthcare centers.

Challenges and Opportunities

Despite its promising growth, the active humidifier devices market faces several challenges. One of the main obstacles is the high cost associated with advanced humidification systems, which can be a barrier to adoption in developing economies. Budget constraints in healthcare facilities, especially in rural areas, limit the penetration of these devices.

Another significant challenge is the need for regular maintenance and the risk of device contamination. Active humidifiers, if not properly managed, can become breeding grounds for harmful microorganisms. Ensuring proper sterilization and hygiene is essential but adds to the operational complexity and cost.

On the flip side, the market also presents considerable opportunities. The rising focus on home healthcare is a major growth driver. With more patients opting for treatment in the comfort of their homes, the demand for compact and portable active humidifiers is on the rise. Additionally, ongoing advancements in automation and connectivity present opportunities for smarter and more efficient humidification systems.

Emerging markets also offer potential, where increasing investment in healthcare infrastructure and government support can pave the way for broader adoption. Education and awareness campaigns around the importance of respiratory health can further enhance market reach in underserved regions.

Key Benefits for Stakeholders

The active humidifier devices market offers numerous benefits for stakeholders, from healthcare providers to manufacturers and end-users. For hospitals and medical professionals, these devices ensure optimal respiratory support, leading to better patient outcomes and reduced complications. The use of advanced humidifiers can shorten recovery times and improve the overall efficiency of intensive care units.

Manufacturers benefit from a growing market driven by continuous demand and the need for innovation. Companies that invest in research and customization are better positioned to capitalize on emerging trends and user needs. The push toward eco-friendly and energy-efficient models also opens up new business opportunities.

For patients, especially those requiring long-term respiratory care, active humidifiers improve comfort and quality of life. The availability of home-based solutions enables greater independence and reduces hospital visits, leading to cost savings and better health outcomes.

Market Share by Geographical Region

The active humidifier devices market exhibits diverse growth patterns across different regions. North America remains a dominant player, owing to its advanced healthcare infrastructure, higher healthcare spending, and rapid adoption of cutting-edge technologies. The United States, in particular, has a robust demand for active humidifiers in both hospital and home care settings.

Europe is another key region, with countries like Germany, the UK, and France leading the market due to stringent healthcare regulations and increased awareness of respiratory health. The European market also benefits from strong governmental initiatives aimed at modernizing medical infrastructure.

Asia-Pacific represents a rapidly growing segment of the active humidifier devices market. Countries such as China, India, and Japan are experiencing increased healthcare investments and growing demand for advanced medical equipment. The expanding middle class and increasing prevalence of respiratory diseases in this region contribute significantly to market growth.

Latin America, the Middle East, and Africa are also witnessing gradual growth. Though these regions face challenges related to limited healthcare resources and lower adoption rates, ongoing improvements in medical infrastructure and international partnerships are paving the way for future expansion.

Competitive Outlook

The competitive landscape of the active humidifier devices market is characterized by the presence of both established players and emerging companies. Intense competition has driven continuous innovation, with companies striving to differentiate their products through features like automation, portability, and energy efficiency.

Strategic collaborations, mergers, and acquisitions are common as companies look to expand their market presence and enhance their product portfolios. Partnerships with healthcare providers and institutions allow manufacturers to better understand clinical needs and tailor their offerings accordingly.

Investment in research and development remains a key focus area, enabling companies to introduce new technologies and comply with evolving regulatory standards. As competition increases, branding, after-sales service, and customer support are becoming important differentiators.

Top Companies

Several companies have established a strong foothold in the active humidifier devices market. These industry leaders are recognized for their commitment to quality, innovation, and customer satisfaction. They continuously work on improving the performance and efficiency of their products to meet the growing demands of healthcare providers and patients.

Leading firms often possess a global distribution network and collaborate with hospitals and research centers to drive innovation. Their experience and resources enable them to adapt quickly to market changes and regulatory updates. These top players also invest heavily in training and support services, ensuring that healthcare professionals can maximize the benefits of their humidification systems.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/active-humidifier-devices-market

Segmentation Outlook

The active humidifier devices market can be segmented based on various parameters, including application, end-user, and product type. In terms of application, the market serves areas such as neonatal care, adult ventilation, and surgical procedures. Each of these segments requires specific humidification solutions tailored to the needs of different patient groups.

End-users primarily include hospitals, ambulatory surgical centers, and home care settings. Hospitals remain the largest consumers due to the high volume of critical care patients requiring respiratory support. However, home care is an increasingly important segment, driven by the demand for portable and user-friendly devices.

Product segmentation typically distinguishes between heated humidifiers, bubble humidifiers, and integrated respiratory systems. Heated humidifiers are widely used in clinical environments for their ability to deliver consistent moisture at controlled temperatures. Bubble humidifiers, while simpler, are commonly used in low-resource settings due to their cost-effectiveness.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


High-flow Oxygen Therapy Devices Market to Grow Steadily, Hitting USD 1.6B by 2035

The global high flow oxygen therapy devices market is anticipated to witness moderate growth, rising from USD 1.3 billion in 2025 to USD 1.6 billion by 2035 at a CAGR of 2.1% over the forecast period. Revenue generated by these devices was approximately USD 1,369.8 million in 2024, reflecting stable demand driven by the increasing prevalence of chronic respiratory disorders, expanding geriatric populations, and growing global healthcare infrastructure.

The high-flow oxygen therapy devices market is gaining significant attention across the global healthcare landscape. These devices are widely used for delivering heated and humidified oxygen at high flow rates, particularly to patients suffering from acute or chronic respiratory failure. Hospitals, clinics, and even home care settings are increasingly incorporating these systems to improve patient outcomes and reduce the need for invasive ventilation. As respiratory illnesses become more prevalent and healthcare infrastructure continues to modernize, the demand for high-flow oxygen therapy devices is witnessing a consistent rise. This trend is anticipated to continue, positioning the market for strong growth over the coming years.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-13794

Market Trends

One of the most notable trends in the high-flow oxygen therapy devices market is the growing adoption of these systems in home healthcare settings. With advancements in device portability and user-friendly interfaces, patients are now able to receive efficient respiratory support from the comfort of their homes. This shift is largely driven by the need to reduce hospital readmissions and lower overall healthcare costs. Another emerging trend is the integration of smart features, such as remote monitoring and AI-based diagnostics, which allow healthcare providers to track patient progress in real-time and make informed decisions without physical presence. Furthermore, the development of more compact and lightweight devices has expanded the market to include pediatric and geriatric patients, boosting overall accessibility.

Driving Forces Behind Market Growth

The primary driving factor behind the growth of the high-flow oxygen therapy devices market is the increasing prevalence of respiratory diseases such as chronic obstructive pulmonary disease (COPD), asthma, and pneumonia. These conditions necessitate effective and continuous oxygen therapy, making high-flow systems a crucial component in patient care. Additionally, the recent global focus on pandemic preparedness and critical care has highlighted the importance of reliable oxygen delivery systems. Public and private investments in healthcare infrastructure, especially in emerging economies, are also contributing to the market’s expansion. Technological innovations that enhance patient comfort and improve therapeutic efficacy are further accelerating the adoption of these devices across various clinical settings.

Challenges and Opportunities

Despite its promising growth trajectory, the high-flow oxygen therapy devices market faces several challenges. High initial costs and maintenance expenses of these devices can act as a barrier, particularly in low-income regions. Additionally, the lack of trained personnel to operate and manage these systems may limit their adoption in some areas. However, these challenges also open doors for innovation and investment. Companies focusing on cost-effective manufacturing and robust training programs stand to gain a competitive edge. There is also a growing opportunity in telemedicine integration, where remote oxygen therapy management can improve accessibility and patient compliance. Collaborations between device manufacturers and healthcare providers can further enhance product offerings and expand market reach.

Recent Industry Developments

The high-flow oxygen therapy devices market has witnessed several key developments in recent times. Many manufacturers have introduced next-generation devices that offer better humidification, adjustable flow rates, and touchscreen interfaces. Some companies have partnered with software developers to integrate data analytics features, providing healthcare providers with insights into treatment efficacy and patient behavior. In response to the COVID-19 pandemic, several nations ramped up the production and distribution of high-flow oxygen therapy devices, leading to rapid innovations and expedited regulatory approvals. These developments have not only strengthened supply chains but also broadened the scope of application for these devices beyond hospital ICUs.

Regional Analysis

Regionally, North America holds a significant share in the high-flow oxygen therapy devices market, driven by a well-established healthcare infrastructure and strong demand for advanced respiratory care solutions. The United States, in particular, benefits from extensive R&D activities and favorable reimbursement policies, which facilitate the widespread adoption of these devices. Europe follows closely, with countries like Germany, the United Kingdom, and France actively investing in respiratory healthcare services. The Asia-Pacific region is emerging as a lucrative market, thanks to its large patient pool, rising healthcare expenditure, and increasing awareness of advanced medical technologies. Countries like China and India are seeing rapid urbanization and improvement in medical services, making them key contributors to future market growth. Meanwhile, Latin America and the Middle East & Africa are gradually catching up, aided by government initiatives and international healthcare collaborations.

Competitive Outlook

The high-flow oxygen therapy devices market is characterized by a mix of established players and new entrants. Competitive strategies often revolve around product innovation, mergers and acquisitions, and strategic collaborations. Leading companies focus on developing high-performance devices with enhanced user experience and improved therapeutic outcomes. There is a growing emphasis on sustainability, with manufacturers exploring eco-friendly materials and energy-efficient designs. Market players are also increasingly investing in digital marketing and global distribution networks to expand their footprint. The competitive landscape remains dynamic, with a constant push for better technology and broader market penetration.

Top Companies

Several top companies are driving innovation and shaping the future of the high-flow oxygen therapy devices market. These include names like Fisher & Paykel Healthcare, Philips Healthcare, ResMed, and Medtronic, all of which are known for their strong product portfolios and global presence. Fisher & Paykel, for example, has been a pioneer in humidification technologies and offers a range of devices suitable for both hospital and home use. Philips Healthcare continues to invest in smart respiratory care solutions, integrating connectivity features that allow real-time monitoring. Emerging players are also gaining traction by offering niche solutions or targeting underserved markets. Collectively, these companies are pushing the boundaries of what high-flow oxygen therapy devices can achieve, ensuring continued growth and innovation within the industry.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/high-flow-oxygen-therapy-devices-market

Segmentation Outlook

The high-flow oxygen therapy devices market can be segmented based on product type, application, end user, and region. By product type, the market includes standalone devices and integrated systems, each catering to different clinical requirements. Application-wise, these devices are commonly used in treating respiratory disorders, post-operative care, and critical care settings. In terms of end users, hospitals represent the largest segment, followed by home care and ambulatory surgical centers. Geographically, the segmentation aligns with regional demand and healthcare infrastructure maturity. Understanding these segments helps stakeholders tailor their strategies to meet specific market needs and capture targeted opportunities. Each segment offers unique growth prospects and challenges, further enriching the overall market landscape.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube