Global Antiepileptic Drug Market Set to Reach USD 28.72 Billion by 2034, Driven by Advancements in Neurological Therapies | FMI

The global antiepileptic drug market is on the cusp of remarkable growth, according to a recent analysis by Future Market Insight. In 2024, the market is projected to be valued at USD 18.85 billion, with an expected surge to USD 28.72 billion by 2034, reflecting a steady compound annual growth rate (CAGR) of 4.3% over the next decade.

Epilepsy, a neurological disorder that affects over 70 million people worldwide, is characterized by recurring seizures that can significantly impair a person’s quality of life. Despite the strides made in medical science, the treatment of epilepsy remains complex. Antiepileptic drug therapy serves as the frontline defense in managing the condition, with success in controlling seizures for approximately two-thirds of patients when properly diagnosed and treated.

Stay Updated with Market Movements: Get Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-3341

However, a significant hurdle remains—about 30% of people with epilepsy, according to the International League Against Epilepsy (ILAE), are considered “drug-resistant,” meaning that even well-established anti-seizure medications fail to alleviate their condition. This underscores the pressing need for both innovative pharmaceutical solutions and non-pharmacological therapies to improve patient outcomes.

The future of the AED market holds considerable promise, particularly with the development of novel medications aimed at pediatric and geriatric populations, who are often more vulnerable to the challenges posed by epilepsy. Additionally, a robust clinical pipeline, bolstered by ongoing experimental research, offers substantial opportunities for market expansion. Yet, the path to improved epilepsy care is fraught with complexities. Cognitive side effects from AEDs, combined with the intricate pharmacodynamics and pharmacokinetics of these medications, pose risks for drug-related complications, adding layers of difficulty to epilepsy treatment.

As global demand for safer and more effective epilepsy treatments intensifies, stakeholders in the pharmaceutical industry are being called upon to accelerate research and development efforts. By addressing the multifaceted nature of epilepsy management, the antiepileptic drug market is set to play a pivotal role in enhancing the quality of life for millions of patients worldwide in the coming years.

This growth narrative not only highlights the current challenges but also the vast potential for breakthroughs in epilepsy treatment, positioning the AED market as a critical component in the future of neurological care.

“Due to the complexity of their prescriptions and medical conditions, patients receiving AEDs may be more susceptible to medication toxicity and interactions, which might make it more difficult for them to adhere to their drug therapy regimen and worsen their seizure control.,” says an analyst of Future Market Insights.

Key Takeaways from the Antiepileptic Drugs Market Report:

  • The AED industry in the United Kingdom is projected to experience a CAGR of 5.9% through 2034.
  • Germany’s epilepsy medication market is estimated to demonstrate a CAGR of 4.1% by 2034.
  • The antiepileptic drug industry in the United States is anticipated to see a CAGR of 4.7% from 2024 to 2034.
  • China’s antiepileptic medication sector is projected to showcase a CAGR of 5.3% through 2034.
  • The antiepileptic drug market in India is anticipated to display a CAGR of 5.4% by 2034.

Rising Interest in Market Trends: Our Detailed Report Provides Essential Insights! https://www.futuremarketinsights.com/reports/antiepileptic-drugs-market

Competitive Landscape of the Antiepileptic Drugs Market:

The antiepileptic drugs market is composed of a diverse range of companies, including pharmaceutical manufacturers, research institutions, and healthcare providers, all effectively competing for an increase in market share. They are either working with other businesses to achieve this goal or they are obtaining authorization from the government bodies to distribute the recently developed therapies to increase their geographic coverage.

For key players in the epilepsy medication market, adherence to good manufacturing practices (GMO) is not just a regulatory requirement but a crucial commitment. This practice significantly reduces the risk of unwanted residues in the final product, ensuring the safety and efficacy of the medication.

Across the globe, pharmacies stand as the preferred and reliable venues for obtaining epilepsy drugs. Their widespread accessibility and convenience reassure patients and healthcare providers about the consistent availability of these crucial medications.

Product launches, approvals, strategic acquisitions, and innovations are just a few of the important strategies used by market participants to maintain and grow their global reach.

Recent Developments in the Antiepileptic Drugs Market

  • The Canadian government approved the sale of SK Biopharmaceuticals’ novel epilepsy medication, cenobamate, under the brand name Xcopri in July 2023. The business intends to increase sales in the nation.
  • Together, IAMA Therapeutics and PsychoGenics will investigate the effectiveness of new treatment candidates in pre-clinical animal models of Dravet syndrome. This rare pediatric epilepsy can have serious, perhaps fatal consequences, starting in January 2023.

Key Companies in the Antiepileptic Drug Market:

  • Merck KGaA
  • Eisai Co., Ltd.
  • AstraZeneca
  • Novartis AG
  • Abbott
  • Teva Pharmaceutical Industries Ltd.
  • Pfizer Inc.
  • GlaxoSmithKline plc
  • Sanofi
  • Johnson & Johnson Service, Inc.
  • Dr. Reddy’s Laboratories Ltd.

Download Our Comprehensive Healthcare Industry Report! https://www.futuremarketinsights.com/industry-analysis/therapy-area

Key Segments:

By Drug Generation:

The industry is diverged into first-generation, second-generation, and third-generation based on drug generation.

By Route of Administration:

Depending on the route of administration, the industry is bifurcated into oral and intravenous.

By Distribution Channel:

Antiepileptic medications are distributed through various distribution channels, including hospital pharmacies, retail pharmacies, online pharmacies, and drug stores.

By Region:

The industry is examined across key regions including North America, Latin America, Europe, East Asia, South Asia, Oceania, as well as Middle East and Africa.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Immunochromatography Kits Market to Reach USD 12.1 Billion by 2032 at a CAGR of 4.1% amid Rising Demand for Rapid Diagnostics | FMI

The global immunochromatography kits market is poised for significant expansion over the next decade, driven by the increasing demand for point-of-care diagnostics, rapid disease detection capabilities, and technological advancements in healthcare. According to a recent report by Future Market Insights, the market, which was valued at USD 8.1 Billion by the end of 2022, is expected to grow at a CAGR of 4.1%, reaching approximately USD 12.1 Billion by 2032.

Kits Dominate the Product Segment

In 2021, kits emerged as the leading product, capturing around 72.7% of the global market share. Immunochromatography kits are favored for their user-friendly design, affordability, and rapid results, making them indispensable tools in both clinical laboratories and remote healthcare settings. These kits are particularly effective in identifying target analytes—such as antigens or antibodies—in a sample, enabling timely and cost-effective diagnosis and treatment.

Gain Access to Market Trends: Request Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15764

A Vital Role in Disease Diagnosis

The lateral flow test, a widely adopted form of immunochromatography assay, continues to be a cornerstone of diagnostic protocols worldwide. From pregnancy testing to infectious disease screening, these assays provide quick insights into patient health, often serving as the first line of defense in medical emergencies.

Despite their utility, the technology does face limitations. False-negative or false-positive results can stem from improper sample collection, specimen degradation, or contamination. Additionally, the indirect nature of immune response detection, as opposed to molecular testing, highlights the need for continued innovation and rigorous quality control.

Regional Insights: USA, China, and Germany Lead Market Growth

United States: A Mature but Growing Market

The United States dominated the North American immunochromatography kits market with a commanding 82.8% share in 2021. This leadership position is underpinned by robust healthcare infrastructure, widespread access to advanced diagnostic technologies, and the growing burden of diseases such as HIV, TB, and cancer. The ongoing demand for effective diagnostic tools is expected to sustain market growth in the coming years.

China: A Lucrative Growth Hub

China accounted for nearly 60.1% of the East Asia market in 2021, showcasing impressive growth potential with a projected CAGR of 4.8% through 2032. The country’s rapidly aging population, rising incidence of chronic and infectious diseases, and enhancements in healthcare infrastructure are driving demand. The COVID-19 pandemic further accelerated the adoption of immunochromatography kits, particularly for SARS-CoV-2 antigen detection, solidifying China’s position as a key player in the global market.

Germany: Anchoring the European Market

In Europe, Germany stands out with a 24.9% share of the regional market in 2021 and a forecast CAGR of 3.7%. The presence of global diagnostic leaders such as Qiagen and the availability of reimbursement policies for diagnostic procedures are supporting the country’s growth. Additionally, increasing awareness of infection prevention is catalyzing further market expansion.

Soaring Demand for Market Information: Uncover Detailed Trends and Insights in Our Report! https://www.futuremarketinsights.com/reports/immunochromatography-kits-market

Category Insights: Applications and Distribution Channels

Infectious Disease Detection Drives Application Growth

Immunochromatography kits used for infectious disease detection accounted for 34.5% of the global market in 2021. Their ability to rapidly detect antibodies or viral proteins makes them highly effective, especially for immunocompromised patients where standard serological tests may fall short. As new infectious threats emerge globally, this application segment is expected to maintain strong growth momentum.

Hospital Pharmacies Remain Primary Distribution Channel

In 2021, hospital pharmacies dominated the distribution landscape with a 36.5% market share. These institutions play a pivotal role in the availability of immunochromatography kits for in-patient and emergency diagnostic use. Their efficiency in point-of-care testing (POCT) enables quicker turnaround times for diagnosis and treatment decisions, further reinforcing their importance.

Innovation and Strategic Collaborations Boost Market Competitiveness

The competitive landscape of the immunochromatography kits market is defined by mergers, acquisitions, and technological innovations. For example:

  • In December 2021, Quidel Corporation finalized the acquisition of Ortho Clinical Diagnostics, enhancing its capabilities in rapid diagnostics.
  • Abbott Laboratories secured a CE mark in January 2021 for its Panbio rapid antigen test, expanding access to self-administered screening tools across Europe.

Such strategic initiatives are enabling companies to expand their product portfolios, geographic reach, and overall market presence.

Key Players Shaping the Industry

Prominent companies profiled in the market include:

  • Abbott Laboratories
  • PerkinElmer Inc.
  • Danaher Corporation
  • Bio-Rad Laboratories
  • F. Hoffmann-La Roche AG
  • bioMérieux SA
  • Becton, Dickinson and Company
  • Siemens Healthineers AG
  • Thermo Fisher Scientific Inc.
  • QIAGEN

These organizations are at the forefront of research, innovation, and commercialization of immunochromatography technologies, focusing on improving sensitivity, specificity, and ease of use.

Get Expert Healthcare Industry Insights Now! https://www.futuremarketinsights.com/industry-analysis/life-science-and-biotechnology

Market Segmentation at a Glance

By Product:

  • Readers
  • Kits

By Application:

  • Sexually Transmitted Diseases
  • Infectious Diseases
  • Diabetes
  • Pregnancy Testing
  • Drug Abuse Testing
  • Others

By Distribution Channel:

  • Hospital Pharmacies
  • Retail Pharmacies
  • Supermarkets/Hypermarkets
  • E-Commerce

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East and Africa (MEA)

As the global healthcare landscape continues to evolve, the immunochromatography kits market is well-positioned for sustained growth, supported by a robust pipeline of innovations, an expanding disease burden, and increasing adoption of point-of-care diagnostic technologies. With continued investment and collaboration, these kits will remain central to public health responses, routine screenings, and emergency diagnostics well into the next decade.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Dental Flap Surgery Market Set to USD 10.31 Billion by 2032 a CAGR of 7.5%, Fueled by Rising Periodontal Cases and Demand for Advanced Dental Solutions | FMI

The global dental flap surgery market is witnessing a significant upsurge, poised to double its valuation from USD 5 Billion in 2022 to USD 10.31 Billion by 2032, growing at a robust CAGR of 7.5% over the forecast period. This notable expansion is attributed to the increasing global burden of periodontitis, rising awareness of oral hygiene, and a surge in demand for triangular flap surgery, an advanced and minimally invasive periodontal procedure.

Periodontitis: A Global Health Concern Driving Demand

As per the World Health Organization (WHO), over 1 billion people globally are affected by periodontal diseases, accounting for approximately 14% of the adult population. This growing prevalence is directly contributing to a rising need for dental flap surgeries, especially for treating periodontal pockets—a hallmark of moderate to severe gum disease.

Get Ahead of Market Shifts: Request Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15760

Flap surgery, a proven and effective method of treating gum disease by removing infection and reshaping the gum line, is increasingly recognized as a crucial intervention. The method allows dental professionals to remove bacteria from under the gums and stitch the tissue back for better attachment and healing.

Rise in Triangular Flap Surgery: A Game-Changer in Periodontal Treatment

The triangular flap surgery segment is witnessing exceptional growth and is expected to hold a 28% market share in 2022. This technique, known for its tension-free closure, rapid wound healing, and minimal tissue trauma, has emerged as a preferred method for addressing gum issues in posterior teeth and maxillary incisors.

Patients prefer this method for its aesthetic advantages, such as the absence of papilla retraction and minimal gingival recession, along with higher satisfaction rates. Clinicians also benefit from better visibility and easier access to affected areas, enabling more efficient treatment. As a result, triangular flap surgery is forecasted to remain a dominant procedure throughout the next decade.

Dental Clinics: The Preferred Hub for Flap Surgeries

On the end-user front, dental clinics are at the forefront of market share, accounting for 70% of all dental flap surgeries in 2022. The primary driver here is the availability of specialists, advanced technologies, and a focus on innovative patient care models.

Dental clinics are especially appealing for patients due to their cost efficiency, personalized services, and enhanced focus on preventive care and education. Over 80% of dental clinics globally are independently owned, a factor that has contributed to increased accessibility and adoption of dental services among a broader population.

Asia Pacific: Emerging as a Dental Surgery Hotspot

The Asia Pacific region is rapidly establishing itself as a leader in the dental flap surgery space, with a 35% market share in 2022. Countries like India, China, and Japan are at the helm of this growth due to several driving factors:

  • A large aging population prone to periodontal diseases
  • High prevalence of dental caries and poor oral hygiene
  • Growth in dental tourism and increased investment in healthcare infrastructure

China, in particular, is witnessing strong momentum with a rise in private dental clinics, advanced technologies, and public awareness campaigns aimed at improving oral care standards.

North America: Dominating the Market with Technological Advancements

With a 40% share in 2022, North America continues to lead the global dental flap surgery market. The United States is at the forefront, benefiting from:

  • A well-developed healthcare system
  • Government funding for dental care programs
  • A steady increase in routine dental visits, especially among the elderly
  • Strong correlations between periodontitis and cardiovascular diseases, prompting preventive treatments

The Canadian Dental Association reports that 11% of Canada’s population suffers from severe periodontal disease, further underlining the need for effective interventions such as flap surgery.

Growing Market Interest: Explore Comprehensive Insights and Trends with Our Detailed Report! https://www.futuremarketinsights.com/reports/dental-flap-surgery-market

Country Focus: The USA and China at the Forefront

In the United States, the developed healthcare ecosystem, combined with R&D advancements, high disposable income, and public awareness, continues to fuel demand for sophisticated dental treatments.

Meanwhile, China is growing at an unprecedented rate due to its expanding network of dental clinics, rise in dental tourism, and widespread public awareness campaigns led by both private players and government initiatives.

Start-Ups and Innovations Reshaping the Dental Flap Surgery Landscape

Several innovative startups are entering the dental flap surgery market, pushing the boundaries of traditional treatment methods:

  • Convergent Dental is revolutionizing procedures with CO₂ laser systems for hard and soft tissue surgeries.
  • Neoss is expanding the scope of dental implant surgeries through modular and minimally invasive approaches.
  • Smiles, Toothsi, and iDentical are creating disruptive dental care models with a focus on accessibility and affordability.

These emerging players are reshaping the competitive landscape by integrating technology, convenience, and patient-centric care into dental services.

Key Companies Profiled

Aspen Dental Management Inc.; Apollo White Digital; Coast Dental; Dr. Joy Dental Clinic; Smiles by Dr. Santos LLC; Axis Dental; Great Expressions Dental Centers; HM Hospital Madrid; Humanitas Hospital; Partha Dental Clinics

Segment Overview

  • By Type:
    • Triangular Flap
    • Rectangular Flap
    • Envelope Flap
    • Submarginal Flap
    • Others
  • By End User:
    • Hospitals
    • Dental Clinics
  • By Region:
    • North America
    • Latin America
    • Europe
    • Asia Pacific
    • Middle East & Africa

Advantage Healthcare Insights to Outpace Competitors! https://www.futuremarketinsights.com/industry-analysis/dental-device

Conclusion

The global dental flap surgery market is undergoing a transformative phase driven by a confluence of clinical need, patient awareness, and technological advancement. As periodontitis and other gum diseases continue to affect millions worldwide, dental professionals and institutions are increasingly adopting flap surgery as a vital treatment modality. With Asia Pacific and North America leading the charge, and triangular flap surgery gaining ground as the method of choice, the industry is on a clear trajectory toward sustained and impactful growth.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Inhalation and Nasal Spray Generic Drugs Market is anticipated to reach USD 49.01 Billion by 2033 at a CAGR of 8.96% | FMI

The global inhalation and nasal spray generic drugs market is projected to have a moderate-paced CAGR of 8.96% during the forecast period. The current valuation of the inhalation and nasal spray generic drugs market is USD 20.78 Billion in 2023. The value of the inhalation and nasal spray generic drugs market is anticipated to reach a high of USD 49.01 Billion by the year 2033.

The primary factor that is driving the sales of inhalation and nasal spray generic drugs is the increasing prevalence of chronic respiratory disorders across the world. According to the Global Asthma Report, there are around 330 million people around the world who suffer from asthma, and it is anticipated that this number is expected to rise to more than 400 million instances by the year 2025. The primary factors contributing to an increase in the number of people diagnosed with asthma around the world include increased air pollution, smoking, and tobacco usage.

Get Insights into Market Movements: Request a Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15759

The inhalation and nasal spray generic drugs market are likely to be driven by factors such as the growing population of elderly people and the increased vulnerability of elderly people to persistent respiratory disorders. According to projections made by the WHO, by the year 2030, one in every six persons throughout the globe is anticipated to be 60 years old or older. In addition to this, it is anticipated that the global population of such people is expected to reach 2.1 billion by the year 2050. In addition, the Asthma and Allergy Foundation of America estimates that around 7.8% of the population in the United States were 65 or older and had asthma in the year 2020.

However, the demand for inhalation and nasal spray generic drugs is anticipated to be hampered by regulatory impediments brought on by strict rules for the selling of generic medications in countries such as Mexico and Russia. For example, the regulatory authority of Mexico, COFEPRIS, has announced new rules for the issuance of registrations of generic pharmaceuticals. These new standards are likely to not include patents of new therapeutic uses in its linkage system. In addition, COFEPRIS provides a unique procedure window for the approval of generic pharmaceutical products in Mexico.

Key Takeaways

  • During the time covered by the projections, the Asia-Pacific region is anticipated to achieve a lucrative CAGR of 11.23%. The formation of strategic alliances in the region to facilitate the production of generic goods is largely responsible for the expansion of the region.
  • In 2021, North America maintained its position as the market leader, with a revenue share that was greater than 35.0%. The primary elements that are contributing to the expansion of this region are, in addition to the growing incidence of chronic respiratory disorders, the introduction of new products, the completion of acquisitions, and the formation of partnerships.
  • Due to rising costs associated with healthcare and robust demand for generic medications, retail pharmacies held the greatest revenue share in 2021, accounting for more than 55.0% of total revenue.
  • As a result of advantageous reimbursement rules and an increasingly older population, the homecare sector accounted for more than 50.0% of the total income generated in 2021.
  • In 2021, the adult patient segment was responsible for more than 40.0% of the revenue that was generated. The primary element that is contributing to the expansion of the segment is an increase in the number of adult patients who suffer from asthma and COPD.
  • Due to the widespread use of bronchodilators for the treatment of respiratory illnesses such as asthma and COPD around the world, the bronchodilators market category accounted for the greatest revenue share in 2021, which was over 25.0%.

Rising Demand for Market Data: Our Full Report Offers Deep Insights and Trend Analysis! https://www.futuremarketinsights.com/reports/inhalation-and-nasal-spray-generic-drugs-market

Competitive Landscape

Growth initiatives, such as product innovation, regulatory approval of new products, and mergers and acquisitions, are a primary emphasis of the inhalation and nasal spray generic drugs market leaders. For instance, Cipla Inc. submitted an ANDA for a generic version of Advair Diskus, fluticasone propionate, and salmeterol inhalation powder in May 2020. Phase three trials of the product were successfully completed by the company in April 2020. The following companies are leaders in the global market for generic inhalers and nasal sprays:

  • Mylan N.V.
  • Akorn, Operating Company LLC
  • Cipla Inc.
  • Sandoz International GmBH (Novartis AG)
  • Apotex Inc.
  • Hikma Pharmaceuticals PLC
  • Sun Pharmaceuticals Industries Ltd.
  • Beximco Pharmaceuticals Ltd

Key Segments in the Inhalation and Nasal Spray Generic Drugs Market

By Drug Class:

  • Bronchodilators
  • Combination Drugs
  • Corticosteroids
  • Decongestant Sprays
  • Antihistamines
  • Others

By Indication:

  • Asthma
  • Chronic Obstructive Pulmonary Disease (COPD)
  • Allergic Rhinitis
  • Others

By Patient Demographics:

  • Geriatric Patient
  • Adult Patient
  • Paediatric Patient

By End-user:

  • Hospitals
  • Homecare
  • Others

By Distribution Channel:

  • Hospitals Pharmacy
  • Retail Pharmacy
  • Online Pharmacies

By Region:

  • North America
  • Latin America
  • Asia Pacific
  • Middle East & Africa (MEA)
  • Europe

Make Informed Decisions in Healthcare with Expert Analysis! https://www.futuremarketinsights.com/industry-analysis/pharmaceuticals

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
How to Wed a Foreign Woman in a Domestic Relation

Marrying a foreign woman can be challenging and frequently involves legitimate issues, requirements for a card, multiculturalism regulations, economic problems, and ethnic differences. When considering this type of relationship, it is important to remain nicely informed and seek specialized advice.

Many of these ladies believe that marrying a prosperous American man may give them monetary security because they are from underprivileged regions. Another are merely seeking romance.

Lawful Voraussetzungen

If your American ( citizen or green card holder ) intending spouse is currently residing abroad, they will need to undergo a “adjustment of status” to convert from temporary work visas to permanent residency in the Us. They must first get married before doing this.

Make sure your marriage has the appropriate evidence to meet these needs because matrimony norms vary by nation. This might include a current passport, age-restricted records, and residency needs.

You ought to conduct research on the native bride regulations in the nation where you intend to get married. Make sure your spouse complies with the registration demands, for as having no obstacles and having authorized waiting phases. You should obtain an established marriage document from the nation where the ceremony took place following your ceremony. To meet the requirements of some nations, you might need to have this report apostilleled or legally verified. This will help you make sure your union is approved for upcoming multiculturalism objectives.

Visas

Marriage to a foreign national involves a variety of authorized responsibilities, some of which require you to take into account your spouse’s current multiculturalism position. In order to obtain a green card, your spouse or girlfriend must usually go through an “adjustment of position” procedure known as “adjustment of status” for a temporary card( such as a K1 Fiance Visa or Cr1 Spouse Visa ). To do this, you must satisfy citizenship and waiting period requirements as well as provide evidence of the existence of the relationship.

If you marry someone outside https://cupidbrides.com/latin-dating-sites/ of the united states, diplomatic running, which is typically quicker, did make this process easier for them. Yet, due to time constraints or job and family commitments, this may not be practical for everyone. Regardless, having a plan B is often a good idea in the event that things don’t go as planned.

Immigration and customs Act

It can take time and money to marry a foreign lady. There are legal obstacles that must be overcome in addition to the multiculturalism law’s numerous needs. To learn more about the procedure, you may consult an attorney.

Additionally, you should be aware of the customs and laws of the nation where you are getting married. Although Canada properly possess diverse views on marriage, marital sexual, and other problems, this nation does possess unique sights.

You may apply for a card to wed a stranger while they are a resident of the united states in some circumstances. A K-1 girlfriend card is what. This visa is granted on the basis that the immigrant has the assurance that they will continue to reside in the united states and won’t refile their program for permanent residency. The immigrant’s sponsor must sign an oath of assistance informing the partner that it will support the couple for ten years after the marriage is approved.

What are the demands for marriage?

If you and your spouse want to get married somewhere else in the world, make sure you follow the laws of the nation where you want to marry. Some nations require a time of internship before you can get married, while others have requirements for identifying and a person’s years. Additionally, you might need to have certain paperwork translated, authenticated, and notarized.

You should also examine whether a nation recognizes relationships between people who are people of other nations. Additionally, U.s. Embassy and Consulate workers cannot marry in additional nations, so you must contact local civil or religious authorities.

The decision to wed a foreign nationwide is get time-consuming, difficult, and expensive. Nevertheless, it’s possible to get past the obstacles by researching the requirements and consulting an suffered emigration attorney. Additionally, you may help your global marriage by addressing cultural distinctions, speaking up, and engaging in one another’s practices.

Although Latin Dating Is Diverse, It is possible to Be Worthwhile It.

Latin dating is unique, but it can be worthwhile. Italian people bring something unique to relationships by having a distinct culture, active lifestyle, and flaming nature https://latin-dating-sites.org/.

Their love and passion for career are a surprise that both stimulates and strengthens. And they are effective at improving their relationship with their families. A spanish girl might be the best choice for you if you’re looking for a partner who is compassionate and kind.

A italian girl will most likely benefit compassion, fealty, and respect for her family and community. Make an effort to learn about her qualifications and practices in order to express your gratitude for her. You can do this to help you form a strong and lasting friendship with her.

Sometimes it can be unpleasant to understand how a Latina ideals home. For instance, if your latina girlfriend or wife works to support you and her own community while caring for her parents, siblings, or children, it may be hard for her to balance all. As she tries to balance her obligations, become patient and sympathetic. She’ll appreciate your efforts to better comprehend her circumstance and work through it along.

Dating a seductive Italian lady can be difficult, despite the myth. Numerous potential matches have a limiting view of Latinas, which frequently involves racialized discrimination and ethnic prejudices. Some persons, for instance, properly sexualize a Latina’s system, fetishize her complexion colour, or create racist remarks about her scalp. As evidenced by the fact that they are the largest group of women with lower socio-economic status in the us, some people may assume that a Latina is certainly educated or competent.

You may become willing to reject prejudices and accept a Latina as her distinctive ego in order to get past this. Despite the difficulties, dating a Latina can be a fulfilling knowledge that will enhance your sense of joy and bring you closer to your loved ones.

Consider joining a neighborhood group or historical event that draws latino participants in order to interact with localized Latinas in a more edible and non-digital setting. You’ll be able to communicate with Latinos there who share your interests and principles in a setting that feels comfortable and safe. You’ll be able to break down barriers and form lasting relationships that will result in long-lasting tales.

Liposomal Doxorubicin Market Set for Steady Growth with 6.3% CAGR Through 2034

The Liposomal Doxorubicin Market is estimated to be valued at USD 1,281.3 million in 2024. Demand is predicted to rise at a CAGR of 6.3% from 2024 to 2034. The market is anticipated to reach USD 2,367.5 million by 2034. The liposomal doxorubicin market is experiencing significant growth as demand for advanced oncology treatments continues to rise globally. Liposomal doxorubicin, a formulation of the chemotherapy drug doxorubicin encased in liposomes, offers a targeted approach for treating various cancers, including breast cancer, ovarian cancer, and Kaposi’s sarcoma. This liposomal delivery method enhances the drug’s efficacy while minimizing its toxic effects, particularly on the heart, which has long been a concern with conventional doxorubicin therapy.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14706

This specialized formulation has become a preferred option among oncologists due to its favorable safety profile and ability to deliver sustained therapeutic concentrations at the tumor site. The liposomal doxorubicin market is expanding across both developed and emerging economies, driven by increasing cancer prevalence, the shift toward safer treatment modalities, and growing awareness of liposomal drug delivery systems.

Government support, ongoing clinical research, and regulatory approvals are also contributing to the rise in adoption. Moreover, as pharmaceutical companies continue to focus on developing and enhancing targeted cancer therapies, the liposomal doxorubicin market is expected to remain a vital segment in the broader oncology drug landscape.

Market Trends

The liposomal doxorubicin market is being shaped by several prominent trends that reflect advancements in drug delivery technologies and changing dynamics in cancer treatment protocols. One of the major trends is the increasing use of nanotechnology in drug formulation. Liposomal encapsulation is part of a larger movement toward nano-drug delivery systems, which enhance the bioavailability and targeting capability of anticancer agents.

The global trend toward personalized medicine is also influencing the development and utilization of liposomal doxorubicin. As oncologists seek to tailor treatments to individual patient profiles, the reduced toxicity and improved pharmacokinetics of liposomal formulations make them an attractive option in personalized therapy regimens. This is particularly evident in populations with higher susceptibility to drug-induced cardiotoxicity, such as elderly patients or those with pre-existing heart conditions.

Furthermore, the integration of liposomal doxorubicin in combination therapies is becoming increasingly common. Oncologists are exploring its use alongside immunotherapies, radiation, and other chemotherapeutic agents to improve treatment outcomes. These combination protocols are enhancing the therapeutic index of existing regimens while leveraging the protective properties of liposomal carriers.

Another key trend is the rise in approvals and ongoing clinical trials evaluating liposomal doxorubicin in indications beyond its traditional scope. Researchers are expanding its application to treat different tumor types, including pancreatic and lung cancers. As more data becomes available, the liposomal doxorubicin market is likely to witness further expansion into new therapeutic areas.

Challenges and Opportunities

While the liposomal doxorubicin market holds significant potential, it also faces several challenges that stakeholders must navigate. One of the primary obstacles is the high cost associated with the production and development of liposomal drug formulations. Compared to conventional chemotherapy, liposomal drugs require complex manufacturing processes and stringent quality controls, which can increase pricing and limit accessibility in low-income regions.

Intellectual property concerns and competition from generic versions are also creating challenges in certain markets. As patents expire, companies face increased pricing pressure and reduced profit margins. This makes it crucial for manufacturers to innovate, differentiate their offerings, and establish strong branding strategies to maintain market share.

Additionally, logistical and storage issues can affect the market. Liposomal doxorubicin formulations often require specific temperature and storage conditions, which may be difficult to maintain in remote or underdeveloped healthcare facilities. This can restrict their distribution and adoption in rural areas.

However, these challenges bring about significant opportunities. The growing focus on reducing chemotherapy side effects presents a major chance for liposomal doxorubicin to cement its place in cancer treatment regimens. Healthcare providers are seeking alternatives that reduce hospitalizations and treatment interruptions due to adverse effects, which liposomal doxorubicin can help achieve.

Another opportunity lies in the development of advanced delivery systems and scalable manufacturing techniques that reduce production costs and improve stability. Partnerships between academic institutions, biotech startups, and pharmaceutical giants can drive innovation and accessibility. Expanding public-private collaborations can also help address regional disparities in cancer care, further boosting the liposomal doxorubicin market.

Key Points:

The liposomal doxorubicin market is primarily driven by its ability to provide effective cancer treatment with fewer side effects. This drug is designed to release doxorubicin slowly and specifically at the tumor site, reducing systemic exposure and minimizing damage to healthy tissues. Such controlled delivery significantly lowers the risk of cardiotoxicity, a common complication of traditional chemotherapy.

Its versatility across multiple cancer types further enhances its market appeal. The drug is commonly used in breast cancer, ovarian cancer, multiple myeloma, and Kaposi’s sarcoma, among others. The increasing burden of these diseases globally supports steady demand.

Moreover, the product’s inclusion in standard treatment guidelines and protocols by various cancer associations adds credibility and facilitates clinical adoption. These endorsements help drive insurance reimbursements and regulatory approvals in multiple countries, further contributing to market penetration.

Key Regional Insights

The liposomal doxorubicin market shows varying degrees of growth across different regions, shaped by healthcare infrastructure, regulatory environments, and cancer prevalence. North America is currently the largest market, led by the United States. This dominance is attributed to a well-established healthcare system, high awareness levels, extensive R&D investments, and the presence of leading pharmaceutical companies.

Europe follows closely, with countries like Germany, the United Kingdom, and France exhibiting high demand for advanced oncology treatments. Regulatory support from bodies such as the European Medicines Agency ensures market accessibility and patient safety. These factors collectively contribute to the region’s steady growth in the liposomal doxorubicin market.

Asia-Pacific is emerging as a fast-growing region, driven by increasing cancer incidence, expanding healthcare infrastructure, and rising investment in oncology research. Countries such as China, India, and Japan are experiencing heightened demand for effective and safe cancer therapies. As these nations continue to adopt global best practices in cancer care, their contribution to the liposomal doxorubicin market is expected to grow substantially.

Latin America and the Middle East & Africa also present untapped potential. Despite challenges like limited access and lower public healthcare spending, improving healthcare reforms and partnerships with international agencies are laying the groundwork for growth in these regions.

Competitive Outlook

The liposomal doxorubicin market is characterized by intense competition among established players and emerging entrants. Leading pharmaceutical companies are focused on expanding their product pipelines, enhancing production capabilities, and strengthening distribution networks to retain market share. They are also actively involved in research and development to create improved formulations and explore new therapeutic indications.

Collaborations and licensing agreements are commonly used strategies in this market. Companies often form partnerships with research institutions and biotech firms to gain access to cutting-edge technologies and accelerate the commercialization of new liposomal doxorubicin products.

In addition, strategic acquisitions are enabling firms to consolidate their market position and gain entry into emerging markets. The competition is further intensified by the entry of generic manufacturers following the expiration of key patents. These companies are leveraging cost-effective production methods to offer affordable alternatives and expand access, particularly in price-sensitive markets.

Top Companies

Several companies play a pivotal role in driving innovation and growth in the liposomal doxorubicin market. These include multinational pharmaceutical giants with a global footprint and specialty firms focused on oncology and drug delivery systems. Their extensive research efforts, robust distribution networks, and regulatory expertise position them at the forefront of the market.

These top companies are actively investing in expanding their portfolios to include next-generation liposomal drugs, aimed at providing enhanced efficacy, better targeting, and reduced adverse effects. Many are also exploring new combinations with immunotherapies and targeted agents to create more comprehensive cancer treatment solutions.

Emerging players, particularly those in biotech and nanotechnology sectors, are bringing fresh perspectives and disrupting traditional models. Their agility and focus on niche innovations allow them to meet unmet needs and carve out specific segments within the liposomal doxorubicin market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/liposomal-doxorubicin-market

Segmentation Outlook

The liposomal doxorubicin market can be segmented based on application, end-user, distribution channel, and region. By application, the market encompasses cancer types such as breast cancer, ovarian cancer, multiple myeloma, and Kaposi’s sarcoma. Breast and ovarian cancers currently account for a significant portion of the market, but other segments are rapidly growing due to broader clinical trials and approvals.

End-users include hospitals, cancer specialty centers, and research institutions. Hospitals remain the dominant end-users, given the need for controlled administration and monitoring during chemotherapy. However, outpatient cancer clinics and specialty centers are becoming increasingly important due to the growing trend of decentralized cancer care.

In terms of distribution, the market is served through hospital pharmacies, retail pharmacies, and online platforms. Hospital pharmacies are the primary distribution channels due to the clinical nature of the drug. However, with the rise in outpatient care and telemedicine, retail and online channels are gaining momentum.

Regionally, North America and Europe continue to lead in market size and technological innovation. Meanwhile, Asia-Pacific is expected to experience the highest growth rate over the forecast period, driven by increased investments in healthcare and pharmaceutical manufacturing.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

DNA Diagnostics Market Set for Robust Growth with 7.8% CAGR Through 2034

The global sales of DNA diagnostics are estimated to be worth USD 27,094.2 million in 2024 and are anticipated to reach a value of USD 57,420.1 million by 2034. Sales are projected to rise at a CAGR of 7.8% over the forecast period between 2024 and 2034. The revenue generated by DNA diagnostics in 2023 was USD 25,133.8 million.

The DNA diagnostics market is transforming the landscape of medical diagnostics by offering highly accurate, efficient, and personalized insights into a variety of genetic and infectious diseases. As the demand for early and precise detection of health conditions increases, DNA-based diagnostic tools are gaining prominence across clinical, research, and home testing applications. These tools are helping healthcare professionals detect inherited disorders, identify infectious agents, guide cancer therapies, and monitor disease progression with unprecedented precision.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14700

With rapid advancements in biotechnology, next-generation sequencing, and polymerase chain reaction technologies, the DNA diagnostics market has evolved significantly. The integration of genetic information into healthcare decisions enables more personalized treatment strategies, better patient outcomes, and optimized therapeutic interventions. As genomics becomes a cornerstone of precision medicine, the relevance of DNA-based diagnostics continues to grow in both developed and developing markets.

Expanding research into genetic disorders, oncology, and infectious diseases is further driving the adoption of DNA diagnostic tools. Moreover, heightened consumer awareness of genetic testing for health risk assessments and ancestry tracing has introduced new growth channels within the market. These evolving applications and the shift toward preventive healthcare are expected to fuel sustained growth in the DNA diagnostics market in the coming years.

Market Trends

One of the most significant trends shaping the DNA diagnostics market is the increasing integration of advanced molecular technologies into routine healthcare. The accessibility of next-generation sequencing and real-time PCR has improved the speed and accuracy of DNA-based testing. These innovations are enabling clinicians to diagnose diseases more effectively and customize treatment regimens based on a patient’s genetic profile.

The market is also witnessing a shift toward non-invasive testing methods. Liquid biopsies, which analyze DNA fragments in blood samples, are gaining traction as a less invasive alternative to traditional tissue biopsies. These tests are especially valuable in oncology, where they help in monitoring tumor progression and detecting cancer mutations in real time.

Another emerging trend is the growing consumer interest in direct-to-consumer DNA testing kits. These kits, which can be ordered online and used at home, offer insights into ancestry, nutrition, lifestyle traits, and genetic risk factors. The popularity of such kits has not only raised public awareness about genetic diagnostics but has also expanded the scope of the DNA diagnostics market beyond clinical settings.

Moreover, artificial intelligence and machine learning are increasingly being employed to interpret complex genetic data. These technologies enhance the diagnostic process by identifying patterns and predicting disease risk with high accuracy. The integration of AI into DNA diagnostics is expected to revolutionize personalized medicine and streamline laboratory workflows.

Driving Forces Behind Market Growth

The primary driver behind the growth of the DNA diagnostics market is the rising global burden of genetic and chronic diseases. Conditions such as cancer, cardiovascular diseases, and rare inherited disorders are prompting the need for early and precise diagnostics. DNA-based tests provide the molecular insights necessary to diagnose these conditions accurately and tailor patient-specific treatment plans.

A growing emphasis on preventive healthcare is also contributing to the expansion of the DNA diagnostics market. As individuals become more proactive about their health, demand for genetic screening and risk assessment tools has surged. These diagnostics empower individuals to take preemptive measures, make informed lifestyle choices, and work with healthcare providers to mitigate potential risks.

Additionally, increasing investments in research and development by pharmaceutical and biotechnology companies are fueling innovation in DNA diagnostics. Government initiatives supporting genomics research, healthcare digitization, and personalized medicine are further accelerating market development. Favorable reimbursement policies and regulatory approvals for new diagnostic products are enhancing market access and patient affordability.

The COVID-19 pandemic also highlighted the critical role of DNA diagnostics in managing infectious diseases. The widespread use of PCR testing for viral detection underscored the value of molecular diagnostics in public health, setting a precedent for their continued application in future outbreaks.

Challenges and Opportunities

Despite its growth potential, the DNA diagnostics market faces several challenges. One of the primary concerns is the high cost of advanced genetic testing technologies, which can limit accessibility in low-income and underserved regions. Although costs have decreased significantly in recent years, affordability remains a barrier for widespread adoption, particularly in rural healthcare settings.

Another challenge lies in the complexity of genetic data interpretation. While DNA diagnostics provide valuable insights, translating these findings into actionable clinical decisions requires specialized expertise. The shortage of trained genetic counselors and molecular pathologists in many regions hampers the effective utilization of diagnostic results.

Privacy and ethical concerns also pose challenges for the DNA diagnostics market. As genetic data becomes more integrated into healthcare, safeguarding patient information and securing informed consent become increasingly important. Addressing these concerns is essential to maintaining public trust and promoting the responsible use of genetic technologies.

Nonetheless, these challenges present several opportunities for market players. Continued investment in low-cost, portable diagnostic devices can improve access in remote and resource-limited areas. Partnerships between public health agencies, research institutions, and private companies can help bridge gaps in infrastructure, training, and affordability.

Furthermore, the development of automated, user-friendly diagnostic platforms offers significant potential for improving scalability and efficiency. These solutions can help laboratories process large volumes of samples with minimal error, reducing turnaround times and expanding access to high-quality diagnostics.

Regional Analysis

The DNA diagnostics market shows strong performance across all major regions, although growth dynamics vary by geography. North America currently leads the market due to its robust healthcare infrastructure, advanced research capabilities, and high adoption of molecular diagnostics. The United States, in particular, is home to several key players and a strong ecosystem for genomic research and innovation.

Europe follows closely, with countries like Germany, the United Kingdom, and France actively promoting personalized medicine and genetic research initiatives. Supportive regulatory frameworks and reimbursement systems contribute to the widespread availability of DNA-based diagnostics in these regions.

The Asia-Pacific region is emerging as a high-growth market for DNA diagnostics. Rising healthcare awareness, improving diagnostic infrastructure, and increasing government investment in genomics are driving demand across countries like China, India, Japan, and South Korea. The growing burden of chronic and genetic diseases, along with expanding medical tourism, also supports market expansion in the region.

Latin America and the Middle East & Africa present emerging opportunities as well. While these regions face infrastructure challenges, rising awareness and international collaboration are encouraging the adoption of DNA diagnostics. Public-private partnerships and mobile diagnostic labs can help extend services to underserved populations.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/dna-diagnostics-market

Competitive Outlook

The DNA diagnostics market is highly competitive, with numerous established companies and emerging startups vying for market share. Key players focus on product innovation, strategic collaborations, and mergers and acquisitions to strengthen their presence. Companies are investing heavily in R&D to develop more accurate, faster, and cost-effective diagnostic tools.

Technological advancements remain a major driver of competitive advantage. Firms that can integrate cutting-edge technologies such as AI, cloud computing, and robotics into their diagnostic platforms are better positioned to lead the market. The ability to provide comprehensive diagnostic solutions across a range of applications, including oncology, infectious diseases, and genetic disorders, is another critical differentiator.

Customization and patient-centric offerings are also becoming essential for companies looking to gain a foothold in the DNA diagnostics market. Providing personalized reports, integrated health recommendations, and seamless digital platforms enhances user experience and builds customer loyalty.

Top Companies

Several top companies are leading the DNA diagnostics market through innovation, global expansion, and strategic partnerships. These organizations develop and commercialize a wide range of DNA-based diagnostic tools, including laboratory equipment, test kits, and software platforms.

Prominent names in the market include global biotechnology and diagnostic firms that have established strong product portfolios and global distribution networks. These companies have the resources to invest in clinical trials, regulatory compliance, and marketing, enabling them to launch new products efficiently and reach diverse customer segments.

In addition to established players, the market includes a growing number of startups focused on niche segments such as home DNA testing, rare disease diagnostics, and AI-driven analysis. These companies are attracting significant venture capital funding and disrupting traditional models with innovative and agile approaches.

Segmentation Outlook

The DNA diagnostics market can be segmented based on application, technology, end-user, and region. By application, the market includes oncology, infectious disease diagnostics, genetic testing, prenatal screening, and forensic testing. Among these, oncology and genetic testing represent the fastest-growing segments due to their role in personalized treatment planning.

In terms of technology, key segments include PCR, microarrays, next-generation sequencing, and in situ hybridization. Each of these technologies offers distinct advantages in terms of sensitivity, speed, and scalability, allowing healthcare providers to select the most appropriate tool based on diagnostic needs.

End-users of DNA diagnostics include hospitals, diagnostic laboratories, research institutes, and home consumers. Clinical laboratories remain the primary users, but the rise of home testing kits and telemedicine platforms is expanding the end-user base and enabling direct-to-consumer engagement.

As precision medicine continues to evolve, market segmentation will grow increasingly granular. This trend will create new opportunities for product differentiation and targeted marketing strategies within the DNA diagnostics market.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Depression Treatment Market Set for Steady Growth with 5.2% CAGR Through 2034

The depression treatment market is valued at USD 11 billion in 2024. It is anticipated to grow at a CAGR of 5.2% during the assessment period and reach a value of USD 18.3 billion by 2034. The depression treatment market continues to expand due to the increasing recognition of mental health as a critical component of overall wellness. Depression remains one of the most widespread and debilitating mental disorders globally, impacting individuals of all ages, genders, and socioeconomic backgrounds. As awareness surrounding the impact of mental health grows, so does the demand for effective, accessible, and personalized treatments for depression.

The depression treatment market is supported by both public and private healthcare initiatives aimed at reducing the global burden of mental illness. A growing number of people are now seeking clinical help for their symptoms, leading to a surge in pharmaceutical prescriptions, psychological therapies, and innovative treatment options. Moreover, the stigma once associated with mental health disorders is gradually diminishing, encouraging more patients to pursue medical intervention. This cultural shift, paired with scientific progress, is shaping a market that offers both therapeutic hope and commercial opportunity.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-14687

This market encompasses a variety of interventions, including antidepressant medications, cognitive behavioral therapies, electroconvulsive therapy, transcranial magnetic stimulation, and newer modalities such as ketamine infusions and digital therapeutics. The increasing diversity of treatment options has enhanced market potential while creating opportunities for further innovation.

Market Trends

The depression treatment market is experiencing a shift toward more personalized and technology-driven solutions. Traditional antidepressants continue to dominate treatment regimens, but recent trends show rising interest in novel therapies with faster onset and fewer side effects. The use of digital platforms, mobile apps, and telemedicine has also grown substantially, enabling patients to access mental health support remotely and consistently.

One significant trend is the development of fast-acting antidepressants such as ketamine-based therapies and esketamine nasal sprays. These alternatives offer rapid relief, particularly for individuals with treatment-resistant depression. As research continues to support their efficacy, demand for these therapies is projected to grow, contributing to the expansion of the depression treatment market.

Another notable trend is the integration of artificial intelligence in mental health care. AI-powered diagnostic tools, chatbots, and predictive analytics are enhancing the ability to identify and monitor depressive symptoms early. These digital solutions allow healthcare providers to deliver more proactive and tailored care, improving overall outcomes for patients.

Pharmaceutical companies are also focusing on next-generation antidepressants that target alternative neural pathways. Unlike conventional selective serotonin reuptake inhibitors (SSRIs), new compounds aim to address depression through glutamate modulation and neuroplasticity enhancement. These innovative mechanisms are reshaping the scientific and commercial landscape of the depression treatment market.

Challenges and Opportunities

Despite significant progress, the depression treatment market faces several challenges. One of the most pressing issues is the variability in patient response to existing therapies. Many individuals do not respond adequately to first-line antidepressants, and it often takes weeks or months to determine the effectiveness of a given treatment. This delay can prolong suffering and increase the risk of complications, including suicidal ideation.

The side effects associated with some antidepressant medications also pose a challenge. Patients often report weight gain, sexual dysfunction, drowsiness, and other adverse effects that impact treatment adherence. Addressing these concerns remains a priority for researchers and pharmaceutical developers aiming to improve therapeutic efficacy and tolerability.

On the regulatory front, approval processes for new depression treatments can be lengthy and complex. Given the vulnerability of the target population, safety is paramount, often slowing the development pipeline. Additionally, mental health remains underfunded in many regions, limiting access to effective treatments for underserved populations.

However, these challenges open the door to numerous opportunities in the depression treatment market. Investment in personalized medicine and biomarker-driven treatment strategies holds the potential to match patients with the most effective therapies more quickly. Furthermore, expanding mental health insurance coverage and telepsychiatry infrastructure can bridge treatment gaps and bring support to previously unreachable communities.

Collaboration between public health institutions, academic researchers, and private-sector innovators is also creating new avenues for growth. Programs that encourage early intervention, workplace mental health support, and school-based mental wellness initiatives are increasingly viewed as effective tools in combating depression at a population level.

Key Points:

The depression treatment market is deeply influenced by changing perceptions of mental health and evolving treatment modalities. An aging population, combined with increasing rates of stress-related disorders and lifestyle factors, has contributed to the rising incidence of depression globally. These demographic and societal shifts ensure a sustained demand for therapeutic interventions and supportive care.

The complexity of depression as a clinical condition requires a multi-modal approach to treatment. Pharmacological solutions continue to play a foundational role, but there is growing emphasis on the integration of psychological therapies, lifestyle interventions, and digital support tools. This diversity of care enhances patient outcomes and expands the commercial landscape for providers and innovators.

Mental health advocacy and education campaigns have been instrumental in driving demand within the depression treatment market. As more individuals become aware of their symptoms and treatment options, the number of patients seeking help continues to grow. This increased demand is encouraging investment in research, healthcare infrastructure, and mental health training for professionals.

Key Regional Insights

The depression treatment market exhibits regional variation based on healthcare infrastructure, cultural attitudes, and economic development. North America holds a significant share of the market, driven by advanced medical research, widespread mental health awareness, and strong healthcare reimbursement systems. The United States, in particular, leads in the development and adoption of novel depression treatments, supported by robust pharmaceutical and biotech industries.

Europe also represents a mature market, with countries like Germany, the UK, and France implementing national mental health strategies and expanding access to care. Government-backed healthcare systems in the region support widespread availability of depression treatments, including psychological therapies and prescription medications.

In Asia-Pacific, the depression treatment market is growing rapidly due to increasing urbanization, socioeconomic pressures, and a rising awareness of mental health conditions. Countries such as Japan, China, and India are making strides in destigmatizing mental illness and investing in mental healthcare infrastructure. However, access to specialized care still varies greatly across urban and rural regions.

Emerging economies in Latin America, the Middle East, and Africa are recognizing the importance of mental health but continue to face challenges in accessibility, funding, and availability of trained professionals. International partnerships, non-governmental organizations, and telehealth services are gradually helping these regions expand their mental health services and improve patient outcomes.

Competitive Outlook

The depression treatment market is highly competitive and driven by the presence of both long-established pharmaceutical companies and emerging biotech firms. Major players are focused on maintaining market share through product innovation, strategic partnerships, and the acquisition of promising technologies. Research and development remain central to maintaining a competitive edge, with companies investing in new drug delivery systems, mechanism-based therapies, and patient support services.

In addition to pharmaceutical firms, digital health startups are increasingly entering the depression treatment market with teletherapy platforms, app-based mood trackers, and AI-driven therapeutic tools. These digital innovations not only complement traditional treatments but also offer scalable and cost-effective solutions for reaching wider populations.

Brand differentiation in this market often hinges on factors such as efficacy, safety profile, speed of onset, and ease of use. Companies that demonstrate strong clinical trial results and offer effective solutions for treatment-resistant depression tend to perform well. Patient support programs, digital integration, and transparent pricing models also contribute to long-term brand loyalty and market success.

Top Companies

Several top companies dominate the depression treatment market through the development of widely used antidepressants and mental health therapies. These include both multinational pharmaceutical corporations and specialized biotechnology firms with a focus on central nervous system disorders. These companies have built strong portfolios of products that are approved across multiple regions and continue to invest in innovative research.

In addition to drug manufacturers, leading telehealth and digital therapy providers are playing an increasingly important role in the market. Their platforms enable access to licensed therapists, personalized treatment plans, and interactive mental health content, broadening the reach of depression treatment services.

Academic collaborations and licensing deals between top companies and research institutions are further driving innovation in the market. These partnerships often lead to the development of novel compounds, targeted therapies, and data-driven treatment protocols designed to improve clinical outcomes.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/depression-treatment-market

Segmentation Outlook

The depression treatment market can be segmented by treatment type, age group, severity of condition, and distribution channel. Treatment types include pharmacological therapies such as SSRIs, SNRIs, atypical antidepressants, and non-pharmacological interventions like psychotherapy and neuromodulation techniques. Each category caters to different patient needs and clinical profiles.

By age group, the market serves adolescents, adults, and elderly populations. With increasing diagnosis rates in teenagers and growing mental health needs among the elderly, tailored treatments for specific age groups are becoming more common. Severity-based segmentation identifies mild, moderate, and severe depression cases, each requiring a distinct therapeutic approach.

Distribution channels range from hospital pharmacies and retail pharmacies to online platforms and direct-to-consumer digital health services. The expansion of online and telehealth-based distribution has allowed for greater convenience and privacy, especially for individuals reluctant to seek traditional in-person care.

As the demand for personalized and accessible treatment options grows, the segmentation of the depression treatment market will continue to evolve. These diverse market segments create opportunities for stakeholders to design patient-centric solutions and address unmet needs across different population groups.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Robotic Wheelchair Market Set for Rapid Growth with 11.1% CAGR Through 2034

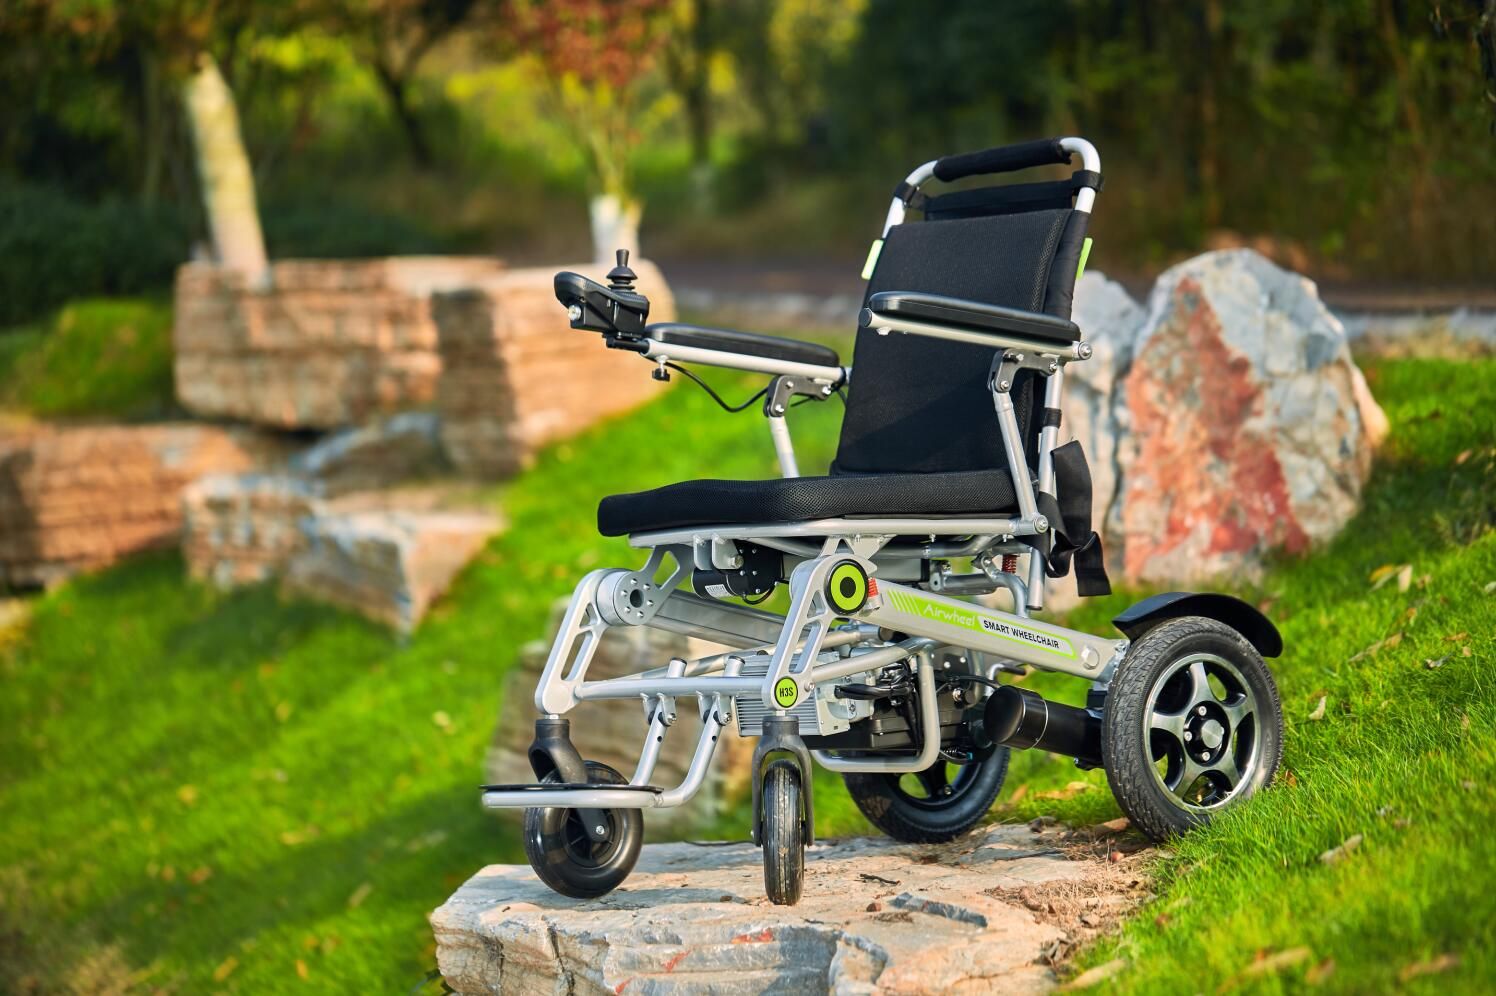
The global sales of robotic wheelchair is estimated to be worth USD 157.4 million in 2024 and anticipated to reach a value of USD 451.1 million by 2034. Sales are projected to rise at a CAGR of 11.1% over the forecast period between 2024 and 2034. The revenue generated by robotic wheelchair in 2023 was USD 141.7 million.

The robotic wheelchair market is witnessing a transformative phase, driven by innovations in robotics, AI integration, and an increasing demand for advanced mobility solutions. These motorized wheelchairs go beyond traditional designs by incorporating smart technologies that allow users to navigate independently and safely in complex environments. With a rising global population of elderly individuals and people with disabilities, the need for intelligent mobility devices is becoming more urgent. Robotic wheelchairs address this need by enhancing users’ autonomy, safety, and quality of life.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-12043

The robotic wheelchair market caters to a wide range of users, including those with severe physical impairments, neurological disorders, or age-related mobility issues. Unlike standard power wheelchairs, robotic models come equipped with features such as obstacle detection, path planning, voice and gesture recognition, and even eye-tracking controls. These capabilities offer a higher level of functionality and independence, particularly in indoor settings or confined spaces. As healthcare systems increasingly prioritize patient-centered care and quality outcomes, robotic wheelchairs are emerging as a preferred solution in both home and institutional settings.

Market Trends

Technological innovation is a defining trend in the robotic wheelchair market, with continuous improvements in machine learning, computer vision, and battery efficiency. The integration of sensors and real-time navigation systems is enabling wheelchairs to interact more intelligently with their environments. Developers are increasingly adopting user-centric designs, focusing on ergonomics, lightweight frames, and modular customization options. These trends aim to make robotic wheelchairs more adaptable and appealing to a broader demographic.

Another key trend is the adoption of Internet of Things (IoT) capabilities in robotic wheelchairs. These devices can now be synced with mobile apps, allowing caregivers and users to monitor performance, battery levels, and location in real time. The rise of telehealth and remote rehabilitation is also creating demand for wheelchairs that support data sharing and remote diagnostics. These connected features not only improve user convenience but also assist healthcare providers in tracking patient progress.

Affordability and access are also shaping the robotic wheelchair market, as companies strive to develop cost-effective models without compromising on advanced functionalities. Some manufacturers are exploring subscription-based or leasing models to increase accessibility among underserved populations. Additionally, there is a growing emphasis on sustainability, with new wheelchairs being designed for energy efficiency and recyclability.

Challenges and Opportunities

Despite its promising growth, the robotic wheelchair market faces several challenges that need to be addressed for its full potential to be realized. One of the main hurdles is the high cost of robotic wheelchairs, which can make them inaccessible to a large segment of the population. This cost is driven by sophisticated technologies such as AI, advanced sensors, and high-performance batteries, which add to the overall expense of production and maintenance.

Another major challenge is regulatory compliance. Robotic wheelchairs must adhere to stringent safety and performance standards, particularly if they are intended for use in medical or institutional environments. Navigating complex regulatory landscapes across different countries can slow down the time to market for new innovations.

However, these challenges also present opportunities for stakeholders in the robotic wheelchair market. As research and development continue to advance, economies of scale may help reduce production costs, making robotic wheelchairs more affordable. Public and private partnerships can play a significant role in funding innovation and improving accessibility through insurance and government reimbursement programs.

There is also an opportunity to expand the market through targeted education and awareness campaigns. Many potential users and healthcare professionals remain unaware of the capabilities of robotic wheelchairs. Highlighting their benefits through outreach and training initiatives can increase adoption and drive market growth.

Key Points:

The robotic wheelchair market is poised for sustained growth due to several converging factors. Rising disability rates, aging populations, and the global emphasis on inclusive mobility are creating a strong demand base. The increasing prevalence of conditions such as multiple sclerosis, spinal cord injuries, and muscular dystrophy further contributes to the need for advanced mobility aids.

Technological breakthroughs are making robotic wheelchairs smarter, more efficient, and easier to use. With built-in navigation systems, obstacle avoidance, and intelligent control interfaces, these devices offer unmatched autonomy for users. The incorporation of AI and machine learning allows wheelchairs to learn user habits and adapt to their environment, making them more intuitive over time.

Healthcare institutions and rehabilitation centers are adopting robotic wheelchairs as part of their assistive technology programs. These institutions recognize the value of improved patient mobility and the reduction in caregiver workload that robotic solutions can provide. As insurance coverage improves and public funding becomes more available, the market is likely to expand further.

Key Regional Insights

Geographically, the robotic wheelchair market shows diverse patterns of adoption, influenced by healthcare infrastructure, economic development, and technological readiness. North America currently leads the market, driven by strong investments in healthcare innovation, favorable insurance policies, and a high prevalence of age-related mobility issues. The United States, in particular, benefits from a robust ecosystem of tech companies, academic institutions, and healthcare providers focused on assistive technologies.

Europe follows closely, with countries like Germany, the UK, and France investing in smart healthcare solutions and aging-in-place initiatives. Regulatory support and funding from the European Union have encouraged the development and adoption of robotic mobility aids. The region also benefits from an increasing number of rehabilitation centers integrating robotics into their treatment models.

The Asia-Pacific region is emerging as a promising market for robotic wheelchairs, with countries like Japan, South Korea, and China leading in robotics research. Japan, with its rapidly aging population, has prioritized assistive technology development, resulting in innovative and compact robotic wheelchair designs. China’s growing middle class and expanding healthcare infrastructure also create opportunities for market expansion, particularly in urban areas.

In Latin America, the Middle East, and Africa, the robotic wheelchair market is still in its early stages. Limited access to advanced healthcare technology and lower levels of public funding remain barriers. However, international aid programs and growing awareness are beginning to create footholds in these regions.

Competitive Outlook

The robotic wheelchair market is characterized by a mix of established medical device manufacturers and emerging startups focused on innovation. Competition is intense, with companies striving to differentiate themselves through features, pricing, and customer support. The market is also seeing strategic collaborations between technology firms and healthcare providers to enhance product offerings and expand reach.

Leading companies are investing heavily in R&D to refine artificial intelligence capabilities, improve battery life, and develop more intuitive control systems. Customization is another key competitive factor, with companies offering modular designs that cater to individual user preferences. Some are integrating augmented reality (AR) and virtual reality (VR) capabilities to support therapeutic applications and interactive training.

Customer service and after-sales support are critical in this market. As robotic wheelchairs require technical maintenance and regular software updates, companies that offer robust support services enjoy a competitive advantage. Moreover, firms that engage with advocacy groups and healthcare professionals to raise awareness and promote their products are likely to succeed in building brand loyalty.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/robotic-wheelchair-market

Top Companies

Several top companies are driving innovation in the robotic wheelchair market, shaping the industry with groundbreaking technologies and user-focused designs. These include both long-standing manufacturers of mobility aids and newer entrants specializing in robotics and artificial intelligence. These companies have successfully leveraged cross-disciplinary expertise to develop highly functional and user-friendly robotic wheelchairs.

These leaders invest in comprehensive R&D programs and collaborate with universities, research institutes, and healthcare organizations to pilot new solutions. Their products often set the benchmark for safety, usability, and efficiency in the market. Additionally, these companies are committed to inclusivity, striving to make their devices accessible to a wide range of users through various pricing models and financing options.

By maintaining a strong global presence and adapting their offerings to local market needs, these top companies continue to dominate and expand the robotic wheelchair market. Their emphasis on continuous improvement and customer engagement ensures that they remain at the forefront of the industry.

Segmentation Outlook

The robotic wheelchair market can be segmented based on product type, technology, end user, and application. Product segments include indoor and outdoor robotic wheelchairs, with many models now offering hybrid capabilities. Indoor variants focus on compact design and maneuverability, while outdoor models are built for durability and terrain adaptability.

Technology-based segmentation includes autonomous navigation, voice-controlled systems, and AI-powered learning interfaces. These technologies cater to users with varying levels of mobility and cognitive function, ensuring personalized and effective assistance.

End users include individuals in home-care settings, hospitals, rehabilitation centers, and assisted living facilities. The home care segment is gaining traction due to a growing preference for independent living among elderly and disabled individuals. Hospitals and rehabilitation centers, on the other hand, utilize robotic wheelchairs to support patient mobility during treatment and recovery.

Application segmentation includes use by the elderly, people with chronic disabilities, and temporary users recovering from surgery or injury. As awareness and demand increase, tailored solutions for each user group are likely to emerge, further diversifying the robotic wheelchair market and expanding its reach.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube