Automated Suturing Devices Market to USD 7.1 Billion by 2035

The automated suturing devices market is evolving rapidly as healthcare professionals increasingly seek advanced tools to improve surgical outcomes and reduce operation times. Automated suturing devices are mechanical or robotic systems designed to perform suturing with precision, consistency, and reduced manual effort. These devices are widely used in minimally invasive surgeries, open surgeries, and other specialized procedures, offering significant advantages in terms of speed, accuracy, and safety. The rising prevalence of chronic conditions and the growing demand for better healthcare infrastructure are fueling the expansion of the automated suturing devices market globally.

The integration of automation in surgical suturing enhances precision, reduces procedure time, and minimizes the risk of human error, making it an attractive option for healthcare providers worldwide. The overall market is expected to be worth around USD 3.6 Billion in 2025 and is projected to grow at a CAGR of 6.9%, achieving a market value of USD 7.1 Billion by 2035.

Automated suturing devices reduce the need for manual suturing, which can often be time-consuming and subject to human error. Surgeons benefit from the consistent stitch quality, better wound closure, and shorter recovery times for patients. These advantages are especially crucial in high-risk or complex surgeries where accuracy is paramount. Additionally, healthcare systems are under pressure to increase procedural efficiency while maintaining high standards of care, making the automated suturing devices market increasingly attractive to hospitals and surgical centers.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-579

Technological advancements have been instrumental in the development of new devices that are smaller, more efficient, and easier to operate. The integration of robotics and AI with automated suturing systems has further enhanced their usability in both laparoscopic and traditional surgeries. This has led to an increased adoption rate and a broader application scope, supporting the ongoing growth of the automated suturing devices market.

Market Trends

Several notable trends are shaping the automated suturing devices market, reflecting the dynamic nature of the healthcare sector and the increasing sophistication of surgical technologies. One major trend is the rising preference for minimally invasive surgical procedures. Patients and healthcare providers are leaning toward less invasive techniques due to benefits such as faster recovery, reduced post-operative pain, and lower risk of infection. Automated suturing devices play a crucial role in enabling these procedures by offering precise and consistent suturing in restricted spaces.

Another significant trend is the development of smart suturing systems integrated with digital interfaces and robotic components. These innovations allow for greater control during procedures and enable real-time feedback to improve surgical precision. As robotic-assisted surgeries become more prevalent, the automated suturing devices market is expected to grow in tandem, with manufacturers focusing on developing devices compatible with robotic platforms.

There is also a growing demand for disposable and single-use automated suturing devices, especially in outpatient surgical centers and in scenarios requiring strict infection control protocols. These disposable solutions reduce the risk of cross-contamination and eliminate the need for re-sterilization, saving time and resources.

The increasing number of partnerships between medical device companies and research institutions is another trend worth noting. These collaborations aim to develop next-generation automated suturing devices that are more ergonomic, cost-effective, and tailored to specific surgical needs. As innovation continues, the automated suturing devices market is likely to become more diverse and accessible to a wider range of healthcare facilities.

Challenges and Opportunities

While the automated suturing devices market offers significant promise, it also faces several challenges that could hinder its growth. One of the main obstacles is the high cost of automated suturing devices, especially for smaller healthcare facilities or those in developing regions. The initial investment and maintenance costs can be substantial, limiting access to these advanced technologies.

Another challenge is the steep learning curve associated with the use of automated suturing systems. Surgeons and healthcare professionals require specialized training to operate these devices effectively, and the lack of standardized training programs can slow adoption. Moreover, integrating automated suturing devices with existing surgical workflows may pose logistical and compatibility issues, particularly in settings with outdated infrastructure.

Despite these hurdles, the automated suturing devices market presents numerous opportunities. The growing emphasis on surgical efficiency and patient safety is driving investment in advanced medical technologies. Governments and private sector players are increasingly funding healthcare modernization projects, creating favorable conditions for the expansion of the automated suturing devices market.

Additionally, the global rise in surgical procedures due to aging populations and increased incidence of lifestyle-related diseases offers a robust growth opportunity. With a focus on improving surgical outcomes and minimizing complications, healthcare providers are actively exploring automated solutions that deliver reliable performance. As awareness grows and technological barriers are addressed, the automated suturing devices market is poised for continued expansion.

Key Points:

  • The automated suturing devices market is driven by a combination of factors, including technological advancements, rising surgical volumes, and the demand for improved patient care. These devices enhance the speed and accuracy of suturing, reduce surgical fatigue, and promote better healing outcomes. The market benefits from ongoing innovation, with new devices being tailored for specific surgical applications such as cardiovascular, gastrointestinal, and gynecological procedures.
  • Another key point is the increased focus on minimally invasive and robotic-assisted surgeries, where automated suturing devices serve as essential tools. With growing acceptance among surgeons and positive patient outcomes, the automated suturing devices market is becoming a vital component of modern surgical practices.

Key Regional Insights

The automated suturing devices market is experiencing growth across multiple regions, each contributing uniquely to the overall expansion. North America remains a leading market, driven by advanced healthcare infrastructure, strong R&D investments, and high adoption of innovative medical technologies. The United States, in particular, is at the forefront due to the presence of major industry players and supportive regulatory frameworks.

Europe follows closely, with countries such as Germany, France, and the UK showcasing strong demand for automated suturing devices. The region benefits from a well-established healthcare system, government support for medical innovation, and increasing awareness about minimally invasive surgical techniques.

The Asia-Pacific region is emerging as a rapidly growing market, propelled by a large patient population, rising healthcare spending, and increasing medical tourism. Countries like China, India, and Japan are investing in healthcare modernization, which includes the adoption of advanced surgical tools such as automated suturing devices.

Latin America, the Middle East, and Africa are gradually recognizing the value of automated suturing devices, with expanding private healthcare sectors and growing investments in hospital infrastructure supporting market growth. As awareness increases and economic conditions improve, these regions are expected to contribute more significantly to the global automated suturing devices market.

Competitive Outlook

The competitive landscape of the automated suturing devices market features a mix of established medical device companies and emerging startups. Leading players are focusing on product innovation, strategic partnerships, and geographical expansion to strengthen their market position. The competition is intensifying as companies race to develop more intuitive, cost-effective, and high-performance suturing solutions.

Research and development are at the core of competitive strategies, with firms investing heavily in technology to gain a competitive edge. There is a strong emphasis on enhancing usability, improving precision, and integrating devices with broader surgical systems. Companies are also leveraging digital marketing and training initiatives to educate surgeons and drive product adoption.

Mergers and acquisitions are common in the automated suturing devices market, enabling firms to diversify their portfolios and enter new markets. Competitive success depends on the ability to innovate while maintaining affordability and regulatory compliance, particularly in price-sensitive markets.

Top Companies

Several top companies dominate the automated suturing devices market, recognized for their technological leadership, global presence, and commitment to quality. These companies have built strong brand reputations and maintain an edge through continuous innovation and customer support.

These key players are constantly developing new models to address the evolving needs of surgeons and healthcare providers. They also invest in training programs, post-sales service, and clinical research to build customer loyalty and support regulatory approvals. The presence of robust supply chains and strong distribution networks gives these companies an advantage in maintaining market share and expanding into emerging regions.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/automated-suturing-devices-market

Segmentation Outlook

The automated suturing devices market can be segmented based on product type, application, end-user, and region. In terms of product type, the market includes reusable and disposable automated suturing devices. Disposable devices are gaining popularity due to their convenience and infection control benefits.

Based on application, the automated suturing devices market serves general surgery, orthopedic surgery, cardiovascular surgery, and others. General surgery currently holds a substantial share, but demand is rising across all segments due to increasing surgical volumes and the adoption of minimally invasive techniques.

End-users of automated suturing devices include hospitals, ambulatory surgical centers, and specialty clinics. Hospitals remain the primary users due to their capacity for high-volume surgeries and access to advanced technologies. However, ambulatory surgical centers are increasingly adopting automated suturing devices to enhance efficiency and meet growing patient demands.

Understanding market segmentation enables manufacturers and healthcare providers to align their strategies, deliver targeted solutions, and maximize patient outcomes. As innovation continues and demand grows, the automated suturing devices market is expected to play an increasingly vital role in the global healthcare landscape.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Pharmacovigilance Market Set for Strong Growth, Rising from USD 7.4B in 2024 to USD 20.9B by 2035

The global market for pharmacovigilance is forecasted to attain USD 9,000.0 million by 2025, expanding at 8.8% CAGR to reach USD 20,902.9 million by 2035. In 2024, the revenue of pharmacovigilance was around USD 7,400.0 million

The pharmacovigilance market plays a critical role in modern healthcare by ensuring the ongoing safety, efficacy, and monitoring of pharmaceutical products. Pharmacovigilance, also referred to as drug safety, involves the collection, detection, assessment, monitoring, and prevention of adverse effects associated with medications. As the global pharmaceutical landscape continues to grow, so does the need for robust pharmacovigilance systems that safeguard patient health and help pharmaceutical companies remain compliant with increasingly stringent regulatory frameworks.

With the approval of new drugs and biologics expanding at an unprecedented pace, pharmaceutical manufacturers must demonstrate not only clinical efficacy but also long-term safety. This has significantly elevated the demand for services and systems dedicated to pharmacovigilance. From post-marketing surveillance to risk management planning, the pharmacovigilance market is central to ensuring that drug-related risks are appropriately identified, evaluated, and mitigated.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1107

Government regulations, international standards, and public health interests are driving the widespread adoption of pharmacovigilance practices. Regulatory bodies such as the FDA, EMA, and WHO require companies to implement rigorous drug safety measures, making the pharmacovigilance market a vital component of drug development and lifecycle management.

Size & Trends

The pharmacovigilance market has experienced strong and consistent growth over the last decade. As the global pharmaceutical and biotechnology industries expand, the volume of clinical trials and newly launched products continues to increase. Each new drug requires comprehensive safety monitoring throughout its life, significantly fueling demand for pharmacovigilance services.

A notable trend in the pharmacovigilance market is the growing adoption of outsourcing models. Many pharmaceutical companies, especially small to mid-sized firms, are choosing to partner with contract research organizations (CROs) and specialized service providers to manage their pharmacovigilance responsibilities. Outsourcing helps reduce operational costs while ensuring regulatory compliance and access to specialized expertise.

Technology integration is also shaping the pharmacovigilance market. Artificial intelligence, machine learning, and big data analytics are being used to automate adverse event detection, streamline data processing, and improve the accuracy of risk assessments. These tools allow organizations to handle large volumes of real-world data efficiently and are setting a new standard for pharmacovigilance operations.

Another trend is the increasing use of real-world evidence (RWE) in pharmacovigilance. Real-world data gathered from electronic health records, insurance claims, patient registries, and wearable devices is being used to supplement clinical trial findings, providing more comprehensive insights into drug safety profiles. This shift toward data-driven pharmacovigilance is improving early detection of safety signals and enhancing post-marketing surveillance.

Challenges and Opportunities

Despite the robust growth of the pharmacovigilance market, several challenges continue to shape its trajectory. One of the primary obstacles is the complexity and variability of global regulatory environments. Each region has its own set of requirements, timelines, and reporting procedures, making compliance a demanding and resource-intensive task for multinational companies.

Another challenge is data management. The pharmacovigilance market deals with an overwhelming amount of safety data, ranging from clinical trial information to post-marketing reports. Ensuring data integrity, consistency, and confidentiality requires sophisticated systems and well-trained personnel, which can be costly and time-consuming to maintain.

Additionally, there is a growing need for skilled pharmacovigilance professionals who understand global regulations, medical terminology, and data analytics. The talent gap in this field can limit the ability of organizations to scale their operations effectively.

However, these challenges also open doors to significant opportunities. Emerging markets are investing heavily in building regulatory capacity and pharmacovigilance infrastructure, creating new demand for services and technologies. The expansion of generic and biosimilar drugs, which require rigorous post-marketing surveillance, presents another growth opportunity for the pharmacovigilance market.

There is also considerable scope for innovation in technology-driven solutions. Companies that develop user-friendly, compliant, and scalable pharmacovigilance platforms can gain a competitive edge. As the importance of patient safety continues to rise, the pharmacovigilance market will benefit from increased funding, regulatory support, and industry collaboration.

Key Benefits for Stakeholders

The pharmacovigilance market offers wide-ranging benefits for stakeholders across the pharmaceutical and healthcare sectors. For pharmaceutical companies, robust pharmacovigilance systems are essential for regulatory compliance and risk mitigation. By monitoring adverse events and ensuring patient safety, companies can avoid costly recalls, litigation, and damage to brand reputation.

Regulatory authorities benefit from a well-functioning pharmacovigilance market by gaining access to reliable safety data that informs policy decisions and public health guidelines. With timely and accurate reporting, regulators can take appropriate actions to protect public health, such as updating drug labels or issuing safety warnings.

Healthcare providers rely on pharmacovigilance systems to make informed decisions about prescribing and managing medications. Access to up-to-date safety information enables physicians and pharmacists to reduce the risk of adverse drug reactions and improve treatment outcomes for their patients.

Patients are perhaps the most important beneficiaries of the pharmacovigilance market. As the primary users of pharmaceutical products, patients gain from the reduced risk of harm, enhanced drug transparency, and improved therapeutic outcomes that result from effective pharmacovigilance practices.

Market Share by Geographical Region

The pharmacovigilance market exhibits regional variation, with North America leading in terms of market share. The United States, with its robust regulatory framework and extensive pharmaceutical R&D activities, dominates the regional landscape. The presence of major pharmaceutical companies and advanced healthcare systems contributes to high adoption rates of pharmacovigilance services and technologies.

Europe is another significant market, driven by stringent safety regulations enforced by the European Medicines Agency (EMA). Countries like Germany, the UK, and France are key contributors to the region’s market size. Europe also plays a pivotal role in shaping international pharmacovigilance standards and promoting cross-border collaboration.

The Asia-Pacific region is experiencing the fastest growth in the pharmacovigilance market. Expanding pharmaceutical manufacturing, rising investments in healthcare infrastructure, and increasing participation in global clinical trials are fueling demand in countries such as China, India, Japan, and South Korea. Regulatory authorities in the region are also enhancing their pharmacovigilance frameworks to align with international standards.

Latin America and the Middle East & Africa are emerging regions in the pharmacovigilance market. Although currently smaller in market share, these areas are witnessing gradual adoption of drug safety practices. Improvements in regulatory oversight and healthcare access are expected to drive future growth in these regions.

Competitive Outlook

The pharmacovigilance market is highly competitive, with a mix of global players, mid-sized firms, and specialized service providers. Companies compete on several fronts, including technological innovation, regulatory expertise, service quality, and geographic coverage.

Large contract research organizations (CROs) and life sciences consultancies often dominate the market due to their comprehensive service offerings and established relationships with pharmaceutical companies. These firms are expanding their pharmacovigilance capabilities through acquisitions, strategic partnerships, and investment in digital tools.

Specialized pharmacovigilance vendors are also gaining prominence by offering niche services such as signal detection, literature screening, and benefit-risk assessment. These companies leverage deep domain expertise and customized solutions to attract clients looking for tailored services.

Technology providers are playing an increasingly important role in the pharmacovigilance market by offering cloud-based platforms, automation tools, and analytics solutions. These innovations help streamline workflows, reduce manual errors, and improve regulatory compliance, giving companies a competitive edge in a data-intensive market.

Top Companies

Several companies lead the pharmacovigilance market with strong portfolios, global reach, and proven track records in drug safety management. These include major CROs, life sciences consultancies, and software vendors that offer end-to-end pharmacovigilance solutions. These top players are recognized for their ability to handle complex safety requirements across all phases of the drug lifecycle.

Their services typically include case processing, signal detection, risk management, regulatory reporting, and medical writing. Many of these firms also provide proprietary platforms that integrate seamlessly with clinical and regulatory systems, offering clients greater efficiency and control.

These top companies maintain their leadership through continuous innovation, client-centric services, and strategic global expansion. Their focus on training, scalability, and adherence to global standards ensures they remain key players in the evolving pharmacovigilance market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/pharmacovigilance-market

Segmentation Outlook

The pharmacovigilance market can be segmented based on service type, clinical phase, end-user, and region. By service type, the market includes spontaneous reporting, expedited reporting, electronic health record mining, and targeted spontaneous reporting. Among these, spontaneous reporting remains the most commonly used method for collecting post-marketing data.

In terms of clinical phase, pharmacovigilance is applicable across preclinical, Phase I-IV, and post-marketing surveillance. Post-marketing pharmacovigilance dominates the segment, as most adverse drug reactions are identified after the product has been commercialized and used by a broader population.

End-users of pharmacovigilance services include pharmaceutical and biotechnology companies, medical device firms, and regulatory authorities. Pharmaceutical companies are the largest consumers, outsourcing a significant portion of their pharmacovigilance needs to third-party service providers.

Regional segmentation highlights North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Each region presents unique opportunities and challenges based on its regulatory environment, healthcare infrastructure, and industry maturity.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
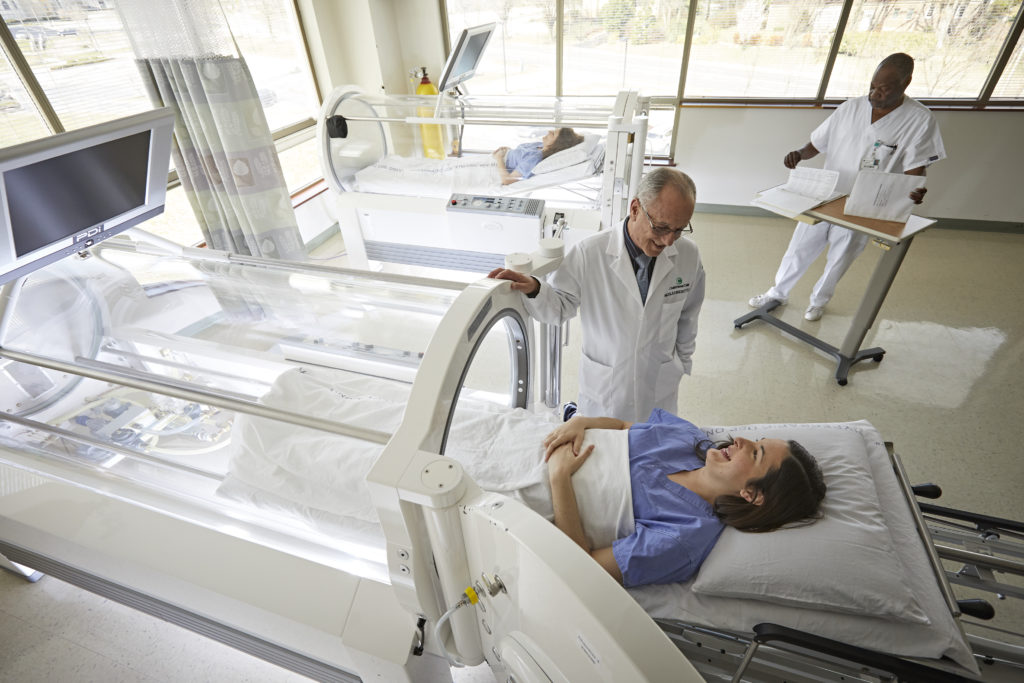
Hyperbaric Oxygen Therapy Devices Market Generates USD 3.59 Billion in 2024, Set to Surpass USD 6.35 Billion by 2035

In the coming years, the hyperbaric oxygen therapy devices product market is expected to reach USD 3,827.6 million by 2025 and steadily grow at a CAGR of 5.2% to reach USD 6,352.4 million by 2035. In 2024, hyperbaric oxygen therapy devices generated roughly USD 3,590.0 million in revenues.

The hyperbaric oxygen therapy devices market is rapidly gaining traction due to its increasing application in wound care, decompression sickness, carbon monoxide poisoning, and various chronic conditions. These devices are designed to deliver pure oxygen in a pressurized chamber, enabling patients to breathe at levels higher than atmospheric pressure. This enhanced oxygen intake supports the body in healing and fighting infections more efficiently.

The hyperbaric oxygen therapy devices market is driven by the rising prevalence of chronic diseases and growing awareness of advanced wound care solutions. The use of these devices has expanded beyond traditional diving-related conditions to include diabetic foot ulcers, radiation injuries, and certain infections. With continuous research demonstrating the efficacy of hyperbaric oxygen therapy in multiple medical scenarios, demand is steadily increasing.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1099

As healthcare providers strive to improve patient outcomes while reducing the duration of hospital stays, the hyperbaric oxygen therapy devices market has positioned itself as a valuable component of modern medical treatment. Furthermore, the integration of advanced monitoring and control systems into these devices is pushing the market toward higher adoption rates across healthcare facilities worldwide.

Market Trends

The hyperbaric oxygen therapy devices market is evolving with several noteworthy trends shaping its future. One of the major trends is the increasing incorporation of artificial intelligence and automation in hyperbaric chambers. This helps monitor patient vitals, control pressure and oxygen levels, and ensure safety protocols are followed efficiently.

Another prominent trend is the shift toward portable and monoplace chambers. These devices offer greater flexibility and can be installed in smaller clinics, ambulatory surgical centers, and even homecare settings. This decentralization of hyperbaric therapy makes it more accessible and convenient for a broader patient base.

The hyperbaric oxygen therapy devices market is also experiencing growth in cosmetic and wellness applications. Clinics are offering oxygen therapy for anti-aging, skin rejuvenation, and fatigue recovery. Although these uses are still under investigation for efficacy, the demand for wellness solutions is fueling market expansion.

Furthermore, there is a noticeable uptick in clinical trials and studies exploring the benefits of hyperbaric therapy in treating neurological conditions, including stroke and traumatic brain injury. The outcomes of these studies could potentially open new avenues and boost acceptance in previously untapped medical fields.

Driving Forces Behind Market Growth

Several factors are contributing to the robust expansion of the hyperbaric oxygen therapy devices market. A significant driver is the increasing global burden of chronic wounds, especially diabetic foot ulcers. As diabetes rates surge globally, the need for effective wound care solutions grows, and hyperbaric oxygen therapy has shown to accelerate healing.

The rising number of sports injuries and trauma cases is another contributor. Hyperbaric oxygen therapy helps in faster tissue recovery, making it a preferred choice among athletes and rehabilitation centers. This increasing use in sports medicine is helping to diversify the market base.

Another key driving force is the expanding healthcare infrastructure in emerging economies. Governments are investing in advanced treatment modalities to improve patient care and outcomes, paving the way for the integration of hyperbaric chambers in public and private healthcare institutions.

Moreover, favorable reimbursement policies in developed countries are making therapy more accessible to patients, encouraging its adoption in mainstream medicine. Continuous technological advancements and product innovation are also reducing the size and cost of devices, increasing their affordability and usability.

Challenges and Opportunities

Despite the positive outlook, the hyperbaric oxygen therapy devices market faces certain challenges. One of the primary obstacles is the high cost associated with the installation and maintenance of these systems. Many smaller clinics may find it difficult to afford such equipment without external financial support or insurance coverage.

There is also a lack of awareness among both patients and healthcare providers regarding the full range of conditions that hyperbaric oxygen therapy can treat. Misconceptions about the therapy and insufficient training among medical personnel can hinder adoption rates.

In terms of regulatory hurdles, obtaining approvals for new applications of hyperbaric oxygen therapy can be a lengthy and complex process. This can delay product launches and slow innovation in certain regions.

However, these challenges also present unique opportunities. Manufacturers that focus on cost-effective and compact device designs can tap into the growing demand in rural and underdeveloped areas. Increasing public and professional awareness campaigns can educate the market and foster wider acceptance.

Furthermore, strategic partnerships between manufacturers and healthcare organizations can boost clinical training programs and improve accessibility. The growing interest in alternative and adjunctive therapies in integrative medicine also offers new market possibilities.

Regional Analysis

The hyperbaric oxygen therapy devices market demonstrates distinct regional trends based on healthcare infrastructure, disease prevalence, and economic development. North America remains the leading market, primarily due to a high incidence of chronic wounds, strong reimbursement frameworks, and advanced medical technologies. The United States accounts for a significant share, supported by favorable policies and extensive clinical research on hyperbaric therapies.

Europe holds the second-largest share, with countries like Germany, France, and the UK investing heavily in wound care and rehabilitation services. The presence of well-established medical device companies and increasing public healthcare funding are key factors supporting growth in the region.

Asia-Pacific is emerging as a highly promising market due to its large diabetic population and expanding healthcare access. Countries like China, India, and Japan are witnessing increased investment in advanced medical equipment and technology. The hyperbaric oxygen therapy devices market in this region is expected to grow rapidly due to rising medical tourism and government support for infrastructure development.

Latin America and the Middle East & Africa are gradually embracing hyperbaric therapy. While these regions face challenges like limited access to high-end medical facilities and affordability issues, they are expected to benefit from increasing awareness and investments in modern healthcare solutions.

Competitive Outlook

The hyperbaric oxygen therapy devices market is highly competitive, with several global and regional players striving for market share through innovation, strategic alliances, and product differentiation. Companies are focusing on research and development to improve the functionality, safety, and affordability of their products.

Mergers and acquisitions are common strategies used by key players to expand their geographical presence and enhance their technological capabilities. In addition, collaborations with hospitals and clinics allow manufacturers to demonstrate the clinical value of their products and improve market penetration.

The competitive landscape is also characterized by the introduction of patient-friendly designs, such as quiet operation, ergonomic interiors, and user-friendly interfaces. These features enhance patient comfort and satisfaction, helping brands stand out in the hyperbaric oxygen therapy devices market.

Moreover, companies are investing in after-sales support and training programs for healthcare professionals to ensure optimal usage and maintenance of the equipment. This holistic approach not only improves the user experience but also builds brand loyalty in a competitive market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/hyperbaric-oxygen-therapy-devices-market

Top Companies

The hyperbaric oxygen therapy devices market is dominated by a handful of established medical technology companies known for their commitment to innovation and quality. These top companies offer a wide range of monoplace and multiplace chambers, along with supporting equipment and software for monitoring and safety.

Many of these companies have a global distribution network and strong partnerships with hospitals, research institutions, and healthcare organizations. Their focus on R&D allows them to stay ahead of emerging clinical trends and technological advancements, ensuring they remain leaders in the field.

In addition to product development, these top firms are involved in educating medical professionals, supporting clinical studies, and lobbying for favorable regulatory policies. Their comprehensive involvement in the ecosystem plays a key role in advancing the hyperbaric oxygen therapy devices market.

Segmentation Outlook

By Product:

  • Mono-place HBOT Devices
  • Multi-place HBOT Devices
  • Topical HBOT Devices

By Application:

  • Wound Healing
  • Decompression Sickness
  • Infections
  • Gas Embolism
  • Others

By End User:

  • Hospitals
  • Ambulatory Surgical Centers
  • Specialty Clinics
  • Other End User

By Region:

  • North America
  • Latin America
  • Western Europe
  • Eastern Europe
  • East Asia
  • South Asia and Pacific
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analystsworldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Neurointerventional Device Market Forecast USD 2.82 Billion in 2025 to USD 4.48 Billion by 2035

The neurointerventional device market plays a vital role in the management and treatment of various neurological disorders, particularly those involving vascular abnormalities such as aneurysms, strokes, and arteriovenous malformations. These devices, which include stents, coils, embolic agents, thrombectomy devices, and catheters, are essential tools used by neurointerventionalists to perform minimally invasive procedures within the brain’s vasculature. The growing prevalence of neurological disorders, advances in medical technology, and rising awareness about minimally invasive treatment options have significantly contributed to the expansion of the neurointerventional device market.

In the coming years, the neurointerventional device market is expected to reach USD 2,824.2 million by 2025 and is expected to steadily grow at a CAGR of 4.7% to reach USD 4,477.6 million by 2035. In 2024, Neurointerventional Device have generated roughly USD 2,699.9 million in revenues.

Neurointerventional devices offer patients a less invasive alternative to traditional surgical methods, reducing recovery times and improving clinical outcomes. This market is a crucial segment within the broader medical devices industry, intersecting neurology, interventional radiology, and neurosurgery. Ongoing research and innovation continue to drive the development of sophisticated neurointerventional devices aimed at enhancing precision, safety, and efficacy in treating complex neurological conditions.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-871

Market Trends

The neurointerventional device market is witnessing dynamic trends shaped by technological innovations and evolving clinical needs. One significant trend is the increasing adoption of advanced thrombectomy devices designed for the rapid removal of blood clots in acute ischemic stroke cases. These devices have transformed stroke treatment paradigms, significantly improving patient survival and recovery outcomes.

Another notable trend is the growing use of flow diversion devices for the treatment of complex cerebral aneurysms. These devices allow for the redirection of blood flow away from the aneurysm sac, reducing rupture risk and promoting vessel healing. The development of bioresorbable materials and enhanced polymer coatings has further improved the safety and performance of neurointerventional devices.

Digitization and integration of imaging technologies also play a pivotal role in this market. Real-time imaging guidance systems paired with neurointerventional devices enable greater precision during procedures, minimizing complications. Moreover, there is an increasing trend towards personalized medicine, with devices tailored to individual patient anatomies and conditions.

Finally, the market is seeing a shift towards hybrid procedures combining neurointerventional techniques with traditional surgery to optimize outcomes. These trends collectively enhance the overall effectiveness of neurointerventional therapies and stimulate market growth.

Driving Forces Behind Market Growth

Several key factors drive growth in the neurointerventional device market. First and foremost, the rising incidence of neurological disorders, especially stroke, is a primary driver. Stroke remains one of the leading causes of death and disability worldwide, and the need for timely intervention has emphasized the importance of effective neurointerventional devices.

Technological advancements contribute substantially to market expansion. Innovations such as smaller, more flexible catheters, improved embolic materials, and enhanced visualization tools have made procedures safer and more effective. These improvements encourage greater adoption of neurointerventional techniques across healthcare providers.

Increased government initiatives and funding aimed at neurological research and stroke awareness programs have also supported market growth. Furthermore, expanding healthcare infrastructure, especially in emerging economies, provides new opportunities for the deployment of neurointerventional devices.

Another driving force is the growing preference for minimally invasive procedures among patients and clinicians due to their benefits, including shorter hospital stays, reduced pain, and quicker recoveries. As the medical community continues to embrace these devices for their efficacy and safety, the neurointerventional device market is expected to witness sustained growth.

Challenges and Opportunities

Despite promising growth prospects, the neurointerventional device market faces challenges that could impact its trajectory. One major challenge is the high cost associated with neurointerventional procedures and devices. These costs can limit accessibility, especially in low- and middle-income countries, hindering market penetration.

Regulatory complexities also pose hurdles. The neurointerventional device market is heavily regulated to ensure patient safety and device efficacy, which can lead to prolonged approval processes and increased development expenses for manufacturers. Additionally, a lack of skilled neurointerventionalists in certain regions limits the adoption of advanced devices.

However, these challenges also present unique opportunities. Manufacturers who invest in cost-effective device development and robust clinical training programs can tap into underserved markets. The growing emphasis on stroke treatment in developing countries opens avenues for expanding market reach.

Moreover, continuous innovation offers opportunities to improve device design and usability, enhancing patient outcomes and clinician satisfaction. Partnerships between healthcare providers and device manufacturers for training and education can help overcome skill shortages. Emerging technologies such as artificial intelligence and robotics are poised to revolutionize neurointerventional procedures, creating fresh growth prospects.

Regional Analysis

The neurointerventional device market exhibits varied growth patterns across different regions due to factors like healthcare infrastructure, disease prevalence, and economic conditions. North America currently holds a dominant position in the market, attributed to advanced healthcare systems, high awareness levels, and the presence of leading device manufacturers. The United States, in particular, benefits from substantial investments in neurological research and innovation.

Europe is another significant market, supported by a strong healthcare infrastructure and increasing adoption of minimally invasive neurointerventional techniques. Countries like Germany, France, and the UK are investing heavily in improving stroke care and neurological disorder management, driving demand for advanced neurointerventional devices.

The Asia-Pacific region represents the fastest-growing market, fueled by rising incidences of stroke and other neurological diseases, expanding healthcare access, and growing awareness. Countries such as China, India, and Japan are witnessing increased adoption of neurointerventional procedures due to improved healthcare infrastructure and government initiatives focused on neurological health.

Other regions, including Latin America and the Middle East & Africa, are gradually gaining traction. Efforts to enhance neurological care and expanding healthcare spending create new opportunities, though market penetration remains relatively low compared to developed regions.

Competitive Outlook

The competitive landscape of the neurointerventional device market is characterized by intense rivalry among major multinational corporations and emerging innovative companies. Key players focus on continuous research and development to launch advanced products that meet evolving clinical needs.

Companies are increasingly engaging in strategic collaborations, mergers, and acquisitions to expand their product portfolios and geographical reach. This consolidation trend helps firms leverage complementary strengths and accelerate innovation.

Product differentiation through technological innovation is a key competitive strategy. Firms invest heavily in developing devices that offer enhanced precision, reduced complication rates, and ease of use. Additionally, expanding clinical trials and gaining regulatory approvals are essential to maintain competitive advantage.

Competitive pricing, strong distribution networks, and robust after-sales support also influence market positioning. Companies that can balance innovation with cost efficiency tend to secure larger market shares.

Furthermore, collaborations with hospitals and research institutions foster product validation and endorsement, bolstering company reputations and market influence.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/neurointerventional-devices-market

Top Companies

Leading companies in the neurointerventional device market include renowned medical device manufacturers with a strong global presence. These firms are known for their extensive product portfolios encompassing coils, stents, catheters, embolic agents, and thrombectomy devices.

These companies continuously invest in research and development to introduce next-generation neurointerventional devices aimed at improving clinical outcomes. Their focus extends beyond product innovation to include training programs for healthcare professionals, enhancing procedural success rates.

Their global distribution channels and regulatory expertise enable rapid product launches and penetration into emerging markets. These top companies often engage in strategic partnerships and acquisitions to consolidate their market position and expand their technology offerings.

By maintaining a patient-centric approach and embracing sustainability, these industry leaders are shaping the future of the neurointerventional device market.

Segmentation Outlook

The neurointerventional device market can be segmented based on device type, application, end-user, and geography. Device types include coils, stents, thrombectomy devices, embolic agents, and catheters. Among these, coils and stents hold significant shares due to their widespread use in aneurysm and stenosis treatments.

Applications primarily include ischemic stroke, hemorrhagic stroke, cerebral aneurysms, arteriovenous malformations, and other cerebrovascular disorders. Ischemic stroke treatment commands the largest segment, driven by the urgent need for clot removal and revascularization.

End-users consist of hospitals, ambulatory surgical centers, and specialty clinics. Hospitals remain the largest end-user segment due to the availability of advanced neurointerventional suites and highly skilled specialists.

Geographically, segmentation includes North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, each demonstrating distinct market dynamics as previously discussed.

Understanding these segments helps manufacturers tailor their strategies to specific clinical needs, regional demands, and user preferences, fostering better market penetration and growth.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Companion Animal Drugs Market Set for Robust Growth with 6.2% CAGR Through 2034

The companion animal drugs market is estimated to reach USD 16,131.2 million in 2024. It is estimated that revenue will increase at a CAGR of 6.2% between 2024 and 2034. The industry is anticipated to reach USD 29,329.2 million by 2034. The respiratory inhaler devices market is a critical component of the global healthcare industry, focusing on devices designed to deliver medication directly to the lungs to treat respiratory diseases such as asthma, chronic obstructive pulmonary disease (COPD), and other chronic respiratory conditions. These devices include metered-dose inhalers (MDIs), dry powder inhalers (DPIs), soft mist inhalers (SMIs), and nebulizers, all aimed at improving drug delivery efficiency and patient compliance.

Respiratory inhaler devices play an indispensable role in managing respiratory disorders by ensuring rapid and targeted drug delivery, which can significantly improve patient outcomes. The market has been expanding steadily, driven by the increasing prevalence of respiratory diseases worldwide and advancements in inhaler technology. Innovations that enhance ease of use, dose accuracy, and portability are shaping the future of the respiratory inhaler devices market.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1077

The healthcare community continues to emphasize respiratory disease management due to rising air pollution, smoking rates, and aging populations, all of which contribute to the growing incidence of lung-related ailments. The market’s evolution is closely aligned with patient-centric care models, focusing on improving quality of life through better therapeutic delivery systems.

Size & Trends

The size of the respiratory inhaler devices market has witnessed substantial growth over recent years and is expected to continue its upward trajectory. The market is influenced by the increasing burden of respiratory diseases globally, with asthma and COPD accounting for a significant share of respiratory-related morbidity and mortality. Patients diagnosed with these conditions require consistent and effective medication delivery, fueling demand for advanced inhaler devices.

Trends within the market highlight a shift towards more technologically advanced inhalers, such as breath-actuated devices that synchronize medication release with patient inhalation, thereby reducing drug wastage and improving treatment efficacy. Additionally, digital inhalers equipped with sensors and connectivity features are becoming popular, enabling real-time monitoring of inhaler use and enhancing patient adherence to prescribed regimens.

Environmental concerns also drive innovation, with a push towards propellant-free devices like dry powder inhalers, which have a lower carbon footprint compared to traditional metered-dose inhalers. This sustainability trend resonates with both healthcare providers and patients, encouraging manufacturers to invest in eco-friendly alternatives.

Moreover, the trend of personalized medicine influences the development of inhaler devices that can be tailored to specific patient needs, taking into account factors such as age, disease severity, and inhalation technique. This patient-centric approach is becoming a standard in the respiratory inhaler devices market.

Challenges and Opportunities

While the respiratory inhaler devices market is growing rapidly, it faces several challenges that could impact its progress. One of the primary challenges is the complexity involved in the correct usage of inhalers. Many patients, especially the elderly and children, struggle with the coordination required to effectively use certain types of inhalers, which can result in suboptimal drug delivery and poor disease control.

Another challenge is regulatory compliance, which varies across different countries. Manufacturers must adhere to strict safety and efficacy standards, which can increase production costs and delay product launches. Furthermore, the market faces intense competition from generic drug manufacturers, which pressure pricing and profitability for branded respiratory inhaler devices.

Despite these challenges, the market offers significant opportunities. The rising prevalence of respiratory diseases worldwide, driven by urbanization, pollution, and lifestyle changes, continues to create strong demand for effective inhaler devices. Emerging economies present untapped markets where improving healthcare infrastructure and increasing awareness about respiratory health are driving adoption.

Technological advancements also open new avenues. Integration of smart technologies in inhalers, such as dose counters, Bluetooth connectivity, and mobile health applications, creates opportunities for better disease management and patient engagement. These innovations can reduce hospital readmissions and improve treatment adherence, benefiting both healthcare providers and patients.

Collaborations between pharmaceutical companies and technology firms can accelerate the development of next-generation inhalers, combining medication expertise with digital health innovations. Such partnerships represent a promising area for growth within the respiratory inhaler devices market.

Key Benefits for Stakeholders

Stakeholders across the respiratory inhaler devices market—including patients, healthcare providers, manufacturers, and payers—benefit from the advances and expansion of this sector. Patients experience improved treatment outcomes through efficient drug delivery, ease of use, and devices designed to fit their lifestyle and health needs. Enhanced adherence to medication regimens reduces exacerbations and hospitalizations, leading to a better quality of life.

Healthcare providers gain tools that allow for more effective management of chronic respiratory conditions. Advanced inhaler devices with monitoring capabilities enable physicians to track patient usage remotely and adjust treatment plans as necessary, facilitating personalized care. This data-driven approach enhances clinical decision-making and patient engagement.

Manufacturers benefit by tapping into a growing market with high demand for innovation and quality. The introduction of smart inhalers and eco-friendly devices enables companies to differentiate themselves and build brand loyalty. The expanding global market also provides opportunities to enter new geographic regions and demographic segments.

Payers, including insurance companies and government healthcare programs, benefit from reduced healthcare costs due to fewer hospital visits and complications arising from poorly managed respiratory diseases. Efficient inhaler devices contribute to cost-effective healthcare delivery by improving disease control and patient outcomes.

Market Share by Geographical Region

The respiratory inhaler devices market exhibits notable regional variation, influenced by healthcare infrastructure, disease prevalence, regulatory environments, and economic development. North America holds a significant share of the market, driven by a high prevalence of respiratory diseases, advanced healthcare systems, and widespread awareness about asthma and COPD management. The presence of key market players and strong reimbursement policies further reinforce North America’s dominance.

Europe also represents a substantial portion of the market, with countries investing heavily in healthcare infrastructure and emphasizing innovation in medical devices. The region’s regulatory landscape promotes safety and efficacy while encouraging green technologies, influencing product development trends in the respiratory inhaler devices market.

Asia-Pacific is the fastest-growing region due to increasing urbanization, rising pollution levels, and growing patient awareness. Emerging economies within the region are expanding healthcare access, leading to higher adoption of respiratory inhaler devices. The increasing burden of respiratory diseases in countries such as China and India fuels demand for cost-effective and advanced inhalers.

Latin America and the Middle East & Africa regions are gradually expanding their market presence. Improvements in healthcare infrastructure, increasing prevalence of chronic respiratory diseases, and government initiatives to promote respiratory health contribute to market growth in these areas.

Competitive Outlook

The respiratory inhaler devices market is highly competitive, featuring a mix of multinational pharmaceutical companies, specialized medical device manufacturers, and innovative startups. Competition revolves around product innovation, technological advancement, pricing strategies, and regulatory compliance.

Key players are investing in research and development to introduce novel inhaler devices with improved drug delivery mechanisms, patient-friendly designs, and digital health integration. The emphasis on environmental sustainability is driving companies to develop propellant-free inhalers and other green technologies to reduce carbon emissions.

Strategic collaborations and partnerships are common within the market, with pharmaceutical companies teaming up with tech firms to develop smart inhalers that provide real-time usage data to patients and healthcare providers. This trend enhances product portfolios and creates competitive differentiation.

Mergers and acquisitions are also shaping the market landscape, allowing companies to expand their geographic footprint and product offerings. Smaller players focusing on niche respiratory devices or specific patient demographics remain vital, driving innovation from the grassroots level.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/companion-animal-drug-market

Top Companies

  • Zydus Life Sciences (Zenex Animal Health Pvt. Ltd.)
  • Ceva Santé Companion Animal
  • Virbac SA
  • Vetoquinol S.A.
  • Hester Biosciences Limited
  • Dechra Pharmaceuticals PLC
  • Ayurvet
  • Vetpharma
  • Shennong Animal Health
  • Intas Pharmaceuticals Ltd.
  • Alivira Animal Health Limited

Segmentation Outlook

By Product Type:

  • In terms of product type, the industry is segregated into anti-infective agents (antibiotics & antimicrobials, anti-fungal, anti-viral), anti-inflammatory & analgesic agents (non-steroidal anti-inflammatory drugs (NSAIDs), corticosteroids, opioids, other), parasiticides (endo-parasiticides, ecto-parasiticides, endectocides), vaccines, hormones & substitutes, nutritional products, other products.

By Animal Type:

  • In terms of animal type, the industry is segregated into cats, dogs, horse, rabbits, birds and other animals

By Route of Administration:

  • In terms of route of administration, the industry is segregated into oral route (tablets/capsules, liquids, powders/premix, other oral route), parenteral route (liquids, powder for injection), topical route, (solutions, creams & ointments), others

By Disease Indication:

  • In terms of disease indication, the industry is segregated into allergy, infectious disease, diabetes, oncology, osteoarthritis, metabolic diseases, cardiac diseases, reproductive disorders, and other indications

By Distribution Channel:

  • In terms of distribution channel, the industry is segregated into institutional sales (veterinary hospitals, veterinary clinics), retail sales (retail pharmacies, drug stores, online pharmacies, hypermarket and supermarkets, and pet shops)

By Region:

  • Key countries of North America, Latin America, East Asia, South Asia & Pacific, Western Europe, Eastern Europe, and Middle East & Africa have been covered in the report.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Respiratory Inhaler Devices Market Set for Steady Growth with 4.5% CAGR to 2035

The respiratory inhaler devices market is a critical component of the global healthcare industry, focusing on devices designed to deliver medication directly to the lungs to treat respiratory diseases such as asthma, chronic obstructive pulmonary disease (COPD), and other chronic respiratory conditions. These devices include metered-dose inhalers (MDIs), dry powder inhalers (DPIs), soft mist inhalers (SMIs), and nebulizers, all aimed at improving drug delivery efficiency and patient compliance.

The rising pollution levels mainly propel the market, the growing number of smokers, and the aging population suffering from lung diseases. Additionally, developments in inhaler technology, such as digital-tracking smart inhalers, are making treatment more convenient and efficient. It is projected to grow at a compound annual growth rate (CAGR) of 4.5% by 2025, reaching USD 40.99 billion, and is expected to reach USD 63.66 billion by 2035.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-493

Respiratory inhaler devices play an indispensable role in managing respiratory disorders by ensuring rapid and targeted drug delivery, which can significantly improve patient outcomes. The market has been expanding steadily, driven by the increasing prevalence of respiratory diseases worldwide and advancements in inhaler technology. Innovations that enhance ease of use, dose accuracy, and portability are shaping the future of the respiratory inhaler devices market.

The healthcare community continues to emphasize respiratory disease management due to rising air pollution, smoking rates, and aging populations, all of which contribute to the growing incidence of lung-related ailments. The market’s evolution is closely aligned with patient-centric care models, focusing on improving quality of life through better therapeutic delivery systems.

Size & Trends

The size of the respiratory inhaler devices market has witnessed substantial growth over recent years and is expected to continue its upward trajectory. The market is influenced by the increasing burden of respiratory diseases globally, with asthma and COPD accounting for a significant share of respiratory-related morbidity and mortality. Patients diagnosed with these conditions require consistent and effective medication delivery, fueling demand for advanced inhaler devices.

Trends within the market highlight a shift towards more technologically advanced inhalers, such as breath-actuated devices that synchronize medication release with patient inhalation, thereby reducing drug wastage and improving treatment efficacy. Additionally, digital inhalers equipped with sensors and connectivity features are becoming popular, enabling real-time monitoring of inhaler use and enhancing patient adherence to prescribed regimens.

Environmental concerns also drive innovation, with a push towards propellant-free devices like dry powder inhalers, which have a lower carbon footprint compared to traditional metered-dose inhalers. This sustainability trend resonates with both healthcare providers and patients, encouraging manufacturers to invest in eco-friendly alternatives.

Moreover, the trend of personalized medicine influences the development of inhaler devices that can be tailored to specific patient needs, taking into account factors such as age, disease severity, and inhalation technique. This patient-centric approach is becoming a standard in the respiratory inhaler devices market.

Challenges and Opportunities

While the respiratory inhaler devices market is growing rapidly, it faces several challenges that could impact its progress. One of the primary challenges is the complexity involved in the correct usage of inhalers. Many patients, especially the elderly and children, struggle with the coordination required to effectively use certain types of inhalers, which can result in suboptimal drug delivery and poor disease control.

Another challenge is regulatory compliance, which varies across different countries. Manufacturers must adhere to strict safety and efficacy standards, which can increase production costs and delay product launches. Furthermore, the market faces intense competition from generic drug manufacturers, which pressure pricing and profitability for branded respiratory inhaler devices.

Despite these challenges, the market offers significant opportunities. The rising prevalence of respiratory diseases worldwide, driven by urbanization, pollution, and lifestyle changes, continues to create strong demand for effective inhaler devices. Emerging economies present untapped markets where improving healthcare infrastructure and increasing awareness about respiratory health are driving adoption.

Technological advancements also open new avenues. Integration of smart technologies in inhalers, such as dose counters, Bluetooth connectivity, and mobile health applications, creates opportunities for better disease management and patient engagement. These innovations can reduce hospital readmissions and improve treatment adherence, benefiting both healthcare providers and patients.

Collaborations between pharmaceutical companies and technology firms can accelerate the development of next-generation inhalers, combining medication expertise with digital health innovations. Such partnerships represent a promising area for growth within the respiratory inhaler devices market.

Key Benefits for Stakeholders

Stakeholders across the respiratory inhaler devices market—including patients, healthcare providers, manufacturers, and payers—benefit from the advances and expansion of this sector. Patients experience improved treatment outcomes through efficient drug delivery, ease of use, and devices designed to fit their lifestyle and health needs. Enhanced adherence to medication regimens reduces exacerbations and hospitalizations, leading to a better quality of life.

Healthcare providers gain tools that allow for more effective management of chronic respiratory conditions. Advanced inhaler devices with monitoring capabilities enable physicians to track patient usage remotely and adjust treatment plans as necessary, facilitating personalized care. This data-driven approach enhances clinical decision-making and patient engagement.

Manufacturers benefit by tapping into a growing market with high demand for innovation and quality. The introduction of smart inhalers and eco-friendly devices enables companies to differentiate themselves and build brand loyalty. The expanding global market also provides opportunities to enter new geographic regions and demographic segments.

Payers, including insurance companies and government healthcare programs, benefit from reduced healthcare costs due to fewer hospital visits and complications arising from poorly managed respiratory diseases. Efficient inhaler devices contribute to cost-effective healthcare delivery by improving disease control and patient outcomes.

Market Share by Geographical Region

The respiratory inhaler devices market exhibits notable regional variation, influenced by healthcare infrastructure, disease prevalence, regulatory environments, and economic development. North America holds a significant share of the market, driven by a high prevalence of respiratory diseases, advanced healthcare systems, and widespread awareness about asthma and COPD management. The presence of key market players and strong reimbursement policies further reinforce North America’s dominance.

Europe also represents a substantial portion of the market, with countries investing heavily in healthcare infrastructure and emphasizing innovation in medical devices. The region’s regulatory landscape promotes safety and efficacy while encouraging green technologies, influencing product development trends in the respiratory inhaler devices market.

Asia-Pacific is the fastest-growing region due to increasing urbanization, rising pollution levels, and growing patient awareness. Emerging economies within the region are expanding healthcare access, leading to higher adoption of respiratory inhaler devices. The increasing burden of respiratory diseases in countries such as China and India fuels demand for cost-effective and advanced inhalers.

Latin America and the Middle East & Africa regions are gradually expanding their market presence. Improvements in healthcare infrastructure, increasing prevalence of chronic respiratory diseases, and government initiatives to promote respiratory health contribute to market growth in these areas.

Competitive Outlook

The respiratory inhaler devices market is highly competitive, featuring a mix of multinational pharmaceutical companies, specialized medical device manufacturers, and innovative startups. Competition revolves around product innovation, technological advancement, pricing strategies, and regulatory compliance.

Key players are investing in research and development to introduce novel inhaler devices with improved drug delivery mechanisms, patient-friendly designs, and digital health integration. The emphasis on environmental sustainability is driving companies to develop propellant-free inhalers and other green technologies to reduce carbon emissions.

Strategic collaborations and partnerships are common within the market, with pharmaceutical companies teaming up with tech firms to develop smart inhalers that provide real-time usage data to patients and healthcare providers. This trend enhances product portfolios and creates competitive differentiation.

Mergers and acquisitions are also shaping the market landscape, allowing companies to expand their geographic footprint and product offerings. Smaller players focusing on niche respiratory devices or specific patient demographics remain vital, driving innovation from the grassroots level.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/respiratory-inhaler-devices-market

Top Companies

Leading companies in the respiratory inhaler devices market include established pharmaceutical giants and specialized medical device manufacturers. These companies have a strong global presence, extensive product portfolios, and significant investments in research and development.

These top companies continuously innovate to improve inhaler technologies, focusing on ease of use, drug delivery efficiency, and patient adherence. Their products are available across diverse therapeutic segments, targeting asthma, COPD, and other respiratory conditions.

They also lead in adopting sustainable manufacturing practices, contributing to the development of eco-friendly inhalers. Their ability to navigate complex regulatory environments and establish strong distribution networks strengthens their competitive position in the respiratory inhaler devices market.

Through strategic partnerships, these companies enhance their technological capabilities and expand into emerging markets, ensuring continued growth and market leadership.

Segmentation Outlook

The respiratory inhaler devices market can be segmented based on device type, application, end-user, and distribution channel. Device types include metered-dose inhalers (MDIs), dry powder inhalers (DPIs), soft mist inhalers (SMIs), and nebulizers. MDIs remain widely used due to their portability and ease of use, while DPIs are gaining traction because of their eco-friendly features and breath-actuated mechanisms.

Applications primarily focus on treating respiratory conditions such as asthma, chronic obstructive pulmonary disease (COPD), bronchitis, and other chronic respiratory diseases. Asthma management represents a significant share, given the widespread prevalence and increasing awareness about the disease.

End-users encompass hospitals, clinics, ambulatory care centers, and homecare settings. The homecare segment is growing as patients prefer self-management and remote monitoring options for chronic conditions.

Distribution channels include pharmacies, hospital pharmacies, online sales, and specialty stores. The rise of e-commerce and online pharmacies has made respiratory inhaler devices more accessible to patients worldwide, facilitating timely delivery and better patient compliance.

This segmentation provides a comprehensive understanding of the market dynamics, helping manufacturers and stakeholders target their strategies effectively to maximize growth in the respiratory inhaler devices market.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Global Artificial Ventilation and Anaesthesia Masks Market Set for Robust Growth, Forecast to Reach USD 3.9 Billion by 2032 | FMI

The global market for artificial ventilation and anaesthesia masks was valued at approximately USD 2.4 billion in 2022 and is projected to grow significantly, reaching an estimated value of USD 3.9 billion by the end of 2032. This growth, driven by increasing global healthcare expenditure, is expected to follow a compound annual growth rate (CAGR) of 5.0% from 2022 to 2032. As medical technology continues to advance and demand for critical care increases worldwide, artificial ventilation and anaesthesia masks are set to play an essential role in ensuring safe and effective patient care across a variety of healthcare settings.

Market Growth & Driving Factors

The artificial ventilation and anaesthesia masks market is expanding rapidly due to several critical factors. Increasing incidences of respiratory diseases, rising healthcare awareness, and the need for better patient care options in critical medical procedures are some of the key drivers for this market growth. As hospitals, emergency care centers, and home care settings continue to rely heavily on mechanical ventilation and anaesthesia during surgeries and intensive care, the demand for these masks is expected to rise.

Get Ahead of Market Shifts: Request Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15790

Further fueling this growth is the accelerating healthcare expenditure worldwide. As countries increase their investments in healthcare infrastructure and services, the adoption of advanced medical devices like artificial ventilation and anaesthesia masks is becoming more widespread. Additionally, with the COVID-19 pandemic highlighting the importance of respiratory support devices, the market for ventilation-related products has seen a surge.

Key Takeaways: The USA, China, and Japan Artificial Ventilation and Anaesthesia Masks Market

  • USA Market:
    • The U.S. holds the largest market share for Artificial Ventilation and Anaesthesia Masks, projected to reach a valuation of USD 1.4 billion by 2032.
    • The market grew at a CAGR of 4.8% from 2017 to 2021 and is expected to see a USD 509.3 million absolute dollar opportunity from 2022 to 2032.
    • Key drivers include the high rate of ICU admissions (5 million annually) and the rising prevalence of chronic sleep disorders, leading to increased demand for ventilation equipment and anaesthesia masks.
    • The Affordable Care Act further boosts market growth by encouraging more patients to seek surgical treatments.
  • China Market:
    • China’s market is still in its early stages but is projected to reach USD 280.4 million by 2032, with a CAGR of 4.3% from 2017 to 2021.
    • The country is expected to have a USD 96.8 million absolute dollar opportunity between 2022 and 2032.
    • The aging population in China, expected to reach 198 million by 2025, is a key factor driving the market.
    • China played a significant role during the pandemic, exporting 16,000 artificial ventilators and anaesthesia masks in a single month.
    • Leading players include Getinge AB, Dragerwerk AG & Co KGaA, Nihon Kohden Corp, and Hamilton Medical AG.
  • Japan Market:
    • Japan’s market is anticipated to experience a CAGR of 3.4% over the next decade, with an absolute dollar opportunity of USD 64.8 million.
    • The market is expected to reach a valuation of USD 226.1 million by 2032.
    • Growth is driven by Japan’s aging population and its high standards of healthcare, which increase demand for advanced ventilation equipment.

These insights highlight the growing demand for artificial ventilation and anaesthesia masks across these regions, driven by aging populations, healthcare reforms, and advancements in medical technologies.

Enhanced Market Demand: Discover Thorough Trends and Insights in Our Complete Report! https://www.futuremarketinsights.com/reports/artificial-ventilation-and-anaesthesia-masks-market

Competitive Landscape

The artificial ventilation and anaesthesia masks market remains moderately competitive, with several key players leading the charge in terms of market share and innovation. Major companies are increasingly focusing on collaboration, partnerships, and research & development (R&D) to stay ahead in the market. These companies are introducing innovative solutions to meet the growing demand for efficient, comfortable, and reliable ventilation and anaesthesia masks.

Key Players in the Market Include:

  • CareFusion Corporation
  • Air Liquide Healthcare
  • Koninklijke Philips N.V.
  • Fisher and Paykel Healthcare
  • ResMed
  • Ambu A/S
  • Acutronic Medical Systems
  • GaleMed
  • HOFFRICHTER GmbH
  • Dragerwerk SA

These companies are leveraging advanced technologies, expanding their product portfolios, and enhancing their customer service to strengthen their market positions. Strategic acquisitions and partnerships are also helping them to broaden their global reach and improve their product offerings.

Recent Developments in the Market:

  • In November 2020, Besmed launched the FitMax CPAP Face Mask, a new anaesthetic gas mask designed for patients who find full-face or nasal masks uncomfortable. This innovation aims to offer better comfort and fit for patients undergoing respiratory therapy.
  • In April 2020, Nihon Kohden Group announced that its NKV-550 series ventilator was approved for production and sale in Japan. This series, introduced in 2019, is now being sold across the globe, providing a highly advanced and reliable ventilation solution for hospitals worldwide.

Market Segmentation

The artificial ventilation and anaesthesia masks market is segmented based on various applications, patient risk levels, and geographical regions. Understanding these segments helps in identifying the key areas driving demand and allows for targeted marketing strategies to be implemented.

By Application:

  1. Operation Room: Masks are used extensively in surgical settings to ensure safe anaesthesia delivery and respiratory support during operations.
  2. Intensive Care Unit (ICU): The ICU segment holds significant demand for artificial ventilation masks due to the critical care requirements of patients requiring mechanical ventilation.
  3. Emergency Room: The emergency room segment is seeing rising demand for ventilators and anaesthesia masks due to emergencies requiring immediate intervention.
  4. Dental: Dental surgeries, particularly those requiring anaesthesia, are driving the demand for smaller, specialized anaesthesia masks.
  5. Home Care: With the rise in at-home care for patients with respiratory issues or who need continued ventilation, there is an increasing demand for home-use ventilation and anaesthesia masks.

By Risk of the Procedure:

  1. High-Risk Patients: For patients undergoing high-risk procedures or suffering from severe respiratory conditions, masks that offer advanced functionality and comfort are essential.
  2. Moderate-Risk Patients: Masks for moderate-risk patients are designed to balance effectiveness and comfort during procedures that carry less immediate danger.
  3. Standard Patients: Standard masks are used in routine medical procedures, catering to patients undergoing general anaesthesia or ventilation.

By Region:

  1. North America: The North American market holds a significant share of the global market due to the advanced healthcare infrastructure and the increasing demand for ventilatory support devices in hospitals and home care settings.
  2. Europe: Europe is experiencing steady growth in the artificial ventilation and anaesthesia masks market, driven by increasing healthcare investments, a rise in surgeries, and the growing geriatric population.
  3. Asia-Pacific (APAC): APAC is expected to witness the highest growth rate over the forecast period. Rapid urbanization, improving healthcare infrastructure, and rising respiratory disease prevalence in countries like China, India, and Japan contribute to this growth.
  4. Middle East and Africa (MEA): The MEA region is gradually adopting more advanced medical equipment, with increasing investments in healthcare infrastructure and government initiatives aimed at improving patient care.
  5. Latin America: Latin America shows a growing need for artificial ventilation and anaesthesia masks, especially in countries with improving healthcare systems and rising awareness of respiratory conditions.

Conclusion

The global artificial ventilation and anaesthesia masks market is on a steady upward trajectory, driven by the increasing demand for respiratory support in hospitals, emergency settings, and home care. As technological advancements continue to improve the comfort and efficiency of these products, the market is expected to witness substantial growth, reaching an estimated USD 3.9 billion by 2032.

The competitive landscape remains dynamic, with key players investing heavily in research and development and launching innovative products to meet the needs of a diverse patient population. With the continued rise in healthcare expenditure, the artificial ventilation and anaesthesia masks market is set for a promising future, ensuring enhanced care for patients worldwide.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Global Scleral Lenses Market Set for Robust Growth: Projected to Reach USD 323.5 Million by 2032 with a CAGR of 6.3% | FMI

The global market for scleral lenses is witnessing a significant upswing, with a projected compound annual growth rate (CAGR) of 6.3% over the next decade. According to a recent report by Future Market Insights, the market is set to grow from a valuation of USD 175.5 million in 2022 to approximately USD 323.5 million by 2032, driven by increasing demand for advanced and comfortable vision correction solutions.

Scleral lenses—large-diameter, gas-permeable lenses—are specifically designed to cover the entire corneal surface and rest on the sclera (the white part of the eye), offering enhanced stability and comfort for wearers. Unlike traditional contact lenses, scleral lenses create a tear-filled vault over the cornea, making them ideal for patients with complex ocular conditions or sensitive eyes.

Stay Updated with Market Movements: Get Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-10247

Rising Preference for Mini Scleral Lenses

Among the various product categories, mini scleral lenses emerged as the dominant segment in 2021, accounting for approximately 47.4% of the global market share. Their relatively smaller size makes them easier to fit and more comfortable for daily use while still offering the advantages of standard scleral lenses, such as oxygen permeability and exceptional tear exchange.

These lenses are particularly useful in managing ocular conditions like keratoconus, pellucid marginal degeneration, neurotrophic keratitis, microphthalmia, and dry eye syndrome, along with corneal scarring and other irregularities. As awareness of scleral lenses as a treatment modality grows, both older adults and younger patients are increasingly opting for them, especially those with intolerance to traditional lenses.

Key Takeaways:

USA: Dominating the Scleral Lenses Market in North America

The USA leads the North American scleral lenses market with a revenue of about USD 69.09 million, driven by the increasing prevalence of eye disorders such as keratoconus. With an estimated 50 to 200 cases per 100,000 people, the demand for scleral lenses continues to grow, ensuring a strong market outlook.

Germany: A Technologically Advanced and Lucrative Market

In Europe, Germany holds a significant market share of 44.7% as of 2021. The country’s market growth is propelled by advancements in eye care technology, including improved lens design, topography measurements, and high-tech materials. These innovations have led to broader adoption of scleral lenses in Germany, making it a key player in the market.

India: Rapid Growth in South Asia

India accounted for 59.8% of the South Asian scleral lenses market in 2021 and is poised for rapid growth. This is attributed to advancements in medical technology, government support for eye care, and a growing patient base due to the rising population and increasing eye diseases. The market in India is expected to expand significantly over the forecast period.

Mini Scleral Lenses: Key Growth Driver

Mini scleral lenses are expected to grow at a CAGR of 4.9%, contributing around USD 79.2 million to the global market in 2021. These lenses, known for their safety, comfort, and effectiveness in treating corneal irregularities, are gaining popularity and contributing to the market’s overall growth.

Corneal Irregularities: The Leading Indication for Scleral Lenses

Corneal irregularities, including conditions like keratoconus and pellucid marginal degeneration, are the primary indications addressed by scleral lenses. With an estimated global market value of USD 82.2 million in 2021, the treatment of corneal irregularities remains the most common application for scleral lenses, driving the demand in the global market.

High Demand for Market Insights: Discover Comprehensive Trends in Our Full Report! https://www.futuremarketinsights.com/reports/scleral-lenses-market

Competitive Landscape: Mergers, Collaborations & Expansions

Key players in the scleral lenses market are actively pursuing strategic initiatives such as mergers and acquisitions, partnerships, product innovations, and geographic expansions to strengthen their foothold in the global market. Companies are leveraging R&D capabilities and digital technologies to optimize lens design and meet the specific needs of patients with complex eye conditions.

Technological Innovations Driving Market Growth

One of the key factors propelling the scleral lenses market is the influx of technological innovations aimed at enhancing lens performance, fitting accuracy, and wearer comfort.

  • In December 2021, BostonSight introduced its Smart360™ design software, revolutionizing the customization of scleral lenses through precise data-driven lens creation.
  • In November 2021, CooperVision Specialty EyeCare announced improved pupil optics for its Onefit™ MED and MED+ scleral lenses, offering better visual acuity and comfort.

These innovations reflect a broader industry trend toward customized, patient-centric solutions, which are becoming central to competitive strategies in the ophthalmic devices space.

Notable companies in the global scleral lenses market include:

  • CooperVision
  • Bausch & Lomb
  • Visionary Optic (Euclid Systems)
  • Art Optical Contact Lens, Inc.
  • AccuLens
  • Valley Contax Inc.
  • ABB Optical Group
  • EssilorLuxottica
  • Solotica
  • Optact International Ltd.
  • Smart Optics LLC
  • Gelflex
  • Biolens Lab
  • Metro Optics, among others.

These companies are not only introducing cutting-edge technologies but are also expanding access through better distribution channels and specialized practitioner training.

Segmental Overview

By Product Type:

  • Mini Scleral Lenses
  • Semi Scleral Lenses
  • Large Scleral Lenses

Mini scleral lenses dominate due to ease of adaptation and widespread clinical application. However, other segments are also showing promising growth as demand diversifies.

By Indication:

  • Corneal Irregularity
  • Surface Ocular Disease
  • Refractive Error
  • Other Indications

The use of scleral lenses for corneal irregularities remains the largest application area, but increasing cases of dry eye disease and complex post-surgical eye conditions are creating new growth avenues.

By Region:

  • North America continues to lead the market due to advanced healthcare infrastructure, high awareness, and early technology adoption.
  • Europe follows closely, driven by rising prevalence of keratoconus and supportive reimbursement policies.
  • East Asia, South Asia, Latin America, Oceania, and MEA are emerging as high-potential markets due to improving healthcare access and increasing diagnosis of vision disorders.

Future Outlook

The future of the scleral lenses market looks promising, bolstered by:

  • Increased prevalence of ocular surface diseases.
  • Growing geriatric population with specific vision care needs.
  • Expanding application in pediatric ophthalmology.
  • Greater customization through digital eye imaging and AI-based lens fitting.
  • Improved practitioner training and awareness campaigns.

In addition, advancements in 3D printing, hybrid lens materials, and tele-optometry are poised to reshape the landscape of specialty contact lenses, making scleral lenses more accessible and effective for a broader patient base.

Conclusion

As the demand for specialized, high-comfort vision correction grows, the global scleral lenses market is positioned for sustained expansion. With mini scleral lenses leading the charge and innovation driving adoption across diverse demographic groups, key stakeholders—including manufacturers, eye care professionals, and investors—have a significant opportunity to capitalize on this growing sector.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Global High Potency API Contract Manufacturing Market Set to Double by 2032, Driven by Surge in Oncology Demand and Precision Medicine | FMI

The global high potency API contract manufacturing market, valued at USD 8 billion in 2022, is poised for robust growth, with projections to reach USD 16 billion by 2032. This remarkable expansion, driven by a CAGR of 7% during the forecast period from 2022 to 2032, reflects the rising global demand for HPAPIs, particularly due to the increasing prevalence of cancer worldwide and the growing need for precision medicine.

Surge in Cancer Incidences Fuels HPAPI Market Growth

Cancer cases have been on a sharp rise globally, with the International Agency for Research on Cancer (IARC) estimating that there would be 19.3 million cancer cases and 10 million cancer-related deaths in 2020 alone. According to updated projections, more than 50 million individuals will be diagnosed with cancer within the next five years. As a result, the utilization of HPAPIs in the treatment of cancer has gained significant traction, making HPAPI production a vital area of focus for pharmaceutical companies.

Discover Market Shifts: Secure Your Sample Report Now! https://www.futuremarketinsights.com/reports/sample/rep-gb-15786

HPAPIs, which are compounds with high biological activity that are used in the development of various treatments, are critical in combating some of the most severe diseases, including cancer. The rising cancer burden and the growing need for targeted therapies are key factors driving the demand for high-potency APIs, accelerating the market’s growth trajectory.

Government Support Boosts HPAPI Research and Development

Another factor contributing to the growing demand for HPAPI contract manufacturing is the increased governmental support for therapeutic substance development. Numerous government initiatives are focusing on enhancing the infrastructure and capabilities for drug discovery and manufacturing, particularly for high-potency drugs. These initiatives aim to support the development of innovative cancer therapies and other life-threatening conditions, further fueling the HPAPI market.

The high investment required for the manufacturing and production of HPAPIs has made contract manufacturing an attractive alternative for pharmaceutical companies. By outsourcing their HPAPI production, companies can significantly reduce capital expenditures and leverage the expertise of established contract manufacturing organizations (CMOs) that are equipped with specialized facilities designed to handle highly potent substances.

Patent Expirations Open New Opportunities

The expiration of patents for several blockbuster drugs is set to unlock new growth opportunities in the HPAPI contract manufacturing market. As patented medications lose their exclusivity, pharmaceutical companies are looking to produce generic versions of these drugs. This shift has been particularly evident in the biosimilar market, where several biological drugs are nearing the end of their patent protection. For example, blockbuster drugs such as Avastin (bevacizumab), Herceptin (trastuzumab), Humira (adalimumab), and Rituxan (rituximab) are expected to lose patent protection in the coming years.

The expiration of these patents will open up significant opportunities for generic drug manufacturers to produce affordable biosimilars and for HPAPI producers to expand their offerings into this lucrative segment. With the demand for cost-effective therapeutic options on the rise, HPAPIs will play a key role in the development of biosimilars, further fueling the market’s expansion.

Outsourcing Becomes the Preferred Strategy

Pharmaceutical companies, once hesitant to outsource HPAPI production due to concerns about patent infringement and confidentiality, have increasingly turned to contract manufacturing organizations (CMOs). The high cost of developing and commercializing new medications, combined with the complexity of manufacturing HPAPIs, has led many companies to seek external partners to handle production.

Outsourcing offers several advantages, including cost savings, access to advanced technologies, and the ability to scale production quickly. Contract manufacturers with specialized facilities for handling highly potent substances provide pharmaceutical companies with the necessary expertise and infrastructure to produce high-quality HPAPIs without the burden of investing in expensive production facilities themselves. As a result, outsourcing is becoming a key strategy for pharmaceutical firms to maintain competitiveness in the rapidly evolving drug development landscape.

Technological Advancements Drive Efficiency

The increasing demand for HPAPIs has also been fueled by technological advancements in production processes. Modern advancements in biotechnology and synthetic chemistry have made it possible to manufacture highly potent APIs with greater efficiency, precision, and safety. Innovations such as continuous manufacturing processes, advanced filtration systems, and improved containment technologies have streamlined the production of HPAPIs, making it more cost-effective and scalable.

As pharmaceutical companies continue to develop more targeted therapies, the demand for more efficient HPAPI manufacturing solutions will only increase. The development of innovative production techniques is expected to be a key factor in the ongoing growth of the HPAPI contract manufacturing market.

Soaring Demand for Market Information: Uncover Detailed Trends and Insights in Our Report! https://www.futuremarketinsights.com/reports/high-potency-api-contract-manufacturing-market

Key Takeaways: High Potency API Contract Manufacturing Market Outlook

  • Asia Pacific Leads Growth Trajectory

The Asia Pacific region is anticipated to witness the fastest growth in the HPAPI contract manufacturing market. Countries like China, India, and Japan are driving expansion due to:

    • Favorable regulatory policies
    • Access to cost-effective and skilled labor
    • A robust pipeline of innovative drugs
    • Improved risk management capabilities
  • North America Remains a Major Market Player

North America is projected to command around 38% of the market share, fueled by rising prevalence of chronic conditions such as cancer and neurological diseases. The U.S., in particular, is a major hub for HPAPI production, with:

    • An aging population
    • Strong demand for oncology and neurological therapies
    • A growing need for high-precision, potent therapies
  • Oncology Dominates Application Spectrum

Oncology is expected to account for over 63% of all HPAPI contract manufacturing applications. The surge in global cancer cases and the increasing use of targeted therapies—like antibody-drug conjugates—are major contributors.

  • Injectables Take the Lead in Dosage Preference

Among dosage forms, injectables account for over 50% of global HPAPI revenues. Their popularity stems from the ability to deliver potent therapies quickly and precisely via subcutaneous, intradermal, or intramuscular routes.

Competitive Landscape

The HPAPI contract manufacturing market is highly competitive, with numerous players vying for market share. Some of the leading companies in this sector include:

  • Piramal Pharma Solutions
  • Lonza
  • Catalent, Inc.
  • VxP Pharma, Inc.
  • Pfizer CentreOne
  • Gentec Pharmaceutical Group
  • AbbVie
  • Aurigene Pharmaceutical Services Ltd.
  • CordenPharma International
  • Curia Global, Inc.

These companies are leveraging their advanced manufacturing capabilities and strategic partnerships to gain a competitive edge. For instance, in June 2021, Lonza made a significant investment of USD 21.5 billion in its Nansha, China plant to expand its API development and manufacturing capacity. This expansion includes the installation of three 1,000 L GMP trains and additional research and GMP facilities for small-scale batch production of highly potent APIs. Such developments are expected to enhance the global supply of HPAPIs and meet the growing demand for these specialized drugs.

Key Market Segments

The High Potency API Contract Manufacturing Market can be segmented based on various factors, including product type, synthesis method, application, and dosage form:

  • By Product Type: Innovative, Generic
  • By Synthesis: Synthetic, Biotech
  • By Application: Oncology, Hormonal Disorders, Glaucoma, Others
  • By Dosage Form: Injectable, Oral Solids, Creams, Others

The market is also segmented by geography, with key regions including:

  • North America
  • Latin America
  • Europe
  • Asia Pacific
  • South Asia
  • East Asia
  • Oceania
  • Middle East & Africa

Conclusion

The global High Potency API Contract Manufacturing Market is witnessing unprecedented growth, driven by a combination of rising cancer rates, increasing demand for precision medicine, technological advancements in manufacturing, and the expiration of patents for major drugs. With pharmaceutical companies increasingly turning to outsourcing as a cost-effective solution, the market for HPAPI contract manufacturing is set to double by 2032, creating new opportunities for both established players and emerging companies in this space.

As the demand for high-potency drugs continues to rise, particularly in oncology and other therapeutic areas, the contract manufacturing sector will play a crucial role in meeting the growing need for these specialized compounds. The future of the HPAPI market looks promising, with continued technological innovations and expanding global partnerships paving the way for success.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Global Laboratory Supplies Market Set to Surpass USD 81.6 Billion by 2032, Fueled by Accelerating Research and Technological Advancements | FMI

The global laboratory supplies market is poised for remarkable expansion, according to a new report from Future Market Insights (FMI). The report projects a robust Compound Annual Growth Rate (CAGR) of 8% over the next decade, forecasting a leap from the current valuation of USD 37.8 billion in 2022 to an impressive USD 81.61 billion by 2032.

This anticipated growth follows a period of substantial development between 2017 and 2021, during which the market demonstrated a notable CAGR of 6%. The consistent upward trend highlights the increasing demand and ongoing evolution within the laboratory supplies sector.

Stay Ahead with Market Trends: Access Your Sample Report Now! https://www.futuremarketinsights.com/reports/sample/rep-gb-15785

Key Drivers of Market Expansion:

  • Technological Advancements: Continuous innovations in laboratory technology are enhancing the efficiency and capabilities of laboratory supplies.
  • Increased R&D Activities: The surge in research and development efforts across various sectors is driving demand for sophisticated laboratory equipment and consumables.
  • Rising Investments in Infrastructure: Growing investments in laboratory infrastructure are contributing to the expansion of the market.

As laboratories evolve and expand their capabilities, the need for advanced and efficient laboratory supplies is expected to increase significantly.

Industry Insights:

“The laboratory supplies market is on the brink of significant transformation, propelled by advancements in technology and heightened research and development activities,” said an FMI. “Our findings indicate a strong and sustained growth pattern, underscoring the essential role of laboratory supplies in various scientific and industrial applications.”

Key Takeaways: Laboratory Supplies Market Insights

  • The USA Dominates Due to Strong R&D Infrastructure

The United States stands as the largest market for laboratory supplies, driven by substantial R&D investments from major pharmaceutical, biotech companies, and academic institutions. Notably, PhRMA reported that biopharmaceutical companies invested over USD 91 billion in R&D in 2020 alone, reinforcing the nation’s leadership in innovation and scientific research.

  • India Emerges as a High-Growth Market

India is gaining traction as a lucrative region for laboratory supplies, propelled by growing public health awareness, rising FDI in pharmaceuticals, and increased investments in healthcare. As per NITI Aayog, FDI inflows in the pharma sector rose from USD 2.5 billion in 2000–01 to USD 50 billion in 2019–20, indicating a robust growth outlook.

  • Equipment Segment Drives Market Expansion

Among product types, laboratory equipment—including centrifuges, microscopes, laminar hoods, and more—accounted for over 63.4% market share in 2021. These tools are critical for processes like drug toxicology and personalized medicine research, and their durability and role in ensuring accuracy and efficiency continue to fuel demand.

Get the Latest on Laboratory Supplies: Our Full Report Highlights Key Trends and Insights! https://www.futuremarketinsights.com/reports/laboratory-supplies-market

Market Competition:

Major players are channelling efforts toward expanding their production capacities to strengthen their market share and cater to the growing demand. Market expansion is anticipated to be aided by the growing number of partnerships and collaborations among key players that are looking to increase their presence in the market.

  • Bio-Rad Laboratories, Inc.
  • Bruker Corporation
  • Danaher Corporation
  • Fujifilm Holdings Corporation (Irvine Scientific Sales Company, Inc.).
  • Agilent Technologies Inc.
  • PerkinElmer Inc.
  • Sartorius AG
  • Shimadzu Corporation
  • Thermo Fisher Scientific, Inc.
  • Waters Corporation

Recent Development:

  • In March 2022, Precisa Gravimetrics AG introduced their Halo range of sophisticated UV-Vis spectrophotometers GB 30 under the Dynamica brand.
  • In February 2021, INTEGRA Biosciences launched the D-ONE single-channel pipetting module for hands-free transfers from individual tubes or wells using the ASSIST PLUS pipetting robot. This system effectively automates tedious tasks such as serial dilutions, sample normalization, hit picking, or pipetting of complex plate layouts, increasing productivity and reproducibility in the lab while reducing hands-on time, processing errors, and physical strain.

Key Segments Profiled in the Laboratory Supplies Market Industry Survey:

Laboratory Supplies Market By Product Type:

  • Equipment
    • Incubators
    • Laminar Flow Hood
    • Micro Manipulation Systems
    • Centrifuges
    • Lab Air Filtration System
    • Scopes
    • Sonicators And Homogenizers
    • Autoclaves And Sterilizers
    • Spectrophotometer And Microarray Equipment
    • Others
  • Disposables
    • Pipettes
    • Tips
    • Tubes
    • Cuvettes
    • Dishes
    • Gloves
    • Masks
    • Cell Imaging Consumables
    • Cell Culture Consumables

Laboratory Supplies Market By Region:

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East and Africa (MEA)

Future Outlook:

Key contributors to this growth include increased investments in healthcare infrastructure, the proliferation of research activities in life sciences, and the escalating demand for advanced laboratory instruments and consumables. As the industry continues to innovate and expand, stakeholders can expect substantial opportunities for growth and development.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube