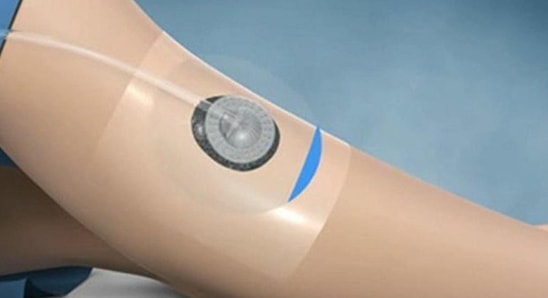
Negative Pressure Wound Therapy Market to Expand to USD 11,434.9 Million by 2035

The global negative pressure wound therapy market is expected to be reach USD 7,087.3 million in 2025 and is likely to expand up to approximately USD 11,434.9 million by the end of 2035. The sales are believed to rise with a CAGR of 4.9% during the period of 2025 to 2035.

The negative pressure wound therapy market has become an essential segment within the advanced wound care industry. Negative pressure wound therapy (NPWT) is a medical technique that uses controlled suction to promote wound healing by removing excess fluid and stimulating tissue growth. This therapy has revolutionized the way chronic, acute, and complex wounds are treated, offering an effective alternative to conventional wound dressings. The increasing prevalence of diabetic ulcers, pressure ulcers, surgical wounds, and traumatic injuries drives demand for NPWT devices globally.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-810

In healthcare settings ranging from hospitals to home care, the adoption of negative pressure wound therapy is steadily rising due to its ability to reduce healing time, minimize infection risk, and improve patient outcomes. The market reflects growing awareness among healthcare professionals about the benefits of this therapy, alongside technological advancements that make devices more user-friendly and accessible.

Market Trends

Several trends shape the current landscape of the negative pressure wound therapy market. A prominent one is the growing emphasis on portable and disposable NPWT devices. These products offer increased mobility and ease of use for patients, enabling outpatient treatment and home care without compromising effectiveness. This shift toward ambulatory care aligns with healthcare systems’ broader efforts to reduce hospital stays and lower treatment costs.

Another key trend is the integration of smart technologies into NPWT systems. Innovations like real-time monitoring, remote data transmission, and automated pressure adjustment enhance treatment precision and allow clinicians to track wound healing progress remotely. Such advancements improve patient compliance and provide valuable insights for personalized care.

Sustainability is also emerging as a consideration, with companies developing eco-friendly and recyclable components for NPWT devices. This reflects a broader healthcare trend toward reducing environmental impact while maintaining high-quality patient care.

Furthermore, collaboration between device manufacturers and healthcare providers is intensifying, leading to customized therapy solutions tailored to specific wound types and patient needs. This trend promotes better clinical outcomes and expands the range of NPWT applications.

Challenges and Opportunities

Despite the promising growth, the negative pressure wound therapy market faces several challenges. One of the foremost concerns is the high cost of NPWT devices and associated consumables. This can limit access, especially in low- and middle-income regions where healthcare budgets are constrained. Affordability remains a critical factor that manufacturers and policymakers must address to expand market penetration.

Another challenge lies in the need for specialized training for healthcare providers and patients. Effective use of NPWT requires understanding device operation, wound assessment, and maintenance protocols. Without proper training, the risk of device misuse or complications increases, potentially hindering therapy outcomes.

Regulatory hurdles also pose difficulties, as varying approval requirements across regions can slow down product launches and increase development costs. Ensuring compliance with international standards while addressing local regulatory frameworks requires careful navigation by manufacturers.

On the opportunity side, the rising prevalence of chronic wounds due to aging populations and lifestyle diseases presents a substantial growth avenue. As diabetes and obesity rates continue to climb globally, the demand for effective wound care solutions like NPWT is expected to grow correspondingly.

Expansion into emerging markets offers significant potential, driven by improving healthcare infrastructure and rising awareness. Companies that can tailor products to meet the unique needs and economic realities of these regions may capture untapped demand.

Technological advancements also create opportunities to develop hybrid therapies combining NPWT with other modalities such as growth factors, antimicrobial dressings, or cellular therapies. These integrated approaches can accelerate healing and reduce complications, appealing to clinicians seeking comprehensive solutions.

Key Points

Negative pressure wound therapy has fundamentally changed wound care by providing a mechanism that accelerates tissue regeneration and reduces infection risk. Its role is especially critical in managing chronic wounds that often resist traditional treatment methods.

Patient comfort and convenience have become central to device design, leading to smaller, quieter, and more intuitive NPWT systems. These improvements support patient adherence and satisfaction, which are crucial for therapy success.

The market also benefits from increasing collaborations between healthcare institutions, research organizations, and device manufacturers. These partnerships foster innovation and evidence-based practice, enhancing product effectiveness and acceptance.

Cost-effectiveness analyses frequently demonstrate that, despite upfront expenses, NPWT can reduce overall treatment costs by shortening hospital stays and minimizing complications. This economic argument strengthens the case for wider adoption among healthcare payers.

Key Regional Insights

Geographically, the North American region continues to dominate the negative pressure wound therapy market. This leadership stems from advanced healthcare infrastructure, well-established reimbursement policies, and strong investment in research and development. The U.S., in particular, has a large base of diabetic and elderly patients, fueling demand for NPWT products.

Europe follows closely, supported by government initiatives promoting advanced wound care and the presence of numerous medical device manufacturers. Western European countries have well-developed healthcare systems that facilitate rapid technology adoption.

The Asia-Pacific region is emerging as a key growth market due to increasing healthcare expenditure, expanding hospital networks, and rising awareness of wound care innovations. Countries like China, India, and Japan are witnessing higher NPWT adoption rates, driven by growing incidences of chronic wounds and traumatic injuries.

Latin America and the Middle East & Africa show steady growth potential despite current limitations in infrastructure and healthcare accessibility. Efforts to enhance healthcare quality and increase insurance coverage are expected to accelerate NPWT market expansion in these regions.

Competitive Outlook

The competitive landscape of the negative pressure wound therapy market is highly dynamic, featuring both established multinational corporations and innovative startups. Market leaders focus heavily on product innovation, expanding their distribution networks, and forming strategic partnerships to strengthen their presence globally.

Companies invest in research and development to enhance device features, improve patient comfort, and integrate smart technologies. Offering comprehensive service packages, including training and technical support, distinguishes leading players and fosters customer loyalty.

Pricing strategies also play a pivotal role, with some manufacturers providing affordable solutions for emerging markets while maintaining premium product lines for developed regions. Flexible financing and leasing options further enhance market accessibility.

Mergers and acquisitions remain common as companies seek to consolidate expertise and broaden their product portfolios. These activities often lead to accelerated innovation and expanded geographical reach, benefiting both manufacturers and end-users.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/negative-pressure-wound-therapy-market

Top Companies

  • 3M (KCI) (30-35%) A dominant player in the NPWT market, 3M (KCI) leads with its V.A.C. therapy system, offering clinically proven solutions for effective wound healing.
  • Smith & Nephew (20-24%) Known for its innovative PICO system, Smith & Nephew emphasizes portable, single-use NPWT devices that enhance patient comfort and mobility.
  • Mölnlycke Health Care (10-14%) A key provider of advanced wound care products, Mölnlycke integrates NPWT technology with specialized dressings for superior healing outcomes.
  • Cardinal Health (8-12%) A major supplier of NPWT devices, Cardinal Health focuses on affordability and accessibility in hospital and homecare settings.
  • ConvaTec Group (5-9%) With a strong emphasis on smart wound care technology, ConvaTec develops NPWT systems featuring pressure control and real-time wound monitoring.

Segmentation Outlook

The negative pressure wound therapy market can be segmented based on product type, end-user, and application. Product categories typically include portable NPWT systems, stationary devices, and accessories such as dressings and canisters. Portable systems are gaining traction due to their convenience and suitability for home care.

End-users cover hospitals, outpatient clinics, long-term care facilities, and home healthcare. Hospitals remain the largest consumer segment because of the critical need for advanced wound care in surgical and trauma patients. However, home care is growing rapidly as patients seek less invasive treatment options outside traditional settings.

Applications span chronic wounds like diabetic foot ulcers, pressure ulcers, and venous leg ulcers, as well as acute wounds from surgery or trauma. The therapy’s versatility allows its use across various wound types, supporting its expanding market presence.

As technology evolves, segmentation will likely incorporate device connectivity, integration with other therapeutic modalities, and data analytics capabilities, reflecting the broader digital transformation in healthcare.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Electronic Medical Record Market Valued at USD 18.82 Billion in 2024, Shows Promising Growth Prospects

Future Market Insights’ updated report on the electronic medical record ecosystem highlights various opportunities and growth spots for the coming decade. As per the analysis, the electronic medical record market is set to account for a current valuation of USD 18.82 billion in 2024.

The electronic medical record market has emerged as a vital component of modern healthcare systems. Electronic medical records (EMRs) are digital versions of patients’ paper charts, providing real-time, patient-centered records that make information available instantly and securely to authorized users. This transformation from traditional paper-based records to digital platforms is revolutionizing how healthcare providers manage patient information and deliver care. EMRs encompass a broad range of functionalities, from recording medical histories and diagnoses to managing prescriptions and lab results, thereby enhancing the efficiency and accuracy of healthcare delivery.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-387

This market’s growth reflects the increasing emphasis on improving patient outcomes through technology, regulatory pushes for digital adoption, and a rising need for streamlined healthcare operations. Healthcare organizations across the world are adopting electronic medical record systems to reduce paperwork, improve data accuracy, and facilitate better communication among healthcare professionals. These systems serve as the foundation for integrating other advanced healthcare IT solutions like telemedicine, analytics, and population health management, further driving their importance.

Size & Trends

The size of the electronic medical record market has expanded substantially in recent years and continues to show robust growth potential. This expansion is driven by widespread digitization efforts in healthcare facilities ranging from large hospitals to smaller clinics and specialty care centers. Increasing government incentives and mandates encouraging the use of EMRs have accelerated adoption rates, especially in developed economies. Additionally, emerging markets are witnessing a steady rise in demand due to growing healthcare infrastructure and digital awareness.

Among key trends, interoperability stands out as a critical focus area. Stakeholders are pushing for EMR systems that can seamlessly exchange data across different platforms and healthcare providers to ensure continuity of care. The demand for cloud-based EMR solutions is also rising, as they offer scalability, flexibility, and lower upfront costs compared to traditional on-premise software. Mobile accessibility is another trend gaining momentum, allowing healthcare providers to access patient records anytime and anywhere, improving responsiveness and care quality.

Another significant trend is the integration of artificial intelligence and machine learning into EMR systems. These technologies enhance data analysis, help predict patient risks, and automate routine documentation, reducing clinician burnout. Personalization of EMR interfaces and workflows is becoming more prevalent to meet the unique needs of different specialties and practices.

Challenges and Opportunities

Despite the rapid growth, the electronic medical record market faces several challenges. One of the primary obstacles is data privacy and security concerns. With sensitive patient information stored digitally, there is a heightened risk of cyberattacks and data breaches. Ensuring compliance with stringent healthcare regulations like HIPAA and GDPR adds complexity to EMR deployment and management. Healthcare providers must invest heavily in security measures to protect patient data and maintain trust.

Usability remains a significant challenge as well. Some EMR systems are criticized for being cumbersome, leading to clinician frustration and decreased productivity. Poorly designed interfaces can contribute to errors and reduce the quality of care. Addressing these issues requires ongoing user feedback, better design practices, and adequate training for medical staff.

Interoperability challenges also persist, as many legacy systems and newer platforms still struggle to communicate effectively. The lack of standardization can hinder data sharing, causing fragmentation in patient records and care gaps. Overcoming these barriers presents a major opportunity for vendors and healthcare providers alike.

The electronic medical record market holds vast opportunities, especially in emerging economies where digital healthcare is just gaining traction. Expanding internet penetration, government support, and increasing awareness about digital health benefits are creating fertile grounds for market growth. Additionally, integration with telehealth services, wearable devices, and remote patient monitoring can create more comprehensive health management ecosystems.

Vendors who can develop user-friendly, secure, and interoperable EMR systems stand to gain competitive advantage. Moreover, offering modular and customizable solutions that cater to specific medical specialties can open new market segments.

Key Benefits for Stakeholders

Electronic medical record systems deliver multiple benefits across the healthcare spectrum. For healthcare providers, EMRs enhance clinical efficiency by streamlining documentation and reducing redundant testing. Real-time access to patient data facilitates better clinical decisions, resulting in improved patient outcomes and safety. EMRs also simplify compliance with healthcare regulations by providing audit trails and standardized reporting.

Patients benefit from EMR adoption through better care coordination and reduced chances of medical errors. They can also enjoy greater transparency and engagement with their health data via patient portals linked to EMRs. This transparency fosters trust and encourages proactive health management.

Healthcare payers and insurers find value in EMRs as well. With better data on patient histories and treatments, insurers can make more accurate risk assessments and streamline claims processing. EMRs enable population health management programs by identifying high-risk groups and monitoring chronic diseases more effectively.

For healthcare IT vendors, the growing demand for EMR solutions presents vast commercial opportunities. Continuous innovation in software capabilities, integration, and analytics will drive long-term relationships with healthcare organizations.

Market Share by Geographical Region

The electronic medical record market displays considerable variation in adoption and growth across geographical regions. North America holds a significant share, primarily due to early digitization initiatives, supportive government policies, and advanced healthcare infrastructure. The United States leads the market with high EMR penetration in hospitals and clinics, driven by federal programs incentivizing EMR adoption.

Europe is another key region with growing EMR deployment. Countries such as the United Kingdom, Germany, and France have made substantial investments in digital health, improving healthcare quality and operational efficiencies. Variations in regulatory frameworks and healthcare systems across European countries influence the rate and nature of EMR adoption.

In the Asia-Pacific region, market growth is rapid, propelled by expanding healthcare infrastructure, increasing government initiatives, and rising healthcare awareness. Nations like China, India, and Japan are witnessing strong demand for EMR solutions, supported by growing hospital networks and a focus on improving healthcare delivery standards.

Latin America and the Middle East & Africa regions are gradually adopting electronic medical records, although at a slower pace due to infrastructural challenges and economic constraints. However, increasing healthcare investments and digital health strategies offer promising prospects for market expansion in these areas.

Competitive Outlook

The competitive landscape of the electronic medical record market is dynamic and characterized by a mix of large multinational corporations and smaller specialized firms. Market leaders focus on enhancing software capabilities, expanding product portfolios, and forming strategic partnerships to strengthen their market position.

Innovation plays a central role in competition, with companies investing in AI integration, cloud computing, and interoperability solutions. Vendors that provide comprehensive, scalable, and customizable EMR platforms tend to secure larger client bases, particularly among hospital networks and multispecialty clinics.

Customer service and training support are critical differentiators as well, given the complex nature of EMR implementation. Companies offering robust onboarding and continuous support are better positioned to maintain long-term customer relationships.

Strategic acquisitions and collaborations are frequent, enabling companies to broaden their technological capabilities and geographic reach. Competitive pricing and flexible subscription models are increasingly used to appeal to smaller healthcare providers and emerging markets.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/electronic-medical-records-market

Top Companies

Several prominent companies dominate the electronic medical record market, each bringing unique strengths to the industry. These organizations invest extensively in research and development to keep pace with evolving healthcare demands and technological trends.

Key players often boast global reach, offering integrated healthcare IT solutions beyond just EMRs, such as practice management, revenue cycle management, and patient engagement tools. Their comprehensive portfolios cater to various healthcare settings, from large hospitals to outpatient clinics.

Innovation-driven firms are carving out niches by focusing on specialized EMR solutions tailored to specific medical fields like oncology, pediatrics, or behavioral health. These specialized products address unique clinical workflows and compliance requirements, adding value for targeted user groups.

Customer-centric approaches, including personalized training programs, data migration assistance, and flexible service agreements, further differentiate top companies in this market. Many of these companies also emphasize cybersecurity, ensuring their products meet the highest data protection standards.

Segmentation Outlook

By Product Type:

  • Hospital EMR
  • Ambulatory EMR
  • By Component:
  • EMR Software
  • EMR Services

By Application:

  • Client Server Setup EMR
  • Hybrid Server Setup EMR
  • Cloud Based EMR

By End User:

  • Hospitals
  • Specialized Clinics
  • General Physician Clinics
  • Ambulatory Surgical Centers

By Region:

  • North America
  • Latin America
  • Western Europe
  • Eastern Europe
  • South Asia and Pacific
  • East Asia
  • The Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
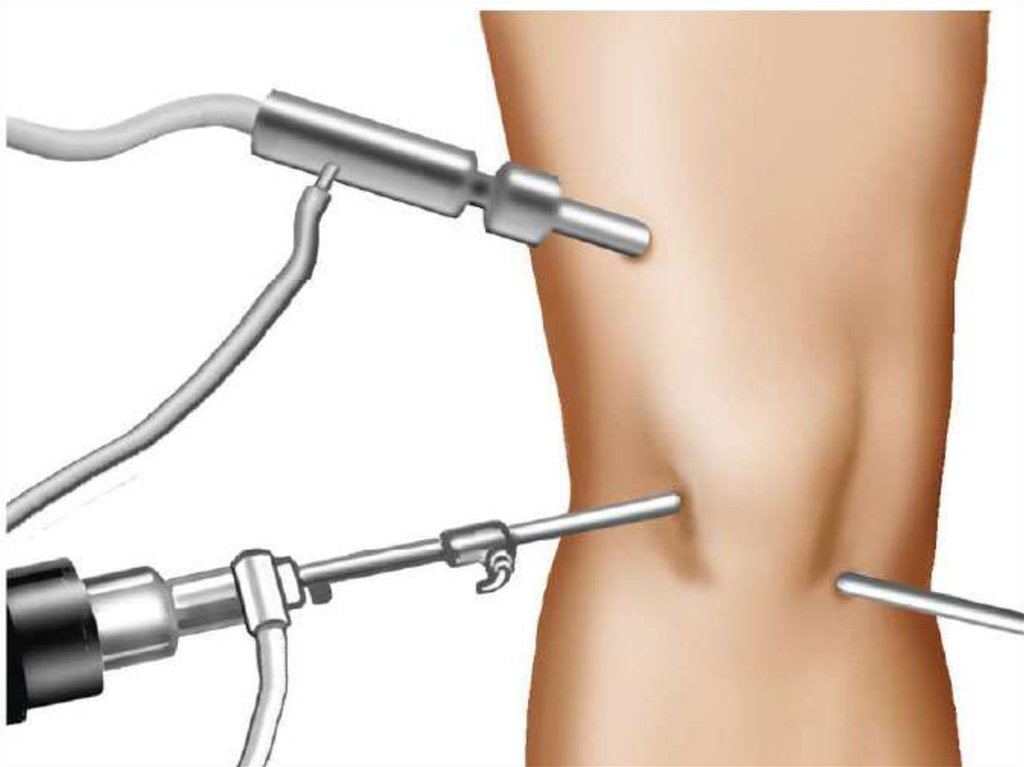
Arthroscopy Procedure and Products Market to Reach USD 12,762.2 Million by 2035, Growing at 5.4% CAGR

The arthroscopy procedure and products market has witnessed significant growth over the past decade, driven by the rising prevalence of joint-related disorders and the increasing preference for minimally invasive surgical techniques. Arthroscopy is a surgical procedure used primarily for diagnosing and treating joint problems, allowing surgeons to view, diagnose, and treat joint issues through small incisions using specialized instruments. The demand for arthroscopy procedures has surged as they offer reduced recovery times, lower risk of infection, and less postoperative pain compared to traditional open surgeries.

The global market for Arthroscopy Procedure and Products is forecasted to attain USD 7,553.0 million by 2025, expanding at 5.4% CAGR to reach USD 12,762.2 million by 2035. In 2024, the revenue of this market was around USD 7,193.9 million.

This market encompasses a wide range of products such as arthroscopes, shavers, trocars, fluid management systems, and related accessories. These products are crucial in facilitating precise joint surgeries and improving patient outcomes. As the global population ages and lifestyle-related joint injuries increase, the arthroscopy procedure and products market continues to expand, supported by technological advancements and rising patient awareness.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1386

Market Trends

One of the key trends shaping the arthroscopy procedure and products market is the continuous innovation in arthroscopic instruments and visualization technology. High-definition cameras and enhanced imaging techniques have transformed arthroscopic surgeries by providing clearer and more detailed views of the joint interior. This has improved diagnostic accuracy and allowed surgeons to perform more complex procedures arthroscopically.

Another important trend is the rising adoption of robotic-assisted arthroscopy. The integration of robotics with traditional arthroscopic systems offers increased precision, reduced surgeon fatigue, and potentially better surgical outcomes. Although still in its early stages, robotic-assisted arthroscopy is gaining traction and expected to influence market dynamics significantly.

Furthermore, there is a growing focus on patient-centric approaches in orthopedic surgeries. This includes minimally invasive techniques, faster recovery protocols, and outpatient procedures, which align well with arthroscopic surgeries. The demand for single-use disposable arthroscopic instruments is also increasing, driven by concerns over cross-contamination and infection control.

Driving Forces Behind Market Growth

The arthroscopy procedure and products market is driven primarily by the rising incidence of musculoskeletal disorders, including arthritis, ligament injuries, and cartilage damage. Sports injuries and road accidents contribute significantly to the growing need for arthroscopic interventions, especially among younger and middle-aged populations who are more active.

Increasing awareness among patients and healthcare professionals about the benefits of arthroscopy over open joint surgery is also a major growth factor. Patients prefer less invasive options that minimize downtime and reduce complications, which encourages healthcare providers to adopt arthroscopic techniques more broadly.

Technological advances in arthroscopy products continue to fuel market expansion. The development of more ergonomic, user-friendly instruments and improved fluid management systems enhances surgical efficiency and patient safety. Moreover, the rising number of orthopedic and sports medicine specialists trained in arthroscopic procedures ensures a steady demand for these products.

Healthcare infrastructure improvements and better reimbursement policies in various countries, especially in developed and emerging economies, also play a pivotal role in the market’s growth. Governments and private insurers increasingly recognize the long-term cost-effectiveness of arthroscopic procedures, further promoting their adoption.

Challenges and Opportunities

Despite its promising growth, the arthroscopy procedure and products market faces several challenges. One significant issue is the high cost associated with advanced arthroscopic equipment, which may limit accessibility in low-income regions and smaller healthcare facilities. Additionally, the requirement for highly skilled surgeons trained in arthroscopic techniques remains a barrier in some areas, potentially restricting market penetration.

The complexity of some arthroscopic procedures can also pose risks, including incomplete treatment or the need for additional surgeries. This can impact patient outcomes and influence perceptions of arthroscopy as a treatment option.

However, these challenges open up opportunities for innovation and education. Developing cost-effective arthroscopy products tailored for use in less developed regions could greatly expand market reach. Training programs and workshops to improve surgeon skills in arthroscopy are gaining importance, supported by healthcare institutions and device manufacturers alike.

There is also potential in expanding the application of arthroscopy beyond traditional joints like the knee and shoulder. Emerging uses in the wrist, ankle, and even small joints present untapped growth avenues. Research into new arthroscopic treatment methods for soft tissue repair and cartilage regeneration further enhances future market potential.

Recent Industry Developments

  • Recent developments in the arthroscopy procedure and products market highlight the focus on technological advancement and improved patient outcomes. The introduction of ultra-high-definition (UHD) arthroscopic cameras and 3D imaging systems allows surgeons to view joint structures with exceptional clarity, facilitating precise interventions.
  • Companies have also launched multifunctional arthroscopic instruments that combine several functions into a single tool, reducing surgical time and equipment costs. These innovations simplify procedures and make arthroscopy more accessible.
  • The emergence of portable and wireless arthroscopy systems represents another key trend. These systems offer flexibility and ease of use in operating rooms, especially beneficial for outpatient settings and minimally equipped hospitals.
  • Collaborations between device manufacturers and healthcare providers have increased, focusing on joint research projects and clinical trials. These partnerships accelerate the development of next-generation arthroscopy products and the validation of their clinical benefits.
  • Sustainability has also gained attention, with companies developing eco-friendly arthroscopic instruments and adopting green manufacturing practices. The push for disposable instruments is balanced with concerns over medical waste, prompting innovation in recyclable and biodegradable materials.

Regional Analysis

The arthroscopy procedure and products market in Europe is robust due to the presence of advanced healthcare infrastructure, high patient awareness, and favorable reimbursement policies. Western European countries lead the market with a high adoption rate of arthroscopic procedures supported by widespread orthopedic expertise and investments in healthcare technology.

Northern Europe has also seen growth, driven by proactive government health initiatives and growing geriatric populations requiring joint care. Southern and Eastern Europe, while currently less mature markets, are witnessing rapid growth owing to improving healthcare standards and increasing awareness.

Emerging economies in Eastern Europe present significant growth opportunities. As healthcare spending rises and access to orthopedic care improves, demand for arthroscopy products is expected to increase. However, regional disparities in regulatory environments and economic development levels mean that market strategies must be tailored accordingly.

Cross-border collaborations and the presence of multinational arthroscopy product manufacturers facilitate market penetration across Europe. Additionally, increasing medical tourism within the region contributes to the market dynamics, with patients traveling to countries with advanced arthroscopic care facilities.

Competitive Outlook

The arthroscopy procedure and products market is highly competitive, with key players focusing on product innovation, strategic partnerships, and geographic expansion. Leading companies invest heavily in research and development to maintain technological leadership and meet the evolving needs of surgeons and patients.

Competition is not limited to large multinational corporations; specialized firms with niche product portfolios also play an important role. These companies often innovate rapidly, catering to specific segments of the arthroscopy market such as single-use instruments or robotic-assisted systems.

Pricing strategies are important in maintaining competitiveness, especially as the market expands into cost-sensitive regions. Many companies emphasize value-added services like training, surgical planning, and post-procedure support to differentiate themselves.

Mergers and acquisitions continue to shape the market, enabling companies to broaden their product offerings and consolidate their market presence. Collaborations with healthcare providers and research institutions further enhance the ability to bring innovative arthroscopy solutions to market.

Top Companies

Leading players in the arthroscopy procedure and products market include a mix of established medical device giants and innovative specialists. These companies have a strong global footprint and a broad product portfolio, ranging from arthroscopes and shavers to advanced visualization and fluid management systems.

Many of the top companies emphasize continuous product development, incorporating surgeon feedback and clinical data into new designs. They also focus on expanding their sales and distribution networks to reach emerging markets while strengthening their presence in mature regions.

Partnerships with orthopedic associations and healthcare institutions are common, aimed at advancing clinical research and surgeon education in arthroscopy. This collaborative approach helps build trust and promotes adoption of new technologies.

Sustainability and patient safety are increasingly prioritized, with leading companies investing in environmentally friendly materials and technologies that reduce infection risks.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/arthroscopy-procedures-products-market

Segmentation Outlook

The arthroscopy procedure and products market can be segmented based on product type, application, end-user, and geography. Product types include arthroscopes, shavers, fluid management systems, trocars, and surgical instruments, each playing a vital role in the success of arthroscopic surgeries.

In terms of applications, knee arthroscopy dominates the market due to the high prevalence of knee injuries and osteoarthritis. However, shoulder, hip, wrist, and ankle arthroscopy are gaining traction as techniques and products evolve to address these joints effectively.

End-users mainly consist of hospitals, ambulatory surgical centers, and orthopedic clinics. The rising trend toward outpatient procedures and ambulatory care centers is creating new avenues for product usage, driven by patient preference for shorter hospital stays.

Geographically, the market covers Europe’s various regions with differing levels of adoption and growth potential. Market strategies must consider the healthcare infrastructure, reimbursement policies, and demographic trends unique to each area.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Europe Viscosupplementation Market to Reach USD 869.8 Million by 2035, Growing at 5.2% CAGR

The Europe viscosupplementation market has been steadily gaining momentum as a preferred treatment for osteoarthritis and other joint-related ailments. Viscosupplementation involves the injection of hyaluronic acid or similar substances directly into the joint space to restore the natural lubrication, thereby alleviating pain and improving mobility. As the aging population in Europe continues to grow, the demand for effective, minimally invasive treatments for degenerative joint conditions has significantly increased. This market reflects the broader shift towards non-surgical interventions that offer patients pain relief and improved joint function without the risks associated with invasive procedures.

The Europe viscosupplementation market is expected to be reach USD 523.9 million in 2025 and is likely to expand up to approximately USD 869.8 million by the end of 2035. The sales are believed to rise with a CAGR of 5.2% during the period of 2025 to 2035.

Healthcare providers across Europe are increasingly recognizing the benefits of viscosupplementation, particularly for patients who are not ideal candidates for surgery or those seeking to delay surgical interventions like joint replacements. Additionally, the growing awareness of osteoarthritis and advancements in the formulations used for injections have enhanced the acceptance of these treatments. This growing adoption, combined with ongoing research and technological innovation, positions the Europe viscosupplementation market for continued expansion.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-eu-1383

Market Trends

The Europe viscosupplementation market is shaped by several key trends that reflect both technological advancements and shifting patient preferences. One of the most prominent trends is the development of longer-lasting viscosupplement formulations that reduce the frequency of injections needed. This improvement not only enhances patient comfort but also lowers overall treatment costs by minimizing repeat visits.

Another notable trend is the increasing incorporation of cross-linked hyaluronic acid products, which tend to offer better viscoelastic properties and prolonged efficacy compared to earlier formulations. Manufacturers are investing in research to develop these enhanced products to meet growing consumer demand for effective and lasting pain relief.

There is also a rising trend towards combination therapies, where viscosupplementation is used alongside other non-invasive treatments such as physical therapy or platelet-rich plasma (PRP) injections. Such multi-modal approaches aim to maximize therapeutic outcomes and offer a comprehensive solution to joint degeneration.

Patient awareness campaigns and education efforts have also contributed to the market growth, encouraging individuals to seek earlier treatment for joint conditions. The expansion of healthcare infrastructure and improved reimbursement policies in several European countries further support the adoption of viscosupplementation therapies.

Challenges and Opportunities

While the Europe viscosupplementation market is poised for growth, it faces several challenges that must be addressed. A primary concern is the variability in treatment outcomes, which depends on factors such as patient age, severity of joint damage, and the specific viscosupplement product used. This inconsistency can affect patient satisfaction and lead to hesitancy among some healthcare providers.

Additionally, the market faces competition from alternative treatments such as corticosteroid injections and emerging regenerative therapies. Some clinicians may prefer these options due to familiarity or perceived efficacy, which can limit the market penetration of viscosupplementation.

Regulatory hurdles also pose challenges, as products must comply with stringent European Union medical device regulations that can delay product launches and increase development costs. The variability in healthcare reimbursement policies across different European countries adds complexity for manufacturers seeking broad market access.

Despite these challenges, the market offers significant opportunities. Innovations in product formulation, including bioengineered and multi-functional viscosupplements, promise to improve efficacy and patient outcomes. The growing prevalence of osteoarthritis, driven by an aging population and increasing obesity rates, guarantees a sustained demand for joint care solutions.

Furthermore, emerging markets within Europe, such as Eastern European countries, present untapped potential due to increasing healthcare spending and improved medical infrastructure. Companies that can effectively navigate regulatory frameworks and tailor products to regional needs are likely to succeed.

Key Points

The Europe viscosupplementation market is fundamentally driven by the need for safer, effective treatments for osteoarthritis and related joint disorders. Its non-invasive nature appeals to both patients and clinicians who aim to avoid or delay surgery. Advances in hyaluronic acid formulations, including cross-linked and higher molecular weight products, enhance treatment durability and patient outcomes.

Education and awareness among patients have increased, encouraging early diagnosis and treatment, which contributes to better long-term management of joint conditions. Reimbursement policies and healthcare infrastructure improvements across Europe are facilitating easier access to viscosupplementation therapies.

However, treatment outcome variability and competition from alternative therapies remain significant considerations. Addressing these through innovation, education, and regulatory compliance will be key to market growth.

Key Regional Insights

Within Europe, there are notable variations in market maturity and growth potential. Western European countries such as Germany, France, and the United Kingdom lead in terms of market size and adoption rates. These regions benefit from advanced healthcare systems, higher healthcare spending, and widespread physician awareness of viscosupplementation benefits.

Northern Europe also shows strong potential due to increasing investments in healthcare technology and a growing elderly population. In contrast, Southern European countries are gradually increasing their adoption as healthcare reforms and infrastructure improve.

Eastern Europe represents a growing opportunity, where increasing disposable incomes and expanding healthcare access are driving demand. However, reimbursement policies in these regions tend to be less favorable, which can slow adoption rates.

The differences in regulatory environments and healthcare policies necessitate tailored strategies for companies looking to expand within the European market. Localization of marketing efforts and adaptation to regional healthcare practices will be important for success.

Competitive Outlook

The competitive landscape of the Europe viscosupplementation market is characterized by a mix of established pharmaceutical companies and specialized medical device manufacturers. These players compete on product innovation, clinical efficacy, regulatory compliance, and pricing.

Companies with a strong focus on research and development tend to lead by introducing advanced formulations that improve patient outcomes and reduce injection frequency. Strategic partnerships with healthcare providers and distribution networks also enhance market reach and credibility.

Competition is also fueled by the entrance of new players offering generic or biosimilar viscosupplement products, which can drive prices down and increase accessibility. However, the emphasis remains on quality and clinical validation, as healthcare providers prefer products with proven efficacy and safety profiles.

Marketing and educational initiatives aimed at healthcare professionals play a crucial role in differentiating brands. Companies that invest in robust training programs and patient awareness campaigns are better positioned to gain physician trust and patient acceptance.

Top Companies

Leading companies in the Europe viscosupplementation market typically have diverse portfolios spanning multiple therapeutic areas and medical devices. Their extensive experience in regulatory affairs and clinical research gives them an edge in product development and market penetration.

These firms prioritize innovation, focusing on enhanced viscosupplement formulations, improved delivery systems, and combination therapies. They also tend to have well-established distribution channels and partnerships with hospitals, orthopedic centers, and clinics across Europe.

In addition to global pharmaceutical giants, specialized firms dedicated exclusively to joint health products contribute significantly to the market dynamics. These companies often provide niche products tailored to specific patient needs and invest heavily in post-market studies to reinforce product credibility.

Emerging players are leveraging digital marketing and direct-to-consumer strategies to expand their footprint, especially in homecare and outpatient treatment settings.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/europe-viscosupplementation-market

Segmentation Outlook

The market segmentation in Europe revolves around product types, treatment applications, end-users, and distribution channels. Product segmentation includes single-injection and multi-injection viscosupplement formulations, each catering to different patient and clinical preferences. Single-injection products appeal due to convenience and reduced clinical visits, while multi-injection therapies may be preferred for more severe cases.

Application segments primarily cover knee osteoarthritis, which represents the largest market share, as it is the most common joint affected. However, viscosupplementation is also applied to other joints like the hip, shoulder, and ankle, with growing research supporting these uses.

End-users include hospitals, orthopedic clinics, specialized rehabilitation centers, and outpatient care facilities. Increasingly, private clinics and ambulatory care centers are adopting viscosupplementation therapies due to their minimally invasive nature and patient demand for outpatient procedures.

Distribution channels consist of direct sales by manufacturers, distributors, and increasingly, online platforms that facilitate easier access for clinics and patients. The expansion of e-commerce in medical supplies offers an additional growth avenue for market players.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
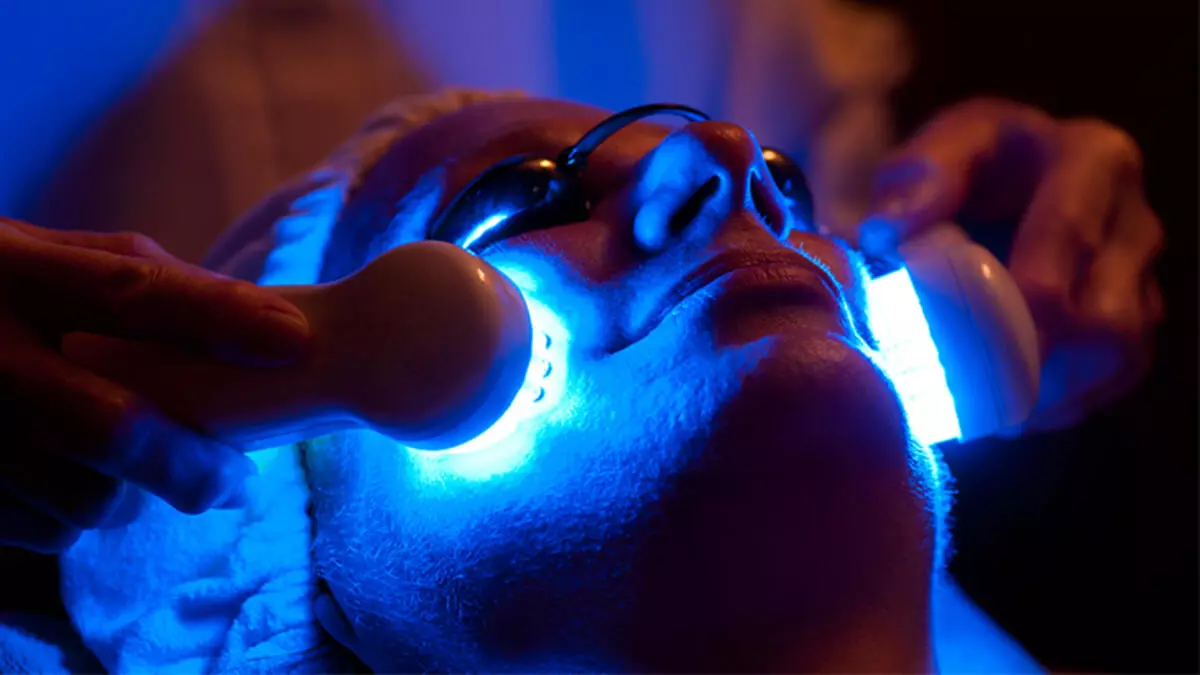
 

Light Therapy Market to Witness Robust Growth, Surpassing USD 1.5 Billion by 2034

The light therapy market has grown increasingly prominent in recent years, reflecting advancements in therapeutic technologies and a rising awareness of light-based treatments for various health conditions. Light therapy, often referred to as phototherapy, utilizes specific wavelengths of light to treat disorders ranging from seasonal affective disorder (SAD) and skin conditions to sleep disorders and pain management. This non-invasive approach offers an alternative or complement to traditional pharmaceutical treatments, making it appealing to patients seeking fewer side effects and more natural healing methods.

Light Therapy Market is expected to reach USD 1012.1 million in 2024 and USD 1,586.8 million by 2034. In the forecast period, the market is expected to expand at a CAGR of 4.6%. A value of USD 1017.2 million was attributed to the light therapy business in 2023.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-1160

Healthcare providers, dermatologists, and wellness centers have widely embraced light therapy devices, integrating them into treatment protocols for both clinical and home use. The growing acceptance of these therapies is driving innovation, encouraging manufacturers to develop more portable, user-friendly, and effective devices. As consumer interest in holistic and non-pharmacological treatments continues to expand, the light therapy market is poised for significant growth in the coming years.

Size & Trends

The current size of the light therapy market is reflective of its broad application across medical and consumer wellness sectors. Increasing demand for light therapy devices is fueled by rising awareness of mental health issues such as depression and anxiety, where light therapy has shown promising results. Additionally, dermatological uses, including the treatment of psoriasis, eczema, and acne, continue to expand the market’s reach.

Trends indicate a shift towards wearable and home-use light therapy devices, allowing individuals to manage their conditions conveniently without frequent clinical visits. The integration of smart technology and apps to monitor treatment duration and intensity also appeals to tech-savvy consumers, improving adherence and outcomes.

Moreover, innovations in light wavelengths, such as red and near-infrared light, have opened new therapeutic possibilities, extending light therapy’s application beyond skin-related issues to muscle recovery, inflammation reduction, and even cognitive health. The rise in self-care and preventive health strategies contributes to this expanding market trend.

Challenges and Opportunities

Despite the promising outlook, the light therapy market faces challenges that could impact its growth trajectory. One major issue is the lack of standardized treatment protocols, which sometimes results in inconsistent outcomes. The effectiveness of light therapy varies with the wavelength used, treatment duration, and the patient’s specific condition, which can lead to skepticism among healthcare professionals and patients alike.

Another challenge lies in regulatory approvals and the varying standards across different countries, which complicates market entry for new products. Consumers often require clear evidence of efficacy and safety, meaning companies must invest in rigorous clinical trials and marketing efforts to build trust.

However, these challenges present unique opportunities. As scientific research continues to validate the benefits of light therapy for a wider range of conditions, acceptance is expected to increase. This scientific backing will also help pave the way for insurance coverage and wider adoption in medical institutions.

There is also significant opportunity in emerging markets where awareness and access to light therapy devices remain limited. Educating healthcare providers and consumers about the benefits of phototherapy can unlock untapped potential. Furthermore, collaboration between technology firms and medical researchers can foster the development of next-generation devices with enhanced efficacy and ease of use.

Key Benefits for Stakeholders

For patients, light therapy provides a non-invasive, drug-free treatment option with minimal side effects, making it attractive for those with chronic or recurring conditions. The ability to use devices at home empowers patients to take control of their health, improving compliance and treatment outcomes.

Healthcare providers benefit from adding light therapy to their treatment arsenal, especially as it complements existing therapies and reduces dependency on pharmaceuticals. Clinics offering light therapy can attract a broader patient base seeking holistic care.

Manufacturers and distributors gain from the expanding market demand by innovating devices that are more portable, affordable, and user-friendly. The ongoing integration of digital technology enhances product differentiation and customer engagement. Investors see light therapy as a growing segment with diverse applications, from clinical treatment to wellness and beauty.

Overall, the stakeholders in this market are positioned to capitalize on increasing consumer preference for personalized and preventive healthcare solutions, as well as rising investment in health tech innovation.

Market Share by Geographical Region

The geographical distribution of the light therapy market reveals varying degrees of adoption based on healthcare infrastructure, consumer awareness, and regulatory environments. North America remains one of the largest markets, driven by advanced healthcare facilities, high prevalence of conditions like seasonal affective disorder, and strong consumer demand for wellness products. The U.S. dominates this region, supported by active research and development and established distribution networks.

Europe follows closely with growing adoption of light therapy in both clinical and home settings. Countries with high healthcare expenditure and progressive regulatory frameworks facilitate market growth. The increasing focus on mental health and dermatological treatments in this region contributes to expanding demand.

In the Asia-Pacific region, the market is growing rapidly as rising disposable incomes, increasing urbanization, and expanding healthcare access encourage adoption. Countries such as China, Japan, and India are witnessing heightened awareness of phototherapy’s benefits. Government initiatives promoting non-invasive and alternative therapies further fuel growth.

Emerging markets in Latin America, the Middle East, and Africa currently represent a smaller share but show promising growth potential due to increasing healthcare investments and improving infrastructure.

Competitive Outlook

Competition in the light therapy market is intensifying as more companies recognize the lucrative potential of this sector. Established medical device manufacturers are expanding their product portfolios to include advanced phototherapy devices, leveraging their existing relationships with healthcare providers.

At the same time, innovative startups focused on wearable and consumer-friendly devices are gaining traction. These companies emphasize design, portability, and digital integration, appealing to a broader consumer base.

Strategic partnerships and collaborations between technology firms, healthcare institutions, and research organizations are shaping the competitive landscape. Companies investing in clinical validation and regulatory approvals tend to build stronger market credibility.

Additionally, pricing strategies and after-sales services such as patient training and support are critical factors influencing competitiveness. The ability to offer customized solutions tailored to specific medical or wellness needs distinguishes market leaders from smaller players.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/light-therapy-market

Top Companies

Several key players dominate the light therapy market, offering a range of products from professional medical devices to consumer-grade home-use equipment. These companies are investing heavily in research and development to refine technologies and expand therapeutic applications.

Market leaders often have global distribution networks and strong brand recognition, which enable them to penetrate diverse markets effectively. They also prioritize compliance with international safety and efficacy standards, ensuring trust among healthcare professionals and end users.

In parallel, emerging companies focused on niche segments such as sleep therapy, skin rejuvenation, or pain management are driving innovation. These firms often introduce specialized products with novel features, attracting specific patient groups.

The diversity of players in this market reflects its broad application and the continuous evolution of light therapy technology.

Segmentation Outlook

The light therapy market can be segmented based on product type, application, end-user, and distribution channel. Product types include light therapy devices such as LED panels, light boxes, laser devices, and wearable units. Each type caters to different therapeutic needs and settings, from clinical to home use.

Applications span mental health conditions like seasonal affective disorder, skin disorders including psoriasis and acne, sleep regulation, pain management, and wound healing. Among these, mental health and dermatology represent the largest shares due to high prevalence and effective treatment outcomes.

End-users range from hospitals, clinics, and dermatology centers to individual consumers purchasing devices for home use. The rise of telehealth and home care is boosting demand in the consumer segment.

Distribution channels include direct sales, online platforms, and retail outlets. The growth of e-commerce has made light therapy devices more accessible globally, allowing manufacturers to reach a wider audience with ease.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
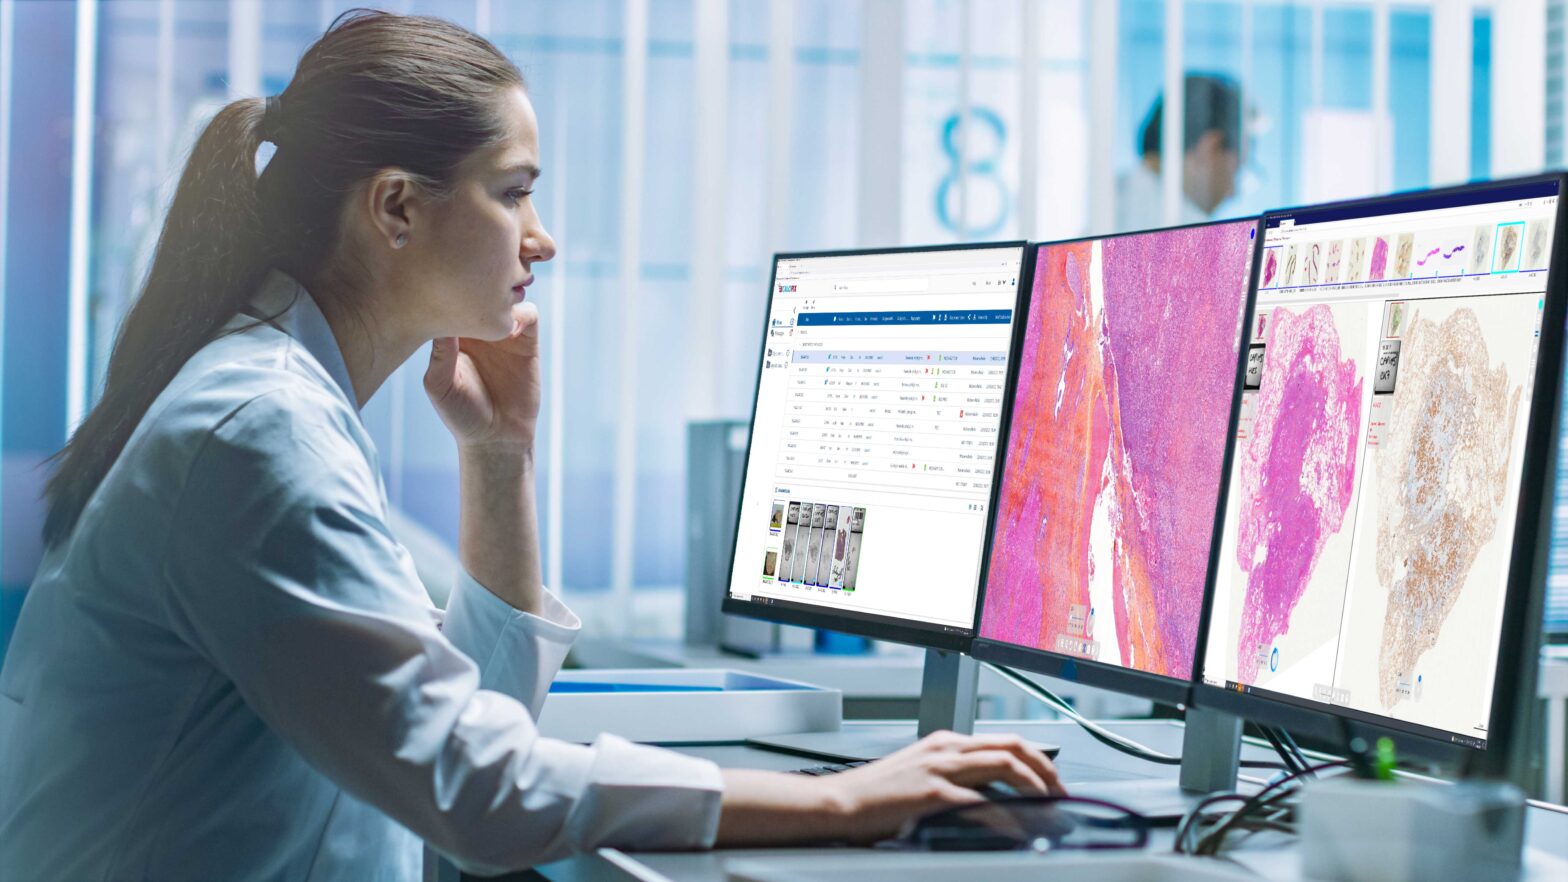
Digital Pathology Market Set for Strong Growth, Hitting USD 9.1 Billion in 2025

The market will be near about USD 9.1 Billion in 2025 and USD 31.3 Billion in 2035, growing at a CAGR of 13.1% over the estimated period. The introduction of artificial intelligence and machine learning in digital pathology systems has improved diagnostic precision and workflows by allowing pathologists to process more information more efficiently.

The digital pathology market has emerged as a revolutionary segment within the broader healthcare and diagnostics industry. It involves the digitization of traditional pathology methods, allowing for better analysis, storage, sharing, and interpretation of pathological data through digital imaging. With the integration of advanced technologies such as artificial intelligence, machine learning, and cloud computing, digital pathology is transforming the way clinicians and researchers approach diagnostics and patient care. The shift from glass slides and manual interpretation to high-resolution digital slides brings efficiency, scalability, and enhanced accuracy.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-124

Healthcare providers are recognizing the value of adopting digital workflows, particularly in streamlining pathology operations, enabling remote diagnostics, and improving collaboration across institutions. The digital shift is also instrumental in supporting personalized medicine by facilitating faster turnaround times and more accurate analyses. As healthcare infrastructure evolves to meet growing patient demands, digital pathology stands at the forefront of innovation.

Market Trends

Emerging trends in the digital pathology market highlight the increasing adoption of AI-powered diagnostic tools and the expansion of telepathology. AI algorithms are now capable of analyzing digital slides, identifying patterns, and even assisting in preliminary diagnoses, significantly reducing the workload on pathologists. Another trend gaining momentum is the use of cloud-based platforms that allow secure sharing of large pathology images, thus supporting remote consultations and second opinions.

The trend toward centralizing data storage while ensuring compliance with data privacy regulations is also shaping market practices. Additionally, pharmaceutical and biotechnology companies are leveraging digital pathology for drug discovery and development, accelerating clinical trials and enhancing biomarker research. These trends collectively point to a more integrated, tech-enabled ecosystem.

Driving Forces Behind Market Growth

The digital pathology market is being propelled by a combination of technological innovation and healthcare system demands. One major driver is the increasing prevalence of chronic diseases such as cancer, which requires frequent and detailed diagnostic analysis. With rising case numbers, healthcare systems need scalable and efficient diagnostic tools—something digital pathology provides.

In addition, the global shortage of skilled pathologists has intensified the need for automated and remote diagnostic solutions. Digital platforms allow fewer professionals to manage a larger volume of work without compromising quality. Integration with laboratory information systems (LIS) and electronic health records (EHR) further boosts efficiency by enabling streamlined workflows and improved data accessibility.

The growing emphasis on personalized and precision medicine is also a crucial factor. By allowing more detailed tissue analysis and integration with genomic data, digital pathology supports targeted therapies. These drivers are laying the foundation for widespread adoption across hospitals, labs, and academic institutions.

Challenges and Opportunities

Despite its many benefits, the digital pathology market faces some notable challenges. One of the biggest hurdles is the high cost of initial setup, including scanners, software, and data storage infrastructure. For smaller laboratories and clinics, these costs can be prohibitive, slowing adoption.

Data security and regulatory compliance also pose concerns. Managing patient data across digital platforms requires adherence to strict guidelines such as HIPAA and GDPR. Ensuring data protection while maintaining accessibility is a delicate balance that organizations must manage carefully.

However, these challenges open the door to several opportunities. As technology becomes more affordable and cloud computing more scalable, smaller institutions will be better positioned to adopt digital pathology solutions. Moreover, the increasing collaboration between healthcare providers and tech companies promises more user-friendly and cost-effective innovations. Startups entering the space with niche solutions for specific pathology needs also offer significant growth potential.

Recent Industry Developments

The landscape of the digital pathology market has seen notable developments in recent years. One of the key areas of progress is the regulatory acceptance of digital pathology systems for primary diagnosis. This shift has encouraged more institutions to transition from analog to digital platforms.

Mergers, acquisitions, and strategic partnerships between tech firms and healthcare organizations are shaping the competitive landscape. Companies are investing in AI development and integrating it into their diagnostic tools, creating hybrid platforms that offer both imaging and analytics. The result is faster and more accurate diagnoses, as well as support for automated workflows.

Academic institutions and research labs are also contributing by developing open-source digital pathology platforms, making innovation more accessible. These initiatives not only promote research but also ensure that smaller healthcare providers can benefit from technological advancements.

Regional Analysis

  • The adoption of digital pathology solutions varies significantly by region. In North America, particularly the United States, market penetration is high due to strong healthcare infrastructure and early adoption of new technologies. Favorable reimbursement policies and high R&D investments have further accelerated growth in this region.
  • Europe follows closely, with countries such as Germany, the United Kingdom, and the Netherlands investing in digital healthcare infrastructure. Initiatives by the European Union to standardize digital health records and promote telemedicine are encouraging broader deployment of digital pathology systems.
  • In the Asia-Pacific region, market growth is driven by rising healthcare expenditure and the need for better diagnostic capabilities in countries with large populations. China and India are emerging as key players due to government support for digital transformation and increasing collaborations with global technology companies.
  • Latin America and the Middle East are gradually entering the digital pathology space, though adoption remains limited due to infrastructural constraints. However, growing interest in telemedicine and remote diagnostics presents promising opportunities for market expansion in these regions.

Competitive Outlook

The digital pathology market is highly competitive, with both established players and innovative startups striving to gain market share. Leading companies focus on comprehensive solutions that integrate hardware, software, and cloud services. They are investing heavily in research and development to maintain a competitive edge, particularly in areas such as AI-based diagnostics and workflow automation.

Startups, on the other hand, often target niche markets or provide customizable solutions for specific pathology needs. Their agility allows them to respond quickly to market demands and experiment with emerging technologies. As the market matures, collaborations between established firms and startups are becoming increasingly common, fostering innovation and expanding product offerings.

Market competition is also influenced by the ability to scale solutions globally while maintaining compliance with local regulatory requirements. Companies that can balance these demands while offering user-friendly platforms are likely to lead the industry forward.

Top Companies

Several companies stand out as leaders in the digital pathology market. These include organizations that have built end-to-end platforms, incorporating digital imaging, data management, and analytics. Their solutions are often adopted by major hospitals, research institutions, and pharmaceutical companies.

What distinguishes top players is their ability to innovate continuously. They not only upgrade their hardware to offer higher resolution and faster scanning but also enhance software capabilities with AI and machine learning integration. Partnerships with academic and research organizations help these companies stay at the forefront of diagnostic advancement.

Customer service, training support, and system interoperability are other differentiators. Firms that offer seamless integration with existing healthcare infrastructure and robust user training programs are more likely to retain clients and expand their footprint.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/global-digital-pathology-market

Segmentation Outlook

The digital pathology market is segmented based on product type, end-use, application, and region. On the product side, the market includes scanners, software, storage solutions, and communication systems. Scanners are the most widely used component, while software solutions are gaining traction due to their analytical and data management capabilities.

End-users range from hospitals and diagnostic labs to academic institutions and pharmaceutical companies. Each segment has unique needs—clinical use demands speed and reliability, while academic users prioritize image quality and analysis tools.

Applications include disease diagnosis, drug discovery, and educational training. Diagnostic applications dominate due to the growing demand for accurate and timely disease identification. However, pharmaceutical research is becoming an equally important segment, especially as companies strive to streamline drug development processes.

Geographically, the market is segmented into regions that reflect differing levels of technological adoption and healthcare infrastructure, impacting how quickly and extensively digital pathology is adopted.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
 

Pin Up Казахстан – официальный сайт сегодня

Пин Ап казино – Официальный сайт Pin Up Casino вход на зеркало

Если вы ищете надежное и проверенное казино, где можно играть в любимые игры и выиграть реальные деньги, то Pin Up Casino – ваш выбор!

Pin Up Casino – это официальный сайт, который предлагает игрокам широкий спектр игр, включая слоты, карточные игры, рулетку и другие. Вам не нужно искать зеркало, потому что на официальном сайте Pin Up Casino вы можете играть в любимые игры и получать реальные выигрыши.

Официальный сайт Pin Up Casino имеет лицензию, что означает, что он является безопасным и надежным местом для игроков. Вам не нужно беспокоиться о безопасности своих данных и средств, потому что на официальном сайте Pin Up Casino все сделано для обеспечения безопасности игроков.

Кроме того, на официальном сайте Pin Up Casino есть множество бонусов и акций, которые помогут вам начать играть и получать выигрыши. Вам не нужно искать другие сайты, потому что на официальном сайте Pin Up Casino вы можете найти все, что вам нужно для игры.

Таким образом, если вы ищете надежное и проверенное казино, где можно играть в любимые игры и выиграть реальные деньги, то Pin Up Casino – ваш выбор. Вам не нужно искать другие сайты, потому что на официальном сайте Pin Up Casino вы можете найти все, что вам нужно для игры.

Начните играть сейчас и получайте выигрыши!

Важно! Вам не нужно искать другие сайты, потому что на официальном сайте Pin Up Casino вы можете найти все, что вам нужно для игры. Начните играть сейчас и получайте выигрыши!

Пин Ап казино – Официальный сайт

Если вы ищете надежный и безопасный способ играть в онлайн-казино, то Pin Up Casino – ваш выбор. Официальный сайт Pin Up Casino предлагает вам широкий выбор игр, включая слоты, карточные игры и рулетку.

Pin Up Casino – это международная онлайн-казино, которая была основана в 2016 году. Компания имеет лицензию на проведение игорного бизнеса, выдана в Куртрахе, Германия. Это означает, что вы можете быть уверены в безопасности и честности игр на этом сайте.

Официальный сайт Pin Up Casino доступен на русском языке, что делает его доступным для игроков из России и других стран, где русский язык является официальным. Сайт имеет простой и удобный интерфейс, который позволяет вам легко найти игру, которая вам нравится.

Pin Up Casino предлагает вам широкий выбор игр, включая:

Слоты: Book of Dead, Gonzo’s Quest, Starburst и многие другие.

Карточные игры: BlackJack, Baccarat, Poker и другие.

Рулетка: European Roulette, American Roulette и другие.

Кроме того, Pin Up Casino предлагает вам различные бонусы и акции, чтобы помочь вам начать играть и насладиться игрой.

Бонусы: приветственный бонус, пин ап казино бонусы за депозит, бонусы за игру.

Акции: акции на игры, акции на бонусы, акции на депозит.

Pin Up Casino – это ваш выбор, если вы ищете надежный и безопасный способ играть в онлайн-казино. Официальный сайт доступен на русском языке, и он предлагает вам широкий выбор игр и бонусов.

Вход на зеркало Pin Up Casino

Pin Up Casino – это популярное онлайн-казино, которое предлагает игрокам широкий спектр игр, включая слоты, карточные игры, рулетку и другие. Казино имеет официальный сайт, на котором игроки могут создавать аккаунт, делать депозит, получать бонусы и играть в игры.

Однако, в некоторых случаях, основной сайт Pin Up Casino может быть заблокирован или недоступен. В этом случае, игроки могут использовать зеркало, чтобы доступаться к официальному сайту и продолжать играть.

Зеркало Pin Up Casino – это безопасный и надежный способ доступа к официальному сайту, если основной сайт недоступен. Зеркало обеспечивает аналогичный уровень безопасности и конфиденциальности, что и основной сайт.

Если вы ищете зеркало Pin Up Casino, то вам нужно найти официальный сайт Pin Up Casino и найти ссылку на зеркало. Зеркало будет иметь аналогичный дизайн и функциональность, что и основной сайт, но с отличием в адресе.

В целом, зеркало Pin Up Casino – это отличный способ доступа к официальному сайту, если основной сайт недоступен. Мы рекомендуем игрокам использовать зеркало, чтобы продолжать играть в игры и получать бонусы.

Важно: Проверьте, является ли зеркало Pin Up Casino официальным, перед тем как использовать его. Некоторые зеркала могут быть фальшивыми, поэтому важно быть осторожным и проверять authenticity зеркала.

Преимущества и функции Pin Up Casino

Pin Up Casino – это популярное онлайн-казино, которое предлагает игрокам широкий спектр развлекательных игр и функций. В этом разделе мы рассмотрим преимущества и функции Pin Up Casino, которые делают его одним из лучших онлайн-казино.

Бонусы и программы лояльности

Pin Up Casino также предлагает различные бонусы и программы лояльности, чтобы помочь игрокам начать играть и продолжать играть. Новым игрокам предлагается приветственный бонус в размере 50% от первого депозита, а также 50 бесплатных спин. Регулярные игроки могут получать бонусы и бесплатные спин в рамках программы лояльности.

Кроме того, Pin Up Casino предлагает программу реферальной системы, которая позволяет игрокам получать бонусы и бесплатные спин, пригласив друзей и знакомых в казино.

В целом, Pin Up Casino – это отличное онлайн-казино, которое предлагает игрокам широкий спектр развлекательных игр, функций и бонусов. Если вы ищете новый игровой опыт, Pin Up Casino – это отличный выбор.

UP-X онлайн-казино – официальный сайт + как зарегистрироваться и войти быстро и безопасно — обзор разделов — бонусы и акции : как получить / выплаты : пошаговая инструкция / платёжные методы – все доступные методы / приложение — на Android и iOS / казино на телефоне – что умеет │ слоты – как выбрать слот • казино с живыми дилерами : лучшие столы • карточные игры — правила и стратегии • безопасность и лицензия – ответственная игра │ мнения пользователей : стоит ли играть │ поддержка пользователей — чат, почта и помощь

UP-X онлайн казино – лицензия и безопасность

Если вы ищете надежное онлайн-казино, где можно играть в любимые игры и чувствовать себя уверенно, то UP-X онлайн-казино – это отличный выбор. В этом обзоре мы рассмотрим, как UP-X обеспечивает безопасность своих игроков и какова его лицензия.

UP-X онлайн-казино – это популярная платформа, которая предлагает игрокам широкий спектр игр, включая слоты, карточные игры и рулетку. Но безопасность игроков – это не только важный аспект, но и обязательное условие для любого онлайн-казино. UP-X понимает это и предпринимает все необходимые шаги для обеспечения безопасности своих игроков.

Лицензия UP-X – это международная лицензия, выдана в соответствии с международными стандартами и нормами. Это означает, что UP-X подчиняется строгим требованиям и нормам, чтобы обеспечить безопасность своих игроков. Кроме того, UP-X имеет официальный сайт, который доступен по адресу upx.com, а также зеркало, доступное по адресу upx зеркало.

UP-X также предпринимает шаги для ап х обеспечения безопасности своих игроков, такие как шифрование данных, использование SSL-сертификатов и регулярные аудиты безопасности. Это означает, что все данные игроков защищены и не могут быть доступны третьим лицам.

В целом, UP-X онлайн-казино – это надежная платформа, которая обеспечивает безопасность своих игроков и предлагает широкий спектр игр. Если вы ищете надежное онлайн-казино, где можно играть в любимые игры и чувствовать себя уверенно, то UP-X – это отличный выбор.

Обратите внимание, что AP X официальный сайт – это upx.com, а зеркало – это upx зеркало. Не пытайтесь играть на других сайтах, которые могут быть фальшивыми или мошенническими.

UP-X Онлайн Казино: Лицензия и Безопасность

Важно отметить, что UP-X онлайн казино имеет официальную лицензию, выдана Мальтийской комиссией по регулированию и лицензированию игорного бизнеса (MGA). Это означает, что казино подлежит строгому регулированию и контролю, чтобы обеспечить безопасность и честность игроков.

UP-X официальный сайт (upx.com) является безопасным и надежным, поскольку он использует современные технологии шифрования и защищает данные игроков. Кроме того, казино имеет официальное зеркало (upx зеркало), которое позволяет игрокам доступаться к игровым автоматам и казино, даже если официальный сайт временно недоступен.

Безопасность и конфиденциальность

UP-X онлайн казино обеспечивает безопасность и конфиденциальность игроков, используя современные технологии шифрования и защищает данные. Все передачи данных между игроком и казино шифруются, чтобы предотвратить доступ к личным данным третьих лиц.

Кроме того, UP-X онлайн казино имеет политику конфиденциальности, которая гарантирует, что все личные данные игроков будут использоваться только для официальных целей и не будут передаваться третьим лицам.

В целом, UP-X онлайн казино является безопасным и надежным выбором для игроков, которые ищут честные и надежные игорные услуги.

Лицензия: Гарантия Качественного Игрового Процесса

Лицензия – это гарантия качественного игрового процесса. Она обеспечивает, что игроки могут наслаждаться безопасным и честным игровым процессом. UP-X онлайн казино имеет лицензию, выдана Мальтийской комиссией по регулированию и лицензированию игорного бизнеса (MGA), что является одним из самых престижных и надежных регуляторов в игорном бизнесе.

Лицензия MGA обеспечивает, что UP-X онлайн казино:

  • проведет честные и случайные игры;
  • обеспечит безопасность транзакций и защиты данных игроков;
  • содержит себя в рамках установленных регулятором лимитов и ограничений;
  • проведет регулярные аудиты и проверки для обеспечения качества и безопасности игрового процесса.

Таким образом, вам не нужно беспокоиться о безопасности и честности игрового процесса в UP-X онлайн казино. Вам достаточно посетить официальный сайт UP-X, чтобы увидеть, что он имеет все необходимые лицензии и сертификаты, подтверждающие его качество.

Вам не нужно искать ап икс официальный сайт вход, чтобы начать играть в UP-X онлайн казино. Вам достаточно перейти на официальный сайт UP-X, чтобы начать играть в безопасном и честном игровом процессе.

Вам не нужно искать ап икс официальный сайт, чтобы увидеть, что UP-X онлайн казино является надежным и безопасным выбором. Вам достаточно посетить официальный сайт UP-X, чтобы увидеть, что он имеет все необходимые лицензии и сертификаты, подтверждающие его качество.

Вам не нужно искать ап икс зеркало, чтобы начать играть в UP-X онлайн казино. Вам достаточно перейти на официальный сайт UP-X, чтобы начать играть в безопасном и честном игровом процессе.

Безопасность: Защита Вашей Информации и Денег

Для начала, мы рекомендуем вам использовать только официальный сайт UP-X, чтобы避免 любые мошеннические действия. Вам не рекомендуется использовать зеркало или любые другие сайты, которые могут быть связаны с мошенничеством.

Когда вы создаете учетную запись на официальном сайте UP-X, мы рекомендуем вам использовать сильный пароль и не делиться им с третьими лицами. Мы также рекомендуем вам регулярно изменять свой пароль для обеспечения максимальной безопасности.

Мы также обеспечиваем безопасность вашей информации с помощью SSL-шифрования, которое защищает вашу информацию от несанкционированного доступа.

Кроме того, мы сотрудничаем с надежными платежными системами, чтобы обеспечить безопасность вашего счета.

Вам не рекомендуется использовать общедоступные компьютеры или устройства, чтобы доступаться к вашей учетной записи, чтобы避免 любые мошеннические действия.

Если вы обнаружите любые мошеннические действия или подозреваете, что ваша учетная запись была compromized, пожалуйста, свяжитесь с нашим поддержкой, чтобы мы поможем вам решить проблему.

Мы всегда готовы помочь вам обеспечить безопасность вашей информации и денег. Если у вас есть какие-либо вопросы или concerns, пожалуйста, свяжитесь с нами.

Проверка: Как Увериться в Точности Информации

Вот несколько советов, которые помогут вам проверить точность информации:

Проверьте официальный сайт UP-X

Вам также стоит проверить, является ли сайт UP-X официальным, или он является фальшивкой. Вы можете это сделать, сравнив информацию на официальном сайте с информацией на других ресурсах.

Если вы обнаружили, что сайт UP-X является фальшивкой, то вам не стоит играть на этом сайте, потому что ваша безопасность находится под угрозой.

Вам также стоит проверить, является ли UP-X лицензированным онлайн-казино. Лицензия – это гарантия, что казино работает в соответствии с законами и правилами, и что ваша безопасность находится под защитой.

Вам не нужно быть экспертом в области онлайн-казино, чтобы убедиться, что информация, которую вы получаете, является достоверной. Вам достаточно проверить официальный сайт UP-X и убедиться, что он является лицензированным онлайн-казино.

Healthcare and Laboratory Label Industry Analysis in Western Europe is Growing at a Strong CAGR of 3.80% by 2034

Healthcare and Laboratory Label Industry Analysis in Western Europe

The healthcare and laboratory label industry in Western Europe is entering a dynamic phase, with strong momentum forecasted over the next decade. With a projected compound annual growth rate (CAGR) of 3.80% from 2024 to 2034, the sector is expected to expand from USD 1,959.80 million in 2024 to USD 2,845.20 million by 2034.

This growth reflects not only the increasing demand for medical and lab-specific labeling but also the region’s broader advancements in healthcare infrastructure, regulatory compliance, and technological innovation.

Healthcare and laboratory labels serve as critical components within medical and scientific environments. These labels are used to identify, track, and provide essential information on pharmaceuticals, diagnostic specimens, laboratory samples, and medical devices. Unlike standard labels, they must endure harsh environments, such as cryogenic conditions, chemical exposure, sterilization, and abrasion, while maintaining readability and integrity.

Unlock Growth Potential and Explore Market Opportunities With Our Comprehensive Industry Overview. Request Your Sample Now
https://www.futuremarketinsights.com/reports/sample/rep-gb-18700

The functionality of these labels is vital for patient safety, data accuracy, and regulatory compliance. As such, manufacturers must adhere to strict standards, including those set by the EU’s Medical Device Regulation (MDR), the International Organization for Standardization (ISO), and the European Medicines Agency (EMA).

Rising Demand for Traceability and Compliance Solutions

One of the most critical factors propelling the healthcare and laboratory label market is the heightened demand for traceability and compliance. With tightening regulations across Western Europe, particularly those surrounding the European Union’s Medical Device Regulation (MDR) and In Vitro Diagnostic Regulation (IVDR), healthcare providers and laboratories are under pressure to ensure accurate labeling for patient safety, drug traceability, and diagnostic result validity.

Key Takeaways From the Healthcare and Laboratory Label Industry Analysis in Western Europe

  • The healthcare and laboratory labels market in the United Kingdom is projected to grow at a CAGR of 3.90% from 2024 to 2034.
  • In Germany, the market is expected to expand at a CAGR of 3.40% over the same period.
  • Plastic remains the dominant material in Western Europe’s healthcare and laboratory label sector, accounting for 63.10% of the market share.
  • The pharmaceutical segment is anticipated to be the leading end-user, capturing a 29.70% revenue share in 2024.

Emerging Trends Reshaping the Industry

  • Sustainable and Eco-Friendly Labels: Sustainability has become a strategic priority. Manufacturers are investing in recyclable and biodegradable label materials, solvent-free adhesives, and linerless label technologies to meet environmental goals.
  • Smart and Connected Labels: Labels with RFID (Radio Frequency Identification), NFC (Near Field Communication), and QR codes are enabling real-time tracking, authentication, and inventory management in healthcare systems.
  • Cryogenic and Chemical-Resistant Materials: Advanced materials that withstand extreme temperatures and chemical exposure are seeing increased demand in laboratory applications, particularly in genetic research and cryopreservation.
  • In-House and On-Demand Label Printing: Hospitals and labs are moving toward on-demand label printing to increase speed, accuracy, and adaptability in dynamic environments.

Innovation in Label Technologies: Smart Labels and RFID Integration

The Western European market has seen a surge in technological advancements. A prominent trend is the adoption of smart labels and RFID (Radio Frequency Identification) technology. These advanced labels are gaining popularity for their ability to enhance inventory management, reduce human error, and improve the overall supply chain visibility in pharmaceutical and laboratory settings.

RFID-enabled labels, in particular, are being used in temperature-sensitive logistics, such as cold chain management for vaccines and biologics, allowing real-time monitoring of environmental conditions. As a result, these innovations are pushing traditional label manufacturers to upgrade their production processes and invest in R&D to stay competitive.

Competitive Landscape: Innovation and Differentiation

Western Europe’s healthcare and laboratory label industry is highly competitive and fragmented, with numerous players ranging from global conglomerates to regional specialists. This has fostered a landscape rich in innovation, price competitiveness, and product diversity.

Key Players

  • Diagramm Halbach GmbH & Co KG
  • UPM Raflatac Corporation
  • Advanced Labelling Systems Ltd.
  • Avery Dennison Corporation
  • CCL Industries Inc.
  • 3M Company
  • Multi-Color Corporation
  • Brady Corporation
  • Sato Holdings Corporation
  • Weber Packaging Solutions, Inc.
  • Schreiner Group GmbH & Co.

Healthcare and laboratory Label in Western Europe Key Segments

By Material:

  • Nylon
  • Plastic
  • Polyester
  • Polyolefin
  • Vinyl
  • Paper
  • Others

By End User:

  • Pharmaceuticals
  • Nutraceuticals
  • Medical Devices
  • Blood Banks
  • Laboratories

By Country:

  • The United Kingdom
  • Germany
  • Italy
  • France
  • Spain
  • Rest of Western Europe

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Ophthalmic Diagnostic Equipment Market to Reach USD 4.85 Billion by 2034, Growing at 3.5% CAGR

The ophthalmic diagnostic equipment market plays a vital role in modern eye care, supporting the diagnosis and management of various vision-related disorders. These devices enable ophthalmologists and optometrists to assess eye health accurately and detect conditions such as glaucoma, cataracts, macular degeneration, and diabetic retinopathy. With an aging global population and the increasing prevalence of chronic eye conditions, the demand for advanced diagnostic tools is steadily rising. The ophthalmic diagnostic equipment market is driven by innovations that enhance the accuracy, efficiency, and accessibility of eye care services across hospitals, clinics, and specialty centers.

The global Ophthalmic Diagnostic Equipment Market size is projected to be worth USD 4,851.00 million by 2034. The market is anticipated to exhibit a 3.50% CAGR until 2034. In 2024, the market is expected to be valued at USD 3,439.00 million.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-771

This market encompasses a broad range of equipment, including optical coherence tomography (OCT), fundus cameras, ultrasound imaging systems, tonometers, and visual field analyzers. Each type of equipment plays a specific role in evaluating different aspects of the eye, from intraocular pressure to retinal imaging. As early diagnosis becomes increasingly important for preventing vision loss, the ophthalmic diagnostic equipment market continues to gain prominence within the broader medical device landscape. Healthcare providers are investing in state-of-the-art diagnostic tools to improve patient outcomes and deliver timely treatment.

Market Trends

The ophthalmic diagnostic equipment market is undergoing significant transformation as a result of technological advancements and shifting patient expectations. One of the key trends is the integration of artificial intelligence (AI) and machine learning algorithms into diagnostic platforms. These technologies assist clinicians by analyzing large datasets and identifying patterns that may indicate early signs of disease. AI-driven diagnostics can improve the accuracy of assessments and reduce human error, enhancing both clinical efficiency and patient care.

Another notable trend is the miniaturization and portability of ophthalmic diagnostic equipment. Portable devices are particularly valuable in remote or underserved areas, where access to eye care may be limited. These compact systems allow for on-site diagnosis, mobile screening programs, and teleophthalmology services. As global healthcare systems aim to expand access and reduce disparities, the demand for portable diagnostic tools is expected to grow within the ophthalmic diagnostic equipment market.

The adoption of multimodal imaging systems is also becoming more prevalent. These systems combine multiple imaging techniques, such as OCT and fluorescein angiography, into a single device, enabling a comprehensive evaluation of the retina and optic nerve. This consolidation streamlines clinical workflows and improves diagnostic precision. The trend toward value-based care is pushing healthcare providers to adopt efficient solutions that offer maximum diagnostic utility.

Additionally, the ophthalmic diagnostic equipment market is seeing increasing investment in research and development, leading to the introduction of innovative products with enhanced features. Manufacturers are focusing on improving image resolution, data connectivity, and user interface design to better meet the needs of clinicians. As awareness of preventive eye care continues to grow, so too does the emphasis on user-friendly and accurate diagnostic technologies.

Driving Forces Behind Market Growth

Several factors are driving growth in the ophthalmic diagnostic equipment market. One of the primary drivers is the global rise in age-related eye diseases. As life expectancy increases, conditions such as cataracts, glaucoma, and age-related macular degeneration are becoming more common. These disorders require regular monitoring and early detection to manage effectively, increasing the demand for high-quality diagnostic equipment.

The growing prevalence of diabetes worldwide is another major contributor to market growth. Diabetic patients are at increased risk of developing diabetic retinopathy, a leading cause of vision impairment. Regular eye examinations using advanced diagnostic tools are essential for early detection and intervention, making diabetic eye care a significant driver of demand in the ophthalmic diagnostic equipment market.

Technological innovation is also propelling market expansion. Devices with faster processing speeds, enhanced imaging capabilities, and seamless electronic health record integration are streamlining clinical operations and improving diagnostic accuracy. The introduction of AI-enabled diagnostics and cloud-based image storage is enabling more efficient data analysis and patient management.

Increased healthcare spending, particularly in emerging economies, is supporting infrastructure improvements and the acquisition of advanced medical technologies. As governments and private organizations invest in healthcare modernization, ophthalmic diagnostic equipment is becoming more widely available, further driving market growth.

Challenges and Opportunities

Despite the promising outlook, the ophthalmic diagnostic equipment market faces several challenges. One of the most significant barriers is the high cost of advanced diagnostic systems. Many of these devices require substantial upfront investment, which can be a limitation for small clinics or healthcare providers in low-income regions. Maintenance costs and the need for specialized training also add to the financial burden.

Regulatory compliance is another challenge, especially for manufacturers operating in multiple countries. Each region has its own set of regulatory standards and approval processes, which can complicate product development and market entry. Ensuring device safety and performance while meeting diverse regulatory requirements is an ongoing concern in the ophthalmic diagnostic equipment market.

Data privacy and cybersecurity are emerging challenges as diagnostic systems become increasingly connected. Protecting patient information and ensuring secure data transmission are critical in the digital healthcare landscape. Companies must invest in robust cybersecurity measures to maintain user trust and regulatory compliance.

Despite these challenges, there are significant opportunities for growth and innovation. The expanding role of telemedicine and mobile health presents new avenues for delivering eye care. Teleophthalmology services, powered by portable diagnostic equipment, can reach patients in rural or underserved areas, opening new markets for manufacturers.

There is also a growing emphasis on preventive care and early diagnosis. Public health initiatives focused on reducing avoidable blindness are creating opportunities for screening programs and increased adoption of diagnostic equipment. Collaborations between healthcare providers, governments, and non-profit organizations can help address access barriers and promote widespread use of ophthalmic diagnostic technologies.

Regional Analysis

The ophthalmic diagnostic equipment market exhibits diverse growth patterns across various geographic regions. North America holds a leading position, driven by advanced healthcare infrastructure, high healthcare expenditure, and widespread adoption of cutting-edge technologies. The United States, in particular, benefits from strong industry presence and supportive regulatory frameworks, making it a key market for diagnostic equipment manufacturers.

Europe also commands a significant share of the ophthalmic diagnostic equipment market, with countries such as Germany, the UK, and France at the forefront. Well-established healthcare systems, high patient awareness, and ongoing investment in medical technology contribute to the region’s market strength. Regulatory support from organizations like the European Medicines Agency further facilitates product adoption.

The Asia-Pacific region is experiencing rapid growth, fueled by a large aging population, rising incidence of chronic diseases, and expanding healthcare access. Countries like China, India, and Japan are investing heavily in healthcare infrastructure, creating favorable conditions for market expansion. Increasing medical tourism in the region also supports the growth of the ophthalmic diagnostic equipment market.

Latin America, the Middle East, and Africa are emerging markets with growing demand for eye care services. While these regions face infrastructure and economic challenges, international collaborations and government initiatives are helping improve access to diagnostic equipment. As awareness and investment increase, these markets are expected to contribute more significantly to global growth.

Competitive Outlook

The competitive landscape of the ophthalmic diagnostic equipment market is marked by the presence of several leading companies, along with numerous emerging players. Established firms dominate the market through their strong product portfolios, global distribution networks, and commitment to innovation. These companies invest heavily in research and development to enhance device capabilities, address evolving clinical needs, and maintain a competitive edge.

Strategic partnerships, mergers, and acquisitions are common in the industry, enabling companies to expand their offerings and enter new markets. Collaborations with academic institutions and healthcare providers facilitate clinical validation and technology advancement. Market competition is also driving efforts to improve device affordability and user-friendliness, particularly in cost-sensitive regions.

Customization and after-sales support have become key differentiators, with companies offering tailored solutions and comprehensive training programs. As competition intensifies, success in the ophthalmic diagnostic equipment market will depend on the ability to innovate, ensure regulatory compliance, and deliver superior customer service.

Top Companies

Several top companies play a central role in shaping the ophthalmic diagnostic equipment market. These industry leaders have built strong reputations through decades of experience, consistent product quality, and ongoing technological advancement. Their wide-ranging product lines cater to various diagnostic needs, from routine eye exams to advanced retinal imaging.

These companies often lead the way in AI integration, device automation, and software compatibility. Their strong global presence allows them to serve diverse markets and respond effectively to regional demands. Investment in clinical research and educational outreach helps reinforce their leadership positions and promote widespread adoption of their technologies.

Through strategic collaborations, product innovation, and expansion into emerging markets, these top companies continue to drive growth and innovation in the ophthalmic diagnostic equipment market.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/sample/rep-gb-771

Segmentation Outlook

The ophthalmic diagnostic equipment market can be segmented by product type, end user, and application. In terms of product type, the market includes optical coherence tomography devices, fundus cameras, visual field analyzers, and others. OCT devices hold a significant share due to their ability to provide detailed cross-sectional images of the retina.

By end user, the market is segmented into hospitals, ophthalmic clinics, and ambulatory surgical centers. Hospitals represent a major end user due to their advanced infrastructure and high patient throughput. However, ophthalmic clinics and specialty centers are increasingly adopting diagnostic equipment to deliver focused care.

The application-based segmentation includes glaucoma diagnosis, cataract evaluation, age-related macular degeneration, and diabetic retinopathy screening. Glaucoma and diabetic retinopathy applications are witnessing particularly high demand, driven by the rising prevalence of these conditions.

Understanding the segmentation outlook helps manufacturers and healthcare providers align their strategies to target high-demand areas, improve patient outcomes, and support market growth. As technology continues to evolve and awareness increases, the ophthalmic diagnostic equipment market is expected to maintain its upward trajectory.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube