General Anesthesia Drugs Market to Surpass USD 6.2 Billion by 2035, Growing at 2.9% CAGR

The general anesthesia drugs market plays a crucial role in modern surgical practices, enabling safe and pain-free procedures for patients undergoing various operations. General anesthesia drugs are administered to induce a reversible loss of consciousness, allowing for complex surgical interventions without causing discomfort or awareness to the patient. These drugs include agents administered intravenously or via inhalation, which act quickly and are tightly controlled to ensure both effectiveness and safety during medical procedures.

Market size, by our current day estimates, would go up from an estimated value of approximately USD 5.2 Billion during the year 2025 to a value substantially exceeding USD 6.2 Billion in the year 2035 at a rate of annual compound growth of 2.9%.

As the global healthcare system continues to advance, the general anesthesia drugs market is experiencing significant growth. This growth is driven by an increase in surgical procedures, advancements in healthcare infrastructure, and a growing aging population requiring frequent medical care. Hospitals, outpatient surgery centers, and specialty clinics all rely on these medications as part of their core service offerings. The demand for general anesthesia drugs has also expanded into dental surgeries and diagnostic procedures, further broadening the scope of their application.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-388

Healthcare providers and anesthesiologists are becoming increasingly particular about the selection of anesthetics, opting for drugs with rapid onset, fewer side effects, and shorter recovery times. This heightened demand for better drug profiles is influencing pharmaceutical companies to innovate and develop improved formulations. The general anesthesia drugs market is consequently positioned as a dynamic and vital component of global healthcare.

Market Trends

Emerging trends within the general anesthesia drugs market indicate a transition toward more tailored and patient-specific anesthetic plans. Healthcare professionals are integrating personalized medicine concepts into anesthesia, considering factors like age, weight, and comorbidities to determine the ideal drug combination and dosage. This trend supports better patient outcomes and minimizes risks associated with adverse reactions or prolonged recovery.

Another trend shaping the general anesthesia drugs market is the increasing use of combination therapies. Anesthesiologists often combine multiple agents to achieve balanced anesthesia—ensuring hypnosis, analgesia, and muscle relaxation—while minimizing the dosage of each individual drug. This strategy helps in reducing side effects and optimizing patient safety. The trend toward multimodal anesthesia management is gaining traction in both developed and emerging healthcare systems.

The rise in ambulatory and day surgeries is also influencing the general anesthesia drugs market. As more procedures shift to outpatient settings, there is a growing preference for fast-acting anesthetic drugs with shorter half-lives. These agents facilitate quicker patient turnover and reduce the length of stay in medical facilities. Pharmaceutical manufacturers are responding by introducing newer agents that allow for faster induction and emergence from anesthesia.

Technological innovations in drug delivery systems and monitoring equipment are also contributing to market expansion. The ability to precisely control drug administration and monitor vital signs in real-time improves safety and efficacy. These advancements support the continued growth of the general anesthesia drugs market across a range of surgical disciplines.

Challenges and Opportunities

Despite promising growth prospects, the general anesthesia drugs market faces several challenges. One significant issue is the potential for drug shortages, often due to disruptions in supply chains or manufacturing delays. Shortages can delay surgeries and put patient care at risk, emphasizing the need for more robust production and distribution systems. Regulatory hurdles and stringent approval processes for new drugs also pose obstacles for manufacturers seeking to bring innovative anesthetics to market.

Safety concerns related to the use of general anesthesia drugs remain a critical challenge. These drugs can have adverse effects, particularly in patients with pre-existing medical conditions or in pediatric and geriatric populations. Anesthesia-related complications, although rare, continue to be a concern and require careful preoperative assessment and drug selection.

Despite these challenges, the general anesthesia drugs market is rife with opportunities. The rise in minimally invasive surgical techniques, which often require general anesthesia, is expanding the scope of application. Additionally, increased investment in healthcare infrastructure in emerging markets is opening new avenues for growth. As more hospitals and clinics are established in these regions, the demand for reliable anesthetic drugs is expected to surge.

Ongoing research into novel drug formulations presents another opportunity. Efforts to develop anesthesia drugs with fewer side effects, better recovery profiles, and enhanced patient tolerance are gaining momentum. Pharmaceutical companies investing in research and clinical trials are well-positioned to capitalize on these market dynamics.

Key Points:

A key advantage of the general anesthesia drugs market is its foundational role in surgical medicine. Without general anesthesia, many procedures would be impractical or impossible to perform safely. The consistent demand for these drugs ensures a stable market environment, even as specific products or practices evolve.

Another important aspect is the shift toward sustainability and efficiency. Healthcare systems are under pressure to reduce costs while maintaining high-quality care. Anesthetic drugs that support rapid recovery and minimize postoperative complications contribute to this goal, making them attractive to providers and patients alike.

Global health trends such as aging populations and rising chronic disease prevalence are fueling the need for more surgeries, further increasing demand in the general anesthesia drugs market. From cardiac procedures to orthopedic surgeries, anesthesia remains a critical component of modern medical intervention.

Key Regional Insights

Geographically, the general anesthesia drugs market demonstrates varied growth patterns. North America holds a leading position due to advanced healthcare infrastructure, a high volume of surgical procedures, and strong pharmaceutical research and development. The United States, in particular, contributes significantly to the market through well-established hospital networks and specialist surgical centers.

Europe follows closely, with countries like Germany, France, and the United Kingdom investing heavily in healthcare modernization and innovation. Regulatory agencies such as the European Medicines Agency (EMA) support the development and approval of new anesthetic drugs, ensuring a steady influx of advanced treatment options.

The Asia-Pacific region is emerging as a powerful growth engine in the general anesthesia drugs market. Rapid urbanization, increased healthcare access, and growing awareness of surgical care are fueling demand in countries such as China, India, and Japan. These nations are witnessing increased surgical procedures across specialties, supported by government initiatives aimed at expanding healthcare coverage.

Latin America, the Middle East, and Africa represent promising but underdeveloped markets. Infrastructure challenges and limited access to healthcare remain barriers; however, ongoing efforts to improve medical facilities and training are gradually unlocking the market potential in these regions.

Competitive Outlook

The general anesthesia drugs market is characterized by intense competition, with numerous pharmaceutical companies striving to gain market share through innovation, strategic partnerships, and geographic expansion. Established players continue to invest in product development and regulatory compliance to maintain their competitive edge.

Generic competition also plays a role in shaping the market. As patents expire on older drugs, generic manufacturers enter the field with cost-effective alternatives. While this can reduce prices and increase accessibility, it also pressures brand-name manufacturers to innovate or differentiate their products through formulation improvements.

Key players in the general anesthesia drugs market are also exploring partnerships with healthcare providers to enhance distribution and training. By working closely with hospitals and clinics, these companies can ensure their products are used effectively and safely. Additionally, they are investing in digital marketing and education campaigns to raise awareness among medical professionals about the latest advancements in anesthesia.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/general-anesthesia-drugs-market

Top Companies

  • Roche – Innovates in IV anesthetics and pain management drugs for a variety of surgical application
  • Pfizer – Offers injectable anesthetic agents with a focus on high-quality generics and clinical safety.
  • Novartis – Develops anesthetic solutions for critical care environments and pain management.
  • Lundbeck – Known for sedative and hypnotic agents, expanding into neurological anesthesia drugs.
  • AbbVie – Focuses on anesthesia agents for minor and major surgeries, offering safe and efficient sedation options.

Segmentation Outlook

The general anesthesia drugs market can be segmented based on drug type, route of administration, and end-user. In terms of drug type, the market includes inhalational agents, such as sevoflurane and desflurane, and intravenous agents like propofol and ketamine. Each drug type has specific use cases based on the procedure and patient profile.

Route of administration is another key segmentation criterion, with intravenous and inhalation routes dominating. Intravenous administration is preferred for rapid induction, while inhalational agents are often used for maintenance of anesthesia during longer procedures.

End-users include hospitals, ambulatory surgery centers, and clinics. Hospitals are the largest segment due to the volume of surgeries performed and the need for a broad spectrum of anesthetic agents. Ambulatory centers are becoming more prominent as day surgeries increase, influencing demand for fast-acting anesthetic drugs.

Understanding these segments allows stakeholders to align strategies with specific market needs and optimize their offerings to cater to different healthcare environments. Each segment presents unique growth opportunities and challenges that must be addressed to succeed in the competitive general anesthesia drugs market.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Global Dental Adhesives Market Set to Reach USD 3.58 Billion by 2032, Driven by Innovation in Restorative Dentistry | FMI

The global dental adhesives market is poised for significant growth over the next decade, with a projected valuation of approximately USD 3.58 billion by 2032, rising from USD 2.31 billion in 2022. This expansion, forecasted at a compound annual growth rate (CAGR) of 4.5%, highlights the increasing adoption of dental adhesives across both restorative and denture-related procedures, according to the latest research by Future Market Insights.

Dental adhesives, particularly restorative adhesives, are leading the market with a substantial share of 64.9% as of 2021. These adhesives play a critical role in modern dentistry, offering durable and reliable bonding solutions for restorative procedures such as enamel etching, dentin adhesion, and the placement of resin-based composite materials.

Stay Informed on Key Market Changes: Get a Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15784

Driving Forces Behind Market Growth

One of the primary contributors to this market growth is the increased demand for minimally invasive restorative dental procedures. As patient awareness and preference for esthetic, non-invasive treatments grow, dental professionals are increasingly turning to advanced adhesive systems to improve clinical outcomes and patient comfort.

Denture adhesives are also seeing widespread adoption due to their non-toxic, water-soluble formulations, which help stabilize dentures and prevent movement during daily activities like speaking, sneezing, or coughing. Their ease of use and effectiveness in enhancing denture retention and comfort further bolster market demand.

Moreover, the rise in the aging population, particularly in North America and Europe, is contributing to the increasing demand for dental prosthetics and associated adhesive solutions. With age, natural tooth loss becomes more prevalent, fueling the need for dentures and related adhesives.

Challenges Hindering Market Expansion

Despite its promising outlook, the dental adhesives market faces several constraints. Rising dental care costs remain a major concern, particularly in low- and middle-income regions where accessibility to dental care remains limited. This cost barrier could hinder market penetration and limit the adoption of advanced adhesive technologies.

A crucial challenge in this market is ensuring the biocompatibility and safety of dental materials. While most adhesives are considered safe, there have been concerns about prolonged use, especially formulations containing zinc. The U.S. FDA has documented adverse events including nerve damage, numbness, and tingling, linked to overuse or misuse of zinc-based denture adhesives.

Furthermore, stringent regulatory requirements across various countries pose a significant hurdle. These include time-consuming approval processes for new materials and the need for extensive clinical validation, which may delay product launches and hinder innovation cycles.

Key Takeaways: Global Dental Adhesives Market Insights

  • USA Leads North America: Holding a dominant 82.0% market share in 2021, the U.S. dental adhesives market continues to thrive due to increasing dental awareness and a rising trend in cosmetic procedures.
  • UK’s Stronghold in Europe: With a 26.1% market share in 2021, the UK is set for continued growth. High demand stems from ill-fitting dentures, cosmetic needs, and prevalent oral health conditions.
  • Japan’s Aging Population Drives Demand: Capturing 33.9% of East Asia’s market in 2021, Japan’s growing elderly demographic is pushing demand for dentures and consequently, dental adhesives.
  • India Emerges as a High-Growth Market: Accounting for 28.6% of South Asia’s market share and valued at USD 95.7 million in 2021, India’s surge is fueled by rising cosmetic dentistry trends and rapid tech adoption in dental care.
  • Restorative Adhesives Dominate: Representing 64.9% of global market share in 2021, restorative adhesives continue to grow with a projected CAGR of 4.6%, thanks to their versatility and advancements in biocompatibility.
  • Liquid Formulations Preferred Globally: These held 30.0% of the market in 2021, favored for their ease of use in both restorations and denture fittings, and expected to grow at a CAGR of 6.4%.
  • Dental Clinics Drive Sales: Leading the distribution channel with 40.3% market share in 2021, clinics remain the primary point of use due to increased dental awareness and the volume of restorative and orthodontic procedures.

Increased Market Attention: Delve into Detailed Trends and Analysis with Our Report! https://www.futuremarketinsights.com/reports/dental-adhesives-market

Competitive Landscape and Key Developments

The dental adhesives market is highly fragmented, with numerous players competing on innovation, product differentiation, and regional presence. Leading companies are actively engaged in strategic expansions, partnerships, and product launches to consolidate their market positions.

Noteworthy developments include:

  • Ultradent Products, Inc., a global innovator in dental materials, launched its South Korean subsidiary—Korea Ultradent Products LLC—in April 2022. This move is part of its strategic expansion to tap into the Asia-Pacific dental market, aiming to improve product accessibility and customer service in the region.

Other prominent players shaping the global dental adhesives landscape include:

  • 3M
  • Dentsply Sirona Inc.
  • GlaxoSmithKline PLC
  • Procter & Gamble Co.
  • Henkel AG & Co. KGaA
  • Johnson & Johnson Services Inc.
  • Mitsui Chemicals Inc.
  • Colgate-Palmolive Company
  • Ivoclar Vivadent AG
  • Tokuyama Dental Corporation Inc.
  • Den-Mat Holdings LLC
  • Prime Dental Manufacturing
  • New World Imports

These companies are focusing on expanding their product portfolios, investing in R&D, and leveraging partnerships to gain competitive advantages in both mature and emerging markets.

Market Segmentation Overview

By Product:

  • Denture Adhesives – used for temporary or semi-permanent denture fixation.
  • Restorative Adhesives – applied in procedures like crown bonding, cavity filling, and orthodontic bracket luting.

By Formulation:

  • Creams
  • Powders
  • Liquid
  • Others

By Distribution Channel:

  • Dental Clinics
  • Hospitals
  • Dental Academic and Research Institutes
  • Others

By Region:

  • North America – continues to lead due to technological advancements and high dental care awareness.
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East & Africa (MEA)

The regional dynamics show strong market potential in Asia-Pacific, driven by growing dental tourism, increasing healthcare investments, and a rapidly expanding middle class with better access to dental care.

Future Outlook

The dental adhesives market is set to evolve rapidly, fueled by innovations in adhesive technology, rising cosmetic dental procedures, and expanding awareness about oral health. While challenges around regulatory compliance and safety remain, proactive industry collaboration and responsible product development are likely to mitigate these issues over time.

As companies continue to invest in biocompatible, high-performance adhesives and strengthen their global distribution channels, the dental adhesives market is poised to become a cornerstone of modern dental care by 2032.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Global At-Home Testing Market on a Robust Growth Trajectory, Forecasted to Surpass USD 11,877.8 Million by 2035 with a CAGR of 4.8% | FMI

The global at-home testing market is poised for remarkable growth, with sales projected to rise from USD 7,789.1 million in 2025 to USD 11,877.8 million by 2035, according to recent market analysis. The market, which generated USD 7,432.3 million in revenue in 2024, is set to expand at a compound annual growth rate (CAGR) of 4.8% over the forecast period of 2025-2035.

This growth is attributed to the increasing consumer preference for self-diagnostic tools that provide quick, convenient, and reliable health monitoring solutions. The shift in healthcare dynamics, further amplified by the COVID-19 pandemic, has made at-home testing a vital component of modern healthcare practices.

Access Key Market Insights: Request a Sample Report Now! https://www.futuremarketinsights.com/reports/sample/rep-gb-15779

A report from the Centers for Disease Control and Prevention (CDC) highlighted this trend, noting that U.S. adults actively utilized at-home COVID-19 tests between August 2021 and March 2022. The adoption of such tools was particularly notable among individuals experiencing COVID-19-like symptoms, reflecting a growing consumer inclination toward accessible self-diagnostic options.

The rising demand for at-home testing solutions aligns with a broader shift toward personalized healthcare. Consumers are prioritizing health management solutions that are easy to use and deliver quick results without requiring visits to healthcare facilities. Technological innovations in diagnostic tools are driving this market evolution, addressing a wide range of health needs from infectious diseases to chronic condition monitoring.

As the at-home testing market continues to expand, it presents substantial opportunities for manufacturers and stakeholders to innovate and cater to the evolving needs of consumers. The growing focus on patient-centric healthcare solutions ensures that at-home testing will remain a significant trend in the years to come.

Key Takeaways: Global At-Home Testing Market

  1. Market Growth:
    • The global sales of at-home testing are estimated at USD 7,789.1 million in 2025 and projected to reach USD 11,877.8 million by 2035, reflecting a CAGR of 4.8% from 2025 to 2035.
    • Revenue in 2024 was recorded at USD 7,432.3 million.
  2. Regional Performance:
    • United States: Expected to grow at a 5% CAGR (2025–2035).
    • Germany: Anticipated to exhibit a 6% CAGR (2025–2035).
    • France: Predicted to grow at a robust 4% CAGR (2025–2035).
    • UK: Estimated to see a 7% CAGR (2025–2035).
  3. Emerging Markets:
    • India: Foreseen as a high-growth market with a 4% CAGR (2025–2035).
    • China: Projected to grow at a strong 8% CAGR (2025–2035).

This growth underscores increasing consumer demand for convenient, reliable, and accessible at-home diagnostic solutions globally.

“At-home testing offers unparalleled convenience and empowers individuals to take proactive steps in managing their health, Advancements in diagnostic technology have significantly enhanced the accuracy and reliability of these tests, making them an integral part of the global healthcare landscape. As consumer awareness and confidence in self-diagnostic tools increase, we expect sustained market growth,” said says Sabyasachi Ghosh Associate Vice President at Future Market Insights (FMI) analyst.

Demand for Market Analysis: Our Comprehensive Report Offers Detailed Trends and Insights! https://www.futuremarketinsights.com/reports/at-home-testing-market

Competitive Landscape:

The at-home testing market remains fiercely competitive, with established leaders and emerging players striving to gain market share. Key industry leaders focus on delivering innovative solutions by partnering with prominent players, leveraging advanced technologies and user-friendly designs. Many competitors integrate smart technology into their offerings, enabling seamless connectivity with mobile apps and cloud-based platforms for real-time data tracking and monitoring.

Recent Industry Developments in the At-Home Testing Market:

  • In October 2024, LetsGetChecked, a global leader in healthcare solutions, announced the acquisition of Truepill, a prominent digital pharmacy platform. This strategic move enhances LetsGetChecked’s capabilities to support healthcare partners—including employers, health plans, providers, and life sciences—in delivering high-quality care and improving health outcomes for diverse populations.

Key Players of At-Home Testing Industry:

  • Abbott Laboratories
  • OraSure Technologies, Inc.
  • Everlywell
  • LetsGetChecked
  • iHealth Labs Inc.
  • Clearblue (SPD Swiss Precision Diagnostics GmbH)
  • Bionime Corporation
  • ACON Laboratories, Inc.
  • Siemens Healthineers
  • Lucira Health

Key Segments of At-Home Testing Industry:

By Product Type:

In terms of service, the industry is divided into digital monitoring instruments, cassettes, midstream, strips, cups, dip cards, test panels, sample collection kits and others.

By Application:

In terms of application, the industry is divided into blood glucose testing, pregnancy & fertility testing, cancer testing, STD/ STI testing (chlamydia and gonorrhoea, HIV testing) testosterone, drug abuse testing, cholesterol testing, thyroid testing and others.

By Sample:

In terms of sample, the industry is divided into urine, blood, saliva, stool, vaginal swab, and semen.

By Distribution Channel:

In terms of distribution channel, the industry is segregated into drug stores, hospital pharmacies and online channels

By Region:

Key countries of North America, Latin America, East Asia, South Asia & Pacific, Western Europe, Eastern Europe, and Middle East and Africa (MEA) have been covered in the report.

Explore FMI’s Related Ongoing Coverage on Healthcare Market Insights Domain:

The global sales of stent graft balloon catheters are estimated to be worth USD 1,047.9 million in 2025 and are anticipated to reach a value of USD 2,194.9 million by 2035. Sales are projected to rise at a CAGR of 6.8% over the forecast period between 2025 and 2035.

The global IoT in healthcare market trends is estimated to be worth USD 243.40 billion in 2025 and is projected to grow at a CAGR of 15.3%, surpassing USD 1 trillion by 2035.

The global alopecia treatment market strategies is estimated to be worth USD 12.5 Billion in 2025 and is anticipated to reach a value of USD 30.5 Billion by 2035. The market is projected to rise at a CAGR of 9.4% over the forecast period between 2025 and 2035.

The global human respiratory syncytial virus (RSV) treatment market outlook is estimated to be worth USD 1,920.3 million in 2025 and anticipated to reach a value of USD 3,969.3 million by 2035. Sales are projected to rise at a CAGR of 7.5% over the forecast period between 2025 and 2035.

The endoscope reprocessing device market overview is estimated to reach USD 2.68 billion in 2025. It is anticipated to grow at a CAGR of 7.3% during the assessment period and reach a value of USD 4.94 billion by 2035.

The global eye infections treatment market opportunity is estimated to be worth USD 8,125.2 million in 2025 and anticipated to reach a value of USD 11,890.2 million by 2035. Sales are projected to rise at a CAGR of 3.9% over the forecast period between 2025 and 2035.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Automated Breast Ultrasound Systems Market to Reach USD 5.42 Billion by 2035, Growing at 8.9% CAGR

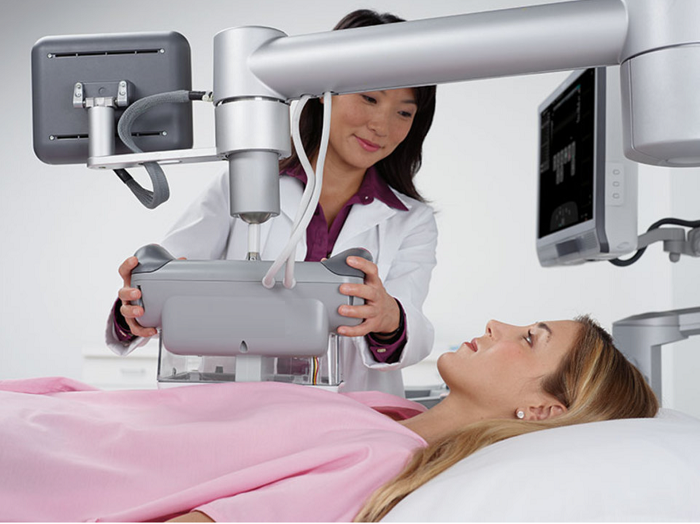
In 2025, the market was valued at approximately USD 2,312.5 million and is projected to reach USD 5,424.6 million by 2035, reflecting a compound annual growth rate (CAGR) of 8.9% during the forecast period. The global automated breast ultrasound systems (ABUS) market is poised for significant growth between 2025 and 2035, driven by increasing awareness of breast cancer screening, technological advancements in imaging, and the rising prevalence of breast cancer.

The automated breast ultrasound systems market has gained significant attention in recent years due to its growing role in the early detection and diagnosis of breast cancer. As breast cancer remains one of the leading causes of mortality among women worldwide, the demand for more precise and reliable imaging techniques is on the rise. Automated breast ultrasound systems (ABUS) have emerged as a powerful alternative to traditional methods, especially for women with dense breast tissue, where conventional mammography may fall short.

The automated breast ultrasound systems market is propelled by the technology’s ability to provide high-resolution, three-dimensional images, enhancing diagnostic accuracy. These systems are non-invasive, radiation-free, and relatively cost-effective, which makes them suitable for both diagnostic centers and hospital settings. As healthcare providers focus more on early cancer detection and patient comfort, ABUS continues to witness increased adoption across various medical environments.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-606

Size & Trends

The automated breast ultrasound systems market is expanding rapidly, driven by technological advancements, increasing cancer awareness, and supportive government initiatives. Market trends indicate that more healthcare facilities are incorporating ABUS into their breast cancer screening programs, especially in regions where dense breast tissue prevalence is high. This growing adoption is also influenced by the rise in female health check-up programs and the availability of funding for breast cancer research.

The market is witnessing a trend toward miniaturization and portability, with companies focusing on developing compact systems that offer the same level of diagnostic clarity as larger machines. This trend is particularly useful for mobile screening units, rural clinics, and emerging economies where healthcare infrastructure is still developing. Additionally, there is an increasing demand for systems that integrate seamlessly with hospital information systems and radiology workflows, improving data storage and retrieval efficiency.

Artificial intelligence is another trend reshaping the automated breast ultrasound systems market. AI-driven software solutions are being integrated to assist radiologists in interpreting results more quickly and accurately. These tools can detect abnormalities that may be missed during manual interpretation, thus reducing diagnostic errors and enhancing patient care.

Challenges and Opportunities

While the automated breast ultrasound systems market shows significant promise, it is not without its challenges. One of the primary hurdles is the high initial cost of purchasing and maintaining ABUS equipment. For small and medium-sized healthcare providers, the capital investment required can be a deterrent. Additionally, the reimbursement landscape for ABUS is still evolving, with coverage varying across regions and insurance providers, which may slow down adoption rates.

Another challenge is the limited number of trained professionals who can efficiently operate and interpret results from automated breast ultrasound systems. Although these systems are designed to be user-friendly, achieving consistent diagnostic outcomes still relies on skilled technicians and radiologists. Lack of adequate training programs could hinder market penetration in some areas.

Despite these challenges, the automated breast ultrasound systems market offers numerous opportunities for growth. Increasing awareness about the limitations of mammography, particularly in women with dense breast tissue, is creating a demand for complementary screening technologies like ABUS. Governments and non-profit organizations are also launching initiatives to improve breast cancer screening accessibility, which further supports market growth.

The rise of telemedicine and digital health solutions opens new avenues for the automated breast ultrasound systems market. Remote screening and diagnostics can benefit from portable ABUS devices, particularly in underserved areas. Additionally, ongoing research into improving image quality and processing speeds presents an opportunity for manufacturers to differentiate their products and gain a competitive edge.

Key Benefits for Stakeholders

The automated breast ultrasound systems market offers a wide range of benefits for stakeholders across the healthcare ecosystem. For patients, the most significant advantage is early and accurate breast cancer detection, especially in those with dense breast tissue. The non-invasive and radiation-free nature of ABUS makes it a safer option for repeated screenings, enhancing patient compliance and comfort.

Healthcare providers benefit from the operational efficiency and diagnostic reliability that automated breast ultrasound systems offer. These systems reduce the workload on radiologists by automating the image acquisition process and providing standardized images that are easier to interpret. This consistency not only improves diagnostic accuracy but also allows for better patient management and treatment planning.

Manufacturers and technology developers also gain from the growing interest in breast health diagnostics. As demand for automated breast ultrasound systems increases, there is greater opportunity to innovate, expand product lines, and explore new markets. Collaborations with healthcare institutions and research bodies enable these companies to refine their technologies and gain regulatory approvals more efficiently.

Policymakers and healthcare regulators benefit from improved public health outcomes and reduced long-term healthcare costs. Early detection of breast cancer through reliable screening methods can lead to earlier treatment interventions, lowering mortality rates and reducing the economic burden of late-stage cancer care.

Market Share by Geographical Region

The automated breast ultrasound systems market demonstrates varied performance across different geographical regions. North America holds a significant share of the market due to its advanced healthcare infrastructure, high awareness levels, and favorable reimbursement policies. The United States, in particular, has been at the forefront of adopting ABUS technology, supported by a strong presence of leading medical device companies and active participation in breast cancer screening programs.

Europe follows closely, with countries like Germany, France, and the United Kingdom driving growth in the region. Government-led initiatives to promote breast cancer awareness and early detection are fueling the demand for automated breast ultrasound systems. European healthcare providers are increasingly incorporating ABUS into their diagnostic routines, recognizing its advantages over traditional imaging methods.

The Asia-Pacific region is witnessing rapid growth in the automated breast ultrasound systems market. Countries such as China, Japan, and India are investing heavily in healthcare modernization and cancer prevention programs. The rising prevalence of breast cancer and growing awareness among women are encouraging the adoption of ABUS technology in this part of the world.

Latin America, the Middle East, and Africa are also emerging markets with considerable potential. While adoption is currently lower due to infrastructural and financial constraints, ongoing improvements in healthcare accessibility and awareness campaigns are expected to drive growth in these regions over time.

Competitive Outlook

The automated breast ultrasound systems market is highly competitive, with several major players vying for market share through product innovation, strategic partnerships, and geographic expansion. These companies are focusing on developing user-friendly systems that offer superior image quality, faster scanning times, and integration with digital health platforms.

Leading manufacturers are investing in research and development to incorporate advanced features such as artificial intelligence, machine learning, and cloud-based data management. These enhancements improve diagnostic precision and streamline workflow, making ABUS systems more appealing to a broader range of healthcare providers.

In addition to product innovation, companies are also engaging in strategic collaborations with hospitals, diagnostic centers, and academic institutions to validate their technologies and expand their market presence. Regulatory approvals from agencies such as the FDA and CE marking in Europe are critical milestones that companies aim to achieve to ensure credibility and compliance.

After-sales support, training programs, and user education are becoming key differentiators in the automated breast ultrasound systems market. Companies that offer comprehensive support packages are more likely to succeed in building long-term relationships with customers and establishing a strong market presence.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/automated-breast-ultrasound-system-market

Top Companies

The automated breast ultrasound systems market features several prominent companies that are leading the way in innovation and market expansion. These top players have a robust product portfolio, a strong global presence, and a track record of clinical validation. They continuously upgrade their technologies based on user feedback and technological advancements to maintain their competitive edge.

Many of these companies are also exploring mergers, acquisitions, and joint ventures to strengthen their positions in emerging markets and gain access to new customer bases. Their focus on research, development, and collaboration ensures that they remain at the forefront of the evolving ABUS landscape.

Segmentation Outlook

The automated breast ultrasound systems market can be segmented based on end-user, application, and product type. End-users typically include hospitals, diagnostic imaging centers, and specialty clinics. Hospitals remain the largest segment, driven by their capacity to invest in advanced diagnostic technologies and their comprehensive cancer care services.

By application, the market is segmented into screening and diagnostics. Screening applications are growing rapidly due to rising awareness and the implementation of population-based breast cancer screening programs. Diagnostic applications remain essential for confirming abnormalities detected during initial screenings or self-examinations.

In terms of product type, cart-based and hand-held systems are the two primary categories. Cart-based systems dominate in large healthcare settings, while hand-held ABUS devices are gaining popularity for their portability and use in outpatient clinics or remote areas.

Geographic segmentation helps manufacturers tailor marketing strategies and product development based on regional needs. Understanding local regulatory environments, healthcare infrastructure, and cultural attitudes toward breast cancer screening is crucial for effective market penetration and sustained growth.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube


Global Teledentistry Market Set to Skyrocket to USD 6.56 Billion by 2032, Fueled by Digital Healthcare Demand and Post-Pandemic Innovation | FMI

The global teledentistry market, valued at USD 1.45 Billion in 2022, is set for explosive growth, projected to reach USD 6.56 Billion by 2032, registering a CAGR of 16.3% over the forecast period. This remarkable growth is underpinned by increasing demand for cost-effective dental care, the expansion of mobile health (mHealth) practices, and the growing digital connectivity in emerging economies.

The COVID-19 pandemic proved to be a pivotal moment for teledentistry. With face-to-face dental procedures carrying a high risk of infection due to the aerosol-based transmission of viruses, virtual consultations surged in popularity. This shift opened a new frontier for oral care delivery, emphasizing safety, accessibility, and innovation.

Keep Up with Market Trends: Access Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-12168

A Paradigm Shift in Dental Healthcare Delivery

The pandemic accelerated the digital transformation of the dental industry. Teledentistry services reduced in-person visits and helped maintain continuity of care without compromising safety. These services proved particularly crucial in rural and underserved communities, where traditional dental infrastructure is limited.

Remote consultations, telemonitoring, and virtual diagnostics have now become integral parts of the dental healthcare ecosystem. The rise of cloud-based solutions, smartphone integration, and IoT applications in dental practices has made teledentistry a sustainable and scalable solution even beyond the pandemic era.

Technological Versatility Fueling Market Expansion

The adaptability of telemedicine technologies—especially those used in teledentistry—has expanded its applications far beyond consultations. Modern platforms now support dental education, treatment monitoring, and real-time diagnostics from any location.

Innovative companies like Toothpick have introduced round-the-clock access to licensed dentists worldwide. Reports indicate that over 75% of dentists have deemed their teledentistry platforms successful, highlighting their validity, convenience, and cost-saving potential.

Key Takeaways: Teledentistry Market Growth Highlights

  1. North America Leads with IoT Integration and Oral Health Focus
    • North America’s teledentistry market is thriving due to increased adoption, strong public-private initiatives in oral healthcare, and the integration of Internet of Things (IoT) technologies enhancing remote dental treatment capabilities.
  2. Asia Pacific Gains Momentum Through Government Support and Tech Penetration
    • Government-led digital health initiatives and the rise of 5G and IoT technologies are improving access to teledentistry in rural and underdeveloped areas of Asia Pacific, particularly boosting market potential in India.
  3. USA Commands Dominance with Tech Advancements and Strong IT Infrastructure
    • The U.S. holds approximately 40% of the teledentistry market share (2022), fueled by the presence of leading players, robust healthcare IT investment, and increasing public awareness about virtual dental care.
  4. India Witnesses Rapid Growth with Mobile-Driven Remote Care
    • India is projected to achieve the fastest CAGR, expected to hold 35% of the market share (2022), due to growing demand for remote dental services and rising healthcare investments.
  5. Software and Services Segment Steers Market with IoT-Driven Demand
    • With a 73% market share (2022), the software and services segment dominates, driven by wireless connectivity and IoT integration. The hardware segment is also gaining traction through innovations like smart toothbrushes.
  6. Cloud-Based Technology Gains Preference for Data Accessibility
    • Cloud-based teledentistry platforms, offering secure data storage and easy access, are expected to claim 65% of the market share (2022), with web-based platforms seeing notable growth due to smartphone penetration in rural areas.
  7. Teleconsultation Emerges as Preferred Mode Post-Pandemic
    • Capturing 55% of the market share (2022), teleconsultation has seen accelerated growth due to COVID-19-driven digital healthcare transitions. Remote patient monitoring is expected to grow at a CAGR of 16.6% (2022–2032).
  8. Healthcare Providers Driving Market Adoption Through Efficient Data Use
    • Dental providers dominate the user base with over 45% market share (2022), benefiting from enhanced data access and real-time reporting. However, patient-driven growth is accelerating with increasing smartphone and internet use.

Soaring Demand for Market Information: Uncover Detailed Trends and Insights in Our Report! https://www.futuremarketinsights.com/reports/teledentistry-market

Market Landscape: Innovation and Strategic Alliances Driving Competition

The teledentistry market is witnessing intense competition, with key players introducing cutting-edge platforms and forming strategic alliances. Notable industry names include:

  • Koninklijke Philips N.V.
  • Align Technology, Inc.
  • SmileDirectClub
  • MouthWatch, LLC
  • Dentulu, Inc.
  • Denteractive Solutions Inc.
  • Toothpick
  • Smile Virtual LLC
  • Virtudent, Inc.
  • Straight Teeth Direct

A landmark collaboration between Koninklijke Philips N.V. and Toothpick in May 2020 exemplifies the kind of innovation shaping the industry’s future. Their joint teledentistry platform aims to deliver high-quality care remotely, supporting Philips’ Sonicare product line with Toothpick’s network of global dental professionals.

Key Segments Profiled in the Teledentistry Industry Survey

By Component:

  • Software & Services
  • Hardware

By Delivery Mode:

  • Cloud-based
  • Web-based

By Application:

  • Tele-consultation
  • Remote Patient Monitoring
  • Education & Training

By End Use:

  • Providers
  • Patients
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East & Africa (MEA)

Future Outlook: Teledentistry Is Here to Stay

As digital health technologies continue to evolve, the teledentistry market is well-positioned for sustainable growth. Government support, rising healthcare digitization, and consumer demand for safer, accessible oral care are expected to bolster this transformation.

The teledentistry revolution is redefining how oral care is delivered, ensuring that quality dental services are just a click away—whether you’re in a city or a remote village.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Asia Pacific Dental Industry Poised for Strong Growth, Projected to Reach USD 18,235.6 Million by 2034 rise at 5.2% CAGR | FMI

The Apac dental industry is experiencing remarkable growth, driven by demographic shifts, evolving lifestyle habits, technological innovation, and rising awareness of oral health. According to the latest market research, the dental market in the Asia Pacific region reached USD 10,518.7 million in 2023 and is projected to grow at a compound annual growth rate (CAGR) of 5.2% through 2034. The market is forecasted to climb from USD 11,139.8 million in 2024 to an impressive USD 18,235.6 million by 2034.

Demographic and Lifestyle Shifts Fueling Demand

One of the primary drivers of this market surge is the rapidly aging population in Asia Pacific. As people age, the prevalence of dental issues such as tooth decay, gum disease, and tooth loss increases significantly. Coupled with this demographic trend, the high burden of oral diseases—including cavities, periodontal diseases, and oral cancers—continues to exert pressure on the dental healthcare system across the region.

Discover How Market Trends Are Shaping Industries: Access Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15767

Furthermore, lifestyle choices such as smoking, poor diet, and excessive alcohol consumption are exacerbating oral health problems, particularly in urban centers. These habits, along with stress-induced conditions like bruxism (teeth grinding) and temporomandibular joint (TMJ) disorders, are contributing to increased demand for both preventive and restorative dental care services.

Technological Advancements Reshaping the Industry

The adoption of cutting-edge technologies is revolutionizing dental practices across Asia Pacific. Innovations in digital dentistry, including CAD/CAM systems, 3D printing, and advanced dental imaging solutions like Cone Beam Computed Tomography (CBCT), are enabling more precise diagnostics, minimally invasive procedures, and faster treatment times. This has significantly enhanced patient outcomes and satisfaction.

Cosmetic dentistry is another rapidly growing segment, fueled by the increasing demand for aesthetic procedures such as teeth whitening, dental veneers, and aligners. The desire for a perfect smile is no longer limited to the Western world, with a growing number of consumers in Asia Pacific investing in elective cosmetic dental treatments.

Public Awareness and Access to Care on the Rise

Greater awareness regarding the importance of oral hygiene and preventive care is encouraging more individuals to seek regular dental checkups and early intervention. Public health campaigns, educational initiatives, and improved access to dental care services—especially in emerging markets like India, Indonesia, and the Philippines—are contributing to this trend.

However, access disparities remain a concern in rural and underdeveloped regions, where many individuals still suffer from untreated dental issues due to inadequate infrastructure or lack of awareness. Bridging this gap presents a significant opportunity for both public and private stakeholders.

Growing Need for Market Insights: Access Our Full Report for Thorough Analysis and Trends! https://www.futuremarketinsights.com/reports/apac-dental-market

Key Takeaways

  • China is projected to lead regional growth with a CAGR of 6.4% from 2024 to 2034, followed by India (5.8%) and Indonesia (5.4%).
  • Among end users, Dental Clinics are expected to grow steadily at a CAGR of 4.4%.
  • Consumables emerge as the fastest-growing product segment with a CAGR of 5.0%.
  • Within applications, the Treatment segment is projected to expand at a CAGR of 4.3% over the forecast period.
  • Strong market momentum is evident across Asia-Pacific, driven by rising dental care awareness and increasing healthcare infrastructure investments.

Competitive Landscape and Key Strategies

The Asia Pacific dental market is highly competitive, with leading global and regional players focusing on innovation, strategic partnerships, and capacity expansion to strengthen their market position. Product launches remain a key strategy to demonstrate technological prowess and address evolving consumer needs.

For instance, in April 2023, ZimVie Inc. introduced RegenerOss® CC allograft particulate, a novel biomaterial comprising a blend of cortical and cancellous bone particles aimed at supporting dental bone regeneration. Similarly, in May 2023, Philips launched the Philips CT 3500, a high-throughput CT imaging system designed to meet the needs of routine radiology and large-scale dental screenings.

Companies like 3M Company, Dentsply Sirona, Ivoclar Vivadent AG, Ultradent Products Inc., STRAUMANN GROUP, and Henry Schein, Inc. continue to invest in R&D, expand their manufacturing capabilities, and explore inorganic growth through mergers, acquisitions, and collaborations.

Extensive Product Segmentation Reflects Broad Scope

The Asia Pacific dental industry encompasses a wide range of products and services categorized by product type, application, and end user:

By Product:

  • Equipment: Dental radiology (extra/intra-oral), CBCT, lasers (soft tissue, gas, diode), systems (chairs, hand pieces, scaling units, light cure), and CAD/CAM systems.
  • Instruments: Air polishing devices, dental scalers, burs.
  • Consumables: Including orthodontics (braces, bands, wires, retainers), endodontics (sealers, files, obturation devices), hygiene maintenance products (sterilizers, air purification, incinerators), whitening, crowns & bridges, implants, prosthetics, and sealants.

By Application:

  • Diagnostics
  • Surgical
  • Treatment

By End User:

  • Hospitals
  • Dental Support Organizations (DSOs)
  • Dental Clinics
  • Dental Laboratories

By Country:

  • China
  • Japan
  • South Korea
  • India
  • Philippines
  • Malaysia
  • Thailand
  • Indonesia
  • Singapore
  • Rest of South Asia

Get Your Hands on Healthcare Market Projections Now! https://www.futuremarketinsights.com/industry-analysis/dental-device

Looking Ahead

With robust economic development, increasing healthcare expenditure, and rising oral health consciousness across Asia Pacific, the dental industry is set to undergo significant transformation over the next decade. Stakeholders who prioritize innovation, accessibility, and holistic patient care will be best positioned to capitalize on the growing demand and shape the future of oral health in the region.

As technological innovation continues to intersect with evolving consumer expectations, the Asia Pacific dental market offers a dynamic and highly promising landscape for growth, investment, and strategic development.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Automated CPR Device Market to Grow at 5.4% CAGR, Hitting USD 255.7 Million by 2034

The global Automated CPR Device Market is estimated to be worth USD 150.6 million in 2024 and is projected to reach a value of USD 255.7 million by 2034. Global sales of automated CPR devices are slated to soar at a CAGR of 5.4% over the assessment period.

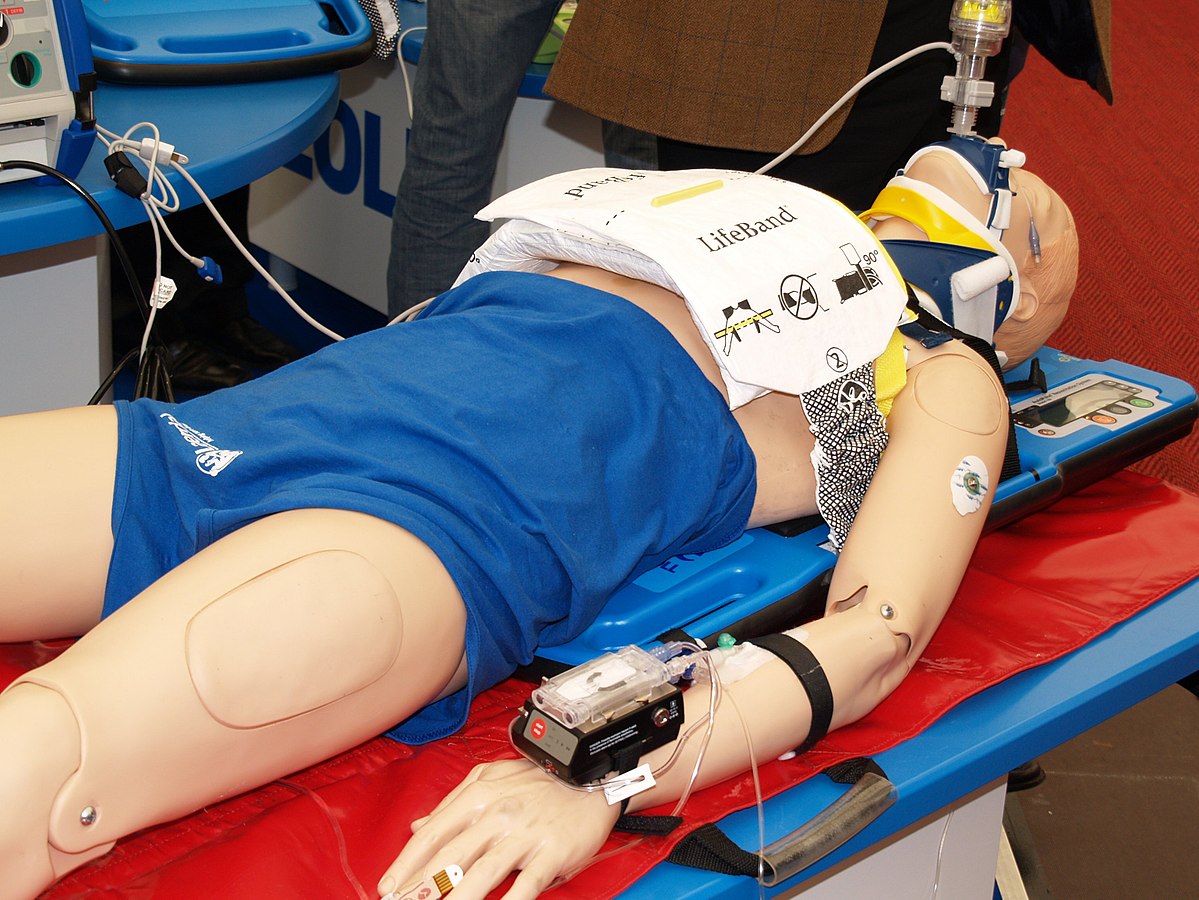
The automated CPR device market has seen significant advancement in recent years due to the critical role that cardiopulmonary resuscitation plays in emergency medical response. Cardiopulmonary resuscitation (CPR) is a lifesaving technique that helps maintain circulatory flow and oxygenation during cardiac arrest. While manual CPR has been the standard for decades, the need for consistent, high-quality chest compressions has led to the development and adoption of automated solutions. These devices are designed to deliver uniform compressions with minimal interruption, reducing the physical burden on medical staff and improving patient outcomes.

Get Sample Report: – https://www.futuremarketinsights.com/reports/sample/rep-gb-720

The automated CPR device market is becoming increasingly vital in both pre-hospital and in-hospital settings. Hospitals, emergency medical services, and ambulances are equipping themselves with automated CPR technology to enhance survival rates during critical cardiac events. These devices are particularly beneficial in high-stress scenarios where maintaining consistent chest compression depth and rate can be challenging for human responders. With advancements in battery technology, portability, and ease of use, automated CPR devices are becoming a standard component in emergency response systems across the globe.

Market Trends

A key trend shaping the automated CPR device market is the integration of intelligent features such as feedback mechanisms, real-time data monitoring, and connectivity to emergency response systems. These enhancements help responders assess the quality of compressions and adjust procedures accordingly. Manufacturers are increasingly incorporating audio-visual prompts and real-time feedback into their devices, ensuring high-quality CPR delivery in every use case.

Another important trend is the miniaturization and portability of automated CPR devices. Lightweight and compact models are becoming more popular, allowing for easier transport and faster deployment during emergencies. This evolution in design is especially significant for use in ambulances, air medical services, and battlefield environments.

The automated CPR device market is also experiencing growth through partnerships between manufacturers and healthcare institutions. Collaborative efforts are focused on conducting clinical trials, gathering performance data, and validating the effectiveness of automated CPR in various clinical settings. These partnerships are crucial for gaining regulatory approvals and expanding the clinical acceptance of these devices.

Driving Forces Behind Market Growth

Several factors are contributing to the rapid expansion of the automated CPR device market. One of the most critical is the increasing incidence of cardiac arrest worldwide. With millions of cases reported annually, the need for reliable and efficient CPR delivery tools has become more pressing. As aging populations grow and lifestyle diseases continue to rise, the demand for advanced emergency response tools, including automated CPR devices, is escalating.

Government initiatives and awareness campaigns emphasizing the importance of CPR training and advanced emergency care are further supporting market growth. Regulatory agencies and healthcare organizations are encouraging the use of evidence-based practices, including the integration of automated CPR technology into standard care protocols.

Technological innovation is another major driver. Continuous research and development in materials, mechanics, and user interfaces have resulted in automated CPR devices that are more accurate, easier to operate, and adaptable to various patient anatomies. Additionally, increased healthcare spending, especially in emerging economies, has created opportunities for expanding product reach and adoption.

Challenges and Opportunities

Despite the promising outlook, the automated CPR device market faces several challenges. High upfront costs and limited reimbursement options remain significant barriers to widespread adoption, particularly in low- and middle-income regions. While the benefits of automated CPR are well-documented, budget constraints often force healthcare providers to prioritize other critical equipment.

Another challenge is training and education. Successful deployment of automated CPR devices depends on proper training for emergency medical technicians, paramedics, and hospital staff. Without adequate knowledge, the devices may not be used to their full potential, compromising their effectiveness.

Nevertheless, the market presents multiple opportunities. There is growing interest in deploying automated CPR devices in non-traditional settings such as public venues, corporate campuses, and sporting events. These locations often have automated external defibrillators (AEDs) available, and the inclusion of CPR devices can significantly enhance the emergency response infrastructure.

Emerging markets also offer substantial growth potential. As healthcare infrastructure develops in regions like Asia-Pacific, Latin America, and parts of Africa, the automated CPR device market is likely to see increased demand. Companies that focus on cost-effective solutions and training support can effectively tap into these markets.

Regional Analysis

The automated CPR device market demonstrates varied growth patterns across different regions. North America is currently the leading market, driven by a well-established healthcare system, high awareness levels, and the presence of key market players. The United States accounts for a major share due to its emphasis on emergency preparedness and advanced cardiac life support protocols.

Europe follows closely, with countries like Germany, the UK, and France showing strong adoption rates. European healthcare systems are known for their focus on innovation and patient outcomes, which supports the integration of automated CPR devices into routine medical care.

The Asia-Pacific region is witnessing rapid growth, fueled by rising healthcare investment and the increasing burden of cardiovascular diseases. Governments in countries such as China, India, and Japan are prioritizing emergency medical services and implementing policies to improve cardiac care, thereby creating a favorable environment for the automated CPR device market.

Latin America and the Middle East are emerging as potential markets with increasing healthcare awareness and modernization. While these regions are in the early stages of adoption, ongoing improvements in healthcare infrastructure and training are expected to drive growth in the coming years.

Competitive Outlook

The competitive landscape of the automated CPR device market is dynamic, with several established companies and emerging players striving to gain market share. Key players are focused on product innovation, strategic collaborations, and geographic expansion to strengthen their market positions. Investments in research and development are crucial for staying ahead in this rapidly evolving field.

Manufacturers are also placing a strong emphasis on user training and customer support. Ensuring that medical staff are well-versed in operating these devices is critical for customer satisfaction and successful outcomes. Companies that offer robust training modules and after-sales service are more likely to retain customers and build brand loyalty.

Product differentiation through advanced features is another common strategy. Enhanced battery life, ease of use, real-time feedback, and compatibility with other emergency devices are among the factors that distinguish leading products. As competition intensifies, companies must continue to innovate while keeping costs in check to maintain profitability.

Top Companies

Several companies are leading the charge in the automated CPR device market, offering a variety of solutions designed to meet different clinical and operational needs. These firms are recognized for their commitment to quality, safety, and innovation. Their product lines include both manual and fully automated options, catering to a broad spectrum of healthcare providers.

These top companies often collaborate with academic institutions and hospitals to conduct research and validate their devices’ effectiveness. Such collaborations not only build credibility but also provide critical insights for future product development. Additionally, mergers and acquisitions are common in this sector, as firms seek to expand their product offerings and geographic reach.

Continual improvement is a hallmark of these top companies. They regularly update their products based on user feedback and clinical findings, ensuring that their devices remain at the forefront of emergency medical care. Their global distribution networks and customer service infrastructures make them reliable partners for healthcare providers worldwide.

Explore In-Depth Analysis-Click Here to Access the Report:- https://www.futuremarketinsights.com/reports/automated-cpr-devices-market

Segmentation Outlook

By Product:

  • Based on product, the industry has been categorized into piston-based devices and load-distributing band-based devices.

By Modality:

  • In terms of modality, the market is categorized into battery-driven and electrically-driven.

By End-user:

  • Different end-users include hospitals (emergency departments, ICUs, and others), ambulatory medical centers, specialty clinics, emergency medical services (ambulances and air ambulances), independent catheterization labs, and long-term care centers.

By Region:

  • Industry analysis has been carried out in key countries of North America, Latin America, East Asia, South Asia and Pacific, Western Europe, Eastern Europe, and Middle East and Africa.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Global Menopause Treatment Market Set for Robust Growth, Forecast to Reach USD 1,308.00 Million by 2034

The global menopause treatment market is projected to witness a substantial surge over the next decade, with its value expected to climb from USD 758.5 million in 2024 to USD 1,308.00 million by 2034, reflecting a robust CAGR of 5.6%. The market’s expansion is underpinned by increasing awareness of hormone replacement therapies (HRT), the rising prevalence of menopausal symptoms, and a growing elderly female population.

Menopause, a natural biological transition experienced by women typically in midlife, can bring about a range of physical and psychological symptoms. Addressing these effectively has become a key focus area in women’s health, prompting a wave of innovation across hormonal and non-hormonal treatment modalities.

Stay Updated with Market Movements: Get Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15766

Key Drivers of Market Growth

The global menopause treatment market is witnessing a paradigm shift, with innovative medication delivery systems such as transdermal patches, vaginal rings, and subcutaneous implants gaining traction over conventional oral therapies. These novel formats offer controlled hormone release, reducing side effects and improving adherence and convenience for patients.

The increasing adoption of non-hormonal therapies is another critical growth lever, especially for patients who cannot or prefer not to undergo hormone therapy. These include selective serotonin reuptake inhibitors (SSRIs), serotonin-norepinephrine reuptake inhibitors (SNRIs), and gabapentinoids.

Furthermore, public health campaigns and educational initiatives have significantly boosted awareness about menopause management, encouraging more women to seek appropriate treatments and support.

Market Restraints

Despite the positive outlook, the menopause treatment market faces challenges. Stringent regulatory frameworks and lengthy drug approval timelines continue to hinder faster market penetration. Safety concerns associated with long-term HRT use, including risks of cardiovascular issues and cancer, have also led to cautious adoption among patients and healthcare providers.

Regional Outlook: Opportunities and Expansion Trends

Europe is emerging as a lucrative region in the menopause treatment space, driven by a mix of high healthcare awareness, favorable reimbursement structures, and a growing aging female demographic. Countries such as Italy (CAGR 5.80%), Germany (5.60%), and France (5.20%) lead the charge in regional growth.

In North America, particularly the United States, innovation in menopause care and a modern healthcare infrastructure provide a strong foundation for steady growth at a 3.00% CAGR through 2034. Canada follows closely with a 4.10% CAGR, supported by evolving patient preferences and access to new therapies.

Meanwhile, the Asia Pacific region shows strong promise, led by China (3.20%), South Korea (2.40%), and Japan (1.60%), where increasing healthcare investments and awareness campaigns are stimulating demand.

Expert Insight

“The menopause treatment product market exhibits an optimistic growth opportunity boosted by surging consciousness, the elderly population, and accelerating healthcare expenses. The evolution of technology and advancing treatment approaches amplify the menopause treatment market expansion from 2024 to 2034,” comments an FMI analyst.

Interest in Market Trends: Get Detailed Analysis and Insights with Our Comprehensive Report! https://www.futuremarketinsights.com/reports/menopause-treatment-market

Key Market Takeaways

  • The oral route of administration dominates with a 58.80% market share in 2024, thanks to ease of use and availability.
  • Hormone therapy remains the leading product category, accounting for 62.40% of the market share in 2024.
  • Retail pharmacies and online sales channels are becoming prominent, improving accessibility and patient engagement.

Competitive Landscape: Innovation-Focused and Fragmented

The menopause treatment industry is highly fragmented, with numerous players leveraging advanced technologies and strategic partnerships to gain a competitive edge. Key players are focusing on product innovation, mergers and acquisitions, and regional expansion to strengthen their market positions.

Noteworthy Developments:

  • In May 2023, Astellas Pharma Inc. secured FDA approval for VEOZAH (fezolinetant)—the first nonhormonal neurokinin 3 (NK3) receptor antagonist to treat vasomotor symptoms (VMS) in menopausal women.
  • MYFEMBREE®, co-developed by Myovant Sciences and Pfizer Inc., received FDA approval in May 2021 for treating excessive menstrual bleeding caused by uterine fibroids in premenopausal women.

Leading Menopause Treatment Providers:

  • Eli Lilly and Company
  • Merck KGaA
  • Novartis AG
  • Bayer AG
  • Pfizer, Inc.
  • Novo Nordisk
  • Ascend Therapeutics
  • Mylan N.V. (Viatris)
  • Cipla, Inc.
  • Glenmark Pharmaceuticals Ltd.
  • MenoGeniX
  • Perrigo Pharma International D.A.C.

Market Segmentation

By Product:

  • Hormone Therapy: Estrogen-only, Progestin-only, Combination, Tibolone
  • Non-Hormonal Therapy: SSRIs, SNRIs, Gabapentinoids, Others

By Route of Administration:

  • Oral
  • Injectable
  • Topical

By Distribution Channel:

  • Institutional Sales: Hospitals, Specialty Clinics
  • Retail Sales: Retail Pharmacies, Drug Stores, Supermarkets/Hypermarkets
  • Online Sales

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East and Africa

Harness Healthcare Market Trends for Your Advantage! https://www.futuremarketinsights.com/industry-analysis/womens-health

The Road Ahead

As the stigma surrounding menopause gradually diminishes, the industry is seeing increased R&D activity aimed at developing personalized and safer treatment options. The next decade is set to witness enhanced integration of digital health solutions, teleconsultations, and wearable health trackers, enabling more proactive menopause management.

With technological advancements, heightened awareness, and growing healthcare investments, the global menopause treatment market is entering a dynamic phase—offering new hope and improved quality of life for millions of women worldwide.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Intraoral Scanner Market Set to Surge Beyond USD 1,548.0 Million by 2034, Driven by Breakthroughs in Robotics-Assisted Dental Imaging | FMI

The intraoral scanner market size is poised to cross USD 744.7 million in 2024 and is likely to attain a valuation of USD 1,548.0 million by 2034. The intraoral scanner industry is projected to thrive at a CAGR of 7.6% from 2024 to 2034.

Robot-assisted intraoral scanners, which employ robotic arms or automated positioning devices, improve scanning precision while reducing human variability. This development indicates a shift toward more automation in dental processes, which reduces reliance on manual dexterity. Robotics-assisted scanning enhances the precision of digital impressions and elevates intraoral scanners to the vanguard of dental automation.

Track Evolving Market Trends: Request Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15768

The intelligent integration of intraoral scanners with 3D printing technology represents a step toward fabricating in-office dental prostheses. This trend streamlines procedures and can decrease turnaround times by eliminating reliance on additional laboratories. By integrating 3D printing, dental offices can improve operational effectiveness and establish themselves as suppliers of personalized, on-demand dental care. The use of this technology is congruent with the industry’s trend towards internal production capacities, which can augment income streams and competitive standing in the marketplace.

Manufacturers of intraoral scanners have a strategic opportunity in the growing dental tourism market. Developing state-of-the-art scanning technology compliant with international standards places businesses in a position to support dental clinics participating in international patient care. Companies can benefit from the growing need for cutting-edge dental technology in prominent global healthcare centers by customizing solutions for this specialized market. Doing so could potentially establish market leadership and increase their worldwide reach.

Key Takeaways from the Intraoral Scanner Market Report:

  • The open system modality segment occupied 97.2% of the market shares in 2024.
  • The dental clinic end user segment captured 37.1% of the market share in 2024.
  • The market size in the United States is projected to increase at a 6.2% CAGR through 2034.
  • The market size in Germany is anticipated to develop at a 6.0% CAGR through 2034.
  • The market size in India is estimated to surge at a 10.0% CAGR through 2034.
  • The market size in China is expected to thrive at a 10.4% CAGR through 2034.

Interest in Market Trends: Get Detailed Analysis and Insights with Our Comprehensive Report! https://www.futuremarketinsights.com/reports/intraoral-scanners-market

Competitive Landscape

The intraoral scanner market is exceptionally competitive, with leading competitors, including Align Technology and Dentsply Sirona, making significant investments in innovation. Startups upend existing models, forcing more established businesses to adapt quickly. Establishing partnerships with dentistry groups and influential individuals bolsters credibility, and firms prioritizing open system designs and interoperability stand out.

Recent Developments

  • In September 2023, Neoss Group, a leading producer of dental implant solutions, proudly announced the NeoScan 2000, a portable and user-friendly wireless intraoral scanner. This follows the successful debut of the NeoScan™ 1000 last year.
  • In June 2023, DentalMonitoring, a France-based artificial intelligence (AI) business, launched ScanAssist, an AI-guided orthodontic scanner. The gadget enhances the patient experience by providing AI-guided instructions and real-time feedback to help patients complete their scans.

Note from the Analysts

“A thorough grasp of client preferences, ongoing innovation, regulatory compliance, and tactical cooperation is necessary for successfully navigating the intraoral scanner market. Adaptability, creative problem-solving, and a strong commitment to sustainability are essential for success in this dynamic environment, as they guarantee alignment with changing trends and the requirements of dental professionals.” Says an FMI analyst.

Key Players in the Intraoral Scanner Market

  • Dentsply Sirona
  • Align Technology
  • 3Shape
  • Carestream Dental
  • Planmeca Oy
  • Dental Wings Inc.
  • Straumann Group
  • Roland DG Corporation
  • Medit Corp.
  • Ormco Corporation
  • Shining 3D Tech Co., Ltd.
  • Dental Corporation (Envista Holdings Corporation)
  • Zimmer Biomet Holdings, Inc.

Discover the Key Drivers in Healthcare – Read the Full Report! https://www.futuremarketinsights.com/industry-analysis/dental-device

Intraoral Scanner Market Segmentation

By Product Type:

  • Intraoral Scanners
    • Benchtop Intraoral Scanners
    • Stand-Alone CAD/CAM Scanners
    • 3D Handheld Scanners
  • Intraoral Cameras
  • Intraoral Sensors
  • Stand-Alone Software

By Modality:

  • Closed System
  • Open System

By End User:

  • Hospitals
  • Dental Clinics
  • Group Dental Practices
  • Ambulatory Surgical Centres

By Region:

  • North America
  • Latin America
  • Western Europe
  • Eastern Europe
  • Asia Pacific (APAC)
  • Middle East & Africa (MEA)
  • Japan

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube

Global Stethoscope Hygiene Devices Market to Nearly Double by 2032 Amid Aging Population Boom and Growing Demand for Infection Control | Future Market Insights

The market for stethoscope hygiene devices is estimated to be worth USD 47.4 Million in 2022, according to Future Market Insights’ most recent industry analysis. Over the course of the forecast period, the market is expected to grow at a CAGR of nearly 6.9%, with an estimated USD 91.4 Million in valuation in 2032.

The stethoscope hygiene devices market is growing due to the rising demand for stethoscope use due to increasing geriatric population. The need for sophisticated stethoscopes has increased due to the rise in the number of elderly people seeking primary diagnoses for a variety of chronic illnesses.

Explore Key Trends in the Market: Request Your Sample Report! https://www.futuremarketinsights.com/reports/sample/rep-gb-15765

According to the CDC, it is known that adults over 65 have a higher risk of getting serious health issues like heart disease, the flu, chronic obstructive pulmonary disease, asthma, and other disorders.

The World Ageing 2019 report estimates that there were around 703 million adults worldwide in 2019 who were 65 years of age or older. In 2050, this number is projected to double to 1.5 billion. This important factor will lead to increased use of the device and can further lead to need to maintain proper stethoscope hygiene, which will help the market in receiving a boost.

This market is constrained by a knowledge gap about stethoscope disinfection and a lack of experience in this area. This knowledge gap provides a potential to avenue to be improved upon to contribute towards maintaining proper stethoscope hygiene by creating awareness about it.

These factors will prove to be important, as rise in use of stethoscopes will lead to the increased demand and production of stethoscope hygiene devices, and hence provide lucrative outlook for growth for the market.

Key Takeaways from Market Study

  • Desk-top stethoscope hygiene device is the leading segment as product, and holds approximately 86.6% market value share in 2021, owing to their widespread availability in the market and limited availability of wearable stethoscope hygiene devices.
  • UV segment is set to lead in terms of technology of stethoscope hygiene devices, with a market value share of around 80.3% in 2021 because UV is widely used for disinfection of all different kinds of things like surface disinfection, etc. as these rays are known for killing the microorganism present on the contaminated object.
  • In 2021, hospitals hold the largest market share value at 30.6%. This segment has become a dominating fragment due to the abundance and diversity of healthcare professionals in the market.
  • South Asia is considered the one most lucrative region with growth at a CAGR of 7.6% at the end of the forecast period, owing to the presence of market-specific products from India that have been launched recently.

“Rising demand for stethoscope use due to increasing geriatric population, and rising rates of nosocomial infection proliferation, are set to propel the sales of stethoscope hygiene devices across the globe,” says an analyst of Future Market Insights.

Growing Need for Market Insights: Access Our Full Report for Thorough Analysis and Trends! https://www.futuremarketinsights.com/reports/stethoscope-hygiene-devices-market

Market Competition

There are only a few new and existing players operating in the stethoscope hygiene devices market, which is highly concentrated. For the purpose of capturing that market, businesses are launching new products in various geographical locations.

  • In 2020, Vioguard launched Cubby Plus UV-C disinfecting chamber with application at home as well as in healthcare facilities.
  • On February 15, 2021, the Indian business Xech introduced the first stethoscope steriliser in the country, the Xech Sterostet, which sterilises stethoscope diaphragms of all sizes using specialised UV-C GI technology.

Key Companies Profiled

LightProgress/eHealth; Xech; Your First Services Inc.; Vioguard; Edmund Optics; Parsons; UV Smart; Tangshan UMG Medical Instrument Co., Ltd.

Key Market Segments Covered in Stethoscope Hygiene Devices Industry Research

By Product:

  • Wearable
  • Desk-Top

By Usage:

  • UV
  • Glass Plasma

By End User:

  • Hospitals
  • Clinics
  • Academic & Research Institutions
  • Ambulatory Care Centres
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East and Africa (MEA)

Advantage Healthcare Insights to Outpace Competitors! https://www.futuremarketinsights.com/industry-analysis/infection-control

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube