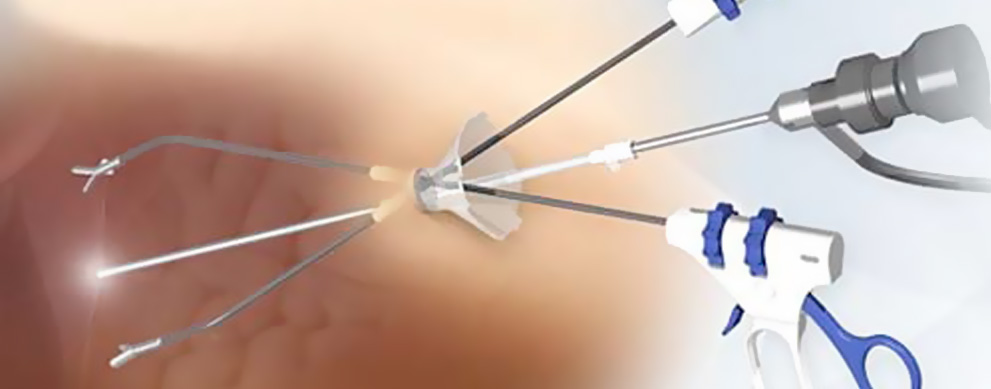
The global minimally invasive neurosurgery devices market is valued at approximately USD 3,227.9 million in 2023, with projections indicating a robust growth trajectory. The market is expected to witness an average compound annual growth rate (CAGR) of 6.3% from 2023 to 2033, potentially exceeding USD 5,950.1 million by the end of the forecast period.
Key Market Insights
Demographic Drivers:
The increasing population of older adults and the rising prevalence of chronic illnesses such as cancer and neurological disorders are the primary factors fueling the growth of the minimally invasive neurosurgery devices market. As the demand for effective surgical solutions rises, healthcare providers are increasingly turning to minimally invasive techniques that offer faster recovery times and reduced complications.
Gastrointestinal Devices Segment:
The gastrointestinal category is anticipated to capture a significant market share due to the growing incidence of gastrointestinal disorders among young, adult, and elderly populations worldwide. This trend reflects the need for innovative surgical solutions that can address these health challenges effectively.
North America Leading the Market:
North America continues to dominate the minimally invasive neurosurgery devices market, driven by the high prevalence of neurological conditions affecting over 25 million people in the region. Neurological disorders are recognized as a leading cause of mortality, leading to increased demand for advanced surgical interventions.
Asia Pacific Growth Potential:
The Asia Pacific region is projected to experience substantial growth in the minimally invasive neurosurgery devices market, fueled by a growing patient population requiring surgical procedures and government initiatives aimed at enhancing the healthcare sector. This region’s increasing investment in healthcare infrastructure is expected to drive further market expansion.
Future Outlook
As the global minimally invasive neurosurgery devices market continues to evolve, advancements in technology and increasing awareness of the benefits of minimally invasive procedures are expected to play crucial roles in shaping the future of neurosurgery.
Competitive Landscape of the Minimally Invasive Neurosurgery Devices Market
Many market players have taken various measures. They create new devices and expand their businesses. They correspondingly make continuous investments to introduce improved devices. They also form strategic alliances with hospitals, research institutions, and other healthcare stakeholders. These strategies help them maintain their footing in the highly competitive industry.
Recent Developments in the Minimally Invasive Neurosurgery Devices Market
In August 2023, Orthofix Medical revealed the complete commercial availability of their 7D Flash navigation system percutaneous module 2.0 in the United States. It adds additional planning elements and expands the usefulness of the 7D Flash neuronavigation system for minimally invasive spine surgery. The 7D system was provided by 7D Surgical, which was subsequently purchased by SeaSpine in 2021 following the merger of Orthofix and SeaSpine this year.
In October 2022, for the very first time, Imperial College London scientists efficiently implanted a bioinspired, fresh, flexible, steerable device in the brains of living animals using a minimally invasive robot. It’s a highly accurate, minimally intrusive platform that advances current technologies. If shown safe and successful, it might increase its ability to effectively and securely detect and treat illnesses in humans.
Key Companies Profiled in the Minimally Invasive Neurosurgery Devices Market Report
Karl Storz GmbH & Co. KG
Olympus Corporation
Conmed Corporation
Richard Wolf GmbH
Boston Scientific Inc.
Integra LifeSciences Holdings Corporation
Aesculap Division
Smith & Nephew Plc
Medtronic
NICO Corp.
Key Segments Covered in the Minimally Invasive Neurosurgery Devices Industry Analysis
By Device Type:
Surgical Devices
Monitoring & Visualization Devices
Endoscopy Devices
By Surgery Type:
Urological
Vascular
Cardiac
Gynaecological
Gastrointestinal
Cosmetic
Bariatric
Thoracic
Breast
Orthopedic
By Region:
North America
Latin America
Europe
Asia Pacific
Middle East & Africa
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global medical waste management system market is set to be valued at approximately USD 8,094 million in 2023 and is projected to grow significantly, reaching around USD 15,336.9 million by 2033. This remarkable growth reflects a compound annual growth rate (CAGR) of 6.6% during the forecast period from 2023 to 2033.
Key Market Insights
Medical waste, which encompasses a wide variety of hazardous and non-hazardous materials generated at healthcare facilities and life science processing companies, poses significant environmental and health risks. The types of medical waste generated include body parts, blood, chemicals, used needles, syringes, soiled dressings, medical devices, diagnostic samples, pharmaceuticals, and radioactive materials.
Growing Awareness of Waste Management:
The increasing recognition of the importance of proper medical waste management is driving demand for efficient waste disposal solutions. Healthcare providers are increasingly prioritizing the implementation of effective waste management systems to mitigate environmental impact and comply with stringent regulations.
Regulatory Compliance:
As governments worldwide impose stricter regulations governing the disposal of medical waste, healthcare facilities are investing in comprehensive waste management systems to ensure compliance. This trend is expected to further fuel the growth of the market.
Future Outlook
The medical waste management system market is poised for significant expansion as healthcare facilities seek innovative and effective solutions for waste disposal. With the rising incidence of healthcare activities and an increasing focus on sustainability, the demand for advanced medical waste management systems is anticipated to grow steadily.
Key Takeaways from Global Medical Waste Management System Industry
North America holds more than 30% of the market share due to rising number of patients in the US and Canada coupled with strict rules/regulations set by government bodies.
Europe holds more than 25% of the market share due to growing demand for medical waste management systems to properly treat, dispose, and recycle medical waste.
The Asia-Pacific is expected to grow at the fastest rate in the medical waste management system market sue to numerous start-ups coming up with e-disposal solution for managing infectious waste.
“Increasing incidences of chronic ailments that need longer hospital stays, emphasis on medical waste management in the developing as well as developed countries, and strict regulations laid down by the government regarding appropriate medical waste disposal are the primary drivers to Global Medical Waste Management System Industry”, says an analyst from Future Market Insights.
Competitive Landscape
Envetec Sustainable Technologies Ltd., in February 2022, tabled GENERATIONS technology, which comes across as one of the breakthrough cleantech solutions safely treating biohazardous materials and waste, inclusive of glass, plastics, sharp containers, PPE, and the other general laboratory consumables.
MediWaste was launched in March 2022 for handling biohazardous waste in Bermuda. Its functionalities include treating, transportation, and disposal of medical waste via two incinerators specifically designed for the serving the purpose mentioned above.
The United Nations Development Programme (UNDP), in collaboration with the Government of Japan, came up with a novel project in August 2022 for supporting various national health agencies with other stakeholders in Bhutan, Bangladesh, and Maldives for addressing an uncontrollable increase in infectious healthcare waste resulting out of the pandemic.
TerraConsult, in April 2019, merged with ByrneLobby for expanding its geographical presence.
Stericycle, in February 2020, made an announcement about inking an agreement with Harso Corporation about selling its business pertaining to Domestic Environments Solutions for US$ 462.5 Million.
Clean Harbors, in August 2021, completed acquisition of HydroChemPSC for US$ 1.25 Billion with the objective of strengthening the opportunities of strong customer service and brand equity.
Key Players:
BioMedical Waste Solutions LLC
Bondtech Medical Waste Containers
Clean Harbors, Inc.
Converge Medical Solutions LLC
Daniels Sharpsmart Inc.
Stericycle, Inc.
Medasend Biomedical, Inc.
Mazaya Waste Management LLC
Sharps Compliance, Inc.
Veolia Environment S.A.
REMONDIS Medison GmbH
Republic Services, Inc.
Waste Management, Inc.
Suez Environment S.A.
What does the Report unveil?
Future Market Insights offers an exclusive perspective and various real-time insights on the Global Medical Waste Management System Industry in its latest study, presenting historical demand assessment of 2016 to 2021 and projections for 2022 to 2032.
The research study is based on service (medical waste treatment, disposable medical waste management, and medical waste recycling), by medical waste (bio hazardous medical waste management system, non-hazardous medical waste management system, sharps medical waste management system, pharmaceutical medical waste management system, radioactive medical waste management system, and other medical waste types management system), by services site (onsite medical waste management services and offsite medical waste management services), by treatment (medical waste management through incineration, medical waste management through autoclaving, medical waste management through chemical treatment, and medical waste management through other approaches), and waste generator (medical waste management system for hospitals, medical waste management system for clinics, medical waste management system for Ambulatory Surgical Centers, medical waste management system for pharmaceutical companies, medical waste management system for biotechnology companies, and medical waste management system for other waste generators).
With an ever-increasing number of government-sponsored programs hitting the floor, the Global Medical Waste Management System Industry is bound to be unstoppable in the years to come. The government agencies adhering to regulations include the US FDA, CDC, OSHA (Occupational Safety and Health Administration), DOT (Department of Transport), and DEA (Drug Enforcement Administration).
Key Segments Covered in the Medical Waste Management System Industry Analysis
By Services:
Medical Waste Treatment
Disposable Medical Waste Management
Medical Waste Recycling
By Medical Waste:
Bio Hazardous Medical Waste Management System
Non-Hazardous Medical Waste Management System
Sharps Medical Waste Management System
Pharmaceutical Medical Waste Management System
Radioactive Medical Waste Management System
Other Medical Waste Types Management System
By Services Site:
Onsite Medical Waste Management Services
Offsite Medical Waste Management Services
By Treatment:
Medical Waste Management through Incineration
Medical Waste Management through Autoclaving
Medical Waste Management through Chemical Treatment
Medical Waste Management through Other Approaches
By Waste Generator:
Medical Waste Management System for Hospitals
Medical Waste Management System for Clinics
Medical Waste Management System for Ambulatory Surgical Centers
Medical Waste Management System for Pharmaceutical Companies
Medical Waste Management System for Biotechnology Companies
Medical Waste Management System for Other Waste Generators
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global homecare medical devices market is poised for significant growth, holding a forecasted value of approximately USD 133,650.67 million in 2022. This market is expected to surpass USD 312,328.06 million by 2032, advancing with a compound annual growth rate (CAGR) of 8.9% during the forecast period.
Key Drivers of Growth
The growth of the homecare medical devices market is primarily attributed to the increasing prevalence of chronic diseases worldwide. Home medical equipment offers patients a safe, convenient, cost-effective, and comfortable alternative to traditional healthcare settings, enabling them to receive quality care in the comfort of their own homes.
Rising Demand for Oxygen-Related Equipment:
The market for oxygen-related home medical equipment is expanding significantly, largely driven by the rising incidence of chronic obstructive pulmonary disease (COPD) globally. As more patients seek at-home solutions for their respiratory needs, the demand for oxygen concentrators and other related devices is surging.
Diverse Range of Devices:
Patients benefit from a variety of home medical devices, including infusion pumps, wheelchairs, glucose meters, and cannulas. For instance, glucose meters and glucometers are essential tools for diabetes management, allowing patients to monitor their blood sugar levels effectively and conveniently.
Future Outlook
As the healthcare landscape continues to evolve, the demand for homecare medical devices is expected to rise steadily. The ongoing trend towards patient-centered care, coupled with advancements in technology, is driving innovation in the home medical equipment sector. Healthcare providers are increasingly recognizing the importance of enabling patients to manage their health at home, resulting in a significant shift towards homecare solutions.
Revolutionizing healthcare delivery, the Homecare Medical Devices Market emerges as a beacon of convenience and empowerment. Designed for in-home use, these devices encompass a spectrum of tools, from monitoring to therapeutic aids, fostering a paradigm shift towards personalized and accessible healthcare. With a focus on enhancing patient autonomy and well-being, the Homecare Medical Devices Market reflects a pivotal stride in making healthcare more individualized and convenient for users in the comfort of their homes
Homecare Medical Devices Market: Drivers and Restraints
The geriatric population are dependent on assistance for mobility. Wheelchair technology is evolving to provide people with disabilities an ease in mobility. Mobility of these people with disabilities depends on wheelchair which solves the purpose to greater extent. Power and manual wheelchairs are used by people depending on their requirements. Many issues impact the choice of a wheelchair, for instance, some patients look for cost effective devices and reimbursement availability.
Medical scooters is a fast growing segment in the global homecare medical devices market owing to its feature of mobility for the aging population and their performance in an outdoor environment. A major driver of the global homecare medical equipment is the growing incidence of Chronic Obstructive Pulmonary Disease (COPD) and other respiratory conditions wherein oxygen is able to improve the quality of life significantly. Portable devices have become affordable and support a mobile lifestyle even while on oxygen. Stationary oxygen concentrators are needed for night use by patients on portable oxygen concentrators during the day. The impact of direct sales through the Internet has brought about distribution channel consolidation, leading to a decrease in the number of distributers in the global homecare equipment market.
Home care medical devices are intended for use in any environment outside a professional healthcare facility. The user could be a patient, caregiver, or family member who directly uses the homecare medical device or provides assistance in using the homecare medical device. A qualified healthcare professional is a licensed or non-licensed healthcare professional with proficient skills and expertise in the use of the homecare medical device such that they can aid or train care recipients and caregivers to use and maintain the device.
The homecare medical equipment market consists primarily of wheelchairs, scooters, oxygen treatment equipment, accessibility beds, lifts, and toilets, which have until recently been sold primarily through distributers. As patients move to the use of home care services for recovery or long-term care, the homecare medical devices are necessary for their care. As a result, complex medical devices are used more frequently in the home, many times under unsuitable conditions. This in turn has adverse implications on the safety and effective operation of these homecare medical devices, especially those with sophisticated requirements for proper operation or maintenance.
Homecare Medical Devices Market: Regional Overview
Region wise, the homecare medical devices market is classified into regions namely, North America, Eastern Europe, Western Europe, Latin America, Japan, Asia Pacific excluding Japan (APEJ), Middle East and Africa (MEA). North America is the largest market for homecare medical devices, followed by Western Europe attributed to the increasing old age population in these regions. Asia Pacific excluding Japan (APEJ) and Japan are growing at significant growth rate which is followed by Middle East & Africa.
Homecare Medical Devices Market: Overview
According to American Association for Homecare more than 8 Mn Americans depend on durable medical equipment and services at home to treat conditions such as multiple sclerosis, Lou Gehrig’s disease, spinal cord injuries, lung disease such as chronic obstructive pulmonary disease (COPD), congestive heart failure, sleep apnea, and diabetes.
Fueled by the rising number of elderly people and technological advancements, the global homecare market has experienced significant growth over the past decade.
A pivotal factor in the growth of this market has been the increasing healthcare cost, which have shifted the focus of healthcare from hospitals to home. Initiatives taken by governments to support home healthcare further propels the market. However, limited insurance coverage for home healthcare devices and risk to the safety of patients and home care workers are the major deterrents curbing the growth of the market.
Key Players:
AirSep
SeQual
Drive Medical
Graham Field
Inogen
Invacare
Mayra
Nordic / Handicare / Permobil
O2Concepts Oxlife
Philips Respironics
Pride
Sunrise Medica
eijin and TiLite.
The report covers exhaustive analysis on:
Market Segments
Market Dynamics
Market Size
Supply & Demand
Current Trends/Issues/Challenges
Competition & Companies involved
Technology
Value Chain
Regional analysis includes
North America (U.S., Canada)
Latin America (Mexico, Brazil, Rest of Latin America)
Western Europe (Germany, Italy, U.K, Spain, France, Nordic countries, BENELUX, Rest of Western Europe)
Eastern Europe (Russia, Poland, Rest of Eastern Europe)
Asia Pacific Excluding Japan (China, India, ASEAN, Australia & New Zealand, Rest of APEJ)
Japan
Middle East and Africa (GCC countries, S. Africa, N. Africa, Rest of MEA)
The report is a compilation of first-hand information, qualitative and quantitative assessment by industry analysts, inputs from industry experts and industry participants across the value chain. The report provides in-depth analysis of parent market trends, macro-economic indicators and governing factors along with market attractiveness as per segments. The report also maps the qualitative impact of various market factors on market segments and geographies.
The homecare medical devices market is classified on the basis of product type, distribution channels and geography.
Based on product type, the global homecare medical devices market is segmented into the following:
Wheelchairs
Scooters
Oxygen treatment equipment
Accessibility beds
Lifts
Toilets
Others
Based on distribution channel, the global homecare medical devices market is segmented into the following:
Direct Distribution Channel
Online Sales
Report Highlights:
Detailed overview of parent market
Changing market dynamics in the industry
In-depth market segmentation
Historical, current and projected market size in terms of volume and value
Recent industry trends and developments
Competitive landscape
Strategies of key players and products offered
Potential and niche segments, geographical regions exhibiting promising growth
A neutral perspective on market performance
Must-have information for market players to sustain and enhance their market footprint
Author By:
Sabyasachi Ghosh (Associate Vice President at Future Market Insights, Inc.) holds over 12 years of experience in the Healthcare, Medical Devices, and Pharmaceutical industries. His curious and analytical nature helped him shape his career as a researcher.
Identifying key challenges faced by clients and devising robust, hypothesis-based solutions to empower them with strategic decision-making capabilities come naturally to him. His primary expertise lies in areas such as Market Entry and Expansion Strategy, Feasibility Studies, Competitive Intelligence, and Strategic Transformation.
Holding a degree in Microbiology, Sabyasachi has authored numerous publications and has been cited in journals, including The Journal of mHealth, ITN Online, and Spinal Surgery News.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
Contact Us:
Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA T: +1-347-918-3531
The global insulin biosimilar market is on track for significant expansion, with an estimated valuation of approximately USD 3,008.0 million in 2024. Exhibiting a year-on-year growth rate of 7.2%, the market is expected to continue its upward trajectory, with overall sales of insulin biosimilars projected to rise at a compound annual growth rate (CAGR) of 6.2% throughout the assessment period. By 2034, the market size is anticipated to reach an impressive USD 5,379.5 million.
Key Growth Drivers
The insulin biosimilar market’s robust growth can be attributed to several factors:
Increasing Prevalence of Diabetes: The global rise in diabetes cases has heightened the demand for effective and affordable insulin therapies, paving the way for biosimilars.
Cost-Effectiveness: Insulin biosimilars provide a more cost-effective alternative to reference biologics, making diabetes management more accessible to patients worldwide.
Improved Market Awareness: Growing awareness among healthcare professionals and patients regarding the benefits of biosimilars is driving market adoption and acceptance.
Advancements in Technology: Ongoing advancements in biomanufacturing and regulatory processes are enhancing the availability and quality of insulin biosimilars.
Future Outlook
As the healthcare landscape continues to evolve, the insulin biosimilar market is poised for substantial growth. With increasing investments in research and development and the rising emphasis on cost-effective treatment options, stakeholders in the pharmaceutical industry are well-positioned to meet the surging demand for insulin biosimilars.
Biosimilar insulin has the capacity of reducing treatment costs of diabetes, increasing insulin treatment’s accessibility, and expanding number of various insulin brands that are available for the ones contracting diabetes. At the same time, they need to overcome regulatory hurdles over here, and address numerous demands at the commercial level. On the top of that, competition from next-generation as well as established branded insulin products needs to be confronted.
The International Diabetes Foundation has confirmed that atleast US$ 760 Bn were spent in the year 2019, which is 10% of overall spending on the adults. This factor is basically accelerating the insulin biosimilars market.
The manufacturers are emphasizing on clinical trials for tabling insulin biosimilar products. On these grounds, LMC Diabetes & Endocrinology Ltd. is on the lookout of volunteers to enable phase 4 study entitled ‘The Effects of Soliqua on glucose variability in type 2 diabetes patients among South Asian population’.
There are rapid-acting biosimilars, which are administered within 15 minutes of having meals. They, as the names suggests, gets absorbed with immediate effect and starts lowering blood glucose. Long-acting biosimilars are capable of controlling blood sugar for whole of the day. They are preferred due to their ability of helping patients with Type 1 diabetes reach lower rates of hypoglycemia with better quality of life. There are premixed biosimilars, which ensure combination of two diverse kinds of insulin – the one controlling sugar between meals and the other at meals.
Future Market Insights has entailed these facts with future perspectives in its latest market study entitled ‘Insulin Biosimilars Market’, with its team of analysts and consultants to execute.
North America holds the largest market share (~69%) due to spike in the number of diabetic patients in the US. As per the National Institute of Diabetes and Digestive and Kidney Diseases, close to 30.3 Mn people staying in the US are diabetic. Also, more than 30% of people all across the US have been diagnosed with prediabetes, as per the National Diabetes Statistics Report. These prediabetic conditions are estimated to increase the population of those getting diabetic.
Europe stands second on this count. This could be attributed to early approvals of biosimilars. As per the IDF Diabetes Atlas, close to 61 Mn adults aged between 20 and 79 are diabetic in IDF Europe Region as of the year 2021.
The Asia-Pacific is expected to grow at the fastest pace in the insulin biosimilars market due to advancements in infrastructure regarding diagnosing chronic diseases. The governments herein are also into easily utilizing insulin management system.
Competitive Biosimilars
GeneSys Biologics makes provisions for safe, high-quality, affordable, and effective insulin biosimilars all over. This start-up is expected to provide, safe, high-quality, affordable, and effective insulin biosimilars all over.
Merck, in April 2022, updated its portfolio pertaining to bioprocessing by acquiring Lonza’s MAST (Modular Automated Sampling Technology) platform. This platform is an aseptic, automated bioreactor sampling system that has been developed in Bend (Oregon, US).
Biocon’s BBL (Biocon Biologics Ltd.), in September 2021, did announce launching ‘Express Scripts’ (one of the leading pharmacy benefit management organizations all over the US). As such, Biocon Biologics interchangeable biosimilar Insulin Glargine (Semglee) would be commercialized by a preferred brand of glargine ‘Viatris’ on NPF (National Preferred Formulary), which is inclusive of over 28 Mn lives.
Eli Lilly’s insulin glargine (Basaglar), which has been co-developed with Boehringer Ingelheim; which is available at a lower price as compared to Lantus (Sanofi); the reference brand.
“With the branded insulin products slated to expire in the upcoming period, the global insulin biosimilars market is expected to grow on an astounded note in the near future”, says an analyst from Future Market Insights.
What does the Report Cover?
The research study is based on biosimilar type (rapid acting biosimilar, long acting biosimilar, and premixed biosimilar) and by disease indication (insulin biosimilar for Type I diabetes and insulin biosimilar for Type II diabetes).
With growing prevalence of diabetes all across, the demand for insulin biosimilars is bound to witness growth on an irrevocable note going forward.
Key Segments Profiled in the Insulin Biosimilars Industry Survey
Global Insulin Biosimilar Market by Biosimilar Type:
Rapid Acting Biosimilar
Long Acting Biosimilar
Premixed Biosimilar
Global Insulin Biosimilar Market by Disease Indication:
Insulin Biosimilar for Type I Diabetes
Insulin Biosimilar for Type II Diabetes
Author By:
Sabyasachi Ghosh (Associate Vice President at Future Market Insights, Inc.) holds over 12 years of experience in the Healthcare, Medical Devices, and Pharmaceutical industries. His curious and analytical nature helped him shape his career as a researcher.
Identifying key challenges faced by clients and devising robust, hypothesis-based solutions to empower them with strategic decision-making capabilities come naturally to him. His primary expertise lies in areas such as Market Entry and Expansion Strategy, Feasibility Studies, Competitive Intelligence, and Strategic Transformation.
Holding a degree in Microbiology, Sabyasachi has authored numerous publications and has been cited in journals, including The Journal of mHealth, ITN Online, and Spinal Surgery News.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The glioblastoma treatment drugs market is poised for substantial growth, with a projected valuation of approximately USD 756.1 million in 2023. The market is expected to reach around USD 1,317.4 million by 2033, capturing a compound annual growth rate (CAGR) of 5.7% over the forecast period.
Key Market Drivers
The demand for glioblastoma treatment drugs is being stimulated by several critical factors:
Rising Incidence of Brain Tumors: The increasing prevalence of brain tumors, particularly glioblastoma, has led to a heightened need for effective treatment options.
High Mortality Rates: The aggressive nature of glioblastoma and its associated high mortality rates underscore the urgent need for innovative and effective therapeutic solutions in healthcare settings.
Growing Old-Age Population: The rise in the elderly population, who are more susceptible to various health issues, including glioblastoma, is further fueling market growth.
Aggressive Treatment Options: The continuous evolution of treatment methodologies and the development of aggressive therapeutic options are also contributing to the expansion of the glioblastoma treatment drugs market.
Future Outlook
As the healthcare industry focuses on improving patient outcomes and extending survival rates for those diagnosed with glioblastoma, the market for treatment drugs is expected to expand significantly. This growth presents opportunities for pharmaceutical companies to innovate and enhance their offerings to meet the increasing demand for effective glioblastoma therapies.
Manufacturers are advancing the global market through innovation, medical devices, and research and development activities. A few of these factors are as follows:
Research and Development Activities:Manufacturers are investing in research and development activities to develop therapies, new drugs, and medical advancement. They are innovating this advancement to expand treatment options to improve patient conditions.
Drug Discovery: Manufacturers in pharmaceuticals are discovering drugs to seek new regulations and identify new components with improved clinical trials. These advancements in drug discovery improve treatment procedures.
Innovation of Medical Devices:Manufacturers are developing better devices with the latest technologies, such as wearable devices, to expand market reach. These devices improve patients’ healthcare.
Quality Control and Compliance:Manufacturers maintain standardization on the healthcare products, ensuring safety. They are following regulatory agencies’ rules and manufacturing aspects.
Global Distribution:Manufacturers are connected with distributors to supply their products globally. They provide their products to end users such as pharmacies, hospitals, and other healthcare providers.
Advancement in Biotechnology:Manufacturers are focused on developing vaccines, gene therapies, and advanced biologics. They are innovating advanced healthcare to treat complex diseases.
Digital Health:Manufacturers are expanding the global market through digital health. They are improving patient outcomes through online application software to support healthcare professionals to work seamlessly.
Patient Engagement:Manufacturers are focusing on initiative programs on patient support, awareness, and educational resources. These programs empower patients’ health and grow awareness towards diseases.
Sustainability Initiatives:Healthcare manufacturers are concerned toward the environmental crisis. They are growing focused on developing non-hazardous medical products to promote greener with sustainability.
“Rising number of brain cancer tumor cases across the globe is stimulating the adoption of glioblastoma treatment drugs. Healthcare settings are focused on developing new drug therapies to improve patient outcomes. The adoption of telemedicine for old-age patients is a key solution to consult with healthcare experts in remote areas,” says an analyst at FMI.
Key Takeaways
The glioblastoma treatment drugs market is expected to grow at a CAGR of 5.7% between 2023 to 2033.
The United States is expected to register a maximum share of 73.1% by dominating the global market by 2033.
Japan is anticipated to capture a CAGR of 4.9% of the global market by 2033.
The United Kingdom significantly drives the global market with an anticipated 9% share of the global market by 2033.
With an estimated share of 2.3% of the market by 2033, Germany is rapidly advancing the global market.
Key Player’s Contribution to the Global Glioblastoma Treatment Drugs Market
The number of essential players highly consolidates the global market. These players are making efforts to develop cost-effective products to attract end users. They are investing their amount in research activities to innovate new products. The key players are adopting various marketing tactics such as mergers, collaborations, acquisitions, and partnerships.
Recent Developments in the Glioblastoma Treatment Drugs Market
In 2021, Lineage Cell Therapeutics announced its new deal with Immunomic Therapeutics. This deal took place to enhance cancer treatment.
In 2019, Merck announced its other acquisition with Peloton Therapeutics to treat brain cancer treatment.
Competitive Landscape in the Glioblastoma Treatment Drugs Market
The present key vendors fragment the global glioblastoma treatment drugs market. These vendors are actively working on developing new and improved products in the worldwide market by investing in research and development activities. These vendors are adopting various marketing tactics to uplift the international market level. These marketing methodologies are collaborations, partnerships, mergers, and acquisitions.
Key players are offering a wide range of products and devices to end-use industries as per their requirements. They are taking feedback and improving their gaps by advancing these devices to satisfy patients’ needs.
Key Players in the Global Glioblastoma Treatment Drugs Market
Gene Therapy
Virus
Kinase Inhibitor
Glioma Steam Cell Targeting
MiRNA Targeting
Pfizer Inc.
Roche Holding AG
Novartis AG
Johnson & Johnson
Merck & Co., Inc.
AstraZeneca PLC
GlaxoSmithKline plc (GSK)
Sanofi S.A.
Recent Developments in the Glioblastoma Treatment Drugs Market
In 2023, Chimeric Therapeutics announced its newly launched Phase 1B clinical trial. It is a cell therapy trial with effective CHM 1101 with safety.
In 2022, Northwest Bio-therapeutics received its approval for the Pediatric Investment Plan.
In 2021, Lineage Cell Therapeutics dealt with Immunomic Therapeutics to create a platform for VAC Cancer Treatment. It helps to treat glioblastoma.
In 2019, Merck announced its acquisitions with Peloton Therapeutics. This acquisition took place to help brain cancer treatment strongly in the global market.
Key Segments in the Glioblastoma Treatment Drugs Market
By Drug Class:
Antineoplastic
VEGF/VEGFR Inhibitors
Alkylating Agents
Miscellaneous Antineoplastic
By Distribution Channel:
Hospitals
Cancer Research Organizations
Long Term Care Centers
Diagnostic Centers
By Region:
North America
Latin America
Asia Pacific
MEA
Europe
Author By:
Sabyasachi Ghosh (Associate Vice President at Future Market Insights, Inc.) holds over 12 years of experience in the Healthcare, Medical Devices, and Pharmaceutical industries. His curious and analytical nature helped him shape his career as a researcher.
Identifying key challenges faced by clients and devising robust, hypothesis-based solutions to empower them with strategic decision-making capabilities come naturally to him. His primary expertise lies in areas such as Market Entry and Expansion Strategy, Feasibility Studies, Competitive Intelligence, and Strategic Transformation.
Holding a degree in Microbiology, Sabyasachi has authored numerous publications and has been cited in journals, including The Journal of mHealth, ITN Online, and Spinal Surgery News.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global implantable infusion pump market is set to witness significant growth, with an expected valuation of approximately USD 485.1 million in 2022. The market is projected to expand at a robust compound annual growth rate (CAGR) of 5.7% between 2022 and 2032, ultimately reaching around USD 892.6 million by the end of the forecast period.
Key Market Drivers
The primary factors driving the growth of the implantable infusion pump market include:
Rising Incidence of Chronic Disorders: The increasing prevalence of chronic conditions such as diabetes and cancer is creating a heightened demand for effective drug delivery solutions.
Aging Population: The growing elderly population is contributing to a higher incidence of health issues that require long-term treatment and management, thereby bolstering the need for implantable infusion pumps.
Technological Advancements: Continuous innovations in medical technology are enhancing the efficiency and reliability of implantable infusion pumps, making them more appealing to healthcare providers and patients alike.
Understanding Implantable Infusion Pumps
An implantable infusion pump is a sophisticated medical device designed to deliver medications directly to patients through various routes, including intra-arterial, intravenous, subcutaneous, intraperitoneal, intrathecal, and epidural pathways. These pumps are surgically implanted in a subcutaneous pocket within the abdominal wall, allowing for seamless administration of therapy over extended periods.
Future Outlook
As the healthcare landscape evolves, the implantable infusion pump market is expected to grow in response to increasing demand for advanced therapeutic solutions. This growth presents opportunities for manufacturers to innovate and expand their product offerings to meet the diverse needs of patients and healthcare providers.
Who are the Leading Players in Implantable Infusion Pump Market?
Some leadingimplantable infusion pump manufacturers include B. Braun Melsungen AG., CareFusion Corporation, Fresenius Kabi AG, Terumo Corporation, Medtronic Plc., Baxter International Inc., Smiths Medical, MOOG Inc., Johnson & Johnson Private Ltd., and Hospira, Inc., Flowonix, The Tandem Diabetes Care.
These key implantable infusion pump providers are adopting various strategies such as new product launches and approvals, partnerships, collaborations, acquisitions, mergers, etc. to increase their sales and gain a competitive edge in the global implantable infusion pump market. For instance,
Flowonix received FDA authorization to market the Prometra® II Pump for use with Intrathecal Baclofen in February 2020.
The Tandem Diabetes Care t:Slim X2 insulin pump with interoperable technology (interoperable t:Slim X2) for providing insulin under the skin for children and adults with diabetes was approved for branding by the US Food and Drug Administration in February 2019.
Medtronic received pre-market approval from the US Food and Drug Administration for the SynchroMed II Implantable Infusion Pump and Implantable System for Remodulin in May 2020.
Key Segments of Implantable Infusion Pump Industry Survey
By Product Type:
Patient-Controlled Analgesia (PCA) Pump
Enteral Pump
Insulin Pump
Elastomeric Pump
Syringe Pump
By Application:
Oncology
Pediatrics/Neonatology
Gastroenterology
Hematology
Diabetes
By End User:
Hospitals
Ambulatory Surgical Centres
Clinics
Home Healthcare
By Region:
North America Implantable Infusion Pump Market
Latin America Implantable Infusion Pump Market
Europe Implantable Infusion Pump Market
Asia Pacific Implantable Infusion Pump Market
Middle East & Africa Implantable Infusion Pump Market
Author
Sabyasachi Ghosh (Associate Vice President at Future Market Insights, Inc.) holds over 12 years of experience in the Healthcare, Medical Devices, and Pharmaceutical industries. His curious and analytical nature helped him shape his career as a researcher.
Identifying key challenges faced by clients and devising robust, hypothesis-based solutions to empower them with strategic decision-making capabilities come naturally to him. His primary expertise lies in areas such as Market Entry and Expansion Strategy, Feasibility Studies, Competitive Intelligence, and Strategic Transformation.
Holding a degree in Microbiology, Sabyasachi has authored numerous publications and has been cited in journals, including The Journal of mHealth, ITN Online, and Spinal Surgery News.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global equine veterinary therapeutics market is poised for significant expansion, projected to generate revenue of approximately USD 2,671.9 million by 2033, up from USD 1,378.7 million in 2023. This remarkable growth reflects an impressive compound annual growth rate (CAGR) of 6.8%.
Key Market Highlights
Robust Growth from Historical Valuation
In 2022, the equine veterinary therapeutics market generated $1,307.6 million. The increasing popularity of horse-related activities, such as racing and jumping, is driving the demand for effective veterinary therapeutics to ensure proper care and treatment for horses, particularly in the event of injuries sustained during these activities.
Diverse Range of Therapeutics
Equine veterinary therapy encompasses a wide variety of treatments designed to prevent, diagnose, and manage numerous diseases and medical conditions affecting horses. As the equestrian sports sector continues to grow, so too does the need for innovative therapeutic solutions that enhance the health and performance of equine athletes.
Future Outlook
With an expanding market driven by the burgeoning interest in horse sports and ongoing advancements in veterinary medicine, the equine veterinary therapeutics market is well-positioned for robust growth in the coming years. Stakeholders are encouraged to explore opportunities for research and development to meet the evolving needs of equine healthcare.
Future Market Insights (FMI) adopted a multidisciplinary approach during the pandemic-era to focus on the growth and development of the Equine Veterinary Therapeutics Market. The study features insights on the current growth dynamics and the major revenue reforms prevailing in the market as along with the key takeaways over the forecast.
The team of analysts at Future Market Insights are focussing on research and market study to produce different Global Equine Veterinary Therapeutics Industry forecasts and predictions at both national and international levels. They have considered several leads of information pertaining to the industry like market figures and merger estimations to assess and produce reliable and informative insights on the Global Equine Veterinary Therapeutics Industry.
Key Players
The writer will create content on the general strategies of market players. And then will write the key players in the market are: Merck animal heath, Affymetrix, Elanco animal heath,Zoetis (Pfizer Animal Health), Equine Health U.K.and others
Segmentation
The report provides insights on the important highlights and current trends prevailing in the market. This helps the readers to gain a deeper understanding and form an unbiased opinion on the market. Numerous segmentations have been provided for this market based on:
Global Equine Veterinary Therapeutics Industry, by Product Type
Global Equine Veterinary Therapeutics Industry, by route of administration
Oral
Parental
Topical
Global Equine Veterinary Therapeutics Industry, by Distribution Channel
Veterinary Hospital
Veterinary Clinics
Pharmacies and drug stores
E-commerce
Other
Product Segmentation
The investigation offers a top to bottom evaluation of different clients’ journeys pertinent to the market and its segments. The study endeavours to assess the current and future development possibilities, undiscovered roads, factors that shapes their income potential in the global market by breaking it into di such as its types, applications, and region-wise assessment.
By Regional Analysis Covered
North America (U.S., Canada)
Latin America (Mexico, Brazil)
Western Europe (Germany, Italy, U.K, Spain, France, Nordic countries, BENELUX)
Eastern Europe (Russia, Poland, Rest Of Eastern Europe)
Asia Pacific Excluding Japan (China, India, ASEAN, Australia & New Zealand)
Japan
Middle East and Africa (GCC, S. Africa, N. Africa, Rest Of MEA)
Full in-depth analysis of the parent market
The analysts at FMI are dedicated to provide insights after extensive research and study. The study also includes estimations, projections and evaluation of the market dynamics.
Important changes in market dynamics
The report has been created after detailed and exhaustive studies by the analysts at FMI taking several factors into consideration like monetary, ecological, social, mechanical, and political status of a particular demography. They study the key data to assess the revenue and production of manufacturers across various regions. The report also covers an in-depth analysis of the key changes in market dynamics in the recent past and the near future.
Segmentation details of the market
Former, on-going, and projected market analysis in terms of volume and value
Assessment of niche industry developments
Market share analysis
Key strategies of major players
Emerging segments and regional markets
Author
Sabyasachi Ghosh (Associate Vice President at Future Market Insights, Inc.) holds over 12 years of experience in the Healthcare, Medical Devices, and Pharmaceutical industries. His curious and analytical nature helped him shape his career as a researcher.
Identifying key challenges faced by clients and devising robust, hypothesis-based solutions to empower them with strategic decision-making capabilities come naturally to him. His primary expertise lies in areas such as Market Entry and Expansion Strategy, Feasibility Studies, Competitive Intelligence, and Strategic Transformation.
Holding a degree in Microbiology, Sabyasachi has authored numerous publications and has been cited in journals, including The Journal of mHealth, ITN Online, and Spinal Surgery News.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global endoscopic vessel harvesting system market is projected to reach a valuation of approximately USD 746.1 million by 2033, growing at a compound annual growth rate (CAGR) of 3.7% from a current valuation of USD 520.4 million in 2023.
Key Market Highlights
Steady Revenue Generation and Growth Trends
The endoscopic vessel harvesting system market has experienced historical growth, with a CAGR of 2.3% from 2018 to 2022. Projections indicate that this growth will accelerate, with the CAGR expected to expand by 1.4% by 2033. The increasing prevalence of cardiovascular diseases, largely driven by an aging population, is significantly contributing to the rising demand for cardiac and vascular procedures. Endoscopic vessel harvesting systems play a crucial role in these treatments, highlighting the growing need for such technologies.
Accessibility and Advancements in Healthcare Infrastructure
Improvements in healthcare infrastructure in emerging markets are making endoscopic vessel harvesting systems more accessible, thereby raising their demand. The integration of data analytics and predictive capabilities in these systems is providing valuable insights during surgical procedures. By leveraging data to inform surgical decisions, healthcare professionals can enhance patient outcomes and promote the adoption of these innovative systems.
Future Outlook
The endoscopic vessel harvesting system market is well-positioned for growth, driven by the increasing demand for effective cardiovascular treatments and advancements in medical technology. Stakeholders are encouraged to invest in research and development to further enhance the capabilities of these systems and meet the evolving needs of the healthcare industry.
The endoscopic vessel harvesting devices market has opened up new opportunities for companies in the field of coronary artery bypass grafting (CABG).
Endoscopic vessel harvesting systems are experiencing an unprecedented surge in usage as a result of the preference for minimally invasive surgical procedures, as well as the growing healthcare sector and rising geriatric population in emerging economies, driving the market’s overall growth. As a result, the Global Endoscopic Vessel Harvesting System Industry is expected to grow significantly during the forecast period.
Coronary artery bypass graft surgery (CABG) is a procedure that restores blood supply to the heart muscle after one or more coronary arteries have been blocked or narrowed. Traditionally, the harvesting procedure used open vein harvesting (OVH), which required a single continuous skin incision. With recent technological advancements, the process is less invasive by endoscopic vessel harvesting (EVH). This technique reduces leg wound morbidity due to small incisions compared to open vein harvesting.
Some major companies in the Global Endoscopic Vessel Harvesting System Industry are Maquet Holding B.V. & Co. KG., OLYMPUS CORPORATION, Terumo Cardiovascular Systems Corporation., Med Europe S.r.l. (Elite Life Care), Sorin Group Inc., Saphena Medical, Inc, and Terumo Cardiovascular Systems Corporation.
Endoscopic vessel harvesting system Market Segments
Global Endoscopic Vessel Harvesting System Industry Dynamics
Endoscopic Vessel Harvesting System Market Size & Forecast 2022 to 2032
Global Endoscopic Vessel Harvesting System Industry Current Trends/Issues/Challenges
Competition & Companies involved
Global Endoscopic Vessel Harvesting System Industry Drivers and Restraints
Global Endoscopic Vessel Harvesting System Industry
The Global Endoscopic Vessel Harvesting System Industry is segmented based on product type and regional presence:
Segmentation based on product type
Disposable
Reusable
Geographically the Global Endoscopic Vessel Harvesting System Industry is segmented into five key regions
North America
Latin America
Europe
Asia Pacific
MEA region
The Asia Pacific endoscopic vessel harvesting system market is expected to grow rapidly as per capita income in Asian countries rises and the medical tourism industry expands. China is expected to be the fastest-growing market for endoscopic vessel harvesting systems due to increased public access to healthcare professionals and an expanding economy.
Key Segments in the Global Endoscopic Vessel Harvesting System Industry
Segmentation based on Product Type:
Disposable
Reusable
Author
Sabyasachi Ghosh (Associate Vice President at Future Market Insights, Inc.) holds over 12 years of experience in the Healthcare, Medical Devices, and Pharmaceutical industries. His curious and analytical nature helped him shape his career as a researcher.
Identifying key challenges faced by clients and devising robust, hypothesis-based solutions to empower them with strategic decision-making capabilities come naturally to him. His primary expertise lies in areas such as Market Entry and Expansion Strategy, Feasibility Studies, Competitive Intelligence, and Strategic Transformation.
Holding a degree in Microbiology, Sabyasachi has authored numerous publications and has been cited in journals, including The Journal of mHealth, ITN Online, and Spinal Surgery News.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.
The global docking station market is set for steady growth over the next decade, driven by increasing demand for portable and flexible work solutions. In 2024, the market is projected to be valued at US$ 1,659.8 million, with a forecast to reach US$ 2,992 million by 2034. This reflects a CAGR of 6.1% between 2024 and 2034.
With the rise in remote and hybrid work environments, professionals require greater connectivity and ease of use, fueling the need for docking stations that enable seamless integration of multiple devices. Furthermore, the growing popularity of compact laptops and tablets, especially in professional environments, has made docking stations an essential tool for productivity.
Key Takeaways from the Market Study:
The docking station market is expected to grow at a CAGR of 6.1% from 2024 to 2034.
Market value is projected to increase from US$ 1,659.8 million in 2024 to US$ 2,992 million by 2034.
Rising demand for remote work solutions and multi-device connectivity is driving market expansion.
Increasing adoption of USB-C and Thunderbolt-enabled docking stations is a key trend.
North America holds the largest market share, followed by Europe and Asia-Pacific.
Drivers and Opportunities
The growing adoption of remote and hybrid work models across industries has been a significant driver for the docking station market. As businesses increasingly embrace flexible working environments, there is a heightened demand for docking stations that allow employees to seamlessly transition between home and office setups, connecting multiple peripherals such as monitors, keyboards, and storage devices.
Furthermore, the rise of BYOD (Bring Your Own Device) policies in corporate environments has amplified the need for versatile docking stations compatible with a range of devices, including laptops, tablets, and smartphones. Advancements in USB-C and Thunderbolt technologies, which provide faster data transfer and multi-device support, are creating opportunities for manufacturers to introduce innovative docking solutions that cater to a wider range of users.
In addition, the expanding gaming and creative content industries, where high-performance workstations are essential, are further driving demand for advanced docking solutions. As professionals in these fields seek to enhance their productivity through multi-screen setups and high-speed data transfers, the market is poised for steady growth.
Components Insights
The docking station market can be segmented into ports (USB, HDMI, Ethernet), connectivity types (wired and wireless), and power delivery features. Among these, USB-C and Thunderbolt docking stations hold the largest share due to their ability to support high-speed data transfers, video output, and charging capabilities in a single solution. The versatility of these docking stations makes them highly sought after, especially in professional and enterprise settings.
Meanwhile, wireless docking stations are gaining traction, offering greater flexibility and convenience for users who prefer cable-free setups. Although still a smaller segment, wireless docking stations are expected to grow as wireless technology becomes more sophisticated.
Application Insights
The docking station market serves a wide range of industries, including IT and telecommunications, BFSI, healthcare, media and entertainment, and education. The IT and telecommunications sector leads the market, with professionals relying heavily on docking stations to connect multiple devices and work more efficiently across various platforms.
The education sector is also adopting docking stations at an increasing rate as schools and universities implement digital learning environments. In this sector, docking stations play a vital role in connecting students and educators to projectors, multiple screens, and audio systems, improving the learning experience.
In the media and entertainment industry, docking stations are used extensively by professionals who require high-speed connections to external hard drives, editing software, and multiple monitors to support tasks such as video editing and 3D rendering.
Deployment Insights
Docking stations are available in both wired and wireless deployment models. Wired docking stations dominate the market due to their reliability, faster data transfer rates, and ease of use, making them the preferred choice for corporate and professional environments.
However, wireless docking stations are becoming more popular, especially in the consumer electronics and home office segments. Wireless solutions offer greater flexibility and convenience, as they eliminate the need for cables and allow users to connect to devices from a distance. With advancements in wireless technology and growing consumer preference for minimalist setups, this segment is expected to see notable growth over the forecast period.
Key Companies & Market Share Insights
The docking station market is highly competitive, with several major players contributing to its growth. Leading companies include Dell Technologies, HP Inc., Lenovo Group, Samsung Electronics, Targus, and StarTech.com, which offer a variety of docking station solutions for different customer needs.
Dell Technologies and HP Inc. continue to lead the market, with their strong presence in the business and enterprise sectors. Both companies offer a wide range of docking solutions compatible with their laptops and tablets, enabling seamless device integration for professional users.
Meanwhile, Lenovo and Samsung are expanding their product offerings to cater to the increasing demand for docking stations in both consumer and enterprise markets. Targus and StarTech.com are focusing on innovation by introducing advanced docking stations with multiple connectivity options and wireless capabilities.
Recent Developments
In 2023, Dell Technologies launched its next-generation Thunderbolt 4 docking stations, designed to offer enhanced compatibility with a wider range of devices and support faster data transfers.
HP Inc. expanded its portfolio with USB-C docking stations featuring multi-port connectivity and dual 4K display support, targeting professionals working in hybrid environments.
Lenovo introduced a new line of ThinkPad Thunderbolt Dock Gen 3 stations, designed for high-performance connectivity in enterprise settings, supporting up to three 4K monitors simultaneously.
Targus announced the launch of wireless docking stations compatible with both Windows and macOS, aimed at providing cable-free solutions for home office users.
StarTech.com introduced its new range of docking stations, featuring 100W power delivery and compatibility with multiple USB-C devices, enhancing versatility for users in creative industries.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries. Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.
The global glaucoma therapeutics market is projected to be valued at approximately USD 6.9 million in 2022, with expectations to expand at a compound annual growth rate (CAGR) of 3.7% over the next decade, ultimately reaching around USD 10.2 million by 2032.
Key Growth Drivers:
The increasing demand for glaucoma therapeutics is significantly influenced by the growing geriatric population and advancements in diagnostic tools that facilitate early detection of glaucoma. As the elderly population becomes more prevalent, the incidence of glaucoma is expected to rise, highlighting the need for effective therapeutic options.
A notable trend within the market is the adoption of prostaglandin analogs, which have emerged as a preferred treatment option due to their efficacy and convenience. Furthermore, lifestyle changes, including increased screen time on devices such as smartphones and laptops, are contributing to the rising incidence of glaucoma among the elderly.
Innovation and Market Dynamics:
The glaucoma therapeutics market is also witnessing a surge in product innovation, with a variety of new treatments in the pipeline and recent product launches that aim to accelerate market growth. As the overall prevalence of glaucoma increases globally, the demand for effective therapeutic solutions is expected to follow suit.
Future Outlook:
With a robust pipeline of innovative products and the growing awareness of glaucoma’s implications, the market for glaucoma therapeutics is well-positioned for continued growth. Stakeholders in the healthcare industry are encouraged to invest in research and development to meet the rising demand for glaucoma treatments.
Laser surgery is more preferred than tradition surgery by booth surgeon and the patients owing to the low risk of failure. By glaucoma type, closed glaucoma will dominate the maximum market share attributed to its more prevalence then open glaucoma.
Glaucoma Therapeutics Market: Drivers and Restraints:
The change in the lifestyle of people has resulted in the rise in the prevalence of glaucoma globally. Increasing prevalence of glaucoma is the primary factor driving the growth of glaucoma therapeutics market around the globe. Glaucoma is more prevalent among the people above the age of 60. Rising geriatric population thought the globe is also responsible for the robust growth of glaucoma therapeutics market over the forecast period. Increasing preference of physician towards the laser surgery for the treatment of glaucoma will propel the growth of glaucoma therapeutics market over the forecast period.
Less awareness among the people about the glaucoma treatment will deter the growth of glaucoma therapeutics market to some extent. Moreover, lack of availability of skilled professional for laser surgery in under developing economies will also hamper the growth of glaucoma therapeutics market. Glaucoma is the eye disease that damage the patient eye nerve optics. The formation extra fluid up in the front part of the eye results the damage to eye nerve optics. Glaucoma is of two type, primary open-angle glaucoma and angle-closure glaucoma which is also referred as closed-angle glaucoma or narrow-angle glaucoma.
Open-angle glaucoma is the most common type glaucoma. Primary glaucoma gradually happens when the eye does not drain the fluids.
This result the building of pressure on eye nerve optics. Open glaucoma causes no change in the eye vision and it is painless too.
Closed-angle glaucoma happens very close to the drainage angle which results the blocking of drainage angle of eyesight. This is a very acute type of glaucoma.
This type of glaucoma may affect the vision of the patient and it may cause severe pain to the eye and the headache.
Glaucoma is generally treated with eye drops, pill, traditional surgery, laser surgery and sometimes the combination of these methods.
The aim of glaucoma treatment is to avoid the vision loss of patient wherever if the vision of particular patient is already lost then it is irreversible by glaucoma treatment.
Regular consumption of medication as prescribed by the physician is very necessary for the proper treatment of glaucoma.
The drugs of glaucoma have very fewer chances of effects which has increased it adoption the global market.
Some of player across the value chain of Glaucoma Therapeutics market are Novartis AG, Allergan, Merck & Co., Inc., Akorn, Inc., Bausch & Lomb Incorporated, Teva Pharmaceuticals, Pfizer and Santen and others.
The research report presents a comprehensive assessment of the market and contains thoughtful insights, facts, historical data, and statistically supported and industry-validated market data.
It also contains projections using a suitable set of assumptions and methodologies.
The research report provides analysis and information according to market segments such as geographies, application, and industry.
The report covers exhaust analysis on:
Market Segments
Market Dynamics
Market Size
Supply & Demand
Current Trends/Issues/Challenges
Competition & Companies involved
Technology
Value Chain
Regional analysis includes:
North America (U.S., Canada)
Latin America (Mexico. Brazil)
Western Europe (Germany, Italy, France, U.K, Spain)
Eastern Europe (Poland, Russia)
Asia Pacific (China, India, ASEAN, Australia & New Zealand)
Japan
Middle East and Africa (GCC Countries, S. Africa, Northern Africa)
The report is a compilation of first-hand information, qualitative and quantitative assessment by industry analysts, inputs from industry experts and industry participants across the value chain.
The report provides in-depth analysis of parent market trends, macro-economic indicators and governing factors along with market attractiveness as per segments. The report also maps the qualitative impact of various market factors on market segments and geographies.
Glaucoma Therapeutics Market: Segmentation
The global Glaucoma Therapeutics market is classified on the basis of treatment type, glaucoma type, and geographic region.
Based on treatment type, Glaucoma Therapeutics market is segmented into following:
Eye Drops
Medication
Laser Surgery
Traditional Surgery
Based on glaucoma type, Glaucoma Therapeutics market is segmented into following:
Open-angle glaucoma
Closed-angle glaucoma
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.