Exploring Growth: United States Bathroom Vanities Market CAGR at 6.7%, Forecasting USD 13.5 Billion Revenue by 2033

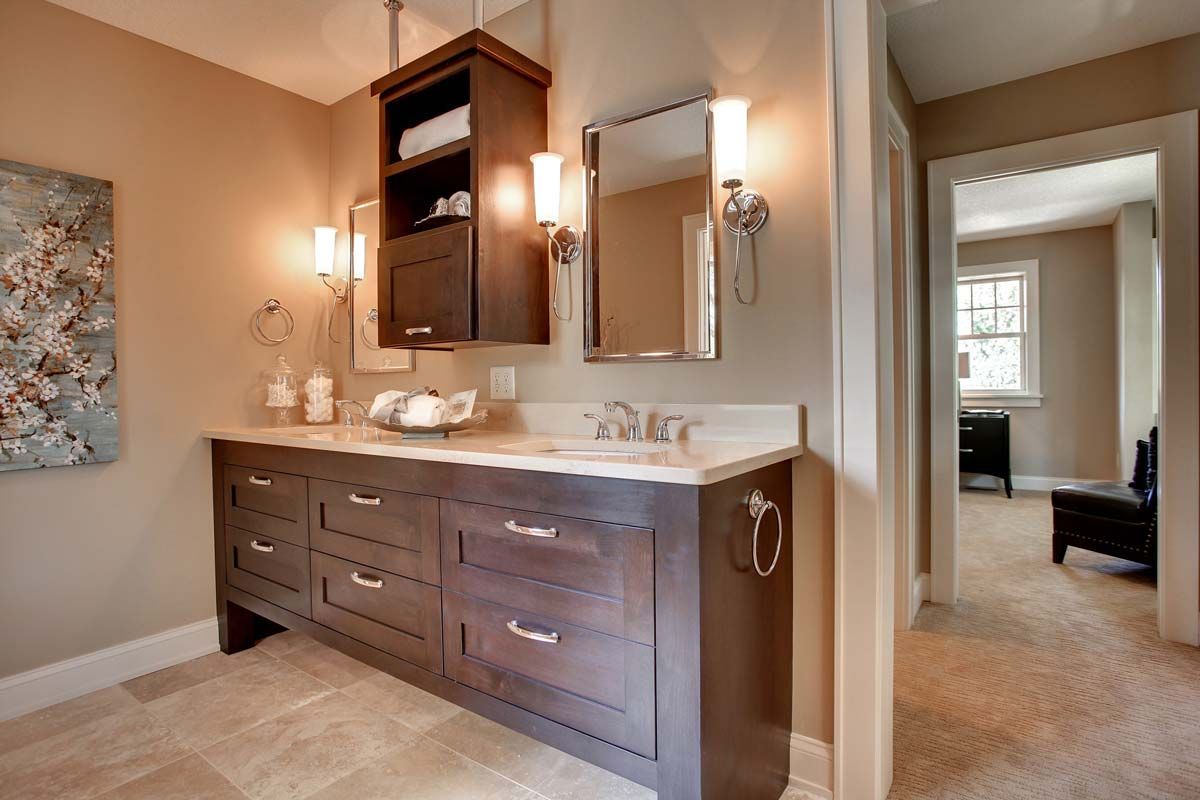
The United States bathroom vanities market is expected to grow at a CAGR of 6.7% from 2023 to 2033, reaching an estimated revenue of approximately USD 13.5 billion by 2033.

The market’s expansion is primarily fueled by renovations and new home constructions. There is an increasing consumer preference for eco-friendly materials, such as bamboo and reclaimed wood, alongside the enduring popularity of traditional materials like plywood and MDF.

Transitional and contemporary styles dominate the market, with consumers favoring clean lines, minimalist designs, and a variety of finishes. While single-sink vanities remain common, there is a noticeable rise in demand for double-sink options in larger bathrooms. Customizable and modular vanities are also gaining traction among buyers.

The global bathroom vanities market, valued at approximately USD 38.6 billion in 2022, is projected to reach USD 41.5 billion in 2023 and soar to USD 80.8 billion by the end of 2033. This remarkable growth, reflecting a CAGR of 6.9%, is fueled by increasing consumer interest in luxury and premium home products, particularly in bathroom renovations.

As homeowners increasingly prioritize upgrading their bathrooms, high-end bathroom vanities have emerged as central elements in renovation projects. This trend is further supported by a shift toward sustainable, eco-friendly options, aligning with consumers’ growing awareness of environmental issues. Manufacturers are responding with innovative designs and customizable options that cater to the unique preferences of discerning buyers.

Key Takeaways

  • The global bathroom vanities market is valued at USD 38.6 billion in 2022 and expected to reach USD 41.5 billion in 2023.
  • The market is projected to grow to USD 80.8 billion by 2033, with a CAGR of 6.9%.
  • Increasing consumer interest in luxury and premium bathroom products is driving demand.
  • There is a rising preference for customizable bathroom vanities that reflect individual styles.
  • Smart vanities featuring integrated technology are gaining popularity among consumers.
  • Sustainability is a key focus, with growing demand for eco-friendly materials.
  • The United States is projected to grow at a CAGR of 6.7%, expected to generate USD 13.5 billion by 2033.
  • The market faces challenges such as limited customization, durability concerns, and environmental impacts from production.

Regional Insights

  • United States: Projected to grow at a CAGR of 6.7%, expected to generate USD 13.5 billion by 2033.
  • China: Anticipated to expand at a CAGR of 6.5%, reaching approximately USD 10.9 billion by 2033.
  • United Kingdom: Set to grow at 5.9% CAGR, with a market size expected to reach USD 2.4 billion by 2033.
  • Japan: Estimated to achieve a market value of USD 6.8 billion by 2033, with a CAGR of 5.8%.
  • South Korea: Projected to reach USD 3.5 billion by 2033, growing at a CAGR of 6.2%.

Competitive Landscape

Key manufacturers are continually innovating bathroom vanity designs, materials, and features to align with evolving consumer preferences. This includes the integration of smart technology, eco-friendly materials, and space-saving solutions. They emphasize sustainable practices by utilizing recycled materials and promoting energy-efficient production processes, providing eco-friendly product options to attract environmentally conscious consumers.

Recent Developments

  • In May 2023, Houston bathroom remodeling company Kitchen and Bath Designs announced a Memorial Day sale
  • In July 2023, Crate & Barrel moved into the home restoration area with an expanded line of culinary the islands, bathroom vanities, and other items that allow customers to renovate their homes without using professionals or demolition.
  • In December 2022, at Chandigarh’s Hotel Park Plaza, Essel debuted its distinctive collection of bathroom vanities and faucets in various colors.

Key Companies Profiled

American Woodmark Corporation

Avanity Corporation

Bellaterra Home, LLC

Design Element Group, Inc.

Design House (DHI Corp.)

Tap into Expertise: Discuss with Our Analyst on Email: sales@futuremarketinsights.com

Bathroom Vanities Market Outlook by Category

By Application:

  • Residential
  • Non-residential

By Material:

  • Stone
  • Ceramic
  • Glass
  • Wood
  • Metal

By Size:

  • 24 to 35 inch
  • 38 to 47 inch
  • 48 to 60 inch

By Region:

  • North America
  • Latin America
  • Western Europe
  • Eastern Europe
  • East Asia
  • South Asia and the Pacific
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Global Frozen Seafood Sales to Grow at a CAGR of 6.8% from 2024 to 2034

Frozen Seafood Market

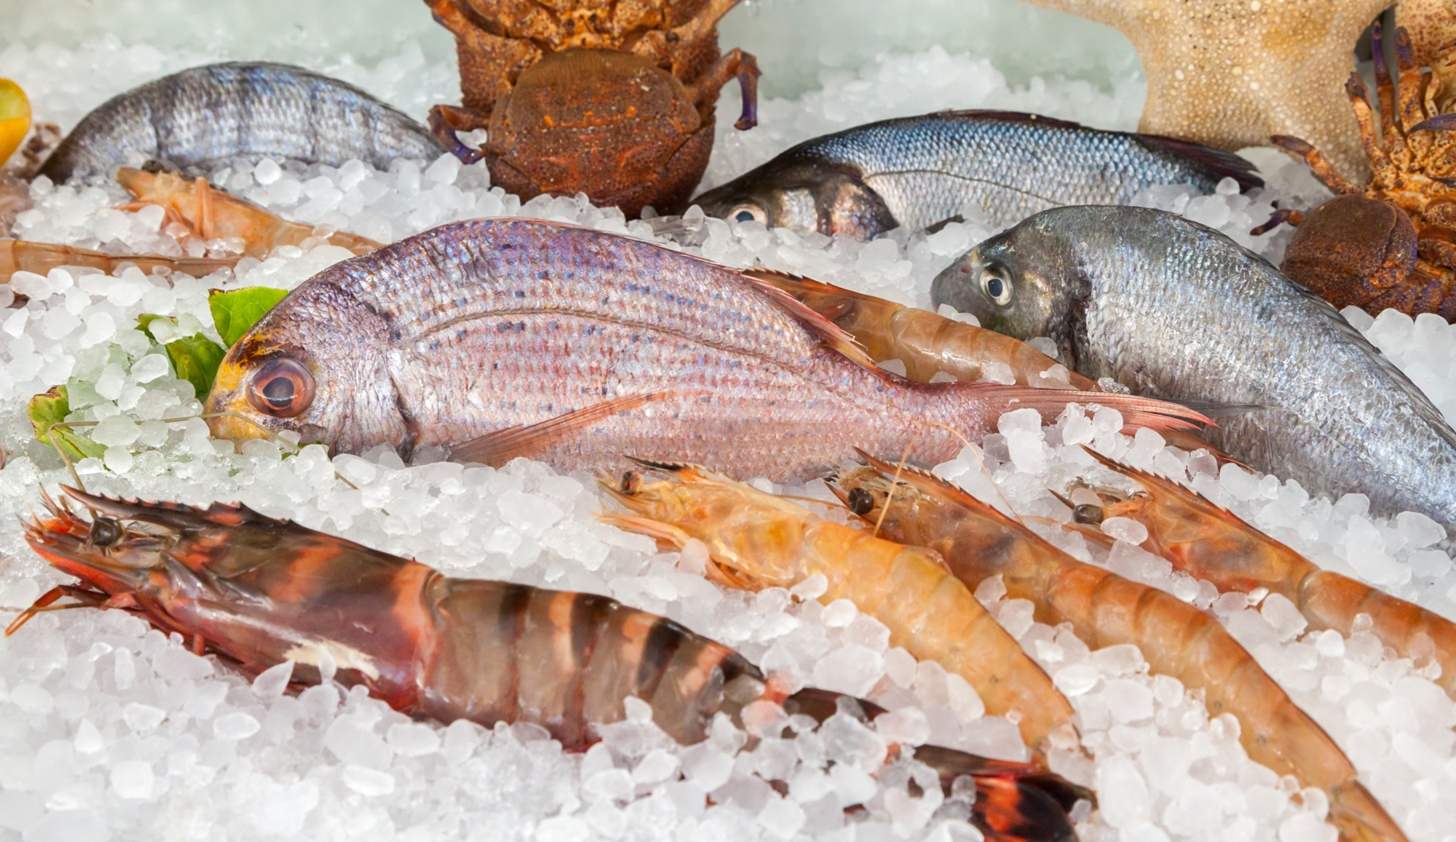
The frozen seafood market is valued at USD 21,995.1 million in 2024 and is anticipated to reach USD 42,657.6 million by 2034. The market is projected to grow at a CAGR of 6.8% from 2024 to 2034.

Customers’ tastes have changed as a result of their increased consciousness of health and wellness, driving sales of frozen seafood products. There is a noticeable tendency to select options that fit dietary preferences and nutritional needs and are thought to be healthier. As a result of this change in consumer awareness, companies have introduced frozen seafood options to meet the needs of these growing health-conscious consumers.

Moreover, the growing consumer demand for frozen seafood as a thickening agent has boosted the global frozen seafood market’s growth. Factors influencing the choice of thickener include frozen state, clarity, taste, and PH, all of which are provided by frozen seed food in a balanced form. As a result, the market’s revenue contribution is anticipated to significantly increase over the forecast period.

“The growing awareness of health and wellness among consumers is fueling sales of frozen seafood products. Companies are capitalizing on this trend and introducing frozen seafood options to gain a higher market share,” says an analyst at FMI.

Key Takeaways from the Report

  • The frozen seafood market is expected to reach a valuation of US$ 42,657.6 million by the end of 2034, growing at a CAGR of 6.8% over the forecast period.
  • The United States is projected to hold a value share of 24.5% in 2024, leading the market.
  • Japan is projected to account for a value share of 1.7% in 2024.
  • The market in India is estimated to rise at a CAGR of 5.9% during the forecast period.

Key Players Invest in Research & Development as the Ultimate Growth Strategy

The industry is defined by a high level of capital expenditure and a complicated manufacturing process. Cost-effective manufacturing procedures can help establish market sustainability. Frozen seafood manufacturers are pursuing strategic alliances and partnerships with other manufacturers to enhance productivity and meet consumers’ demands.

Some of the key players in the market are Marine Harvest ASA, Austevoll Seafood ASA, SalMar, Coast Seafood, Charoen Pokphand Foods, Fortune Fish & Gourmet, Maruha Nichiro, Norway Royal Salmon, Mitsubishi Corporation, Trident Seafood, etc.

Country-wise Insights

Countries CAGR (2024 to 2034)
United States 4.9%
United Kingdom 5.2%
Germany 5.0%
China 4.2%
India 5.9%
Japan 5.6%

Buy Report now

Key Market Segments Covered in Frozen Seafood Industry Analysis

By Nature:

  • Organic
  • Conventional

By Form:

  • Raw
  • Processed

By End-Use:

  • Food Processing Industry
  • Food Service Industry
  • Retail/Household

By Product Type:

  • Fish
    • Marine Pelagic
    • Marine Demersal
    • Diadromous
    • Others
  • Molluscs
    • Bivalves
    • Gastropods
    • Cephalopods
    • Others
  • Crustaceans
    • Shrimps
    • Crabs
    • Lobsters
    • Krill
    • Others
  • Others

By Distribution Channel:

  • Business to Business (Manufacturers and Distributors)
  • Business to Consumer
    • Modern Trade (Hypermarket & Supermarket)
    • Convenience Stores
    • Traditional Grocery Stores
    • Specialist Food Stores
    • Wholesale Stores
    • Discount Stores
  • E-commerce/Online Stores

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • MEA

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact FMI:
Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website:https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Global Endodontics and Orthodontics Market Set to Surge: Projected CAGR of 5.3% by 2032

The global endodontics and orthodontics market is witnessing an unprecedented surge, with market experts predicting a steady Compounded Annual Growth Rate (CAGR) of 5.3% between 2022 and 2032. With sales projected to reach an impressive USD 5.09 billion by 2022, this sector is on a promising growth trajectory, driven by innovation, evolving patient preferences, and a heightened focus on oral health.

Technological Innovations Transforming Dental Care:

Technological advancements are reshaping treatment methodologies, resulting in more efficient, less invasive procedures that are enhancing patient experiences. Innovations like digital radiography and 3D imaging have significantly improved the accuracy of diagnostics and treatment planning, particularly in endodontics. These technologies are setting a new standard for precision and patient comfort, further driving demand for dental care.

In orthodontics, clear aligners and computer-aided design (CAD) systems are revolutionizing traditional treatments, offering more aesthetically pleasing and comfortable solutions for patients. This technological evolution aligns with the increasing patient awareness and preference for aesthetically focused dental treatments, particularly among adults seeking orthodontic care.

Rising Demand for Preventive and Aesthetic Dental Care:

Patient awareness of preventive oral health care is on the rise, with more individuals prioritizing regular dental checkups and treatments. This focus on prevention has significantly contributed to the growing demand for both endodontic and orthodontic services. Additionally, the demand for aesthetic dental treatments, such as clear aligners and cosmetic orthodontic procedures, has skyrocketed, further fueling market growth.

Endodontics and Orthodontics: Market Breakdown:

The endodontics market includes a wide range of tools, materials, and professional services. From endodontic files to apex locators and specialized dental chairs, these tools are essential for performing complex procedures such as root canals. Advances in disinfectants, sealers, and gutta-percha materials have also improved treatment outcomes.

In the orthodontics market, traditional braces and innovative clear aligners dominate. The development of custom orthodontic appliances using CAD systems has made orthodontic care more personalized and effective. Manufacturers of brackets, wires, and other orthodontic devices are playing a pivotal role in driving this market forward.

Opportunities for Stakeholders:

With the endodontics and orthodontics sectors rapidly expanding, a wide array of opportunities has emerged for stakeholders across the industry. Dental practitioners, equipment manufacturers, and product suppliers are all set to benefit from the rising demand for innovative treatments and preventive care.

As the market continues to evolve, the industry is expected to witness increased investment in research and development, fostering further advancements and market expansion. The future of endodontics and orthodontics promises continued growth, with numerous opportunities for innovation and increased access to cutting-edge dental care.

Soaring Demand for Market Information: Uncover Detailed Trends and Insights in Our Report!

Competitive Landscape:

Examples of some of the key players featured in the Endodontics and Orthodontics market report include:

  • Danaher
  • Dentsply Sirona
  • 3M
  • Align Technology
  • Straumann Group
  • Henry Schein
  • Dentsply Sirona
  • Danaher
  • 3M
  • Institut Straumann AG
  • Align Technology, Inc.
  • Coltene Group

Market Segmentation:

The endodontics and orthodontics market is segmented by product type, application, and region.

  • By product type, the market is segmented into instruments and consumables. Consumables are expected to dominate the market during the forecast period due to their high volume usage.
  • By application, the market is segmented into endodontics and orthodontics. Orthodontics is expected to be the fastest-growing segment during the forecast period due to the rising demand for cosmetic dentistry.
  • By region, the market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. North America is expected to account for the largest market share during the forecast period due to the high prevalence of dental diseases and the early adoption of new technologies.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Refined Functional Carbohydrates Market to Reach USD 400 Million by 2033, Says Future Market Insights, Inc.

Refined Functional Carbohydrates Market

The refined functional carbohydrates market is estimated to reach a valuation of USD 232.54 million in 2023. The market’s overall valuation may thrive at a CAGR of 5.7% between 2023 and 2033. According to estimates, by 2033, the market is likely to be worth USD 404.81 million.

Increasing consumption of functional foods, including functional carbohydrates, is resulting in a steady increase in demand for refined functional carbohydrates. As gut health plays an important role in livestock production. Therefore, to improve immunity, refined functional carbohydrates are often added to animal feeds.

Energy and functional ingredients can also be obtained from highly refined carbs. For example, refined functional carbs are used in poultry feed formulations to increase the efficiency of feed utilization, which reduces feed costs and improves animal performance.

For the refined functional carbohydrates market to grow, several factors must be considered. This includes the expanding animal feed industry, the growing need for nutritious foods, and the rising disposable income of people around the world.

Refined functional carbohydrates are expected to grow substantially as disposable incomes rise and health benefits become more apparent. Research and development expenditures for agro genomics are an important factor determining the growth of the refined functional carbohydrates market.


Drivers
  • Animal protein demand is on the rise
  • Potential health benefits for human
  • Governments and regulatory agencies provide support
Restraints
  • Production cost is relatively high
  • Limited awareness and understanding of benefits
Opportunities
  • Rise in demand for sustainable and natural products
  • Emerging market in Asia Pacific region due to increasing demand for animal protein

Key Takeaways from Market Study

  • The refined functional carbohydrates market is expected to record a CAGR of 5.7% over the forecast period.
  • The Mannan oligosaccharides product segment is forecast to register a 6.8% CAGR through 2033.
  • The United States is likely to have a significant market share of 89.9% in the North America region.
  • South Korea accounts for 65.0% of the market share in the Asia Pacific in 2023.

Competitive Landscape:

Companies operating in the global market are focusing on product launches with various claims to meet emerging consumer demands. Refined carbohydrates are also becoming increasingly popular as an ingredient in products. For instance, products such as white bread, white flour, pasta, and white wine, among others.

Several prominent companies that dominate this market, including refined functional carbohydrates, are DuPont Danisco, Lallemand, Orffa, VWR Corporation, Super Beta Glucan, Pet Health Solutions, and others.

Recent Developments:

  • A new funding program for the improvement or expansion of livestock and dairy slurry stores was launched in December 2022. This program enables livestock and dairy farmers to apply for grants of up to US$ 309,612.
  • Korea’s Ministry of Agriculture, Food and Rural Affairs (MAFRA) decided to remove longstanding trade barriers in September 2022. Removal of this trade barrier can improve pork and poultry exports to the European Union. By adopting such initiatives, livestock farming may be boosted, resulting in greater utilization of D-mannose carbohydrates in animal feed.

Grab Premium Report and Stay Ahead of Your Competition! https://www.futuremarketinsights.com/checkout/16947

Market Segmentation by Category

By Product:

  • Mannan Oligosaccharides
  • Beta-glucan
  • D-Mannose

By Application:

  • Cattle/Calves
  • Poultry
  • Swine
  • Aquaculture

By Region:

  • North America
  • Latin America
  • Europe
  • The Middle East and Africa
  • East Asia

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact FMI:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-845-579-5705
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

According to FMI Cryogenic Label Market Size, Forecast, Analysis and Share Surpass USD 2,126.6 Million | 2034, At 6.20% CAGR

The demand for cryogenic labels is reaching unprecedented heights, driven by advancements in precision medicine and the growing reliance of the global healthcare sector on biobanks. As of 2024, the cryogenic label market is valued at USD 1,166.8 million and is projected to grow at a remarkable CAGR of 6.20%, potentially reaching USD 2,126.6 million by 2034.

Cryogenic labels, essential for tracking and identifying samples in various industries, are increasingly being utilized beyond their traditional applications in healthcare and academia. The recent boom in the pharmaceutical sector, spurred by the COVID-19 pandemic, has further influenced market dynamics. Companies within the pharmaceutical industry are leveraging cryogenic labels to effectively track and manage samples critical for vaccine development, production, and distribution.

This surge in demand is also supported by significant investments from both public and private pharmaceutical entities, which are keen to enhance their capabilities in sample management. The versatility of cryogenic labels is now being recognized across diverse sectors, including biotechnology, food processing, industrial manufacturing, aerospace, veterinary medicine, and academic research institutions.

Unlock Comprehensive Insights—Read the Full Report Today!

Moreover, the integration of cryogenic labels with cutting-edge digital technologies—such as barcode systems, RFID tags, and laboratory information management systems—has transformed their functionality. These advancements facilitate the automation of data capture, enable real-time tracking, and ensure seamless integration, ultimately enhancing the overall performance of cryogenic labels.

“The cryogenic label market is poised for significant growth as industries increasingly adopt advanced labeling solutions for extreme conditions. Innovations in materials and adhesives will drive efficiency and reliability in applications ranging from pharmaceuticals to food storage.” Says a Lead Consultant Ismail Sutaria in Packaging at Future Market Insights (FMI).

Prominent Drivers of the Cryogenic Label Market

  1. Increasing Demand for Cryogenic Applications: The growing use of cryogenic technologies in various industries, such as healthcare (for biobanking and cryopreservation), aerospace, and energy, drives the demand for cryogenic labels. These labels are essential for ensuring proper identification and traceability of cryogenic materials and samples.
  2. Technological Advancements: Innovations in label materials and printing technologies enhance the durability, visibility, and performance of cryogenic labels. Improved adhesive properties and resistance to extreme temperatures and moisture make these labels more effective in cryogenic environments.
  3. Stringent Regulatory Compliance: Regulatory standards and guidelines in sectors like pharmaceuticals and biotechnology necessitate precise labeling for cryogenic products. Compliance with these regulations drives the demand for reliable and standardized cryogenic labels.
  4. Growth of the Life Sciences Sector: The expansion of the life sciences industry, particularly in research, development, and clinical trials, increases the need for cryogenic storage solutions. This, in turn, boosts the demand for cryogenic labels to ensure proper management of biological samples.
  5. Rising Investments in R&D: Increased investments in research and development activities in fields such as cryogenics and materials science promote the growth of the cryogenic label market. As new applications emerge, the demand for specialized labels tailored to these innovations rises.

Key Takeaways From The Cryogenic Label Market

  • The sensor data analytics market was valued at USD 1,099.4 million in 2023.
  • China is a key player, projected to grow at a CAGR of 7.10%.
  • Thailand is anticipated to see a CAGR of 6.90% through 2034, highlighting its market potential.
  • Canada is also expected to flourish, with a CAGR of 5.90% forecasted through 2034.
  • South Korea’s market outlook is positive, with a projected CAGR of 5.60% through 2034.
  • India is slated for growth with a CAGR of 7.60% during the forecast period.
  • Permanent adhesives hold a dominant market share of 71.10% as of 2024, indicating a strong preference in the industry.

Competitive Landscape

The cryogenic label business is well-established, with a large number of companies competing for international domination. Following the pandemic, its significance has skyrocketed, with corporations investing more money in enhancing their cryogenic storage facilities. This has opened up new opportunities for cryogenic label producers to create sustainable and cheap goods that meet the needs of environmentally concerned customers and enterprises.

Key Companies

  • Brady Corporation
  • Thermo Fisher Scientific Inc.
  • GA International Inc.
  • Weber Packaging Solutions, Inc.
  • LabTAG – Division of GA International Inc.
  • CryoSafe – Custom Biogenic Systems
  • Cryo Coders
  • Cryo Ink
  • Tektag
  • CryoElite
  • Nalgene
  • Eppendorf
  • Remel Inc.
  • Bel-Art – SP Scienceware
  • CryoChoice
  • Cryo-ID
  • StarLabel Products
  • Cryo Supplies
  • Cryo Labels
  • TydenBrooks Security Products Group

Recent Developments

  • In July 2022, Schreiner MediPharm developed Freeze-Lock, a cryo label enduring sub-zero temps for medications like COVID-19 vaccines. It featured two layers ensuring adhesive strength and readability, meeting storage demands for crucial therapies.
  • In August 2021, FLEXcon Company, Inc. launched its revamped PHARMcal® line, offering track and trace solutions for pharmaceutical labeling. The simplified product range streamlines selection for customers, ensuring consistent quality and performance across global availability.
  • In May 2020, Mactac unveiled new cryogenic labels designed for extreme temperatures as low as -320 degrees Fahrenheit. The labelstocks featured advanced adhesives and were intended for use in medical research, clinical laboratories, and biobanks, providing reliable identification in harsh conditions.
  • In October 2022, Avery Dennison engineered a new portfolio of label materials, the Pharmaceutical and Healthcare Collection, meeting rigorous standards. This collection addressed growing demands for innovation in pharmaceutical labeling amid heightened focus on health and wellness during the pandemic.

Key Segments of the Cryogenic Label Industry

By Adhesive Type:

  • Permanent
  • Removable

By Material Type:

  • Nylon
  • Polyester

By End User:

  • Laboratory
  • Chemical
  • Healthcare
  • Electronics
  • Shipping
  • Other

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • Middle East & Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Traction Motors Market to Surpass USD 30.0 Billion by 2032, Growing at 13.0% CAGR

Traction Motors Market

Global sales of traction motors reached approximately USD 11.7 billion in 2022, with demand expected to grow at a CAGR of 13.0% from 2022 to 2032, surpassing a valuation of USD 30.0 billion by 2032. This growth is driven by increasing demand for high-performance motors across industries such as automotive and electronics.

Traction motors are essential for their rotational properties, which provide the necessary torque for engines and machines. They play a critical role in various electrical and industrial applications, including elevators, escalators, and locomotives.

Advancements in hybrid combustion engine technology are further boosting the integration of traction motors to enhance efficiency. The growing demand for land, air, and water vehicles is also contributing to the adoption of traction motors globally.

Additionally, the rising trend of automation in mechanical operations has underscored the importance of traction motors. Their use in consumer appliances like washing machines will continue to drive demand in the global market.

Key driver of the global market for traction motors

  • Rising demand for efficient power conversion
    Under normal conditions, traction motors are efficient in converting a majority of the electrical power into mechanical energy, which assists the locomotive operations such as dynamic braking.
  • Increasing electrification of automobiles
    The demand for electric vehicles (EV) has gained considerable traction in the automotive industry. As a result, there is a subsequent upsurge in the demand for EV traction motors.
  • Varying emission standards
    Technological developments owing to the changing emission regulations has generated the demand for engines with reduce emissions. This is steering the demand for more enhanced and fuel-efficient traction motors in the global market.
  • The only constraints reshaping the dynamics of the market include the operational glitches of traction motors. The overheating of traction motors is one of the major restraints hampering the growth of the global market. The insulation breakdown and the commutation malfunctions are also observed as the factors limiting the adoption of traction motors.

    Leading Industrial Contributors

    Expanding the product portfolio by enhancing the existing range of traction motors will be observed as the key strategy by manufacturers. Aisin, ABB, Alstom, General Electric, Continental, Mitsubishi, Magna International, and Toshiba, among others can be regarded as the leading companies in the global market for traction motors.

    The research report presents a comprehensive assessment of the market and contains thoughtful insights, facts, historical data, and statistically supported and industry-validated market data. It also contains projections using a suitable set of assumptions and methodologies. The research report provides analysis and information according to market segments such as geographies, types and applications.

    Among the regional segmentation of the global market, Asia Pacific is expected to witness higher production of traction motors, owing to the booming automobile sales in countries such as China, Japan and South Korea. The rising industrialisation in North America is anticipated to promote the use of traction motors in several manufacturing machinery. Also, the advancements incorporated with traction motor technology are also predicted to boost the demand in European countries such as United Kingdom.

    Key Companies Profiled

  • Aisin
  • ABB
  • Alstom
  • General Electric
  • Continental
  • Mitsubishi
  • Magna International
  • Toshiba

Market Segmentation & Regional Overview
Application:
• Transportation
• Industrial machinery and equipment
• Others

End Users:

• Hybrid vehicles
• Compact construction equipment
• Escalators
• Elevators
• Other (Washing machines, Electric Aircraft, etc.)

Region:
• North America
• Latin America
• Western Europe
• Eastern Europe
• APEJ
• Japan
• Middle East & Africa

Report Preview: https://www.futuremarketinsights.com/reports/traction-motors-market

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogsYouTube

Global Wall Art Market Poised for Significant Growth Driven by Minimalism and DIY Trends

The global wall art market is poised for significant growth, with a projected valuation of approximately USD 94.8 billion by 2033, reflecting a compound annual growth rate (CAGR) of 5.4% from 2023 to 2033. As of the end of 2023, the market size is expected to be around USD 56.2 billion, indicating a robust financial potential of USD 38.6 billion during the forecast period.

Key Drivers of the Global Wall Art Market

  • Rising Demand for Minimalism: Increased consumer preference for minimalist design in North America is enhancing wall art demand, as individuals seek clean lines and simplicity in their interiors.
  • Growing Home Ownership: The rise in home ownership across Europe is prompting consumers to invest in personalized wall art to reflect their individual styles in newly acquired spaces.
  • Influence of DIY Culture: The popularity of platforms like Pinterest and Instagram is inspiring DIY enthusiasts in the Asia Pacific region, leading to greater creativity and engagement with wall art projects.
  • Technological Advancements: The integration of digital art technologies is enabling high-quality reproductions and diverse presentation options, catering to consumer demands for unique and timely products.
  • Focus on Sustainability: Increasing awareness and demand for eco-friendly products are driving manufacturers to adopt sustainable materials and practices, appealing to environmentally conscious consumers.
  • Post-Pandemic Home Decor Trends: The shift towards personalized and aesthetically pleasing living spaces, fueled by the pandemic, continues to influence consumer spending on wall art.
  • Artisan Engagement: The growing interest in purchasing art directly from artisans is fostering a deeper connection between consumers and unique wall art pieces, enhancing market growth.

Regional Insights

  • United States: The market is projected to reach USD 16.3 billion by 2033, driven by demand for unique, artisanal wall art that allows for personal expression.
  • China: Expected to reach USD 13.3 billion by 2033, traditional art forms and Feng Shui principles are boosting wall art demand, particularly wall hangings.
  • Japan: Anticipated to achieve a market valuation of USD 8.9 billion by 2033, commercial spaces are increasingly utilizing wall art to enhance brand identity and consumer experience.
  • United Kingdom: With a projected market size of USD 3.4 billion by 2033, demand for eco-friendly wall art made from sustainable materials is rising among environmentally conscious consumers.
  • South Korea: Expected to develop a market worth USD 4.2 billion by 2033, the popularity of K-dramas is driving millennials to replicate visually appealing aesthetics in their interiors.

Competitive Landscape

Leading wall art providers are employing a mix of organic and inorganic strategies to stay competitive in today’s dynamic market. Many companies are securing licensing agreements for popular artworks or collaborating with artists to offer unique designs, allowing them to create appealing art collections and connect with dedicated fan bases.

Prominent brands are also focusing on expanding their international reach beyond domestic markets to better understand diverse cultural preferences and explore new growth opportunities.

The rapid growth of online marketplaces and e-commerce platforms is expected to revolutionize the way wall art is sold and purchased. Many providers are actively working to enhance their online presence through well-known marketplaces and their own websites, aiming to deliver products directly to customers’ doorsteps and boost sales.

For instance,

  • In September 2023, A Square Designs, a Kolkata-based company, introduced its new range ‘Power of Wall Art.’ Its new exhibit is proof that carefully placed wall art can transform any room from the commonplace to the exceptional.
  • In July 2023, Art Prints AI, a maker of artificial intelligence (AI) generated prints and wall art, unveiled its latest collection on its official website. The collection’s original landscapes, abstract patterns, and portrait images are made with a variety of aesthetics in mind. The company’s goal is to establish itself as a market leader for digital artists’ AI-generated wall art.
  • In May 2023, the most popular online seller of gigantic wall art in the world, BIG Wall Decor, launched a new range that honors the season’s airy vibe. The freshly released Minimalist line of prints has a lot of clean space with pops of vibrant color. Themes span from the geometric artwork of Karine Tonial Grimm to the vivid abstract works of Artur Chen.

Wall Art Market Top Players

VGL Group

Art.com Inc.

Uprise Art LLC

Saatchi Art Limited

Society6 LLC

Get Strategic Guidance from Our Analyst Contact us on: +1-347-918-3531

Global Segmentation of Wall Art Market

By Type:

  • Wallpapers/Stickers/Wall Coverings
  • Hangings
  • Frameworks
  • Décor Shelves
  • Others

By Sales Channel:

  • Offline
  • Hypermarkets and Supermarkets
  • Specialty Stores
  • Others
  • Online

By Application:

  • Residential
  • Commercial

By Region:

  • North America
  • Latin America
  • Western Europe
  • Eastern Europe
  • South Asia and Pacific
  • East Asia
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Global Soft Touch Film Market to be Worth USD 3.9 Billion by 2034: Future Market Insights, Inc.

The soft touch film market value is expected to rise from USD 2.9 billion in 2024 to USD 3.9 billion by 2034. The market is analysed to surge ahead at a CAGR of 3.1% over the next decade.

The global soft touch film market is expected to experience significant growth due to increased promotion activities across industrial and commercial sectors and the increasing use of these films in electronic packaging.

Soft touch films, made from plastics like polypropylene, polyethylene terephthalate, and polyethylene, provide a velvety texture and a scuff-resistant surface that enhances and protects the substrate product’s appearance. They are primarily designed for one-side lamination and come in three types of coatings: water-based, solvent-based, and FDA-compliant.

Demand for soft touch films is increasing due to their ability to enhance textural feel, minimize glare, preserve image color, and offer vivid color clarity. End users are shifting their preference towards ultra-matte soft touch films due to their premium finish, fingerprint resistance, protection from toner chipping, and enhanced grip.

Find Out More—Read the Complete Report for Full Insights!

Soft touch films are also being used in the printing and publishing sector for applications such as corporate brochures, postcards, boxes, and premium prints. However, factors such as increasing costs, decreasing substrate color brightness, and strict regulations regarding plastic use are hindering sales.

Consumers are increasingly favoring sophisticated and luxurious packaging, driving demand for soft touch films that enhance the tactile and visual appeal of premium products. The growth of the electronics industry and the need for protective, scuff-resistant packaging for electronic devices are boosting the demand for soft touch films. Leading companies are continuously introducing innovative soft touch film products to meet changing consumer demands.

“The growing popularity of reading among millennials and collaborations between well-known authors and publishers are further encouraging the use of soft touch films in the literary sector,” says a Lead Consultant Ismail Sutaria in Packaging at Future Market Insights (FMI).

Key Takeaways from the Soft Touch Film Market Report

  • Historically, the soft touch film sector grew at a pace of 2.8%. The market’s worth rose from USD 2.4 billion in 2019 to USD 2.8 billion in 2023.
  • Polypropylene is predicted to hold a leading position throughout the projection period. The category is expected to have a 34.1% share in 2024.
  • In 2024, packaging sector is expected to have the largest market share of 52.3%.
  • In the United States, the industry is predicted to report a CAGR of 1.9% over the forecast period.
  • In Asia Pacific, India and China are the top achievers, with CAGRs of 5.5% and 4.8%, respectively, throughout the predicted period.
  • The demand from Spain is anticipated to register a CAGR of 2.7% by 2034.

Competitive Landscape

The soft touch film market is experiencing a fascinating shift. Leading players are prioritizing sustainability, and recognizing the growing consumer demand for eco-friendly packaging solutions such as biopolymer, and bioplastics. The evolution of the industry translates to a surge in research and development of lamination paper made from recycled or biodegradable materials.

At the same time, international companies are pursuing strategic alliances such as mergers and acquisitions. The partnerships, particularly with domestic firms and innovative startups, offer access to new technologies and expertise.

This allows them to expand their product portfolios of soft lamination film, catering to a wider range of applications and propelling global sales. The dynamic landscape signifies a future where eco-conscious layering films are anticipated to be at the forefront, driven by both consumer preferences and strategic industry collaborations.

Key Players of the Soft Touch Film Industry

  • Amcor Limited
  • Dow Chemical Co.
  • Doro Tape (UK) Ltd.
  • Monotech Systems Ltd.
  • Avery Dennison Corporation
  • DUNMORE Corporation
  • Ampacet Corporation
  • Pragati Corporation
  • Jet Technologies
  • Taghleef Industries SLU
  • Flex film Limited
  • Cosmo Films, Ltd.

Recent Industry Developments in Soft Touch Film Market

A soft touch, home compostable film line from Earthfirst® Films was unveiled in May 2023. It is intended for use in a variety of applications, including produce labels, retail bags, and e-commerce shipping envelopes. The films are available in clear matte, white gloss, and strong side seals. They are created from a special combination of biopolymers and are friendly to greenhouse gases (GHGs).

Key Segments of the Soft Touch Film Industry

By Material:

In terms of material, the industry is divided into Polypropylene (PP), Polyvinyl Chloride (PVC), Polyester (PET), Polyamide (PA), Polyethylene (PE), and other materials such as EVA, and EVOH.

By Thickness:

In terms of thickness, the industry is segregated into upto 0.1 mm, 0.1 to 0.5 mm 0.5 to 1.0 mm, and above 1 mm.

By End-use:

End use industries of the sector are lamination, packaging, printing and publication.

By Region:

Key countries of North America, Latin America, Europe, East Asia, South Asia, Middle East and Africa (MEA), and Oceania have been covered in the report.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:     

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Die Bonder Equipment Market to Surpass USD 6,726.7 Million by 2033, Driven by 4.3% CAGR

Die Bonder Equipment Market

According to a report by Future Market Insights (FMI), the die bonder equipment market is valued at USD 4,415.3 million in 2023 and is projected to exceed USD 6,726.7 million by 2033, with a CAGR of 4.3% during the forecast period.

The growing demand for advanced semiconductor devices, such as microchips and sensors, is driving the need for high-precision die bonding solutions. As consumer electronics, automotive technologies, and IoT devices continue to advance, die bonder equipment manufacturers are experiencing increased demand for their cutting-edge machinery.

The industry’s focus on miniaturization and enhanced functionality in electronic components fuels innovation in die bonder technology. Manufacturers are tasked with developing equipment capable of handling smaller and more complex die sizes, making die bonding a crucial step in semiconductor production.

The rise of 5G technology and the increasing adoption of electric vehicles are also significant contributors to the industry’s growth. These trends highlight the need for faster, more efficient die bonding processes to support these evolving technologies.

However, the industry faces certain challenges. The high initial capital investment required for advanced die bonder equipment can deter smaller manufacturers from entering the market, limiting competition and innovation. Additionally, stringent regulatory requirements, particularly in the electronics and automotive sectors, present compliance hurdles, demanding significant resources to meet safety, quality, and environmental standards.

Despite these challenges, the die bonder equipment market offers numerous growth opportunities. Innovations in materials, processes, and energy efficiency can enhance sustainable semiconductor manufacturing, catering to the increasing demand for green technologies.

Another emerging trend is the adoption of Industry 4.0 principles, driving the development of smart, interconnected die bonder equipment. These systems enable real-time monitoring, predictive maintenance, and remote operation, improving overall efficiency. Furthermore, the industry is shifting toward hybrid bonding technologies, which support the bonding of various materials and substrates, aligning with the demand for versatile die bonder equipment across diverse semiconductor applications.

Key Takeaways from the Die Bonder Equipment Market:

  • Fully automatic die bonders emerge as the dominating product type, with a 36.7% market share in 2023.
  • Integrated Device Manufacturers retain a grip as the top end-user category, holding a significant market share of 67.20% in 2023.
  • The United States holds a 2.3% market share in 2023, driven by its rising technology and manufacturing sector.
  • Germany holds a 1.7% market share in 2023, leveraging its engineering excellence.
  • The United Kingdom commands a 2.0% market share in 2023, fueled by emerging tech markets.
  • China secures a substantial 4.9% market share in 2023.
  • India accounts for a 5.2% market share in 2023, powered by its electronics manufacturing sector.
  • Japan holds a 2.6% market share in 2023, emphasizing precision engineering.

Competition Outlook for the Die Bonder Equipment Market:

The competition in the die bonder equipment industry is dynamic and characterized by several key players vying for market share and innovation. Leading companies such as Kulicke & Soffa Industries Inc., Palomar Technologies, Besi, ASM Pacific Technology Ltd., and Shinkawa Electric Co., Ltd. are at the forefront of die bonder equipment manufacturing. These industry giants continually invest in research and development to introduce cutting-edge technologies and equipment, aiming to meet the evolving demands of semiconductor and electronics manufacturers.

In addition to established players, the die bonder equipment sector also witnesses the emergence of innovative startups and smaller companies. These startups often focus on niche markets, offering specialized solutions catering to industry needs. Their agility and capacity to address unique customer requirements contribute to the industry’s diversity.

Key Companies Operating in the Die Bonder Equipment Industry:

  • Besi
  • ASM Pacific Technology Limited (ASMPT)
  • Kulicke & Soffa Industries Inc.
  • Tresky AG
  • SHIBAURA MECHATRONICS CORPORATION
  • West·Bond, Inc.
  • Panasonic Corporation
  • MRSI Systems
  • SHINKAWA LTD.
  • Palomar Technologies
  • DIAS Automation
  • Toray Engineering
  • FASFORD TECHNOLOGY

Die Bonder Equipment Industry Key Segments:

By Product Type:

  • Manual
  • Semi-automatic
  • Fully Automatic

By Attachment Method:

  • Epoxy
  • Eutectic
  • Soft Solder
  • Flip Chip

By End Use/User:

  • Integrated Device Manufacturers (IDMs)
  • Outsourced Semiconductor Assembly and Test (OSAT)

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • Middle East & Africa

Report Preview: https://www.futuremarketinsights.com/reports/die-bonder-equipment-market

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogsYouTube

Variable Air Volume (VAV) System Market to Reach USD 38,247 Million by 2034, Driven by Demand for Energy-Efficient HVAC Solutions

Variable Air Volume System Market

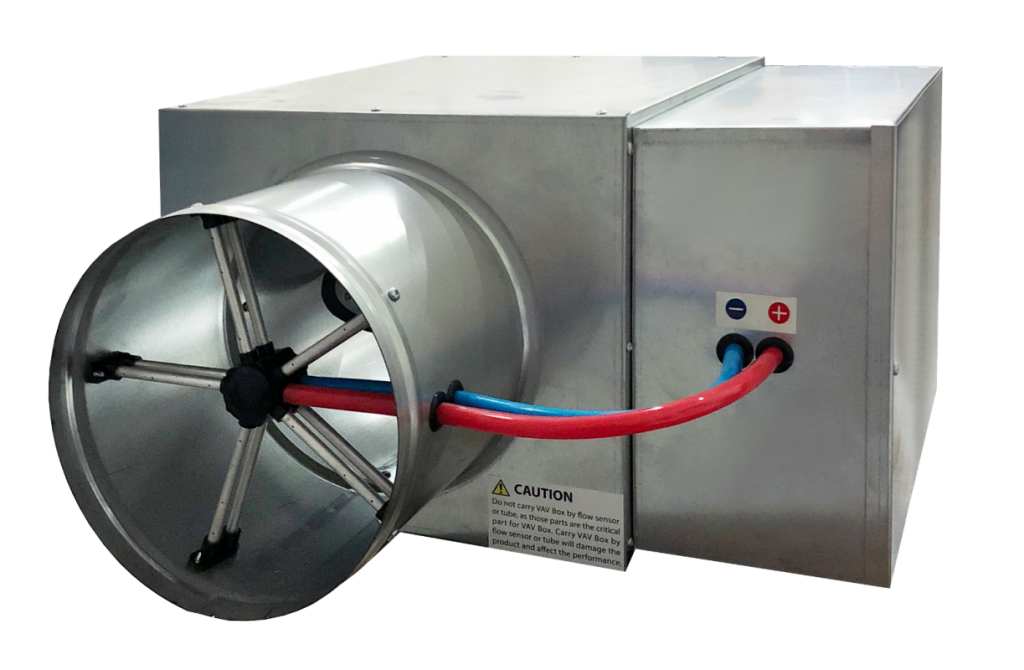
According to Future Market Insights (FMI), the variable air volume (VAV) system market is projected to grow at a CAGR of 10.2%, reaching USD 38,247 million by 2034, driven by the increasing demand for energy-efficient HVAC systems. In 2024, the market is expected to hold a value of USD 14,480 million, propelled by the rising adoption of smart buildings and automation technologies in commercial and residential sectors.

The VAV market is focusing on improving energy efficiency and occupant comfort, with a growing interest in radiant cooling systems. Integrating occupant feedback into system controls helps address thermal comfort issues more effectively. VAV systems also play a crucial role in meeting building ventilation codes through demand-controlled ventilation, adjusting airflow based on real-time occupancy and air quality data. Additionally, advanced technologies like dedicated outdoor air systems are gaining popularity for reducing heating and cooling energy consumption, particularly in buildings with lower cooling demands.

In cooling technologies, indirect evaporative cooling is gaining traction for its energy-saving benefits without increasing indoor humidity, especially in green buildings. The Asia-Pacific region is expected to lead the market due to rising disposable incomes and shifting preferences toward higher living standards. The region’s commercial, residential, and industrial sectors are driving demand for VAV systems because of their compact designs, lower energy consumption, quieter operation, and improved precision.

However, challenges such as high installation and maintenance costs, raw material price fluctuations, a lack of skilled labor, and strict government regulations are obstacles to widespread adoption. Addressing these challenges will be key to continued market growth.

Opportunities in the market are driven by stringent sustainability and energy regulations worldwide, alongside increased investments in infrastructure projects. The demand for single-zone VAV systems, known for their compact design, energy efficiency, and quiet operation, is expected to rise, along with the growing preference for centralized cooling systems in public spaces like auditoriums, hotels, malls, and supermarkets. These trends are anticipated to continue throughout the forecast period.

Key Takeaways from the Variable Air Volume System Market Report:

  • The VAV system industry is anticipated to be worth USD 14,480 Million in 2024.
  • In 2024, the single zone VAV segment is expected to account for around 45.4% share in terms of product.
  • France is projected to showcase a CAGR of 7.1% in the forecast period.
  • Spain is anticipated to register a CAGR of 7.7% over the forecast period.

Competitive Landscape:

The variable air volume (VAV) system market is fiercely competitive, with top manufacturers and new entrants focusing on innovation. These systems are vital for energy-efficient temperature control and air quality management in commercial buildings.

Companies are heavily investing in research and development for advanced VAV systems with IoT integration. Moreover, they are offering custom solutions, forging strategic partnerships, and targeting high-growth regions to drive market growth. Emphasizing compliance with green building standards and providing robust after-sales service further enhances customer satisfaction and contributes to success in the VAV system market.

  • Vemco Inc., based in Pittsburgh, Pennsylvania, is a key supplier of full-scale energy management solutions, encompassing HVAC control systems and building automation technologies.
  • Trane Inc., headquartered in Swords, Ireland, is a well-known global supplier of heating, ventilation, and air conditioning (HVAC) systems and services, delivering sustainable and effective solutions for residential, commercial, and industrial uses.

Leading Players in the Variable Air Volume System Market:

  • Honeywell International Inc.
  • Schneider Electric
  • KMC Controls Inc.
  • Vemco Inc.
  • Trane Inc.
  • Emerson Climate Technologies
  • Johnson Controls

Variable Air Volume System Market Segmentation Analysis:

By Product Type:

  • Single-zone VAV
  • Multiple-zone VAV

By Application:

  • Residential
  • Commercial
  • Industrial

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • Middle East and Africa

Report Preview: https://www.futuremarketinsights.com/reports/variable-air-volume-system-market

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogsYouTube