The Automotive TCU Industry: Driving Connectivity, Performance, and Efficiency in Modern Vehicles | FMI Reports

Automotive TCU Industry

The global automotive TCU industry is set to grow at a CAGR of 5.1% from 2023 to 2033, with an estimated valuation of USD 13.66 billion in 2023. According to Future Market Insights (FMI), the market is expected to exceed USD 22.47 billion by the end of 2033.

The Automotive TCU industry is evolving rapidly as it plays a crucial role in enhancing the performance, fuel efficiency, and driving experience of modern vehicles. TCUs are essential for controlling and optimizing the operation of automatic transmissions, allowing for seamless gear shifts, better power management, and increased vehicle safety. As vehicles become more complex and technologically advanced, the TCU industry is witnessing growth driven by innovation and the need for more efficient powertrain systems.

The automotive market is seeing a shift toward more sophisticated transmission technologies, including dual-clutch systems, continuously variable transmissions (CVTs), and automated manual transmissions. This trend is accompanied by the integration of TCUs with other vehicle electronic systems, such as advanced driver-assistance systems (ADAS) and in-vehicle networking, to enhance the overall driving experience. Additionally, advancements in semiconductor technology and software development are enabling TCUs to manage real-time data and support electric and hybrid vehicles, which are becoming increasingly prevalent.

The rise in demand for electric and hybrid vehicles is driving the need for TCUs capable of managing complex transmission and power management systems. As automakers prioritize fuel efficiency and reduced emissions, TCUs play an essential role in optimizing engine performance and power distribution, contributing to overall vehicle sustainability. Furthermore, the industry’s growth is supported by the continuous push for safer, more reliable, and connected vehicles.

Exhaustive Market Report: A Complete Study

Key Drivers:

  • Advancements in Transmission Technology: The development of advanced transmission systems like CVTs, dual-clutch, and automated manuals has increased the need for more sophisticated TCUs to manage them effectively.
  • Electrification of Vehicles: The shift toward electric and hybrid vehicles requires TCUs that can handle complex power management and operate seamlessly with electric motors and regenerative braking systems.
  • Consumer Demand for Enhanced Driving Experience: The focus on smoother gear transitions, better acceleration, and optimized fuel efficiency has led automakers to invest in advanced TCU technologies.
  • Integration with Advanced Driver-Assistance Systems (ADAS): TCUs are being integrated with ADAS and other vehicle electronic systems to improve overall vehicle performance, safety, and driver comfort.
  • Increased Focus on Fuel Efficiency and Emissions Reduction: TCUs contribute to optimizing engine power and fuel usage, aligning with global efforts to reduce vehicle emissions and improve fuel economy.
  • Emerging Trends in Connectivity and IoT: The rise of connected vehicles that rely on real-time data processing and communication to enhance performance is driving the adoption of smart TCUs capable of supporting these technologies.
  • Regulatory and Safety Standards: Compliance with stringent safety and environmental regulations is prompting manufacturers to develop TCUs that meet new performance and emissions standards.

Key Takeaways:

  • The automotive TCU industry is growing rapidly due to advancements in transmission systems and the rising demand for more efficient and environmentally friendly vehicles.
  • TCUs are becoming integral to modern vehicles as they support enhanced driving experiences, improved fuel economy, and better power management in electric and hybrid vehicles.
  • The integration of TCUs with ADAS and IoT technologies is improving vehicle safety, connectivity, and overall functionality.
  • The focus on fuel efficiency and emissions reduction is prompting the development of TCUs that optimize power usage and contribute to greener automotive practices.
  • Consumer preferences for smoother and more responsive driving have led automakers to prioritize advanced TCU solutions.
  • The industry is being shaped by emerging technologies and the need for seamless data processing to support connectivity and vehicle performance.

Competitive Landscape

Leading corporations including Bosch, Continental, Delphi Automotive, Denso Corporation, General Motors Company, Hitachi Automotive System, Magna International, Magneti Marelli SpA, Mitsubishi Electric Corporation, ZF Friedrichshafen, and others are making high investments in the establishment of research institutes in different regions to come up with improvements in their offerings.

They are adopting business strategies such as sales contracts, strategic alliances, acquiring technical expertise, product approvals, patents and events, joint ventures, partnership agreements, collaborations, digital marketing, mergers and acquisitions, capacity utilisations, technological advancements, etc. to lead the global automotive TCU market with largest market share.

  • In 2020, Samsung Electronics Co. Ltd announced its partnership with BMW to showcase its new approach to enhance its mobility by leveraging its first commercialized 5G TCU. Moreover, in October 2020, BorgWarner completed the acquisition of Delphi Technologies.
  • The acquisition leads to the strengthening of Electronics and Power Electronics Products, Capabilities, and Scale, positions BorgWarner for Greater Growth, and enhances Key Combustion.
  • Customers will globally benefit from the extensive portfolio of BorgWarner and Delphi Technologies OE-quality aftermarket parts, services, diagnostic tools, and test equipment. In addition to this, Magna announced the launch of its new eBeam technology known for its scalability and for giving automakers the ability to electrify their trucks without sacrificing utility and functionality.
  • HARMAN confirmed an agreement with the American Centre for Mobility (ACM) to evaluate real-world use cases of road-ready technology during the MWC Barcelona 2023 in February 2023. This improves visibility, decreases driver anxiety, and boosts safety while allowing the host vehicle to undertake a safe overtake manoeuvre with the help of the HARMAN 5G TCU and HARMAN Savari MECWAVE.

Segmentation of the Global Automotive TCU Market

By Application:

  • AT (Automatic Transmission)
  • CVT (Continuous Variable Transmission)
  • DCT (Dual Clutch Transmission)

By Vehicle Type:

  • Passenger Car
  • LCV (Light Commercial Vehicle)
  • HCV (Heavy Commercial Vehicle)

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East & Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Revolutionizing Tire Safety and Efficiency: Key Drivers and Trends in the Automatic Tire Inflation System Industry | FMI Reports

Automatic Tire Inflation System Industry

The Automatic Tire Inflation System industry is projected to be valued at USD 2,178.1 million in 2023 and is expected to grow to USD 3,755.9 million by 2033. The market is anticipated to expand at a CAGR of 5.6% during the forecast period from 2023 to 2033.

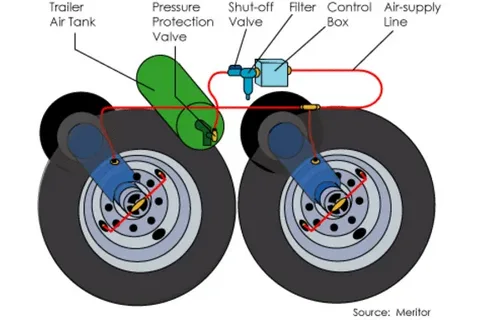
The Automatic Tire Inflation System (ATIS) industry is transforming vehicle safety and performance by ensuring optimal tire pressure in real-time. This technology, which automatically maintains tire pressure within a pre-set range, enhances vehicle safety, improves fuel efficiency, and extends tire lifespan. The ATIS industry is gaining traction as an essential component in both commercial and passenger vehicles due to its potential to reduce maintenance costs, boost fuel economy, and prevent tire-related accidents.

With growing safety regulations, advancements in sensor technology, and increasing awareness of the importance of tire maintenance, the demand for automatic tire inflation systems is expanding. This technology offers substantial benefits, including reducing tire wear, improving fuel efficiency, and enhancing the overall driving experience. The industry is further driven by the push for integrated vehicle technologies and the development of advanced electronic systems that enable real-time monitoring and control.

As the automotive industry evolves, the ATIS market is positioned to grow, fueled by the integration of ATIS with IoT, AI, and telematics. These integrations allow for seamless data collection and analysis, providing valuable insights for fleet management and predictive maintenance. The continued focus on road safety and environmental sustainability is reinforcing the growth of this sector, making ATIS a key innovation in modern vehicle management.

Exhaustive Market Report: A Complete Study

Key Drivers:

  • Safety Regulations and Standards: Increasing emphasis on vehicle safety and regulations that mandate or encourage technologies that reduce tire-related accidents are driving ATIS adoption.
  • Rising Fuel Prices and Efficiency Demands: As fuel prices remain a concern for both consumers and businesses, ATIS systems that optimize tire pressure and improve fuel economy are becoming more attractive.
  • Technological Advancements in Sensors and IoT: Innovations in sensors, wireless communication, and IoT are enabling more efficient and reliable automatic tire inflation systems.
  • Awareness of Tire Maintenance Benefits: Growing awareness about the impact of tire pressure on vehicle performance, safety, and fuel efficiency is boosting the adoption of ATIS.
  • Fleet Management and Logistics Needs: The commercial sector’s increasing demand for effective fleet management and operational cost reduction is driving the adoption of ATIS to prevent downtime and reduce tire maintenance costs.
  • Integration with Advanced Vehicle Systems: The synergy between ATIS and modern vehicle telematics, AI, and data analytics allows for more sophisticated monitoring and predictive maintenance capabilities.
  • Environmental and Cost-Saving Concerns: The emphasis on reducing carbon emissions and improving fuel efficiency to lower overall operating costs is influencing vehicle manufacturers and operators to implement ATIS.

Key Takeaways:

  • The Automatic Tire Inflation System industry is poised for growth as safety regulations, fuel efficiency requirements, and advancements in vehicle technologies continue to drive its adoption.
  • ATIS enhances vehicle safety by maintaining optimal tire pressure, which in turn reduces the risk of blowouts and tire-related accidents, contributing to road safety.
  • The integration of IoT and sensor technologies is facilitating real-time monitoring, enabling vehicle operators to maintain tire performance and predict maintenance needs.
  • The commercial vehicle sector, driven by fleet management and logistics needs, represents a significant market segment for ATIS, as it helps reduce tire maintenance costs and improve fuel economy.
  • Consumer awareness of tire maintenance and fuel efficiency is pushing the demand for ATIS systems, encouraging automakers to adopt and integrate this technology into new vehicle models.
  • The continued focus on environmental sustainability and cost savings is reinforcing the importance of ATIS in reducing fuel consumption and operational expenses.

Competitive Landscape

The key strategies chosen by large companies include several growth strategies such as technology development, expansion as well and mergers and acquisitions to surge market share, reach and revenue.Dana Incorporated; Meritor, Inc.; EnPro Industries, Inc.; Nexter Group; Servitech Industries, Inc.; Hendrickson USA, LLC; Tire Pressure Control International Ltd.; PTG Reifendruckregelsysteme GmbH; Aperia Technologies, Inc.; Systems GmbH; Bigfoot Equipment Ltd.; Tibus Offload Ltd. & Co. KG; AIR CTI; FTL Technology Limited; Col-Ven S.A.

  • In 2023, BFGoodrich Tires introduced the BFGoodrich® ActivAir, a fully integrated tire inflation system designed to enhance off road capabilities. The system enables drivers to adjust tire pressure without leaving their seats, offering convenience and flexibility in various off road situations.
  • In 2023, Danfoss Editron partnered with Meritor Inc. and Electra Commercial Vehicles to widen its product portfolio and offer a complete ATIS solution for electric commercial vehicles.
  • In 2022, EnPro Industries acquired Bridgestone Commercial Solutions, a leading provider of ATIS for commercial vehicles. The acquisition expands the product portfolio of the company and strengthens its position in the ATIS market.
  • In 2021, John Deere launched its 8R series tractor with a home built ATIS system integrated as an option.

Key Segmentation for the Automatic Tire Inflation System Industry

The Automatic Tire Inflation System (ATIS) industry can be segmented based on various factors that reflect the different aspects of the market and its applications. Understanding these segments helps businesses, investors, and stakeholders to navigate and target their strategies effectively. Below are the main segments that define the ATIS industry:

1. By Vehicle Type

  • Passenger Vehicles: Includes cars and SUVs, where ATIS can help in maintaining optimal tire pressure for better fuel efficiency, safety, and tire lifespan.
  • Commercial Vehicles: Such as trucks, buses, and vans, where maintaining tire pressure is critical for safety, fuel economy, and overall vehicle performance.
  • Off-Road Vehicles: Used in mining, construction, and agriculture, where tire performance is essential for demanding terrains and heavy-duty applications.
  • Electric Vehicles (EVs): A growing segment, as the need for efficient tire management aligns with the broader push for sustainable and energy-efficient solutions.

2. By Technology

  • Central Tire Inflation Systems (CTIS): Systems that allow for real-time inflation and deflation of tires to adjust to different road and weather conditions.
  • Automatic Tire Pressure Monitoring Systems (TPMS): Systems that provide real-time tire pressure data and may include automatic inflation features to maintain optimal pressure.
  • Direct Inflation Systems: Use sensors and automatic valves to ensure tires remain properly inflated without manual intervention.
  • Indirect Inflation Systems: Use a combination of wheel sensors and vehicle data to estimate tire pressure, triggering alerts for inflation when necessary.

3. By Component

  • Compressor Units: Essential for generating the air pressure needed to inflate tires.
  • Control Units: The electronic system that monitors and adjusts tire pressure in real-time.
  • Sensors and Valves: Used to measure tire pressure and control air flow to maintain proper inflation levels.
  • Pneumatic Lines and Connectors: Infrastructure that links various components to create a functioning inflation system.

4. By End-Use Application

  • Transportation and Logistics: ATIS play a significant role in ensuring the safety and efficiency of commercial transport vehicles, reducing fuel consumption and tire wear.
  • Mining and Construction: Vital in maintaining tire performance under harsh conditions, which helps reduce downtime and maintenance costs.
  • Agriculture: Used in tractors, harvesters, and other farming equipment where consistent tire pressure helps with traction and efficiency.
  • Military and Defense: Where tire integrity is crucial for vehicle performance in varied terrains and mission-critical operations.

5. By Sales Channel

  • OEM (Original Equipment Manufacturer): ATIS integrated into vehicles during manufacturing.
  • Aftermarket: Systems sold as upgrades or retrofits to existing vehicles, catering to consumers looking for enhanced vehicle performance and safety.

6. By Region

  • North America: Driven by the demand for commercial vehicles and regulatory requirements for safety and fuel efficiency.
  • Europe: Known for stringent environmental and safety regulations, boosting demand for advanced tire management systems.
  • Asia-Pacific: The largest market due to the significant production and adoption of commercial and passenger vehicles, coupled with rapid urbanization.
  • Middle East and Africa: Growing demand for commercial and off-road vehicles in infrastructure and mining projects.
  • Latin America: Emerging markets with increasing transportation and infrastructure needs.

7. By Type of Inflation

  • Single-Point Inflation: Inflates all tires simultaneously at a set pressure.
  • Individual Tire Inflation: Allows for individual tire pressure adjustment, providing greater control over tire health and fuel economy.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Boosting Cycling Performance: Key Drivers and Trends in the Bicycle Components Aftermarket | FMI Reports

Bicycle Components Aftermarket

The bicycle components aftermarket was valued at USD 14 billion in 2022 and is estimated to reach USD 14.62 billion in 2023. The growing popularity of cycling, driven by high traffic congestion and safety concerns for riders, has led to an increased demand for bicycle accessories. According to FMI analysis, the market is expected to grow at a CAGR of 6.9% from 2023 to 2033, reaching approximately USD 28.3 billion by 2033.

The bicycle components aftermarket industry is a dynamic and essential segment within the cycling market, offering cyclists a wide range of options to enhance the performance, comfort, and customization of their bikes. With growing interest in cycling for fitness, leisure, and commuting, the demand for high-quality, specialized bicycle components has surged. The aftermarket sector plays a pivotal role in supporting cyclists’ needs by providing upgrade options, replacement parts, and custom solutions that cater to diverse riding styles and preferences.

This industry encompasses a variety of components, including wheels, pedals, handlebars, gear sets, brakes, frames, and other parts designed to improve the functionality and aesthetics of bicycles. The rise in cycling’s popularity, driven by health and eco-conscious trends, urban mobility solutions, and competitive sports, has fueled the growth of the bicycle components aftermarket. Additionally, the growth of e-bikes has introduced new opportunities, as specialized parts for electric-assisted bicycles require tailored solutions that support enhanced power systems and performance.

The aftermarket is characterized by a mix of premium and budget-friendly options, catering to professional cyclists, casual riders, and commuting enthusiasts. Online retail platforms, specialized bike shops, and direct-to-consumer sales have further facilitated access to bicycle components, expanding market reach and customer base. As innovation in cycling technology continues, the aftermarket is expected to grow, supported by trends such as 3D printing, lightweight materials, and improved ergonomic designs.

Exhaustive Market Report: A Complete Study

Key Drivers:

  • Growing Popularity of Cycling: An increase in cycling for fitness, recreation, and transportation has fueled the demand for bicycle components that enhance performance and comfort.
  • Rising Interest in E-bikes: The growing market for e-bikes has created a demand for specialized aftermarket components that accommodate electric power systems and related technologies.
  • Customization and Personalization Trends: Cyclists’ desire to customize and personalize their bikes has led to increased demand for diverse and high-quality aftermarket components.
  • Advancements in Cycling Technology: Innovations in materials, design, and manufacturing, such as 3D printing and carbon fiber, have improved the functionality and performance of bicycle components.
  • Urban Mobility Solutions: The shift toward sustainable transportation has led to more people incorporating bicycles into their daily commute, boosting the need for durable and reliable components.
  • Online Retail and E-commerce Growth: The expansion of online platforms and direct-to-consumer sales channels has made it easier for cyclists to access a wide variety of bicycle parts, enhancing market growth.
  • Competitive Cycling and Sports: The increasing popularity of competitive cycling and sports has driven demand for high-performance components designed for professional and semi-professional athletes.

Key Takeaways:

  • The bicycle components aftermarket industry is expanding as more consumers take up cycling for fitness, commuting, and recreation, creating demand for quality and customizable parts.
  • E-bikes represent a significant and growing market, necessitating specialized parts that support the unique demands of electric-assisted cycling.
  • Advances in technology and materials, including lightweight alloys, carbon fiber, and 3D-printed components, are driving product innovation and performance improvements.
  • Cyclists’ preference for personalization and upgrades has increased the importance of aftermarket solutions, from entry-level parts to high-end, performance-focused components.
  • The rise of urban cycling and environmentally conscious transportation has contributed to higher demand for durable and efficient bicycle parts.
  • Online and e-commerce channels have democratized access to bicycle components, making it easier for consumers to find and purchase parts tailored to their needs.
  • Competitive sports, from amateur races to professional events, continue to push the boundaries of performance and precision, driving demand for premium bicycle components.

Competitive Landscape

Some of the prominent players profiled in the global market are:

  • Dorel Industries Inc
  • Accell Group N.V.
  • Shimano Inc.
  • SRAM LLC
  • Hero Cycles Limited
  • Campagnolo S.R.L.
  • Merida Industry Co. Ltd.
  • Specialized Bicycle Components
  • Rohloff AG
  • Giant Manufacturing Co. Ltd.
  • Avon Cycles Ltd.

Some of the important developments of the key players in the market are:

  • In January 2023, Hero Cycles, a leading cycle manufacturer in India, announced it might enter the electric vehicle (EV) market with a significant investment of 1,500 crore rupees ( USD 206 million).
  • In November 2022, Shimano lifted the veil on a host of new e-bike products and technologies, from an entirely new drive unit to e-specific drivetrains and-in collaboration with Blubrake-antilock braking.

Key Segments Covered in the Bicycle Components Aftermarket Industry Analysis

By Component Type:

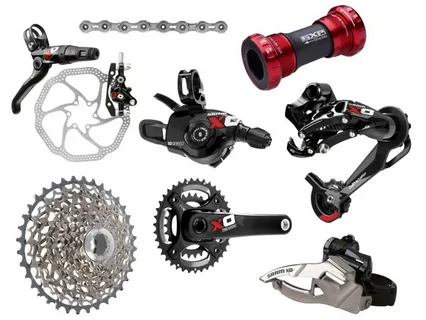
  • Derailleurs
  • Road Groupsets
  • Suspensions
  • Wheel Sets
  • Brakes
    • Hydraulic
    • Mechanical
  • Caliper Type
  • Gears
  • Others (Bottom Brackets etc.)

By Sales Channel:

  • Specialty Bicycle Retailers
  • Discount Stores
  • Department Stores
  • Full-line Sporting Goods Stores
  • Outdoor Specialty Stores
  • Other Sales Channel

By Bicycle Type:

  • Mountain Bike
  • Hybrid/Cross
  • Road
  • Comfort
  • Youth
  • Cruiser
  • Recumbent/Tandem
  • Electric
  • Folding

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia Pacific
  • The Middle East & Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Powering the Future: Key Insights and Drivers of Growth in the Electric Vehicle Battery Industry | FMI Reports

Electric Vehicle Battery Industry

The global electric vehicle battery industry is expected to grow at a robust CAGR of 8.5%, with projected revenues reaching USD 21,258.4 million by 2033. The market is currently valued at USD 9,402.3 million in 2023.

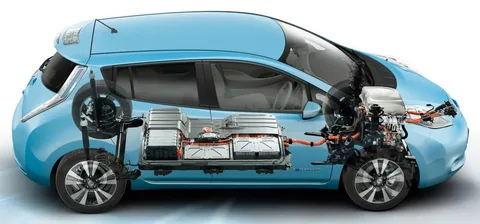
The Electric Vehicle (EV) Battery Industry is at the forefront of the transition to a cleaner, more sustainable future in transportation. As the global automotive sector shifts toward electric mobility, the demand for high-capacity, efficient, and durable EV batteries continues to surge. These batteries are not just essential for powering electric vehicles; they are pivotal in reducing carbon emissions, enhancing energy storage capabilities, and enabling the widespread adoption of renewable energy sources.

EV batteries, primarily lithium-ion, have seen significant advancements in energy density, charging speed, lifespan, and safety, thanks to continuous research and technological innovation. Additionally, the market is experiencing a diversification of battery chemistries, such as solid-state batteries, which promise even higher efficiency and safety standards. This evolution is not only driven by consumer expectations for better performance and longer ranges but also by regulatory pressures and environmental commitments aimed at curbing greenhouse gas emissions.

With global governments offering incentives and support for EV adoption, the EV battery industry is set for substantial growth. This growth is accompanied by a need for an efficient supply chain and strategic partnerships that ensure the steady availability of raw materials such as lithium, cobalt, and nickel. The industry is also seeing a rise in secondary markets for battery recycling and second-life applications, further promoting sustainability and reducing environmental impact.

Exhaustive Market Report: A Complete Study

Key Drivers:

  • Growing EV Market: The rapid adoption of electric vehicles worldwide is the primary driver behind the demand for advanced EV battery technologies.
  • Technological Advancements: Innovations in battery chemistries, such as solid-state and lithium-sulfur, are enhancing energy density, safety, and efficiency.
  • Environmental Regulations and Policies: Stricter emissions standards and policies supporting green initiatives are pushing manufacturers to prioritize electric vehicle development and the development of efficient batteries.
  • Consumer Demand for Longer Ranges and Faster Charging: The need for greater range, faster charging times, and improved battery life is leading to continuous improvements in battery technology.
  • Incentives and Government Support: Tax credits, subsidies, and incentives for both manufacturers and consumers are fueling growth in the EV and EV battery market.
  • Sustainability and Recycling Initiatives: The rise in battery recycling and second-life battery applications is promoting a more sustainable approach to EV battery production and disposal.
  • Raw Material Supply Chain Challenges: The increasing demand for materials like lithium, cobalt, and nickel is influencing investments in mining, material sourcing, and recycling technology to secure supply chains.

Key Takeaways:

  • The EV battery industry is on an upward trajectory as electric vehicle adoption accelerates, driven by advancements in battery technology and a growing push for sustainability.
  • Innovations in battery chemistries and the development of new technologies such as solid-state batteries are set to redefine performance standards, making EVs more efficient and safer.
  • Government incentives and regulations play a crucial role in boosting the EV and battery markets, aligning with global efforts to reduce carbon emissions.
  • Consumer preferences for longer driving ranges and faster charging capabilities are pushing manufacturers to focus on improved battery performance and lifecycle.
  • The industry must navigate challenges related to raw material sourcing and the environmental impact of battery production, highlighting the importance of recycling and sustainable practices.
  • Secondary markets for battery reuse and recycling are emerging as vital components of a circular economy, ensuring reduced waste and resource conservation.

Key Market Players

  • Automotive Energy Supply Corporation
  • Panasonic Corporation
  • BYD Company Limited
  • GS Yuasa Corporation
  • LG Chem Ltd.
  • Samsung SDI Co., Ltd
  • Tesla Motors, Inc.
  • Hitachi Chemical Company, Ltd.
  • Narada Power Source Co. Ltd.
  • Johnson Controls International Plc.
  • Tianneng Power International Co., Ltd.
  • Crown Battery Corporation
  • Furukawa Electric Co., Ltd.
  • EnerSys
  • Wanxiang Group Corporation
  • East Penn Manufacturing Co.
  • Toshiba Corporation
  • Leoch International Technology Ltd.

Key Segmentations

By Battery Capacity:

  • Less than 20 kWh
  • 21 to 40 kWh
  • More than 41 kWh

By Vehicle Technology:

  • HEV
  • PHEV
  • BEV

By Vehicle Type:

  • Passenger Cars
  • Light Commercial Vehicles
  • Heavy Commercial Vehicles
  • Others

By Battery Type:

  • Lithium Ion
  • Lead Acid
  • Nickel Hydride
  • Others

By Region:

  • North America
  • Latin America
  • Asia Pacific
  • The Middle East and Africa
  • Europe

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Revolutionizing Vehicle Care: Key Trends and Drivers in the Automotive Garage Equipment Industry | FMI Reports

Automotive Garage Equipment Industry

The automotive garage equipment industry was valued at USD 24.4 billion in 2022 and is expected to reach USD 26.8 billion in 2023. The demand for automotive garage equipment is being driven by the growth of repair shops and independent garages, which are contributing to increased vehicle sales in emerging economies.

The Automotive Garage Equipment industry is at the heart of the automotive service sector, providing essential tools and machinery that support vehicle repair, maintenance, and customization. From basic mechanical repairs to advanced diagnostics and electric vehicle (EV) servicing, this industry is evolving rapidly in response to technological advancements and changing market demands. As vehicles become increasingly sophisticated, the demand for advanced garage equipment tailored for modern automotive needs is growing.

Garage equipment includes everything from vehicle lifts, tire changers, and wheel aligners to diagnostic machines, AC servicing units, and specialized tools for electric and hybrid vehicle maintenance. The global emphasis on sustainability, safety, and efficiency has led to the development of eco-friendly and energy-efficient equipment, positioning the industry for sustainable growth. The integration of AI, IoT, and automation into garage equipment is also enhancing service capabilities, making workshops more productive and service offerings more comprehensive.

With the increasing adoption of EVs, the industry is experiencing a shift toward specialized equipment that can handle high-voltage components and battery management systems. This trend is driving equipment manufacturers to innovate and create solutions that support a diverse range of vehicle types and repair needs, ensuring that automotive workshops remain well-equipped to meet future challenges.

Exhaustive Market Report: A Complete Study

Key Drivers:

  • Technological Advancements in Vehicles: The increasing complexity of modern vehicles, including EVs and hybrids, has driven demand for advanced garage equipment capable of servicing sophisticated electrical and mechanical systems.
  • Growing Vehicle Fleet: A steady rise in the number of vehicles on the road globally has heightened the need for efficient, high-quality garage equipment to manage repairs and maintenance.
  • Shift Toward Electric Vehicles (EVs): The rapid adoption of electric vehicles is influencing the development of specialized equipment for EV battery maintenance, diagnostics, and high-voltage safety.
  • Focus on Safety and Regulatory Compliance: Stricter safety and environmental regulations are prompting workshops to invest in updated, certified, and compliant equipment that meets new industry standards.
  • Consumer Demand for Faster Service: The need for quick and efficient vehicle servicing has spurred the development of automated and advanced diagnostic tools that minimize repair times and increase workshop productivity.
  • Integration of Smart Technology: The adoption of IoT-enabled equipment and AI-powered diagnostics is revolutionizing automotive garages, allowing for predictive maintenance and better service management.
  • Sustainability Trends: The move toward eco-friendly and energy-efficient equipment is growing, driven by environmental regulations and the push for greener automotive practices.

Key Takeaways:

  • The automotive garage equipment industry is expanding, driven by advances in vehicle technologies and the rising demand for efficient, safe, and eco-friendly service tools.
  • The emergence of electric and hybrid vehicles is reshaping the market, with specialized equipment needed for battery management and electrical component servicing.
  • Consumer expectations for faster service and advanced diagnostics are prompting the development of automated and smart garage solutions.
  • Workshops are investing in equipment that meets stringent safety and environmental standards to comply with regulations and align with sustainability goals.
  • The integration of IoT, AI, and automation in garage equipment is enhancing the efficiency and productivity of workshops, paving the way for a new era of vehicle care.

Competition Landscape

Some of the prominent players in the global market are-

  • MAHA Maschinenbau Haldenwang Gmbh & Co. KG
  • Snap-on Incorporated
  • Robert Bosch GmbH
  • Continental AG
  • Forward Lift Company (Dover Corporation)
  • VisiCon Automatisierungstechnik GmbH
  • Standard Tools and Equipment Co.
  • Symach Srl
  • Nussbaum Automotive Solutions
  • SAMVIT GARAGE EQUIPMENT
  • Sarveshwari Engineers
  • PULI Industries (Guangzhou Jingjia Auto Equipment Co., Ltd.)
  • Boston Garage Equipment Ltd.
  • Arex Test Systems B.V.
  • LKQ Coatings Ltd.
  • Aro Equipments Pvt. Ltd
  • Istobal S.A.
  • Con Air Equipment Private Limited
  • Oil Lube Systems Pvt Ltd.
  • Gray Manufacturing Company, Inc.

Important Developments of the Key Players in the Market

  • In August 2021, Forward Lift, a part of Dover Corporation and Vehicle Service Group, launched a new line of frame-engaging adapter kits for the company’s mobile column lifts. These attachments allow technicians to easily lift and service a wide range of forklifts to reach pallet trucks and heavy vehicles.
  • In April 2023, ISTOBAL USA revealed some exciting news at The Car Wash Show, Las Vegas, NV (Booth #1155. The company is going to showcase multiple new products and options specially developed for the United States market. The new solutions respond to a demand from United States customers for innovation, efficiency, and profitability.

Automotive Garage Equipment Market Segmentation

By Vehicle:

  • 2 Wheelers
  • Light Vehicles
  • Heavy Vehicles

By Equipment:

  • Lifting Equipment
  • Body Shop Equipment
  • Wheel & Tire Alignment
  • Vehicle Diagnostics & Testing
  • Washing Equipment
  • Other Tools

By Garage:

  • OEM
  • Franchisee Garages
  • Independent Garages

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • The Middle East & Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Driving Growth: Key Trends and Drivers in the Automotive Repair & Maintenance Services Industry | FMI Reports

Automotive Repair & Maintenance Services Industry

The global automotive repair and maintenance services industry is anticipated to be valued at USD 915.88 billion in 2023 and is projected to grow to USD 1,850 billion by 2033, achieving a CAGR of 7.2%.

The Automotive Repair & Maintenance Services industry is a cornerstone of the global automotive sector, playing a vital role in ensuring vehicle safety, reliability, and performance. With the increase in vehicle ownership and technological advancements, the demand for professional repair and maintenance services is expanding rapidly. This industry encompasses a range of services including routine maintenance, diagnostics, collision repair, engine overhauls, and tire and brake services.

As vehicles become more complex with the integration of advanced technologies, the need for specialized service providers equipped with state-of-the-art tools and skilled technicians has grown. Furthermore, the rise of electric vehicles (EVs) and hybrid models has introduced new challenges and opportunities within the market, requiring a shift in service approaches and technician expertise. Additionally, trends toward vehicle customization, digital service platforms, and eco-friendly repair practices are driving innovation and consumer expectations.

In an era of evolving consumer needs and stringent regulations, the Automotive Repair & Maintenance Services industry is poised for continuous growth, with a heightened focus on service quality, customer convenience, and sustainability.

Exhaustive Market Report: A Complete Study

Key Drivers:

  • Growing Vehicle Fleet and Aging Cars: The increasing number of vehicles on the road and the trend toward longer vehicle lifespans are driving demand for repair and maintenance services.
  • Advancements in Vehicle Technology: Modern vehicles are equipped with sophisticated systems such as ADAS, EV powertrains, and advanced electronics, which require specialized training and diagnostic tools for proper servicing.
  • Rise of Electric and Hybrid Vehicles: The growing adoption of EVs and hybrid vehicles is shifting the focus of repair services, leading to the need for technicians skilled in high-voltage systems and specialized EV components.
  • Emphasis on Safety and Regulatory Compliance: Heightened safety standards and environmental regulations are driving vehicle owners to seek professional repair services to ensure compliance and maintain vehicle integrity.
  • Increased Consumer Expectations for Convenience: The demand for faster, more convenient services has led to the growth of mobile repair units and digital service platforms that provide online booking and remote diagnostics.
  • Sustainability and Eco-Friendly Practices: There is a push for greener repair solutions, including the use of eco-friendly parts, sustainable materials, and recycling practices that align with global environmental initiatives.

Key Takeaways:

  • The automotive repair and maintenance services market is expanding as vehicle ownership rises and the complexity of vehicles increases, requiring specialized services.
  • The integration of advanced technologies in vehicles, including EVs and connected car systems, is reshaping service approaches and the skill sets needed for repair professionals.
  • Consumer expectations are shifting toward more convenient, tech-enabled services, prompting the growth of mobile repair services and digital platforms for booking and diagnostics.
  • Compliance with stringent safety regulations and a focus on sustainable practices are shaping the service offerings in the industry.
  • The growth in EVs presents both challenges and opportunities, driving demand for specialized training and tools to meet the needs of electric and hybrid vehicle owners.

Competitive Landscape

The automotive repair & maintenance services market is highly competitive, with several key industry players investing heavily in the production of these services. The key industry players are Arnold Clark Automobile Ltd., Asbury Automotive Group Inc., Ashland Automotive Group Inc., Belron International Ltd, Driven Brands Inc., Carmax Autocare Center, Firestone Complete Autocare, Goodyear Tire & Rubber Company, Halfords Group PLC, Monro Inc.

Some recent developments in the market are:

Key industry players are utilizing organic growth strategies like acquisitions, mergers, tie-ups, and collaboration to bolster their product portfolio. This is expected to propel the global automotive repair & maintenance services market.

  • In March 2021, Monro Inc. entered into a definitive agreement to acquire Mountain View Tire & Service, Inc. The acquisition not only strengthens Monro, Inc.’s foothold in the western region but also expands its overall presence to a total of 116 stores, further positioning the company in an attractive market.
  • On November 4, 2022, Belron International Ltd. confirmed its submission of a Commitment Letter to the Science Based Targets initiative (SBTi). This letter signifies their determination to establish science-based emissions reduction targets, aligning with the objectives of the Paris Agreement
  • In October 2019, Driven Brands Inc., a United States automobile aftermarket company, completed the acquisition of ABRA Automotive Systems LP.
  • In July 2022, FullSpeed Automotive® announced its accelerated growth plans through acquisitions to reach its goal of expanding to 1,000 units by the end of 2023. As a leading franchisor and operator of automotive aftermarket repair facilities, FullSpeed Automotive® is known for its flagship brands Grease Monkey® and SpeeDee Oil Change & Auto Service®.

Key Segments Profiled in the Automotive Repair & Maintenance Services Industry Survey

By Services & Parts

  • Engine Oil
  • Gear Oil
  • Brake Oil
  • Grease
  • Tires
  • Batteries
  • Wear & Tear Parts
  • Air Filter
  • Cabin Filter
  • Oil Filter
  • Wiper Blades
  • Others

By Service Providers

  • Automobile Dealerships
  • Franchise General Repairs
  • Specialty Shops
  • Locally Owned Repair Shops
  • Tire Shops
  • Others

By Vehicle Type

  • Passenger Cars
  • LCV
  • HCV

By Region

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • Middle East & Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Powering Progress: Key Insights and Drivers of Growth in the Automotive Wires Industry | FMI Reports

Automotive Wires Industry

The global automotive wires industry was valued at USD 4,823.2 million in 2022 and is projected to grow to USD 4,937 million in 2023. This growth is driven by increased demand in the global automotive market, fueled by rising vehicle sales, including both passenger and commercial vehicles. According to reports from Future Market Insights, the automotive wires market is expected to expand at a CAGR of 6.03% from 2023 to 2033, reaching approximately USD 8,868.7 million by 2033.

The Automotive Wires industry is a crucial component of the global automotive sector, enabling the seamless functioning of electrical systems within vehicles. With the rapid advancement in vehicle technologies and the surge in electric vehicle (EV) adoption, the demand for high-quality, efficient, and durable automotive wiring solutions has seen significant growth. Automotive wires are essential for connecting electronic systems, sensors, infotainment units, safety features, and power systems, making them indispensable for modern vehicles’ functionality and performance.

The industry is currently experiencing transformative changes driven by the need for increased vehicle electrification, lightweight materials, and improved safety standards. Technological innovations, such as high-performance cables and the integration of advanced insulation materials, are meeting the stringent requirements for energy efficiency, durability, and heat resistance. Additionally, industry players are focusing on sustainability by implementing eco-friendly practices and developing recyclable materials that comply with global environmental standards.

As the automotive landscape continues to evolve, the market for automotive wires is poised for sustained expansion, with advancements in autonomous vehicles and connected car technologies further fueling demand.

Exhaustive Market Report: A Complete Study

Key Drivers:

  • Rise of Electric Vehicles (EVs): The growth of the electric vehicle market is driving significant demand for specialized wiring solutions that can handle higher power requirements and increased electrical systems.
  • Advancements in Vehicle Technologies: Modern cars are equipped with sophisticated electronic components, including advanced driver-assistance systems (ADAS), infotainment, and electric powertrains, all of which require reliable wiring solutions.
  • Increased Focus on Lightweight Materials: To improve vehicle efficiency and fuel economy, manufacturers are adopting lightweight wiring solutions that maintain strength and performance.
  • Regulatory and Safety Standards: Stricter safety regulations are compelling automotive manufacturers to use high-quality, flame-retardant, and heat-resistant wires to meet compliance and safety benchmarks.
  • Technological Integration in Automotive Design: The rise of connected cars, autonomous vehicles, and IoT-enabled solutions are driving the need for more complex wiring systems that can support high data transmission and power distribution.
  • Sustainability Initiatives: The push for eco-friendly production processes and recyclable materials is reshaping the industry, aligning with global efforts toward reducing the environmental impact of automotive manufacturing.

Key Takeaways:

  • The demand for automotive wiring solutions is expected to continue growing as electric vehicles and advanced vehicle technologies become mainstream.
  • Innovations in lightweight, high-performance materials and advanced insulation are enhancing the efficiency, durability, and safety of automotive wiring.
  • The industry is responding to consumer preferences and environmental pressures with a focus on sustainable practices and eco-friendly solutions.
  • Key factors such as regulatory compliance, safety standards, and technological advancements are shaping the direction of the automotive wires market.
  • The integration of advanced wiring systems into autonomous and connected vehicles will play a significant role in the future of the automotive industry.

Competition Landscape

Some of the prominent players in the global market are:

  • LEONI AG
  • Sumitomo Electric Industries, Ltd.
  • Fujikura Ltd.
  • Delphi Automotive Plc.
  • PKC Group
  • Furukawa Electric Co., Ltd
  • Yazaki Corporation
  • General Cable
  • Lear Corporation
  • Draka (Subsidiary of Prysmian Group)
  • Samvardhana Motherson Group
  • Allied Wire & Cable, Inc.
  • Coroplast Fritz Müller GmbH & Co. KG.
  • Kromberg & Schubert
  • Acome
  • Yura Corporation
  • Kyungshin Corporation

Some of the important developments of the key players in the market are:

  • In May 2023, Rabat – Lear Corporation, an American automotive seating and electrical systems manufacturer, announced its plans for converting its Tangier plant into a Connection Systems facility. Movement of such is expected to generate around 150 new job opportunities while further focusing on Lear’s manufacturing footprint in Morocco.
  • In January 2023, Mouser Electronics, Inc., the authorized global distributor of the newest semiconductors and electronic components, announced a new distribution agreement with Yazaki North America, i.e., considered as a leading manufacturer of connectors, wire harnesses, meters, and many other products that are of high-quality were used for automotive purposes.

Key Segments Covered in Automotive Wires Market

By Material Type:

  • Copper
    • Oxygenic Copper
    • Pure Copper (Oxygen Free)
    • Copper Silver (CuAg)
    • Copper Magnesium (CuMg)
    • Copper Tin (CuSn)
  • Aluminum
  • Others (Nickel, etc.)

By Vehicle Type:

  • Conventional Fuel Vehicles
    • Passenger Vehicle
    • Commercial Vehicle
  • Electric Vehicles
  • Hybrid Vehicles

By Application:

  • Chassis and Safety
    • Conventional Chassis
    • Semi-forward Chassis
    • Full-forward Chassis
  • Body
    • Facia
    • Roof
    • Door & Window
    • Seat
    • Interior
  • Heating Ventilation & Air-Conditioning (HVAC)
    • Engine
    • Sensors

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • Middle East & Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Enhancing Asset Longevity: Key Trends and Drivers in the Surface Protection Service Industry | FMI Reports

Surface Protection Service Industry

The surface protection service industry is projected to reach USD 13,933.50 million in 2024, driven by increased demand for safeguarding surfaces from damage, wear, and deterioration.

The market is expected to grow at a CAGR of 5.10% from 2024 to 2034. One major factor fueling this growth is the rising awareness among industries and consumers about the importance of maintaining the integrity and durability of surfaces, particularly in high-traffic areas or environments that face harsh conditions.

By 2034, the surface protection service market is anticipated to exceed USD 21,063 million. The growing emphasis on sustainability across various industries is also contributing to this expansion, as there is a higher demand for eco-friendly surface protection solutions. These solutions prioritize minimizing environmental impact, utilizing biodegradable materials, reducing energy usage during application, and ensuring responsible disposal practices.

The Surface Protection Service industry plays an essential role in ensuring the durability and lifespan of various assets across sectors, from construction to manufacturing and consumer goods. This industry has seen significant growth driven by increasing demand for high-quality maintenance and protection solutions that reduce wear and tear, improve aesthetics, and enhance overall product performance. With advancements in technology and a growing emphasis on sustainable practices, businesses are increasingly turning to specialized surface protection services to maintain competitive advantage and meet regulatory standards.

The industry encompasses a range of services such as coating applications, anti-corrosion treatments, scratch protection films, and custom shielding solutions tailored to the unique requirements of different industries. The integration of smart technology and automated systems has further revolutionized the approach to surface protection, offering more efficient and cost-effective solutions. In response to rising environmental concerns, eco-friendly coatings and biodegradable protection options are becoming more prevalent, aligning with global sustainability goals.

Exhaustive Market Report: A Complete Study

Key Drivers:

  • Rising Industrial Demand for Asset Longevity: Industries focused on maintaining high-value assets such as automotive, aerospace, and construction require consistent surface protection to maximize their lifespan and operational efficiency.
  • Advancements in Technology: The adoption of innovative materials and automated application systems has enhanced the effectiveness of surface protection services, driving greater uptake.
  • Sustainability and Environmental Regulations: Increasing awareness of environmental impact has spurred demand for eco-friendly protective solutions, leading to a shift toward sustainable practices within the industry.
  • Consumer Preferences for Quality and Durability: The demand for high-quality products with long-lasting finishes has propelled businesses to seek superior surface protection solutions.
  • Economic Growth and Infrastructure Development: Expanding construction and manufacturing projects worldwide are fueling the need for surface protection services to safeguard equipment and structures.
  • Technological Integration: The use of advanced coatings and smart surface protection technologies like IoT-enabled sensors is providing real-time monitoring and predictive maintenance capabilities.

Key Takeaways:

  • The Surface Protection Service industry is poised for continued growth as more sectors prioritize the protection of assets to reduce maintenance costs and extend service life.
  • Advanced materials and automated solutions are enhancing service efficiency, which is expected to create a competitive edge for service providers.
  • Eco-friendly and sustainable surface protection options are on the rise due to heightened environmental consciousness and regulatory pressures.
  • Industries such as automotive, aerospace, and construction are major contributors to the demand for specialized surface protection services.
  • Future innovations are likely to involve smart coatings and real-time data analytics, providing unprecedented insight into asset condition and prevention of damage.

Competition Outlook of the Surface Protection Service Industry

Companies are relentlessly innovating, formulating next-generation coatings boasting superior performance, enhanced durability, and eco-friendliness. Nanotechnology, self-healing properties, and specialized functionalities are paving the way for transformative solutions.

Environmental consciousness is driving a shift towards sustainable practices. Companies are prioritizing the development of eco-friendly formulations, minimizing waste generation, and exploring circular economy solutions to reduce their environmental footprint and cater to environmentally responsible clients.

Industry leaders are consolidating their strengths through strategic mergers and acquisitions, expanding their service portfolios and geographical reach. Recognizing the power of collaboration, companies are forging strategic partnerships with research institutions, startups, and even competitors to tackle complex projects and develop groundbreaking solutions.

Companies are strategically focusing on specialized niches, offering unique solutions for specific applications like concrete protection, high-temperature environments, or temporary protection during construction. This trend fosters innovation and caters to diverse client needs. Recognizing the importance of local nuances, regional players are adapting to specific regulations and challenges, offering culturally relevant solutions, and building strong relationships with local clients to enhance their competitive edge.

Recent Developments in the Surface Protection Service Industry:

  • AkzoNobel unveiled a new powder coating technology that can reduce energy consumption and carbon emissions by up to 25%. The company also completed the sale of its specialty chemicals business to The Carlyle Group and GIC for USD 12.5 billion on October 1, 2023.
  • Nippon Paint Holdings launched a new anti-viral paint that can deactivate 99.9% of coronaviruses on surfaces on January 28, 2024. The company also acquired the remaining 49% stake in Nippon Paint (India) from its joint venture partner, Berger Paints, on September 30, 2023.

Key Companies in the Market

  • Shawcor
  • PPG Industries
  • Hempel
  • Jotun
  • AkzoNobel
  • Sherwin-Williams
  • Nippon Paint Holdings

Key Segmentations

By Product Type:

  • Corrosion Protective Rubber Lining
  • Corrosion Protective Coating Systems
  • Acid Proof Lining
    • Ceramic & Brick Lining
    • Tile Lining
    • Thermoplastic Lining

By Application:

  • Process Vessels, Equipment & Rigs
  • Collection Basins & Tanks
  • Pipelines
  • Others (water treatment facilities, incinerators, etc.)

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia
  • Oceania
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:      

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs | YouTube

Sports Nutrition Market to Grow at an 11.5% CAGR Through 2033, Says FMI Report

Sports Nutrition Market

According to Future Market Insight, the global sports nutrition market is likely to reach USD 61.66 billion by 2033, registering a CAGR of 11.5%. This is a considerable increase from its projected value of USD 20.77 billion in 2023.

Global participation in sports and fitness activities is on the rise, with more people engaging in diverse exercise routines and athletic pursuits. This trend spans professional athletes, fitness enthusiasts, and casual gym-goers, all contributing to a growing demand for sports nutrition products designed to boost performance, endurance, and recovery.

As health and wellness take center stage, consumers are increasingly prioritizing products that support their fitness goals, weight management, and nutritional needs. Sports nutrition offerings such as protein powders, energy bars, and dietary supplements are gaining popularity, perfectly aligning with these evolving lifestyle trends.

Understanding the Sports Nutrition Market

The sports nutrition market encompasses a diverse range of products designed to enhance athletic performance, support recovery, and promote overall health for active individuals. As fitness trends continue to evolve, this market has witnessed significant growth, driven by various factors:

  1. Market Overview: The sports nutrition market includes supplements, energy bars, protein powders, hydration products, and more, catering to athletes and fitness enthusiasts. It has expanded beyond traditional athletes to include casual gym-goers and individuals seeking healthier lifestyles.
  2. Key Trends:
    • Increased Awareness: Growing awareness of the benefits of proper nutrition for performance and recovery has led to increased demand for sports nutrition products.
    • Clean Label Products: Consumers are increasingly seeking products with natural ingredients and transparent labeling, driving brands to reformulate their offerings.
    • Personalization: Tailored nutrition plans based on individual needs and preferences are gaining popularity, with brands offering customized solutions.
  3. Target Demographics: The market serves various segments, including professional athletes, amateur sports enthusiasts, and recreational exercisers. Different demographics, such as age and gender, influence product preferences.
  4. Distribution Channels: Sports nutrition products are sold through various channels, including specialty stores, online platforms, gyms, and health clubs. The rise of e-commerce has significantly changed how consumers access these products.
  5. Challenges: The market faces challenges such as regulatory scrutiny, competition from non-sports-specific health products, and the need for continuous innovation to meet evolving consumer demands.
  6. Future Outlook: With the global focus on health and fitness expected to continue rising, the sports nutrition market is poised for further expansion. Innovations in product formulations, sustainability, and marketing strategies will be crucial for brands to remain competitive.

Key Trends in the Sports Nutrition Industry

  • The evolution of popular supplements includes protein powders, energy bars, and sports drinks.
  • Increasing awareness of the benefits of sports nutrition for performance and recovery
  • Specialized products developed for specific fitness goals
  • Technology integration for tracking nutrition and performance
  • Expansion of female-focused sports nutrition.

Key Challenges in the Sports Nutrition Industry

  • Intense market competition and price wars
  • Regulatory restrictions and guidelines on ingredients and claims
  • Consumer skepticism and negative perception
  • Limited consumer awareness and education
  • Potential health risks and side effects
  • Fluctuating raw material prices
  • Limited availability and distribution channels
  • Economic downturns impacting consumer spending

Key Takeaways from the Sports Nutrition Market:

  • The sports nutrition industry in the United Kingdom is anticipated to rise, exhibiting a CAGR of 3.8% through 2033.
  • The United States dominated the sports nutrition industry in 2022, holding a 23.9% global market share.
  • In 2022, Japan had a 2.4% share of the sports nutrition industry globally.
  • With a CAGR of 25.8% over the forecast period, India is predicted to develop rapidly in the sports nutrition industry.
  • The sports nutrition industry in China is expected to increase, registering a CAGR of 4.2% over the forecast period.
  • Germany accounted for 5.9% of the global sports nutrition industry in 2022.

Competitive Landscape in the Sports Nutrition Market

Key players employ various measures to preserve their market positions and broaden their global reach. Those strategies involve the following:

  • Emphasizing features, quality, and performance to stand out from competitors
  • Identifying specific target segments based on demographics, interests, or fitness goals
  • Offering specialized programs or services to cater to different customer groups
  • Building a strong brand presence through effective marketing campaigns
  • Leveraging endorsements and partnerships with influential athletes or fitness influencers
  • Utilizing digital marketing channels and social media to engage with target audiences
  • Acquiring or partnering with complementary businesses to broaden the product portfolio
  • Creating an ecosystem of interconnected fitness products for a seamless user experience
  • Collaborating with fitness clubs, gyms, or sports organizations to increase reach and visibility
  • Partnering with health and wellness brands to offer integrated solutions

Recent Developments by Key Players

  • In December 2022, HealthKart secured a funding round and raised US$ 135 million. Temasek, a wealth fund based in Singapore, primarily led the funding. HealthKart has strategic plans to utilize the funds for expanding the sales of supplements and other nutritional products to new customers.
  • In August 2022, Spacemilk, an American sports nutrition brand, and NextFerm Technologies, an Israeli food technology start-up, signed a partnership agreement. The agreement involves the ProteVin supply, a non-GMO protein alternative.
  • In January 2022, Cut, an energy drink, was launched by Hydroxycut. Its primary goal is to help consumers reduce their body fat percentage. Hydroxycut, the brand behind ‘Cut,’ operates under the parent company Lovate Health Sciences.

Key Players in the Sports Nutrition Market

  • Nestlé S.A.
  • Red Bull GmbH
  • Ajinomoto Co., Inc.
  • Keurig Dr. Pepper, Inc.
  • Nutrabolt
  • GlaxoSmithKline plc.
  • Optimum Nutrition, Inc.
  • Premier Nutrition Corporation
  • Biothrive Sciences
  • Nutrabolt
  • Now Foods
  • INC Sports Nutrition
  • Vitaco Health
  • Uelzena Group

Key Segmentation:

By Ingredient Type:

  • Plant-derived Ingredient
    • Soy Protein
    • Rice Protein
    • Pea Protein
    • Potato Protein
  • Animal-derived Ingredient
    • Creatine
    • Milk Protein
    • Whey Protein Concentrates
    • Casein
    • BCAA (Branded Chain Amino Acid)
  • Blends

By Nature:

  • Organic
  • Conventional

B2C

By Function:

  • Energizing Products
  • Rehydration
  • Pre-Workout
  • Recovery
  • Weight Management

By Product Form:

  • Ready-to-drink
  • Energy & Protein Bar
  • Powder
  • Tablets/Capsules

By Flavour:

  • Regular
  • Flavored
    • Fruit Punch
    • Berries
    • Citrus
    • Chocolate
    • Vanilla
    • Others

By Sales Channel:

  • Modern Trade
  • Convenience Store
  • Specialty Store
  • Pharmacy Store
  • Online Retail
  • Other Sales Channel

By Price Range:

  • Economic
  • Premium

Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • The Middle East & Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs YouTube

Fish Feed Market to Grow Steadily at 3.5% Annually Through 2033: FMI

Fish Feed Market

According to FMI, fish feed market is expected to reach USD 116,480 million by 2023. It is estimated that the market is poised to reach USD 163,530 million between 2023 and 2033, representing a CAGR of 3.5%.

Fish feed consists of a blend of essential materials, additives, and supplements derived from both natural and synthetic sources, formulated specifically for farmed fish. Supported by the UK Seafood Innovation Fund (SIF), Rare Earth Global—a producer of industrial hemp for sustainable applications—has secured over £260,000 in funding to undertake a two-month evaluation of fish feed quality as part of a broader R&D project. Last year, Scottish salmon farmers explored the feasibility of incorporating hemp seeds into their fish diets.

Globally, fish accounts for approximately 15% of the protein consumed per capita. Its low carbon footprint, high yield efficiency, and distinctive protein profile have driven increased consumption, boosting the demand for fish feed amid a growing shortage of marine-based feed resources.

The fish feed market is a vital segment of the aquaculture industry, which has seen significant growth due to increasing global demand for fish as a primary source of protein. This market encompasses various products designed to provide essential nutrients for the optimal growth and health of fish.

Market Dynamics

Drivers

  1. Rising Demand for Seafood: The growing population and changing dietary preferences are driving the demand for fish, prompting the expansion of aquaculture.
  2. Aquaculture Growth: With the depletion of wild fish stocks, aquaculture is becoming the primary method of fish production, necessitating high-quality fish feed.
  3. Health Consciousness: Increased awareness of the health benefits of fish consumption is pushing demand for sustainably farmed fish.

Challenges

  1. Raw Material Scarcity: Dependence on fish meal and fish oil, which are derived from wild fish stocks, poses sustainability challenges and cost fluctuations.
  2. Environmental Regulations: Stricter regulations on aquaculture practices and feed formulations can impact production and operational costs.
  3. Competition from Alternatives: The emergence of plant-based and alternative protein sources for fish feed may disrupt traditional feed markets.

Fish feed demand may vary depending on consumer preferences for sustainable seafood products and healthy seafood. Aquaculture practices may have to adapt their feed formulations and production methods as consumers become more aware of their environmental and health impacts.

Advances in aquaculture technology, such as automated feeding systems, precision feeding, and data-driven management, could influence the demand for specialized fish feed products in the market. The demand for specific types of fish feed can be affected by the type of fish farmed. Dietary requirements for different species can influence fish feed composition and formulation.

Feed formulations that are more efficient and cost-effective have been the result of ongoing research and development in fish nutrition and feed technology. As farmers pursue improved production outcomes and cost-saving measures, demand will increase.

Sustainable aquaculture practices are becoming increasingly important to minimize environmental impact. The ecological footprint of fish farming operations can be reduced by using feed ingredients that are sourced responsibly.

Different species of fish require different levels of nutrition. Creating specialized feeds to meet the dietary needs of farmed fish, including salmon, tilapia, catfish, shrimp, and carp, is driving the demand for fish feed.

Key Takeaways from the Market Study

  • By 2032, the global market for fish feed is predicted to reach US$ 1,58,000 million.
  • In 2022, the United States held 25.8% of the global fish feed market.
  • According to industry estimates, fish feed demand is expected to rise at an average CAGR of 8% between 2022 and 2032.
  • In 2022, the market for fish feed grew by 6.7% in China.
  • Towards the end of 2022, Japan was responsible for 4.4% of the global market.
  • Germany accounted for 13.1% of the global fish feed market in 2022.
  • The fish feed market recorded a CAGR of 1.6% between 2018 and 2022.

“Plant-based fish feed will continue to be popular as the market for sustainable and organic fish feed grows in the market. Intensified fish farming practices and growing awareness of health and nourishing foods to grow the market.” says an FMI analyst.

Competitive Landscape

A growing number of companies are collaborating with other companies and forming strategic partnerships in order to grow their fish feed businesses. A growing number of fish feed market players are investing heavily in research and development, developing new products, expanding their geographical reach, and forming strategic partnerships.

  • On April 2023, ICAR-Central Inland Fisheries Research Institute, Barrackpore signed an agreement with Glaucus Agrochem Pvt Ltd for the usage of the floating fish feed “CIFRI Cagegrow”. For a period of five years, ICAR-CIFRI has granted a nonexclusive license for manufacturing and selling its floating fish feed Cagegrow in India. ICAR’s commercial arm, Agrinnovate India Ltd, completed the commercialization process.
  • On August 2023, Kerala varsity produced fish feed from organic waste. As part of its experimental fish meal production project, Kerala Fisheries and Ocean Studies University (KUFOS) is using organic waste to produce fish meals. A black soldier fly larvae-based project is being developed to produce the organic waste protein needed for fish feed production.

Know More about What the Fish Feed Market Report Covers

Future Market Insights offers an unbiased analysis of the global fish feed market, providing historical data for 2018 to 2022 and forecast statistics from 2023 to 2033.

To understand opportunities in the fish feed market, the market is segmented based on product type, form, end-use application, and distribution channel industry type across six major regions.

Market Segmentation

Product Type:

  • Plant Based
  • Fish & Fish Products
  • Microorganism

Form:

  • Pellet
  • Granules
  • Flakes
  • Sticks
  • Powder

End Use Application:

  • Commercial
  • Household

Distribution Channel:

  • B2B
  • B2C
    • Store based
    • Online retail

By Region:

  • North America
  • Latin America
  • Western Europe
  • Eastern Europe
  • South Asia and Pacific
  • East Asia
  • Middle East and Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Contact Us:

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedInTwitterBlogs YouTube