Paraffin Wax Demand Soars as Companies Embrace Its Aesthetic and Thermal Insulating Properties for Packaging and Beyond

According to Future Market Insights (FMI), the worldwide demand for paraffin wax market is expected to reach USD 10509.6 million in 2024 and USD 18253.6 million by 2034. The market is projected to rise at a CAGR of 5.7% by 2034.

The industry is experiencing dynamic changes due to increasing demand from various industries, such as packaging, healthcare, and cosmetics. Sustainability efforts and creative uses in the candle industry are pushing the business towards customized mixtures of wax and eco-friendly substitutes.

Crude oil is the main raw material for wax extraction, and the high demand for crude oil has led to an increase in its by-products, such as paraffin wax.  The quality of paraffin wax varies based on the source of crude oil, refining degree, and wax composition.

Manufacturers are looking towards sustainable wax choices as consumer tastes change due to rising environmental concerns. Bio-based wax made from renewable resources like sugarcane or coconut oil is gaining traction among ecological-conscious consumers.

Key Takeaways from the Paraffin Wax Market Report:

  • The paraffin wax market is expected to reach a value of USD 18253.6 million by 2034.
  • The market is projected to surge at a CAGR of 5.7% by 2034.
  • China’s paraffin wax market is expected to grow at a CAGR of 6.4% by 2034.
  • The United Kingdom is set to rise at 2.2% CAGR by 2034.
  • Based on product type, the fully refined segment is expected to hold a market share of 62.9% in 2024.

“Growing industrialization and manufacturing activities to surge demand for high-purity waxes like nuclear paraffin wax, particularly in industries like cosmetics, pharmaceuticals, and candle manufacturing. Availability of raw materials and technological advancements further influence market dynamics, with regional trends often affecting overall supply and demand.” – Opines Nikhil Kaitwade Associate Vice President at Future Market Insights (FMI).

To Gain More Insights about this Research, Visit!

Competitive Landscape

The global paraffin wax market is fragmented and diversified, with numerous key participants. The market is evaluated based on product offerings, financial statements, key developments, strategic approach, market position, geographical penetration, and other key features. The report’s competitive landscape section details the leading companies, key developments, partnerships, mergers, acquisitions, new product launches, and regional and industry footprints.

Leading Paraffin Wax Brands:

  • Sinopec
  • ExxonMobil
  • PetroChina Company Limited
  • Sasol
  • CEPSA
  • Honeywell
  • Petrobras
  • Nippon Seiro Co., Ltd
  • Petro-Canada
  • Repsol

Industry Updates-

  • In 2023, Saudi Aramco, Sinopec, and SABIC partnered to establish a refinery and petrochemical cracker complex in China and Saudi Arabia, aiming to enhance their collective capabilities.
  • In 2023, Eneos Corporation partnered with Niigata Public Corporation of Agriculture and Forestry to achieve a decarbonized society through forest conservation, aiming to reduce Scope 1 and 22 CO2 emissions by 46% by 2030.

Get More Valuable Insights:

Future Market Insights (FMI), in its new offering, provides an unbiased analysis of the global paraffin wax market, presenting historical demand data (2019 to 2023) and forecast statistics for the period from 2024 to 2034.

The study incorporates compelling insights on the paraffin wax market based on product type (fully refined, semi-refined, and others), application (candles, packaging, cosmetics, hot melt, board sizing, and rubber), and region.

Key Segments of Market Report:

By Product Type:

The landscape is categorized into three leading product types: fully refined, semi-refined, and others.

By Application:

A few key applications include candles, packaging, cosmetics, hot melt, board sizing, and rubber.

By Region:

Information about key countries of North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia, and the Middle East and Africa is given.

Browse Complete Research: Paraffin Wax Market is Expected to Reach USD 18253.6 Million, Globally by 2034 at 5.7% CAGR: Future Market Insights, Inc.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Polyvinyl Chloride Market Set to Expand at 3.6% CAGR, Boosted by Sustainable Manufacturing and Rising Industry Applications

The global polyvinyl chloride market size is estimated to reach USD 70156.2 million by 2024 and is set to grow at a CAGR of 3.6% from 2024 to 2034. It is estimated that worldwide sales of polyvinyl chloride will total USD 100115.7 million by 2034, driven by the increasing application of PVC in the healthcare sector.

PVC flooring is affordable, durable, and easy to install, making it a popular choice for homeowners and businesses. The material’s corrosion resistance contributes to surging demand in various industries.

The construction industry is expected to surge the demand for polyvinyl chloride (PVC) products due to infrastructure development, urbanization, and renovations across the globe. PVC is gaining traction in various end-use industries due to high versatility and affordability.

There is a growing emphasis on sustainable practices in its manufacturing and use. This includes advancements in PVC formulations, recycling techniques, and the creation of eco-friendly PVC products.

PVC components are used in marine infrastructure and industrial applications due to their ability to withstand corrosion, moisture, and chemicals. The material has a high utilization in the healthcare industry due to its biocompatibility, ease of sterilization, and cost advantage.

However, the industry faces challenges due to its reliance on oil and gas derivatives, environmental concerns, and regulations on PVC use and disposal. Companies are working on developing sustainable PVC formulations and addressing these challenges through responsible waste management and compliance with regulations.

Key Takeaways from the Market Report

  • The polyvinyl chloride market is set to reach USD 100115.7 million by 2034 with a CAGR of 6%.
  • By product type, rigid PVC is likely to dominate the polyvinyl chloride market with a value share of 2% in 2024.
  • Based on end-use industries, building, and construction will likely account for a market share of 3% in 2024.
  • The United States is anticipated to record a CAGR of 2% between 2024 and 2034.
  • Germany is estimated to hold the leading position in Europe and show steady growth at a CAGR of 8% by 2034.

“Nations having ambitious plans for their infrastructure development are the prominent drivers pushing sales of PVCs around the globe,” says a lead analyst at Future Market Insights (FMI).

Browse the Complete Report!

Who’s Winning?

The polyvinyl chloride industry is highly competitive, with key players like Formosa Plastics Corporation, Chinyang Chemical Co. Ltd, BASF SE, and Arkema S.A. developing bio-based plasticizers and compostable PVC formulations to reduce environmental impact and meet consumer demand for sustainable goods. These players are increasingly investing in innovative recycling technologies to reduce virgin materials and promote a circular economy. They are also focusing on developing unique PVC films with enhanced properties, promoting lead-free compounds, and focusing on minimizing production costs and maximizing resource usage in niche markets.

Leading Polyvinyl Chloride Brands

  • Formosa Plastics Corporation
  • Chinyang Chemical Co. Ltd
  • BASF SE
  • Arkema S.A.
  • Ineos Chlorvinyls Ltd
  • Saudi Plastic Products Company Ltd
  • Occidental Petroleum Corporation
  • Premier Polyfilm Ltd
  • The Chemical Company

Industry Updates-

  • Bharti Airtel, headquartered in New Delhi, in February 2024, partnered with IDEMIA to launch recycled PVC SIM cards.
  • Phoenix Industries, headquartered in Colombo, in March 2024, re-launched their range of PVC product lines under a new Super PVC brand.

Get More Insights into the Polyvinyl Chloride Market Report

In its latest report, Future Market Insights (FMI) offers an unbiased analysis of the polyvinyl chloride market, providing historical data from 2019 to 2023 and forecast statistics for the period 2024 to 2034. To understand the industry potential, growth, and scope, the industry is segmented based on product type (rigid PVC and flexible PVC), application (pipes and fittings, films and sheets, cables, and others), end-use industries (building and construction, electrical and electronics, automotive, packaging, medical and others), and region (North America, Latin America, Western Europe, South Asia, East Asia, Eastern Europe, and the Middle East and Africa).

Key Segments of Market Report

By Type:

Based on type, the sector is divided into rigid PVC and flexible PVC.

By Application:

PVC has applications in pipes and fittings, films and sheets, cables, and others.

By End-use:

By end-use, the sector is segmented into building and construction, electrical and electronics, automotive, packaging, medical, and others.

By Region:

The polyvinyl chloride industry is spread across North America, Latin America, Western Europe, South Asia, East Asia, Eastern Europe, and the Middle East and Africa.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Global Polycarbonate Sheet Market Sees Strong Growth, Driven by Renewable Energy and Electric Vehicle Trends

The global polycarbonate sheet industry value reached USD 1975.9 million in 2023. Over the forecast period, the value is anticipated to rise at 5.1% CAGR. The market is predicted to increase from USD 2076.6 million in 2024 to USD 3415 million in 2034.

The global polycarbonate sheets market growth is set for propitious growth, invigorated by promising demand from the automotive, and building & construction industries. Witnessing a projected CAGR of 4.3% from 2024 to 2034, this billion-dollar industry will receive noteworthy momentum from the Asia Pacific market. Expediting infrastructural activities in developing countries continue to create lucrative white spaces for manufacturers of polycarbonate sheets.

Moreover, high-performance attributes of polycarbonate sheets such as superior thermal resistance, outstanding impact resistance, impressive optical clarity, and dimensional stability are soaring the demand. As compared to other thermoplastics such as acrylic and polymethyl methacrylate (PMMA), polycarbonate sheets undergo minimal degradation when heated or cooled.

Key Takeaways of Polycarbonate Sheets Market Study

  • Crucial attributes such as high impact resistance, thermal insulation, and dimensional stability are boosting the demand for polycarbonate sheets.
  • Polycarbonate sheets are set to become a preferred alternative for acrylic and glass on account of low maintenance cost and degradation over time.
  • Low carbon emissions are prompting manufacturers to accelerate the adoption of polycarbonate sheets.
  • The role of polycarbonate sheets in manufacturing sturdy, lightweight, and eco-friendly automotive components will steer the demand through 2029.
  • Increasing usage of polycarbonate sheets in commercial and residential spaces for cladding and roofing applications will exhibit promising growth through the forecast period.
  • Gains in the polycarbonate sheets market will remain concentrated in Asia Pacific through 2029.
  • Fluctuations in raw material prices will hinder the growth of the polycarbonate sheets market during the projection period.

“Globally leading manufacturers of polycarbonate sheets must plan massive investments in strengthening their supply chain across Asia Pacific to capitalize on surging demand.”

Browse the Complete Report!

Asia Pacific Garners Over 43% Share in Global Market

Consumers in Asia Pacific (APAC) would be the key demographic for polycarbonate sheet manufacturers. Increasing net worth income of consumers in emerging Asian economies is capturing the attention of global market leaders. APAC continues to account for more than 43% of the total market value. Moreover, rapid industrialization is accentuating the demand for polycarbonate sheets. Strong government impetus and supporting policies are facilitating the growth of the polycarbonate sheets market in this region.

In view of maturing end-use industries such as automotive and construction, the polycarbonate sheets market in Europe and North America is relatively saturated. However, the packaging industry in these two regions will offer new growth opportunities on account of heightened demand from nuclear families.

Industry Leaders to Unlock Profitable Avenues Through Product Innovation

Major players profiled in this study, include but are not limited to, Trinseo, Spartech, Mitsubishi Gas Chemical, Evonik Industries, SABIC, Arla Plast, 3A Composites, Covestro, Excelite, Gallina India, and Palram Industries. Leading players continue to diversify their product portfolio, especially in Asia Pacific. In view of the enormous population, a wide range of application-specific polycarbonate sheets will cater to variegated end-use segments.

For instance, Covestro launched new polycarbonate thermoplastics under the series ‘Makrolon’ which cater to various applications such as LED lighting, architectural glazing, eyewear, electronics, sporting equipment, automotive headlamps, and medical devices. Moreover, global players must collaborate with regional manufacturers to expand their market foothold.

Polycarbonate Sheets Market Segmentation

Type:

  • Solid
  • Multiwall
  • Corrugated

End-Use:

  • Building & Construction
  • Automotive
  • Electrical & Electronics

Region:

  • North America
  • Latin America
  • Europe
  • MEA
  • Asia Pacific

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
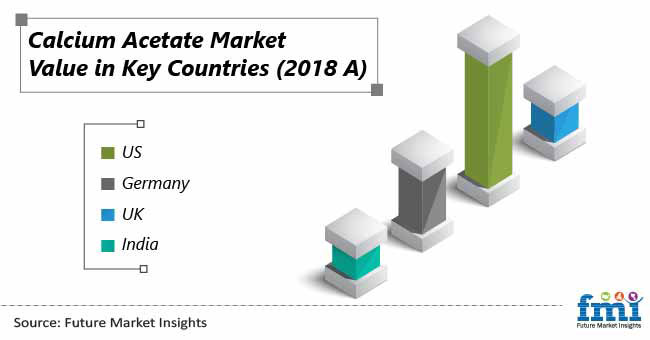
Rising Demand for Calcium Acetate in Dairy Products and Blood Dialysis to Fuel Market Growth Through 2029

Calcium Acetate Market

The global calcium acetate industry demand is poised to witness steady growth throughout the forecast period (2019 to 2029), with a projected Compound Annual Growth Rate (CAGR) of 3%. Key drivers fueling this growth include the continuous demand from diverse end-use sectors such as pharmaceuticals, food & beverages, and textiles. Market analysis by Future Market Insights (FMI) forecasts a concentration of bulk demand in Europe and North America.

Key Takeaways:

  • Pharmaceutical Applications Driving Growth: Calcium acetate’s role in treating hypophosphatemia, particularly among patients with kidney diseases undergoing dialysis, is a significant driver of market growth. The compound helps regulate blood phosphate levels, thereby reducing the risk of stroke or heart disease.
  • Expansion in Food & Beverage Industry: The use of calcium acetate as a preservative and additive in food products, especially in the manufacturing of dairy products like milk powder, cream, and condensed milk, is expected to experience substantial growth during the forecast period.
  • Diverse Industrial Applications: Calcium acetate finds applications in various industries, including pharmaceuticals, chemicals, and construction. It is used in the production of anti-epileptic drugs, resins, printing inks, lubricants, and as a concrete accelerator in the construction sector.

Regional Analysis:

  • Europe Dominates Market Share: The European region is expected to lead the calcium acetate market, driven by substantial investments in research and development (R&D) activities aimed at diversifying its applications. However, the market may face challenges due to saturation in certain segments.
  • Asia Pacific Emerges as Growth Hub: Asia Pacific is anticipated to witness significant demand for calcium acetate, driven by factors such as rising income levels, increasing purchasing power parity, and improving lifestyle. Countries like Indonesia, Taiwan, Thailand, Japan, and India are poised to be major contributors to this growth, particularly in pharmaceuticals, soaps, and detergents.

To Gain More Insights about this Research, Visit!

Competitive Landscape

Key players in the consolidated calcium acetate market include,

  • Alemark
  • Merck Millipore
  • GFS Chemicals
  • Richman Chemical
  • Allan Chemical Corp.
  • Avantor Performance Materials
  • AVA Chemical PVT. LTD.
  • Hawaii Chemicals & Scientific

Leading players are leveraging economies of scale for sustained competitive advantage.

Calcium Acetate Market: Segmentation

The global calcium acetate market is segmented in detail to cover every aspect of the market and present a complete market intelligence approach to readers.

Function

  • Texturizer
  • Stabilizer
  • Thickener
  • Firming Agent

Application

  • Pharmaceuticals
  • Agriculture
  • Food and Beverages
  • Pet Food

Region

  • North America
  • Latin America
  • Europe
  • MEA
  • Asia Pacific

Old Study: https://www.globalbankingandfinance.com/calcium-acetate-market-latest-technology-and-market-trends-forecast-2019-2029/

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Anti-Seize Compounds Market Set to Reach USD 236.4 Million by 2029 Amid Rising Infrastructure Investments and Construction Spending

Anti-seize Compounds Market

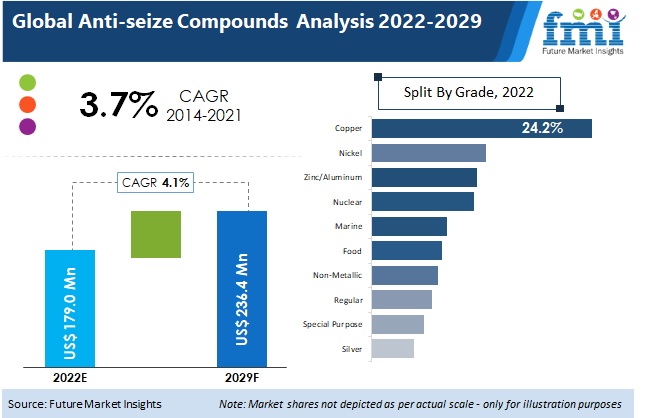
According to the latest report by FMI, the global sales of anti-seize compounds market is expected to reach a valuation of USD 236.4 Million by 2029. Increasing urbanization and rapid industrialization are creating massive opportunities for the construction industry, and significantly contributing to the rising demand for anti-seize compounds.

Substantial growth in the anti-seize compounds market is mainly backed by the growth of the automotive & transportation industry, which holds a prominent share in the consumption of anti-seize compounds, closely followed by the petrochemical sector.

“In most end-use industries, galling or seizing can increase maintenance time, resulting in longer shutdowns or closure. Increasing use of anti-seize compounds has enabled end users to reduce maintenance cost as well as time, and has simultaneously offered an efficient solution for improving gasket performance.”

Key Takeaways of Anti-seize Compounds Market Study

  • Anti-seize compounds serve almost all major end users, including automotive & transportation, petrochemicals, mining, and others. The industrial sector in Asia Pacific is growing substantially, thereby increasing the demand for anti-seize compounds in the region.
  • Copper-grade anti-seize compounds find use in almost all end-use industries; hence, the segment is the most prominent amongst other grades. The nickel-grade anti-seize compounds segment is anticipated to grow at a substantial rate, as these are increasingly being preferred in industries such as petrochemicals, oil exploration, and other industries where chemicals are involved, on account of nickel’s inert nature.
  • East Asia is a prominent market for anti-seize compounds and is expected to continue its dominance, owing to its strong industrial growth and high adoption of the product in the region.
  • Increasing awareness about the need for the protection of the environment and the prevention of soil contamination has restricted the use of metallic anti-seize compounds on a global scale. Moreover, users prefer nonmetallic anti-seize compounds over metallic ones, owing to their high cost.

Browse the Complete Report!

The market Landscape is Fairly Fragmented

The global anti-seize lubricants market is fairly fragmented, owing to a number of players holding small shares in the market. The top ten established players account for more than one-third of the total supply. Manufacturers are focusing on strengthening their partnerships with end users and original equipment manufacturers (OEMs).

Established players provide services to end users, which is an added advantage and will help them build relations for long-term supply.

Key Companies Profiled

  • FUCHS
  • Chevron Corporation
  • Calumet Specialty Products Partners – Bel-Ray
  • DuPont – Molykote
  • 3M Company
  • Henkel AG
  • CSW Industrials, Inc.
  • CRC Industries
  • Anti-Seize Technology
  • Permatex Inc.
  • Saf-T-Lok International Corporation
  • Bostik Inc.

Anti-Seize Compounds Market Taxonomy

Grade

  • Silver Grade
  • Nickel Grade
  • Food Grade
  • Marine Grade
  • Copper Grade
  • Regular Grade
  • Nuclear Grade
  • Non-metallic Grade
  • Zinc/Aluminum Grade
  • Special Purpose Anti-seize Grade

Sales Channel

  • Offline
  • Online

Container Type

  • Cans
  • Cartridges
  • Drums
  • Other Containers

End Use

  • Automotive & Transportation
  • Construction Equipment
  • Aircraft
  • Mining Equipment
  • Food Processing Equipment
  • Marine
  • Power Generation
  • Oil Exploration Equipment
  • Steel Foundry
  • Petrochemicals
  • Textile Equipment
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • South Asia
  • East Asia
  • Oceania
  • Middle East & Africa

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Green Roofing Solutions: Revolutionizing the Industry with Sustainable and Energy-Efficient Materials

The global Roofing Material Market is expected to experience substantial growth over the next decade, driven by increasing urbanization, rising demand for eco-friendly roofing solutions, and significant investments in infrastructure projects. According to industry projections, the market size is expected to grow from an estimated USD 147.1 billion in 2024 to USD 231.1 billion by 2034, at a compound annual growth rate (CAGR) of 4.6% during the forecast period.

Understanding the Roofing Material Market

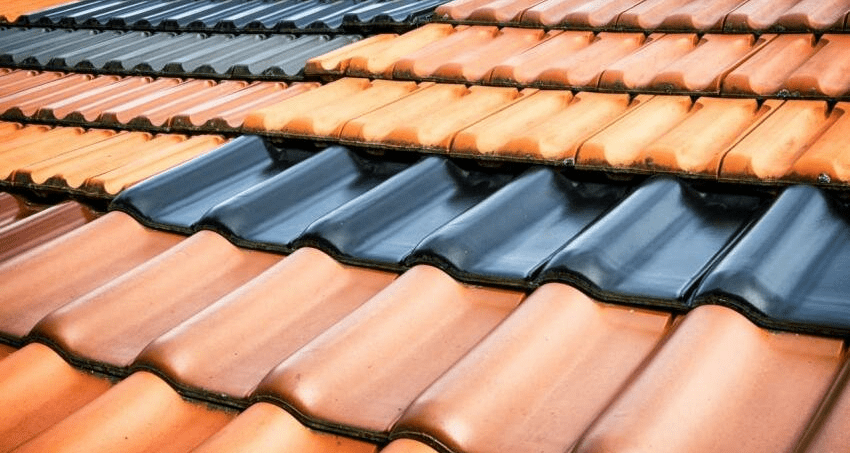
Roofing materials are essential components of construction, ensuring durability, protection, and aesthetics of buildings. The roofing material industry comprises a variety of products, including asphalt shingles, metal roofing, clay and concrete tiles, and synthetic materials. These materials cater to both residential and non-residential sectors, ensuring that they provide protection from environmental factors such as rain, heat, snow, and wind while also offering energy efficiency and sustainability.

With growing awareness around energy conservation, roofing materials have evolved from traditional options to more advanced, eco-friendly solutions. Green roofs, solar-integrated roofing systems, and materials with high reflective properties are gaining traction globally. The roofing material market is now not only about providing shelter but also contributing to environmental goals by enhancing energy efficiency and reducing carbon footprints.

Roofing Material Value and Growth Projections

The Roofing Material Market is set to grow at a consistent pace over the next decade. As of 2024, the market size is valued at approximately USD 147.1 billion. By 2034, this figure is projected to rise to an impressive USD 231.1 billion, reflecting a healthy CAGR of 4.6%. Several factors contribute to this growth, ranging from increasing global population and urbanization to governmental policies supporting energy-efficient buildings and the modernization of existing infrastructure.

The demand for sustainable roofing solutions is also playing a key role in this market expansion. As countries aim to reduce greenhouse gas emissions, both new construction and renovation projects are adopting sustainable roofing materials that provide better thermal insulation and reduce energy consumption. Additionally, the expansion of commercial spaces, growth in the tourism and hospitality sectors, and the rapid development of residential real estate projects are all contributing to the rising demand for roofing materials.

Prominent Drivers of the Roofing Material Market

  1. Urbanization and Infrastructure Development: Rapid urbanization in emerging economies is driving the demand for housing and infrastructure, which in turn fuels the roofing material market. Governments and private sectors are making significant investments in both residential and non-residential construction projects, especially in regions such as Asia-Pacific, Latin America, and Africa.
  2. Sustainability and Energy Efficiency: With increasing emphasis on sustainability and energy-efficient buildings, the demand for green and eco-friendly roofing solutions has surged. Innovations like cool roofing materials that reflect more sunlight and absorb less heat have gained popularity in hot climates, while solar roof panels are seeing increased adoption in developed nations.
  3. Climate Resilience and Durability: Extreme weather conditions and changing climate patterns have created a demand for roofing materials that offer superior protection and durability. This has prompted the development of materials that can withstand heavy rains, high winds, and extreme temperatures, making them a crucial part of disaster-resilient construction strategies.
  4. Renovation and Retrofitting of Old Structures: A substantial portion of the global building stock, particularly in developed countries, is aging. This is leading to increased renovation and retrofitting activities, where outdated roofing systems are being replaced with modern, energy-efficient materials. The retrofitting market is growing, especially in regions like North America and Europe, where the aging infrastructure demands urgent updates.
  5. Technological Advancements: The roofing industry is embracing technological advancements such as prefabricated roofs, robotic roofing systems, and advanced materials like polymer-modified asphalt. These innovations are driving efficiency in construction while improving the performance and lifespan of roofing materials.

Browse the Complete Report!

Leading Roofing Material Brands

  • Owens Corning Inc.
  • Johns Manville Corporation
  • GAF Materials Corporation
  • CertainTeed
  • Mapei SpA
  • Braas Monier Building Group
  • Atlas Roofing Corporation
  • ETEX
  • Carlisle Companies Inc.
  • IKO Industries Inc.
  • TAMKO Building Products
  • Alumasc Group PLC
  • DECRA Roofing Systems Inc.
  • Bauder Ltd.
  • Worthouse
  • Carlisle Companies Inc.
  • ETEX
  • Crown Building Products LLC
  • Boral Roofing

Challenges Faced by the Roofing Material Market

While the roofing material market is poised for growth, several challenges could impact its trajectory:

  1. Raw Material Price Volatility: The fluctuating prices of raw materials like bitumen, metals, and polymers can pose a significant challenge to manufacturers, as it affects the overall cost of roofing products. This can impact pricing strategies and profitability, especially for small to mid-sized enterprises.
  2. Environmental Regulations: Stringent environmental regulations concerning the use of non-biodegradable materials and the disposal of construction waste are becoming more prevalent. Manufacturers are under pressure to comply with these regulations, which could increase production costs and lead to additional investment in R&D for eco-friendly alternatives.
  3. Labor Shortages: In many regions, a shortage of skilled labor in the construction industry, including roofing professionals, can delay projects and lead to higher labor costs. This is particularly evident in developed countries, where the demand for experienced workers exceeds the available workforce.
  4. Supply Chain Disruptions: Geopolitical tensions, trade restrictions, and global events such as the COVID-19 pandemic have exposed vulnerabilities in supply chains. Delays in the transportation of raw materials and finished products can hinder market growth, especially in regions heavily dependent on imports.

The global Roofing Material Market is on a steady growth trajectory, with increasing urbanization, a focus on sustainability, and advancements in construction technology driving demand. While challenges such as raw material price volatility and environmental regulations exist, the market is expected to remain resilient, achieving a projected value of USD 231.1 billion by 2034.

As manufacturers adapt to changing market dynamics and invest in sustainable solutions, the roofing material industry will continue to play a critical role in shaping the future of global construction.

Key Segments of Market Report

By Product Type:

In terms of product type, the industry is segregated into asphalt shingles, concrete tiles, clay tiles, synthetic tiles, metal roofing, membrane roofing, green roofs, and others.

By End-use:

Residential and non-residential are the two end-users. The residential segment is further classified into new construction and renovation. The non-residential category is bifurcated into new construction and renovation.

By Region:

Information about several countries in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia, and the Middle East and Africa is provided.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Increasing Environmental Regulations Fuel Nitric Acid Market Expansion in the Automotive Sector

The demand for nitric acid is influenced by its role in the production of ammonium nitrate, which is used in manufacturing explosives. Furthermore, the increasing demand for nitric acid in the automotive industry, electronics, and agrochemical sectors is projected to drive its growth in the forecasted period.

The global nitric acid market growth is anticipated to attain a valuation of USD 30.66 billion in 2023 and is estimated to reach USD 42.7 billion by 2033, trailing a CAGR of 3.3% during the forecast period.

The nitric acid market is poised for growth, fueled by the rising demand from fertilizer formulators and the increased consumption of fertilizers in agricultural economies worldwide. Further, the growing need for food has driven the expansion of fertilizers and agricultural units globally, aiming to maximize crop yield, reduce cultivation time, and promote healthy crop growth.

The advancement of cutting-edge technologies like the mono-medium pressure process, mono-high pressure process, and dual pressure process is set to boost awareness and drive market growth in the upcoming years by enabling efficient production of nitric acid. Additionally, the growing demand for the product from the nylon production sector is expected to create new opportunities in the global market.

The demand for nitric acid is expected to rise due to increased consumption and manufacturing of ammonium nitrate, adipic acid, and toluene di-isocyanate. Nitric acid is widely adopted and captures a significant portion of the global demand.

The explosives industry, particularly in coal and metals mining, contributes to a substantial demand for nitric acid. Additionally, the production of explosives utilizing ammonium nitrate as a precursor significantly drives the demand for nitric acid.

Key Takeaways in Nitric Acid Market Research Study:

  • The market in Europe is expected to capture a CAGR of 3.1% during the forecast period.
  • The demand for nitric acid in the Asia Pacific is predicted to expand with a significant CAGR of 4% during the forecast period.
  • The sales of nitric acid in Brazil are expected to secure a CAGR of 2.9% from 2023 to 2033.
  • By application, the fertilizer segment is expected to expand with a CAGR of 5.2% between 2023 and 2033.

“Increasing use of nitric acid in the production of ammonium nitrate and fertilizers is expected to fuel market expansion during the forecast period,”– comments an FMI Analyst

To Gain More Insights about this Research, Visit!

Competitive Landscape in Nitric Acid Market:

The market for nitric acid is highly competitive, with various prominent industry players making substantial investments in increasing their manufacturing capabilities.

Latest Innovations in the Nitric Acid Market

  • In July 2022, Nutrien Ag Solutions signed an agreement to acquire Casa do Adubo S.A., a company in Brazil. This planned move aligns with Nutrien’s Retail growth strategy in Brazil and is expected to boost sales by USD 400 billion.
  • In June 2022, Nutrien Ag Solutions enhanced its fertilizer production capacity to effectively address shifts in global energy, agriculture, and fertilizer markets.
  • In June 2022, Omnia Holdings Limited actively pursued expansion opportunities in Canada, Indonesia, and Australia to strengthen its international mining and agriculture portfolio.
  • In June 2022, CF Fertilisers UK Limited unveiled its restructuring plans for operations in the United Kingdom. The company aims to centralize production exclusively at the Billingham manufacturing facility in Teesside.
  • In April 2022, BASF and SINOPEC commenced the expansion of their joint venture, BASF-YPC Co., Ltd., in Nanjing.

The Top Key Players are:

  1. BASF SE
  2. Dupont
  3. Nutrien Ltd.
  4. Omnia Holding Limited
  5. Apache Nitrogen Products Inc.
  6. CF Industry Holdings, Inc
  7. Thyssenkrupp AG
  8. Yara International ASA
  9. Rashtriya Chemical & Fertilizers Ltd.

Valuable Insights Available

Future Market Insights offers an unbiased analysis of the global nitric acid market, providing historical data from 2018 to 2022 and forecast statistics from 2023 to 2033.

The market is segmented based on application and region, to understand opportunities in the nitric acid market.

Key Segmentation of the Nitric Acid Market

By Application:

  • Fertilizers
  • Nitrobenzene
  • Adipic acid
  • Toluene diisocyanate (TDI)
  • Nitrochlorobenzene
  • Others

By Region:

  • North America
  • Latin America
  • Europe
  • Asia Pacific
  • The Middle East and Africa

Read Complete Research: https://finance.yahoo.com/news/global-nitric-acid-market-poised-103000514.html

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Ceiling Tiles Market Size Set to Reach USD 14,389.2 million by 2033, Driven by Sustainability and Energy-Efficient Building Trends

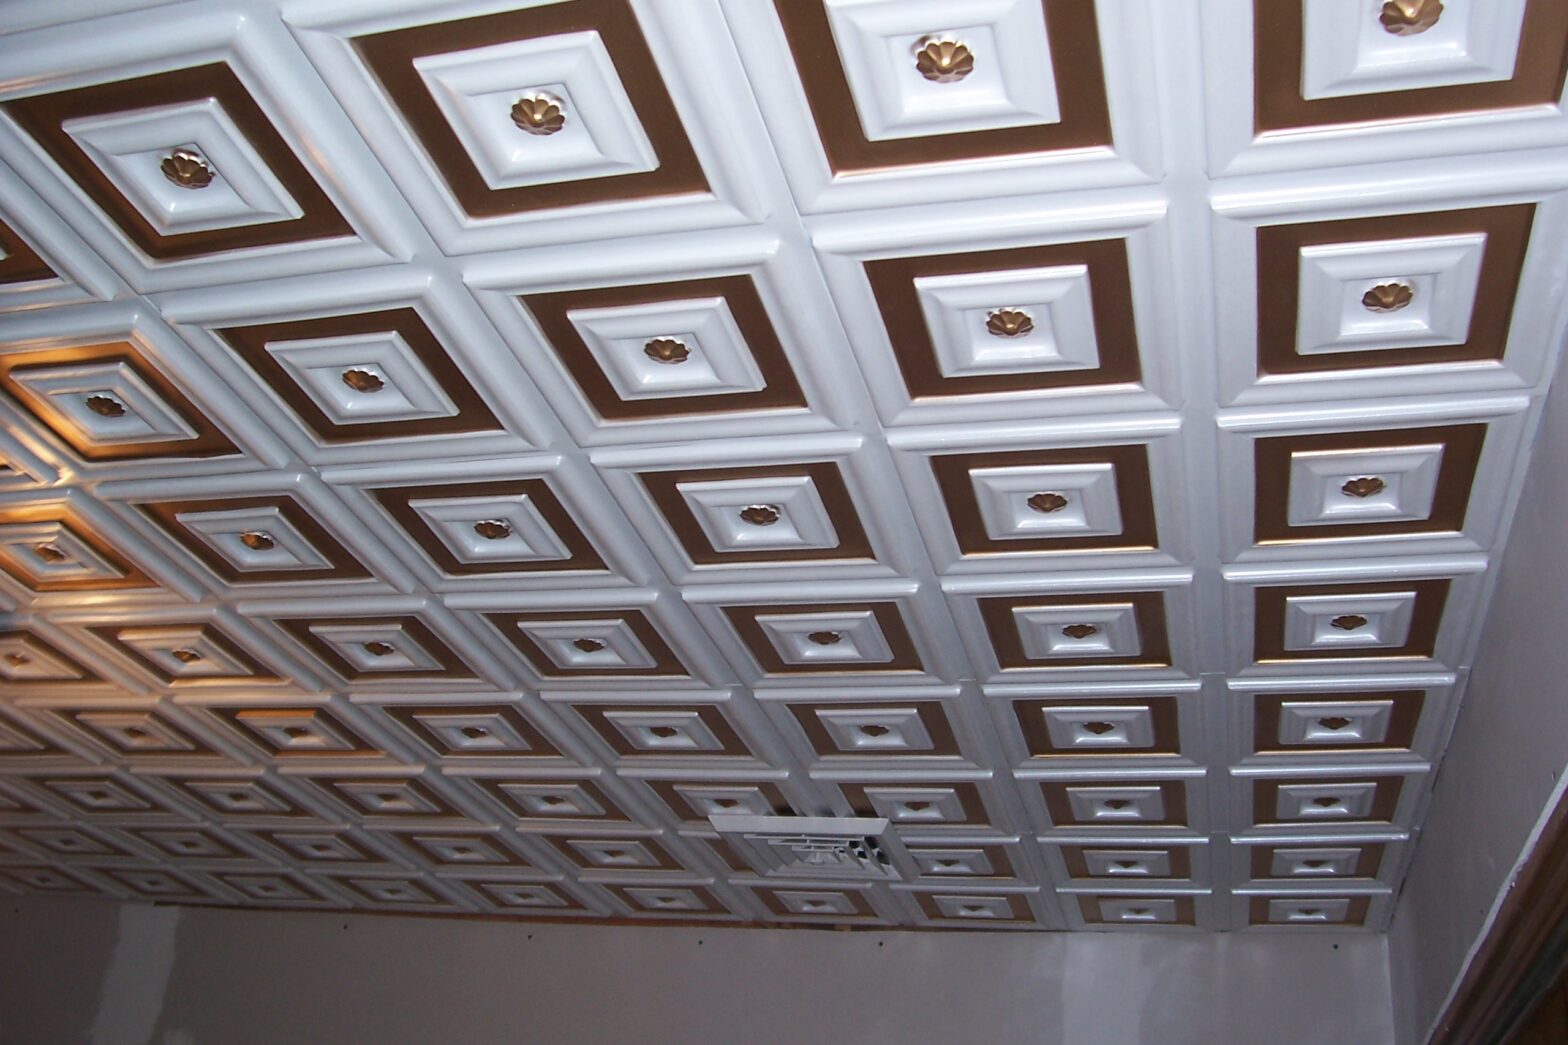
The ceiling tiles industry size is expected to reach USD 7,923.3 million by 2023 and USD 14,389.2 million by 2033, growing at a 6.1% CAGR. The growth in the construction and building industry has stimulated ceiling tile manufacturers to prosper. Ceiling tiles are becoming more popular throughout the world due to an increasing emphasis on decorating interiors and exteriors in commercial, industrial, and other fields.

Commercial construction is expected to expand in light of the increase in skyscrapers, hospitals, colleges, and shopping malls. According to predictions, the market will grow due to factors including the growing demand for thermal insulation and acoustic insulation. Metalworks ceilings are often constructed from aluminum, which can contain up to 98% recycled material. Construction waste is reduced by metal ceilings, which are reclaimable after their use and have a long lifespan. In addition, perforated panels with acoustical backing can also improve indoor environmental quality with metal ceilings by reducing reverberation time and enhancing acoustics, both of which can reduce the cost of energy consumption.

A sustainable ceiling may be constructed from recycled and recyclable materials, or from components that are environmentally friendly in the extraction, manufacture, and transportation process. In addition to being more sustainable, a durable ceiling does not have to be replaced as often as an inflexible ceiling. The Mineral & fiberglass ceiling tiles are a great option since they are stable under low to high frequencies. Ceiling tiles manufactured from mineral fibers tend to have a lower noise reduction coefficient (NRC) and a higher ceiling attenuation classification (CAC). Ceiling tiles made of fiberglass will keep a room quieter than mineral fiber ones. In addition to being moisture-resistant and sagging-resistant, fiberglass panels offer low density.

“A growing concern for the environment is encouraging major construction companies to use sustainable ceiling tiles, offering manufacturers a chance to expand their product lines,”, says an FMI analyst.

Key Takeaways

  • Approximately two-fifths of revenue in 2023 came from mineral fiber/gypsum ceiling tiles
  • Installed ceiling tiles are expected to enjoy an increase in demand in the future
  • The commercial market will account for over 90% of sales by 2033.
  • Drop ceiling tile is installed, its popularity is expected to skyrocket, due to its ease of installation against the backdrop of an explosion in popularity.
  • The development of infrastructure in India and China will spur sales.
  • The United States is expected to achieve significant growth in the coming years, backed by a positive housing market.
  • Regulations requiring periodic upgrades in ceiling material to lead the UK market’s growth.

Browse the Complete Report!

Competitive Landscape

The ceiling tile industry faces intense competition around the world. Their leading position in the highly competitive market will be maintained by offering a cost-effective and broader product line.

The key industry players are

  • Armstrong World Industries
  • USG Corporation
  • Compagnie de Saint-Gobain S.A. i
  • Hunter Douglas N.V.
  • SAS International
  • Rockfon, LLC
  • Odenwald Faserplattenwerk GmbH
  • Knauf AMF GmbH & Co. KG
  • Dexune
  • durlum GmbH
  • Techno Ceiling Products
  • Credence Industries
  • Prolad India Pvt. Ltd
  • India Gypsum Pvt. Ltd
  • Bangzheng International (KET Ceiling)

Market Developments Include:

  • In April 2023, Rockfon will unveil acoustic ceilings that reflect current trends in nature and wellness. Stone wool ceiling panels from Rockfon are not only beautiful but also support healthy acoustics and environmental quality in interior spaces. “Colors of Wellbeing” is a collection of matte-finished Rockfon® Chicago Metallic ceiling suspension systems and Rockfon Color-all acoustic stone wool ceiling panels.
  • In May 2023, Woven Image will introduce Fuji, a range of ceiling tiles for spaces with raw concrete interiors that improve sound quality. With industrial materials surfaces and exposed ceilings, the Fuji collection is a perfect choice for commercial offices that are becoming increasingly trendy. Compared to flat panels, tiles, or baffle systems, these tiles have concave three-dimensional shapes that offer better acoustic performance.

Ceiling Tiles Market Outlook by Category

By Material Type:

  • Mineral Fiber
  • Metal
  • Wood and Engineered Wood
  • Gypsum
  • Others

By Installation Type:

  • Suspended
  • Surface Mounted

By End Use:

  • Residential
    • Apartment Buildings
    • Individual Residences (Villas, Row Houses, Bungalows)
  • Commercial
    • Retail
    • Hospitality, Leisure & Entertainment
    • Offices
    • Healthcare
    • Educational Institutions
    • Others
  • Industrial

By Region:

  • North America
  • Latin America
  • East Asia
  • South Asia & Pacific
  • Western Europe
  • Eastern Europe
  • Central Asia
  • Russia & Belarus
  • Balkan & Baltic Countries
  • Middle East & Africa

Old Source: Ceiling Tiles Market is Anticipated to Reach USD 140 Billion by Rising at a CAGR of 14.8% during the forecast period of 2023 to 2033 | Future Market Insights, Inc.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
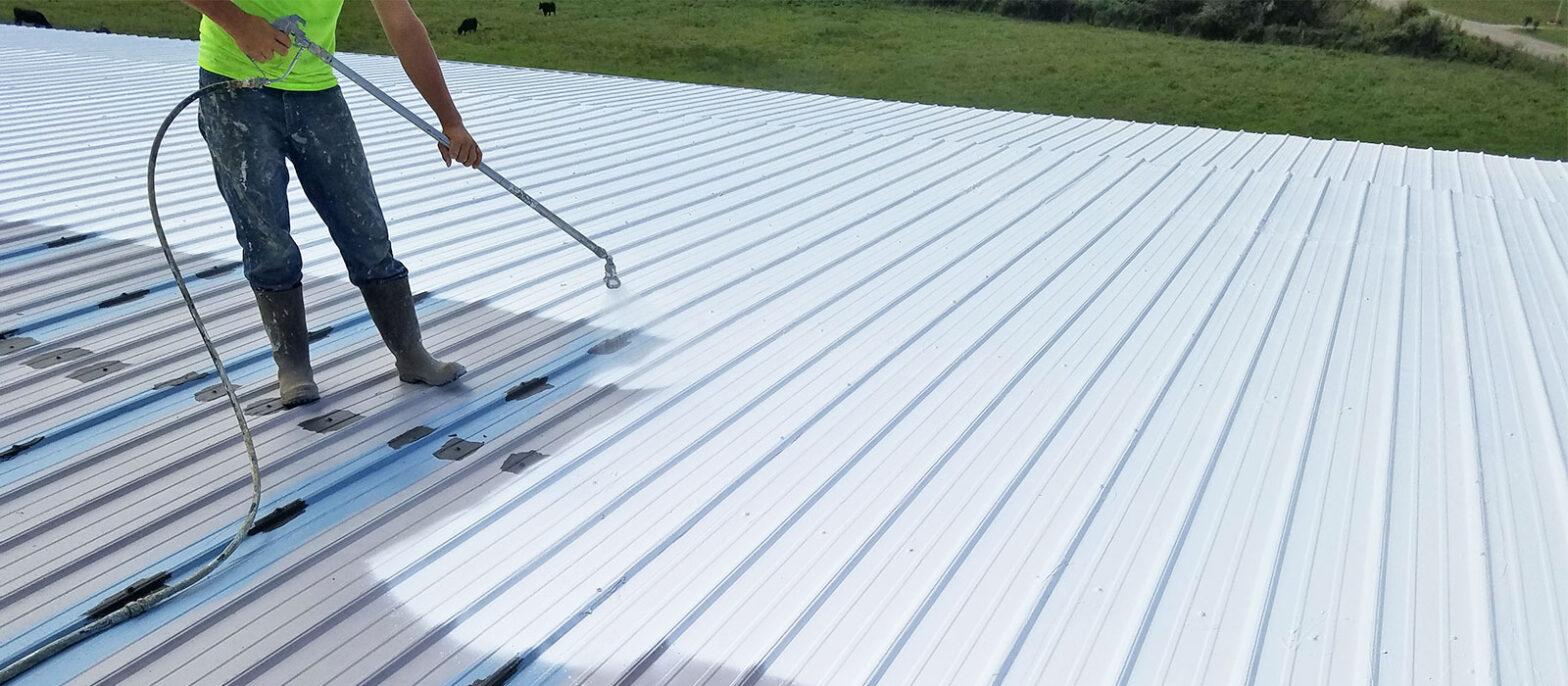
Energy-Efficient Elastomeric Coatings Gain Popularity with Rising Demand for Sustainable Building Solutions

The global elastomeric coating market size is expected to reach USD 15760.5 million by 2034 in response to the growing demand for energy-efficient and sustainable building solutions. The industry is anticipated to reach USD 7874.8 million in 2024. This growth is attributed to the rising number of new product developments worldwide. The market is projected to witness a CAGR of 7.2% through 2034.

The elastomeric coating market is thriving due to the rising demand for energy-efficient and sustainable building solutions. These coatings offer exceptional resistance to weathering, UV radiation, and environmental factors, reducing maintenance and enhancing energy efficiency. Additionally, the emphasis on eco-friendly methods and the growing popularity of cool roof coatings contribute to market growth.

Environmental regulations impact production costs and lead to reformulation to reduce VOC emissions. Elastomeric coatings face challenges in harsh environments but are essential for sustainable infrastructure development. Governmental initiatives and the rise of bio-based elastomeric coatings further drive market expansion.

Elastomeric coatings offer weather resistance and are essential for sustainable infrastructure development. Government initiatives and the rise of bio-based coatings are also contributing to market growth, providing sustainable options without compromising on quality.

Key Takeaways from the Elastomeric Coating Market

  • The elastomeric coating industry is anticipated to be worth USD 15760.5 million in 2024.
  • From 2024 to 2034, the building and construction segment is expected to account for a share of 1% CAGR in terms of application.
  • The United States is projected to showcase a CAGR of 4% in the forecast period.
  • China is anticipated to register a CAGR of 8% over the forecast period.

“Rising demand for high-performance elastomeric coatings, fueled by infrastructure development and a shift toward sustainable bio-based coatings, presents significant opportunities for growth. This trend reflects the increasing priority placed on durability and environmental sustainability in construction projects,” says a Future Market Insights (FMI) analyst.

Competitive Landscape

The elastomeric coating market is shaped by the active engagement of top companies in strategic activities to secure a significant share. These companies are heavily investing in research to discover new applications and products, enhancing their competitive positions. Strategic collaborations between large and small-scale industries aim to drive innovation and minimize competition in product development.

Competitive evaluation in this market centers on the range of products and services offered, emphasizing performance, durability, and application-specific features. Companies differentiate themselves by focusing on product quality, technological advancements, and the ability to meet specific industry needs. Factors such as environmental sustainability, regulatory compliance, and customer service play significant roles in distinguishing competitors within the elastomeric coating industry.

Market players are leveraging technological advancements and sustainability initiatives to gain a competitive edge. This includes the development of eco-friendly formulations and the integration of advanced materials to meet evolving demands. The competitive landscape is continuously evolving, with companies striving to innovate and differentiate themselves through a combination of product excellence, strategic partnerships, and a customer-centric approach.

Browse the Complete Report!

A Key Industry Development-

  • In 2023, Gaco introduced GacoFlex A48, a new high-build acrylic elastomeric roof coating. The product allows for the application of up to 80 wet mils in a single pass, offering extended roof life, enhanced visual appeal, robust adhesion, high tensile strength, and impressive reflectivity.

Leading Elastomeric Coating Brands

  • BASF SE
  • Sherwin-Williams Company
  • DowDuPont Inc.
  • Huntsman Corporation
  • Covestro AG
  • PPG Industries Inc.
  • Versaflex Inc
  • Rhino Linings Corporation
  • Nukote Coating Systems
  • Marvel Industrial Coatings LLC
  • Pidilite Industries Ltd.

Get More Insights into the Elastomeric Coating Market Report

In its latest report, Future Market Insights (FMI) offers an unbiased analysis of the elastomeric coating industry, providing historical data from 2019 to 2023 and forecast statistics for the period 2024 to 2034. To understand the industry potential, growth, and scope, the market is segmented based on type (acrylic, polyurethane, epoxy, silicone, polyurea, and others), application (building and construction [roof, wall, floor, bridges, and others], industrial, automotive and transportation, and others), and regions.

Key Segmentation of Market Report

By Type:

The industry is segregated into acrylic, polyurethane, epoxy, silicone, polyurea, and others.

By Application:

A few important applications include building and construction [roof, wall, floor, bridges, and others], industrial, automotive and transportation, and others.

By Region:

The main countries of North America, Latin America, Europe, East Asia, South Asia, Oceania, and the Middle East and Africa are covered.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube
Global Solar Inverter Market Forecasted to be Valued at USD 20,883.04 Million by 2033, Growing at an Average 6% CAGR | FMI Report

The solar inverter market is set on a path of substantial growth, with forecasts predicting a robust Compound Annual Growth Rate (CAGR) of 6% leading up to 2033. By that year, the market anticipates reaching a notable valuation of USD 20,883.04 million. Noteworthy progress is expected by 2023, with a significant milestone targeting a valuation of USD 11,660.98 million, underscoring the market’s upward trajectory.

String inverters, valued for their cost-effectiveness and durability, continue to be the preferred choice for numerous solar installations, owing to their accessibility and low-maintenance characteristics. As the global commitment to renewable energy sources strengthens, the solar inverter market assumes a pivotal role in converting solar power into usable electricity, making substantial contributions to a greener and more sustainable future for consumers and businesses alike.

Driving Forces and Government Initiatives Shaping the Solar Inverter Market:

Solar inverters are influenced by critical factors such as roof orientation, shading, and roof inclination. Among renewable energy sources, solar photovoltaics have demonstrated significant cost reductions of around 72% for Levelized Cost of Electricity (LCOE), surpassing reductions seen in other sources like wind energy. This reduction stands as a major catalyst for the future growth of the solar inverter market.

Governments worldwide are taking proactive measures to promote solar inverters in industrial applications. For instance, China’s National Energy Administration (NEA) has set a target as part of its 14th Five-year Plan to account for over 50% of all installed capacities by 2025.

Notable Insights from the Solar Inverter Market:

North America commands the largest share of the market, largely due to the higher adoption rate of solar energy, particularly in the US.

The Asia-Pacific region is poised for rapid growth in the solar inverter market, with Japan and India taking the lead.

Favorable policies and incentives in Europe, including residential feed-in-tariffs (FITs), are expected to drive growth. Germany is leading the way, followed by the UK.

Recent Developments in Solar Inverter Industry:

In March 2022, Huawei Technologies forged a collaboration with Meienergy Technology Co., Ltd. to integrate smart energy storage into a 1 GW utility solar plant in Africa, incorporating a 500 MWh energy storage system developed by Meienergy.

SMA Solar Technology AG teamed up with LG Chem to blend SUNNY BOY Battery storage inverters with RESU 10M batteries, introducing innovative home storage solutions. This strategic alliance aims to develop integrated DC/DC converters to enhance the operational voltage of the batteries.

Canadian Solar Inc. unveiled its utility-scale battery storage solution, ‘SolBank,’ in September 2022, catering to the growing demand for energy storage in large-scale applications.

In January 2022, Sungrow introduced its innovative 1+X Modular central inverter during the World Future Energy Summit in Abu Dhabi. This inverter stands out for its modularity, which can be assessed at the inverter, system, and component levels.

In June 2022, V-Guard Industries Ltd. unveiled a new range of on-grid solar power inverters called ‘Solsmart.’ These inverters come with built-in switches that offer additional safety benefits, incorporating advanced safety features. Available in both three-phase and single-phase configurations, Solsmart On-Grid PV inverter also offers a 10-year warranty.

In April 2022, SMA Solar Technology AG launched a new 3-phase inverter series designed for residential and commercial solar PV systems with outputs nearing 135 kW. The series includes four new models with rated powers of 25 kW, 20 kW, 15 kW, and 12 kW, catering to various system sizes and requirements.

Key Companies Profiled:

  • Siemens AG
  • Fimer Group
  • SMA Solar Technology AG
  • Delta Electronics Inc
  • SunPower Corporation
  • Omron Corporation
  • Eaton

Global Solar Inverter Market by Category:

By Type:

  • Central Inverter
  • Micro-Inverter
  • String Inverter

By System Type:

  • Off Grid
  • On Grid

By Phase:

  • Single Phase
  • Three Phase

By End-Use:

  • Residential
  • Commercial and Industrial
  • Utilities

By Region:

  • North America
  • Latin America
  • Europe
  • East Asia
  • South Asia Pacific
  • The Middle East and Africa 

Access Report Details for More In-Depth Information:

Author:

Nikhil Kaitwade (Associate Vice President at Future Market Insights, Inc.) has over a decade of experience in market research and business consulting. He has successfully delivered 1500+ client assignments, predominantly in Automotive, Chemicals, Industrial Equipment, Oil & Gas, and Service industries.

His core competency circles around developing research methodology, creating a unique analysis framework, statistical data models for pricing analysis, competition mapping, and market feasibility analysis. His expertise also extends wide and beyond analysis, advising clients on identifying growth potential in established and niche market segments, investment/divestment decisions, and market entry decision-making.

Nikhil holds an MBA degree in Marketing and IT and a Graduate in Mechanical Engineering. Nikhil has authored several publications and quoted in journals like EMS Now, EPR Magazine, and EE Times.

About Future Market Insights (FMI)

Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.

Join us as we commemorate 10 years of delivering trusted market insights. Reflecting on a decade of achievements, we continue to lead with integrity, innovation, and expertise.

Contact Us:        

Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: 
sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
LinkedIn| Twitter| Blogs | YouTube